


 |
市場調查報告書
商品編碼
2120406
農用輪胎:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Agricultural Tires - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,農業輪胎市場規模將從 2025 年的 86.1 億美元成長到 2026 年的 91.1 億美元,然後在 2031 年達到 121.2 億美元,2026 年至 2031 年的複合年成長率為 5.86%。
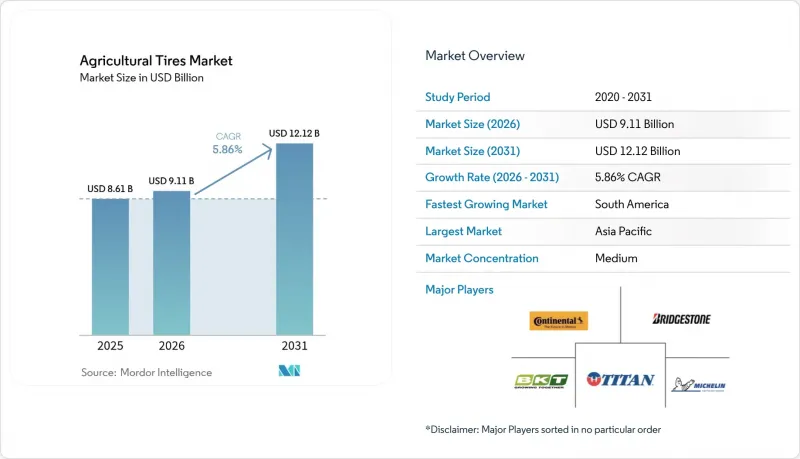
本報告按銷售管道(OEM 和替換/售後市場)、應用領域(曳引機、聯合收割機等)、輪胎結構(斜交胎、子午線胎、IF/VF 子午線胎)、輪圈尺寸(20 英寸以下和 20 英寸以上)、設備馬力等級(30 馬力以下和 30 匹馬力兼容性以及地區進行細分技術以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分技術兼容性以及地區進行細分。市場預測以價值(美元)和銷售量(單位)表示。
全球農用輪胎市場趨勢及洞察
歐盟和烏克蘭的重建需求激增。
世界銀行的ARISE基金正在投資7億美元用於修復農業機械,為超過9萬名農民提供支持,並旨在增加配備優質子午線輪胎的大馬力曳引機的訂單。隨著可耕種面積恢復種植穀物、向日葵和油菜籽,供應商正在將歐洲工廠的產能重新分配到IF/VF尺寸的輪胎。經銷商報告稱,輪胎是受損設備重組時最先更換的消耗品之一,加劇了原始設備製造商(OEM)的訂單。受損鐵路的修復和物流走廊的重新開放縮短了成品輪胎和原料的交貨時間。隨著更換需求的激增,預計從2027年起,這種成長勢頭將放緩。
新興國家機械化的勢頭
在巴西,由於政府貸款計畫刺激了對大型播種機和噴藥機的投資,預計曳引機產量將會增加。在印度,由於補貼政策調整和強勁的季風降雨,市場情緒正在改善,但曳引機的普及率仍然低於可耕種面積的一半。在中國,合作社正在整合農田,以證明投資購買100馬力或以上、需要大直徑子午線輪胎的曳引機是合理的。車輛更換也是推動需求的一個因素,因為在2010年至2015年購買的曳引機現在正處於首次更換輪胎的階段。隨著機械化的發展,農業輪胎市場正受益於平均輪圈尺寸和載重指數的結構性成長。
天然橡膠和石油化學產品的成本波動
泰國和印尼的植物病害爆發導致乳膠產量下降,而原油價格波動則推高了合成橡膠和炭黑的成本。由於缺乏完善的避險策略,中型輪胎製造商不得不反覆提價,但一些融資緊張的農民選擇延長輪胎使用壽命以應對價格上漲。預計到2025年,天然橡膠的價格將在每噸13,550元至17,400元人民幣(約1,960美元至2,516.91美元)之間波動。大型製造商加快了永續橡膠試驗計畫以降低風險,但實用化仍需時日。這種限制因素具有週期性,但其頻繁出現足以影響整個農用輪胎市場的合約策略和庫存緩衝。
細分市場分析
在農業輪胎市場,替換/售後輪胎佔據主導地位,預計到2025年將佔據71.29%的市場佔有率。這反映了農業機械的使用壽命長,以及輪胎在惡劣的田間作業條件下頻繁磨損。農民通常會優先考慮維護保養,以避免在播種和收穫高峰期運作,從而推動了對替換輪胎的穩定需求。售後市場也受益於農村地區分銷網路的不斷擴展以及新興市場中多品牌輪胎選擇的日益豐富。
此外,作物生長週期和地形條件帶來的波動也為新輪胎帶來了穩定的需求,鞏固了該細分市場在全球農業輪胎市場的主導地位。同時,OEM通路是成長最快的細分市場,預計到2031年將以5.97%的複合年成長率成長,這主要得益於機械化程度不斷提高的經濟體中新型曳引機和收割機銷量的成長。高功率機械和精密農業設備的普及進一步加速了對OEM輪胎的需求,尤其是那些採用先進輪胎技術並根據新設備規格量身定做的輪胎。
預計到2025年,曳引機輪胎將佔據最大的市場佔有率,達到56.73%,凸顯了其作為全球農業機械基石的關鍵作用。曳引機在農業輪胎總需求中佔比最大,因為它們需要多種輪胎配置來應對從土壤耕作到運輸等各種作業。這一細分市場受益於車輛的持續更新換代、亞洲和非洲機械化水平的提高,以及為提高燃油效率而日益普及的高牽引力子午線輪胎和IF/VF技術的廣泛應用。
隨著精密農業的發展,噴藥機是成長最快的應用領域,年複合成長率高達6.03%。現代噴藥機需要特殊的輪胎,以最大限度地減少土壤壓實並具有高浮力,從而催生了對先進子午線輪胎和VF輪胎的需求,這些輪胎能夠保護作物產量並提高田間作業效率。收割機的平均售價較高,因為它們需要最大的胎體來在鬆軟的土壤上運輸重型穀倉。拖車和加長型堆高機等農業機械也在推動輪胎需求,尤其是在多元化農業地區,輪胎的應用範圍已擴展到畜牧養殖和物料運輸。整體而言,由於應用結構的變化,農業輪胎市場正逐漸轉型為專業化花紋和高附加價值產品。
區域分析
亞太地區是農業輪胎市場的主要驅動力,預計2025年將佔全球銷售額的37.83%。這主要得益於該地區大量農用車輛正在進行現代化改造。印度和中國的政府獎勵措施正在推動曳引機在傳統糧食產區以外的地區普及,而東南亞的人工林也在推動機械化以應對勞動力短缺問題。該地區的農民對價格較為敏感,通常選擇斜交輪胎或普通子午線輪胎,但隨著雙季種植的日益活性化,人們對土壤壓實問題的認知也在不斷提高。本地製造商正在滿足入門級市場的需求,但在高價值園藝領域,對IF/VF輪胎的投資是合理的,而高階品牌正在不斷擴大市場佔有率。
北美和歐洲的農用輪胎市場雖然已經成熟,但仍佔據相當大的佔有率。隨著機械化程度的提高,輪胎更換週期佔據主導地位。這些地區的農民較早採用了輪胎內通訊系統(CTIS)和智慧輪胎分析技術,使其成為下一代技術的培養箱。然而,由於大宗商品價格的周期性下跌和補貼政策的調整會立即反映在原始設備製造商(OEM)的生產計劃中,因此需求往往不太穩定。在東歐,受污染農地的複墾導致了重組需求的暫時性激增,並促使配備高階輪胎的新型農用機械投入使用。
預計到2031年,南美洲將錄得6.21%的最高成長率。這主要得益於巴西塞拉多地區大豆和玉米種植面積的擴大,以及阿根廷為應對出口價格波動而擴大生產規模的努力。融資項目使得大型曳引機和高容量噴霧器得以更換,從而增加了對更寬輪圈和先進胎面花紋的需求。中東和非洲地區雖然目前市場規模仍小規模,但具有長期成長空間。政府支持的糧食安全計畫、沙漠地區的灌溉農業以及捐助者資助的機械化計畫正逐步提升基本需求。分銷挑戰和惡劣的氣候條件凸顯了具有卓越抗穿刺性和耐熱性的輪胎配方的重要性。未來,隨著融資管道的拓展,可能會出現一個“突破”,即許多買家將直接從斜交輪胎轉向智慧子午線輪胎,從而進一步提升農業輪胎的市場佔有率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興市場的快速機械化與車輛現代化
- 從斜交輪胎過渡到子午線輪胎/低土壤壓實型IF-VF輪胎
- 世界人口不斷成長,糧食安全面臨壓力。
- 由於老舊曳引機,對替換曳引機的需求激增。
- 即時輪胎壓力監測系統和 CTIS(氣瓶追蹤系統)的日益普及推動了輪胎和車輛系統的進步。
- 歐盟和烏克蘭的經濟復甦帶動了整車製造商需求的激增。
- 市場限制因素
- 農產品價格波動
- 天然橡膠和石油化學產品的成本波動
- 供應商的退出導致選擇範圍縮小,價格上漲。
- 影響橡膠樹葉的疾病限制了原料的供應。
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按銷售管道
- OEM
- 替換件/售後市場
- 透過使用
- 聯結機
- 結合
- 噴霧器
- 拖車
- 裝載機和加長型堆高機
- 其他農業設備
- 輪胎結構
- 偏見
- 徑向
- IF/VF 徑向
- 按輪圈尺寸
- 小於20英寸
- 20-30英寸
- 30-40英寸
- 40吋或更大
- 按馬力等級分類的設備
- 小於30馬力
- 30~70 HP
- 71~150 HP
- 150馬力或以上
- 空氣填充技術的兼容性
- 標準輪胎
- CTIS就緒/智慧輪胎
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Bridgestone Corporation
- Michelin
- Continental AG
- Balkrishna Industries Ltd(BKT)
- Titan International Inc.
- Trelleborg AB
- Yokohama Rubber Co. Ltd.(ATG)
- Nokian Tyres plc
- Apollo Tyres Ltd.
- Prometeon Tyre Group
- CEAT Ltd.
- Mitas as
- Goodyear Tire & Rubber Co.
- Hankook Tire & Technology
- GRI Tires
- Maxam Tire International
- Specialty Tires of America
- Magna Tyres Group
- Petlas Tire Industry
第7章 市場機會與未來展望
According to Mordor Intelligence, the agricultural tires market size is expected to grow from USD 8.61 billion in 2025 to USD 9.11 billion in 2026 and is forecast to reach USD 12.12 billion by 2031 at a 5.86% CAGR over 2026-2031.
This report is Segmented by Sales Channel (OEM and Replacement/Aftermarket), Application (Tractors, Combine Harvesters, and More), Tire Construction (Bias, Radial, and IF/VF Radial), Rim-Size (Less Than 20 Inch and More), Equipment Horse-Power Class (Less Than 30 HP and More), Inflation-Technology Compatibility, and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Agricultural Tires Market Trends and Insights
EU-Ukraine Reconstruction Demand Spike
The World Bank's ARISE facility has channelled USD 700 million into farm machinery recovery, aimed at reaching over 90,000 farmers and accelerating orders for high-horsepower tractors that ship with premium radials. Suppliers are reallocating European plant capacity toward IF/VF sizes as cleared acreage returns to grain, sunflower, and rapeseed. Dealers report that tires are among the first consumables replaced when equipment is rebuilt after being destroyed, pushing OEM backlogs higher. Logistics corridors reopened as damaged rail lines were restored, shortening delivery cycles for finished tires and raw materials. The spike is expected to taper after 2027 as the replacement wave normalizes.
Mechanization Momentum in Emerging Economies
Brazilian tractor output is projected to rise after government credit lines revived capital spending on large planters and sprayers. In India, subsidy tweaks and a good monsoon are lifting sentiment, although penetration remains below half of arable land. Chinese cooperatives are pooling plots to justify investments in 100-plus-HP tractors that need larger-diameter radials. Fleet renewal also drives demand, as tractors bought during the 2010-2015 surge are now due for their first tire change. As mechanization progresses, the agricultural tires market benefits from a structural rise in average rim size and load index.
Natural-Rubber and Petrochemical Cost Swings
Plant disease outbreaks in Thailand and Indonesia cut latex yields, while crude-oil fluctuations lifted synthetic rubber and carbon-black costs. Mid-tier tire makers, lacking sophisticated hedging, pushed through multiple price increases, which some cash-constrained farmers deferred by extending tire life. Natural rubber prices fluctuated annually between 13,550 and 17,400 CNY (USD 1,960-2,516.91) per ton in 2025. Larger manufacturers accelerated sustainable-rubber pilot programs to lower exposure, but commercialization will take time. The restraint is cyclical yet recurs often enough to influence contracting strategies and inventory buffers throughout the agricultural tires market.
Other drivers and restraints analyzed in the detailed report include:
- Shift From Bias to Radial / IF-VF Tires
- Real-Time Tire-Pressure and CTIS Adoption
- Commodity-Price Volatility Affecting Farm Income
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Replacement/Aftermarket tires dominate the agricultural tires market, with a commanding 71.29% share in 2025, reflecting the long operational life of farm equipment and the frequent tire wear cycles under heavy field use. Farmers typically prioritize maintenance to avoid downtime during peak planting and harvest seasons, which drives consistent replacement demand. The aftermarket segment also benefits from expanding rural distribution networks and increasing availability of multi-brand tire options across emerging markets.
Additionally, fluctuations in crop cycles and terrain conditions create steady pull-through demand for new tires, reinforcing the segment's leadership within the global agricultural tires market. Meanwhile, the OEM channel represents the fastest-growing segment, expanding at a 5.97% CAGR through 2031 as new tractor and harvester sales rise in mechanizing economies. Growth in large-horsepower machinery and precision farming equipment further accelerates OEM tire demand, particularly for advanced tire technologies aligned with new equipment specifications.
Tractor tires hold the largest share at 56.73% in 2025, affirming their critical role as the backbone of agricultural machinery worldwide. Tractors require multiple tire configurations for tasks ranging from soil preparation to hauling, making them the single most significant contributor to overall agricultural tire demand. The segment benefits from continuous fleet modernization, growing mechanization in Asia and Africa, and the increasing adoption of high-traction radial and IF/VF technologies for improved fuel efficiency.
Sprayers form the fastest-growing application segment, expanding at a 6.03% CAGR as precision agriculture intensifies. Modern sprayers require specialized tires with low soil compaction and high flotation, creating demand for advanced radial and VF tires that protect crop yields and enhance field productivity. Harvesters require the largest casings to carry heavy grain tanks through soft soils, leading to premium average selling prices. Implementers such as trailers and telehandlers add incremental demand, especially in mixed farming zones where livestock or materials handling broaden tire-use scenarios. Overall, the application mix gradually tilts the agricultural tires market toward specialized patterns and higher value per unit.
Complete Report Scope:
- By Sales Channel
- OEM
- Replacement / Aftermarket
- By Application
- Tractors
- Combine Harvesters
- Sprayers
- Trailers
- Loaders & Telehandlers
- Other Implements
- By Tire Construction
- Bias
- Radial
- IF / VF Radial
- By Rim-Size
- Less than 20 inch
- 20 to 30 inch
- 30 to 40 inch
- More than 40 inch
- By Equipment Horse-Power Class
- Less than 30 HP
- 30 to 70 HP
- 71 to 150 HP
- More than 150 HP
- By Inflation-Technology Compatibility
- Standard Tires
- CTIS-Ready / Smart Tires
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific leads the agricultural tires market, capturing 37.83% of revenue share in 2025, driven by a vast fleet that is still modernizing. Government incentives in India and China encourage tractor ownership beyond traditional cereal belts, while Southeast Asian plantations mechanize to offset labor shortages. Farmers in the region often choose bias or basic radials due to price sensitivity, yet awareness of soil compaction is rising as double-cropping intensifies. Local manufacturers meet entry-level needs, but premium brands grow share where high-value horticulture justifies IF/VF investments.
North America and Europe together represent a mature yet sizable slice of the agricultural tire market. Replacement cycles dominate because mechanization is already universal. Farmers here experiment early with CTIS and smart-tire analytics, making these regions incubators for next-gen features. However, cyclical dips in commodity prices or subsidy reforms quickly filter into OEM production schedules, making demand somewhat erratic. Reconstruction in Eastern Europe adds a transient spike as contaminated fields re-enter cultivation, drawing new machinery with premium tire packages into service.
South America records the fastest growth rate of 6.21% to 2031, propelled by Brazil's soy and corn expansion across the Cerrado and Argentina's push for scale to hedge export volatility. Credit programs enable upgrades to larger tractors and high-capacity sprayers, thus increasing demand for wider rims and advanced tread patterns. The Middle East and Africa remain smaller in absolute value but offer a long runway. Government-backed food security projects, irrigated desert farming, and donor-funded mechanization schemes slowly raise baseline demand. Distribution challenges and harsh climates put a premium on puncture resistance and heat-tolerant compounds. Over time, as credit access widens, a leapfrog effect could move many buyers straight from bias to smart radials, contributing incremental share to the agricultural tires market.
- Bridgestone Corporation
- Michelin
- Continental AG
- Balkrishna Industries Ltd (BKT)
- Titan International Inc.
- Trelleborg AB
- Yokohama Rubber Co. Ltd. (ATG)
- Nokian Tyres plc
- Apollo Tyres Ltd.
- Prometeon Tyre Group
- CEAT Ltd.
- Mitas a.s.
- Goodyear Tire & Rubber Co.
- Hankook Tire & Technology
- GRI Tires
- Maxam Tire International
- Specialty Tires of America
- Magna Tyres Group
- Petlas Tire Industry
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Mechanization & Fleet Renewal in Emerging Markets
- 4.2.2 Shift From Bias to Radial / If-VF Low-Compaction Tires
- 4.2.3 Growing Global Population & Food-Security Pressure
- 4.2.4 Surging Replacement Demand from Aging Tractor Fleet
- 4.2.5 Real-Time Tire-Pressure & CTIS Adoption Accelerating Upgrades
- 4.2.6 EU-Ukraine Reconstruction Triggering OEM Demand Spike
- 4.3 Market Restraints
- 4.3.1 Fluctuating Agricultural Commodity Prices
- 4.3.2 Natural-Rubber & Petrochemical Cost Volatility
- 4.3.3 Supplier Exits Limiting Choice & Raising Prices
- 4.3.4 Rubber-Leaf Disease Constraining Raw-Material Supply
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Sales Channel
- 5.1.1 OEM
- 5.1.2 Replacement / Aftermarket
- 5.2 By Application
- 5.2.1 Tractors
- 5.2.2 Combine Harvesters
- 5.2.3 Sprayers
- 5.2.4 Trailers
- 5.2.5 Loaders & Telehandlers
- 5.2.6 Other Implements
- 5.3 By Tire Construction
- 5.3.1 Bias
- 5.3.2 Radial
- 5.3.3 IF / VF Radial
- 5.4 By Rim-Size
- 5.4.1 Less than 20 inch
- 5.4.2 20 to 30 inch
- 5.4.3 30 to 40 inch
- 5.4.4 More than 40 inch
- 5.5 By Equipment Horse-Power Class
- 5.5.1 Less than 30 HP
- 5.5.2 30 to 70 HP
- 5.5.3 71 to 150 HP
- 5.5.4 More than 150 HP
- 5.6 By Inflation-Technology Compatibility
- 5.6.1 Standard Tires
- 5.6.2 CTIS-Ready / Smart Tires
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Russia
- 5.7.3.7 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Turkey
- 5.7.5.4 Egypt
- 5.7.5.5 South Africa
- 5.7.5.6 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Bridgestone Corporation
- 6.4.2 Michelin
- 6.4.3 Continental AG
- 6.4.4 Balkrishna Industries Ltd (BKT)
- 6.4.5 Titan International Inc.
- 6.4.6 Trelleborg AB
- 6.4.7 Yokohama Rubber Co. Ltd. (ATG)
- 6.4.8 Nokian Tyres plc
- 6.4.9 Apollo Tyres Ltd.
- 6.4.10 Prometeon Tyre Group
- 6.4.11 CEAT Ltd.
- 6.4.12 Mitas a.s.
- 6.4.13 Goodyear Tire & Rubber Co.
- 6.4.14 Hankook Tire & Technology
- 6.4.15 GRI Tires
- 6.4.16 Maxam Tire International
- 6.4.17 Specialty Tires of America
- 6.4.18 Magna Tyres Group
- 6.4.19 Petlas Tire Industry
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 對 2035 年前的標準子午線農業輪胎市場進行分析和預測:按類型、產品、技術、組件、應用、最終用戶、功能、安裝類型和設備分類。
 農業輪胎市場-2026-2032年全球市場預測
 農業輪胎市場規模、佔有率和成長分析:按產品類型、輪胎結構、輪圈尺寸、應用、分銷管道、最終用戶和地區分類-2026-2033年產業預測農業輪胎市場:2026-2032年全球市場預測(依產品類型、類型、輪胎類型、輪圈尺寸、材料、應用、最終用戶和銷售管道)
 農業輪胎市場規模、佔有率、趨勢和預測:按產品、應用、通路和地區分類(2026-2034 年)
 全球標準子午線農用輪胎市場報告:2021-2032年歷史表現及預測農業機械輪胎市場:依產品類型、結構、外形、銷售管道和應用分類-2026-2032年全球預測標準子午線農用輪胎市場:按輪圈直徑、胎面花紋、銷售管道和最終用戶分類,全球預測,2026-2032年
 全球農業輪胎市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 農業輪胎市場-全球產業規模、佔有率、趨勢、機會及預測(依車輛類型、輪胎類型、需求類別、地區及競爭格局分類,2021-2031年)