


 |
市場調查報告書
商品編碼
2120320
過氧化鈣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Calcium Peroxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
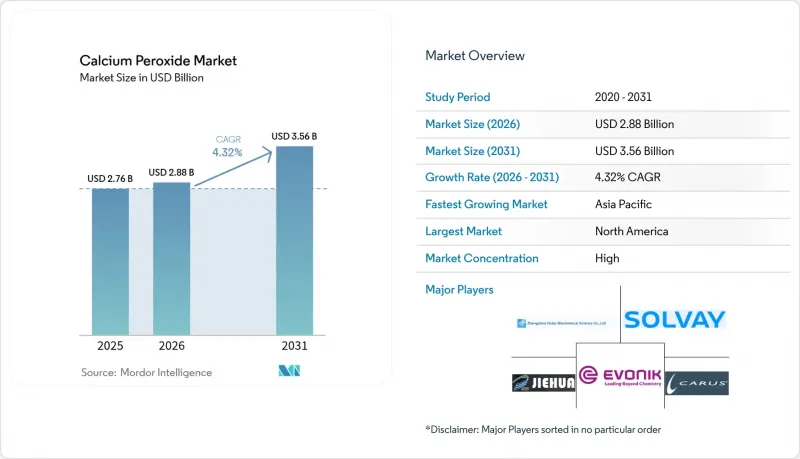
根據 Mordor Intelligence 預測,過氧化鈣市場規模預計將從 2025 年的 27.6 億美元成長到 2026 年的 28.8 億美元。
此外,預計到 2031 年市場規模將達到 35.6 億美元,並且預計從 2026 年到 2031 年將以 4.32% 的複合年成長率成長。
本報告按等級(食品級、工業級)、應用(織物改良劑、種子消毒劑、漂白劑、氧化劑等)、終端用戶行業(食品飲料、農業、採礦、紙漿造紙等)和地區(亞太地區、北美、歐洲、南美、中東和非洲)進行細分。市場預測以美元計價。
全球過氧化鈣市場趨勢及洞察
烘焙業中麵團改良劑的使用量增加
隨著「免揉麵」工藝的日益普及,取代了傳統的麵團熟成工藝,工業烘焙對過氧化鈣的需求也隨之成長。 20-35 ppm 的最佳添加量能夠改善麵筋強度、保水性和冷凍麵團的穩定性,幫助大規模烘焙企業實現各工廠產品品質的標準化。歐洲禁用偶氮二甲醯胺進一步推動了該化合物的應用,因為其分解產物能夠最大限度地降低健康風險。北美和歐洲生產規模的擴大確保了跨國食品集團的穩定供應。零售通路冷凍和半成品消費量的成長也支撐了過氧化鈣市場的長期銷售量成長。此外,設備升級改造,整合線上氧化劑添加功能,也加速了該產品的普及應用。
口腔護理和牙齒美白產品的應用日益廣泛。
奈米級產品在牙齒美白凝膠和漱口水中備受關注。這是因為它們能夠透過緩慢釋放氧氣來提亮琺瑯質並抑制生物膜的形成。臨床研究表明,它們比過氧化氫更能有效滲透牙本質小管,並降低牙齒敏感度。領先的口腔護理品牌正將過氧化鈣定位為一種「親膚氧氣」成分,以符合潔淨標示的趨勢。亞太地區的快速都市化正在擴大高階美白產品的消費群體,並推動短期需求。美國、歐盟和日本的監管批准正在促進非處方 (OTC) 和專業產品的順利商業化。
儲存和處理過程中的健康和安全風險
過氧化鈣是一種強氧化劑,與有機物接觸會加劇火勢。其粉塵也會刺激眼睛、皮膚和呼吸道。倉庫需要將過氧化鈣與易燃物隔離,並進行溫度控制和局部排氣通風系統改造。這些措施會增加合規成本,尤其對於新興市場的小規模加工商。由於缺乏既定的職業接觸限值,監管的不確定性增加,並可能延誤工廠的許可證發放。此外,培訓和個人防護設備的要求也會推高總擁有成本,阻礙對成本較為敏感的過氧化鈣市場細分領域的快速普及。
細分市場分析
到2025年,食品級過氧化鈣將佔據56.10%的市場佔有率,這反映出全球烘焙集團對符合嚴格食品安全標準的穩定氧化性能的強勁需求。優質供應商提供的產品符合FCC和ASTM標準,並最大限度地減少粒徑差異,從而確保在高速攪拌機中均勻分散。受土壤修復、水產養殖和精密農業化應用的推動,預計到2031年,工業級過氧化鈣的複合年成長率將達到4.98%。用於口腔清潔用品和製藥領域的專用奈米顆粒產品利潤率更高,正吸引主要化學製造商的研發投資。
北美和歐洲的監管審計收緊了供應商選擇標準,更傾向於選擇擁有經檢驗危害分析計劃的成熟製造商。同時,工業級配方製造商優先考慮氧氣生成、水不溶性成分和流動性,以滿足土壤修復承包商施藥設備的要求。亞太地區直播稻和池塘治理領域的應用,推動了工業級產品的持續銷售量成長。嚴格的認證要求與性能客製化之間的相互作用,維持了整體平衡,從而保障了過氧化鈣市場的長期韌性。
區域分析
預計到2025年,北美將以37.75%的市場佔有率引領市場,這得益於其嚴格的土壤修復方法、技術先進的烘焙行業以及對以過氧化鈣為基礎的氧氣輸送劑的精準播種工具的早期應用。美國環保署(EPA)的棕地津貼持續刺激對固態氧化劑的需求,這些氧化劑能夠降低現場作業風險。加拿大緊隨其後,其資源產業的土壤修復以及不列顛哥倫比亞省的水產養殖試驗推動了這一趨勢。同時,墨西哥也受益於依賴美國供應鏈的加工食品出口。過氧化氫工廠產能的提升,例如Engro對下游過氧化鈣生產的投資,正在增強原料的穩定供應。
預計到2031年,亞太地區將以5.96%的複合年成長率實現最高成長,主要得益於大規模水產養殖和直播稻種植技術的普及。日本鰻魚養殖場和越南蝦類養殖場展現了池塘供氧的多功能性,並產生了持續的每月需求。中國強制性的污染土壤整治、印度機械化水稻插秧機的應用以及韓國口腔護理領域的創新生態系統,都在拓展過氧化鈣的應用範圍。中國和馬來西亞的區域製造商正在石灰石礦床附近運作工廠,以降低物流成本並縮短交貨時間,從而增強該地區過氧化鈣市場的競爭力。
歐洲的趨勢正受到烘焙生產線逐步淘汰偶氮二甲醯胺的影響,德國、法國和英國的烘焙業正轉向使用過氧化鈣作為替代品。波蘭和義大利前工業區的土壤修復也進一步刺激了對過氧化鈣的需求。在北歐的高價值水產養殖領域,沉積物氧化法的試驗應用正在推進,並拓展了新的應用場景。南美洲、中東和非洲是新興的潛在市場,來自亞太地區的技術轉移正應用於巴西塞拉多地區的生態修復計畫和埃及的吳郭魚養殖場。儘管基礎設施不完善和監管不統一在一定程度上減緩了成長速度,但對過氧化鈣的需求仍在穩步流入全球市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 烘焙業麵團調節劑的使用量增加
- 口腔護理產品和牙齒美白產品的使用率不斷提高。
- 對現場土壤和地下水修復的需求日益成長
- 擴大種子包衣技術在精密農業的應用
- 水產養殖池塘的氧氣供應技術正引起人們的注意。
- 歐洲逐步減少偶氮二甲醯胺的使用,正在推動過氧化物基替代品的採用。
- 市場限制因素
- 儲存和處理過程中的健康和安全風險
- 更便宜的過氧化氫/過氧化苯甲醯替代品的威脅
- 石灰和碳酸鈣等原料價格的波動
- 價值鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 按年級
- 食品級
- 工業級
- 透過使用
- 衣物柔順劑
- 種子消毒劑
- 漂白
- 氧化劑
- 中間的
- 其他用途
- 按最終用戶行業分類
- 食品/飲料
- 農業
- 礦業
- 紙漿和造紙
- 製藥
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- AkzoNobel NV
- American Elements
- BASF SE
- Carus Group Inc.
- Evonik Industries AG
- Mahalaxmi Enterprise
- Nikunj Chemicals
- Noshly Pty Ltd
- Pioneer Enterprise
- Shangyu Jie Hua Chemical
- Solvay SA
- STP Chem Solutions
- Sunway Lab
- Zhengzhou Huize Biochemical Technology Co. Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, calcium peroxide market size in 2026 is estimated at USD 2.88 billion, growing from 2025 value of USD 2.76 billion with 2031 projections showing USD 3.56 billion, growing at 4.32% CAGR over 2026-2031.
This report is Segmented by Grade (Food Grade, Industrial Grade), Application (Dough Conditioner, Seed Disinfectant, Bleaching Agent, Oxidizing Agent, and More), End-User Industry (Food and Beverage, Agriculture, Mining, Pulp and Paper, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Calcium Peroxide Market Trends and Insights
Increased Use as Dough-Conditioner in Bakery Industry
Demand for calcium peroxide in industrial bakeries rises as no-time dough processes replace traditional proofing. Optimum addition rates of 20-35 ppm improve gluten strength, moisture retention, and frozen dough stability, helping large bakers standardize quality across plants. Regulatory bans on azodicarbonamide in Europe further favour the compound because its breakdown products pose minimal health risks. Production scale-up in North America and Europe secures a consistent supply for multinational food groups. Greater consumption of frozen and par-baked items in retail channels sustains long-term volume growth for the calcium peroxide market. Equipment upgrades that integrate inline oxidant dosing also streamline adoption.
Growing Adoption in Oral-Care & Dental Whitening Products
Nanoparticle grades are gaining traction in tooth whitening gels and mouthwashes because slow oxygen release inhibits biofilms while brightening enamel. Clinical studies show better penetration into dentinal tubules than hydrogen peroxide, reducing sensitivity. Major oral-care brands position calcium peroxide as a "gentle oxygen" ingredient, aligning with clean-label trends. Rapid urbanisation in the Asia Pacific widens the consumer base for premium whitening products, adding near-term demand. Regulatory approvals across the United States, European Union, and Japan smooth commercialisation for both OTC and professional lines.
Health & Safety Hazards During Storage/Handling
Calcium peroxide is classified as a strong oxidizer; contact with organics can intensify fires, and the dust irritates eyes, skin, and respiratory tracts. Warehouses require isolation from combustible materials, temperature control, and local exhaust ventilation systems. These measures raise compliance costs, especially for small processors in emerging markets. Absence of an established occupational exposure limit adds regulatory uncertainty and may delay plant approvals. Training and personal protective equipment requirements also elevate the total cost of ownership, restraining rapid diffusion in cost-conscious segments of the calcium peroxide market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for In-Situ Soil & Groundwater Remediation
- Expansion of Seed Pelleting for Precision Agriculture
- Volatile Lime & Calcium Carbonate Feedstock Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Food Grade accounted for 56.10% of the calcium peroxide market share in 2025, reflecting entrenched demand from global bakery groups that require consistent oxidant performance under strict food safety codes. Premium suppliers deliver products that conform to FCC and ASTM benchmarks and maintain a narrow particle-size span, enabling homogeneous dispersion in high-speed mixers. Industrial Grade is forecast to post a 4.98% CAGR to 2031 as soil remediation, aquaculture, and precision agriculture gain scale. Specialty nanoparticle variants aimed at oral-care and pharmaceutical uses command higher margins, attracting R&D investments from chemical majors.
Regulatory audits in North America and Europe reinforce supplier selection criteria, favouring long-standing producers with validated hazard-analysis plans. Meanwhile, Industrial Grade formulators emphasise oxygen yield, water insolubles, and flowability to meet remediation contractors' dosing equipment requirements. Adoption of direct-seeded rice and pond treatment in Asia Pacific underpins sustained tonnage growth for Industrial Grade. The interplay of stringent certification on one side and performance customisation on the other maintains overall balance and undergirds long-term resilience of the calcium peroxide market.
Complete Report Scope:
- By Grade
- Food Grade
- Industrial Grade
- By Application
- Dough Conditioner
- Seed Disinfectant
- Bleaching Agent
- Oxidizing Agent
- Intermediary Chemicals
- Other Applications
- By End-user Industry
- Food and Beverage
- Agriculture
- Mining
- Pulp and Paper
- Pharmaceutical
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of APAC
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America led with a 37.75% revenue share in 2025 thanks to stringent remediation legislation, a technologically advanced bakery sector, and early deployment of precision seeding tools that favour calcium peroxide-based oxygen donors. The United States Environmental Protection Agency's brownfield grants continue to stimulate demand for solid-form oxidants that lower site operation hazards. Canada follows with resource-sector soil clean-up and aquaculture trials in British Columbia, while Mexico benefits from food-processing exports that hinge on US supply chains. Capacity additions in hydrogen peroxide plants, such as Engro's investment that feeds downstream calcium peroxide production, enhance raw material security.
Asia Pacific posts the fastest regional CAGR at 5.96% to 2031, propelled by large-scale aquaculture operations and direct-seeded rice adoption. Japanese eel farms and Vietnamese shrimp ponds illustrate the breadth of pond-oxygenation uses, driving recurring monthly demand. China's contaminated-land restoration mandates, India's mechanised rice planters, and South Korea's oral-care innovation ecosystem all expand application diversity. Regional manufacturers in China and Malaysia commission new plants close to limestone deposits to trim logistics costs and shorten delivery cycles, reinforcing competitiveness of the calcium peroxide market in the region.
Europe's trajectory is shaped by the phased withdrawal of azodicarbonamide from bakery lines, pushing bakeries in Germany, France, and the United Kingdom toward calcium peroxide alternatives. Soil remediation in old industrial belts of Poland and Italy presents additional volume. Northern Europe's high-value aquaculture sector pilots sediment oxidation regimes, adding another use case. South America and the Middle East & Africa provide emerging potential, with Brazil's Cerrado reclamation and Egypt's tilapia ponds drawing on technology transfer from Asia Pacific. Infrastructure gaps and regulatory variability temper the growth slope yet still feed incremental tonnage into the global calcium peroxide market.
- AkzoNobel N.V.
- American Elements
- BASF SE
- Carus Group Inc.
- Evonik Industries AG
- Mahalaxmi Enterprise
- Nikunj Chemicals
- Noshly Pty Ltd
- Pioneer Enterprise
- Shangyu Jie Hua Chemical
- Solvay SA
- STP Chem Solutions
- Sunway Lab
- Zhengzhou Huize Biochemical Technology Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increased use as dough-conditioner in bakery industry
- 4.2.2 Growing adoption in oral-care and dental whitening products
- 4.2.3 Rising demand for in-situ soil and groundwater remediation
- 4.2.4 Expansion of seed-pelleting for precision agriculture
- 4.2.5 Aquaculture pond-oxygenation technologies gaining traction
- 4.2.6 Europe phase-down of azodicarbonamide drives peroxide alternatives
- 4.3 Market Restraints
- 4.3.1 Health and safety hazards during storage/handling
- 4.3.2 Substitution threat from cheaper hydrogen/benzoyl peroxides
- 4.3.3 Volatile lime and calcium carbonate feedstock pricing
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Grade
- 5.1.1 Food Grade
- 5.1.2 Industrial Grade
- 5.2 By Application
- 5.2.1 Dough Conditioner
- 5.2.2 Seed Disinfectant
- 5.2.3 Bleaching Agent
- 5.2.4 Oxidizing Agent
- 5.2.5 Intermediary Chemicals
- 5.2.6 Other Applications
- 5.3 By End-user Industry
- 5.3.1 Food and Beverage
- 5.3.2 Agriculture
- 5.3.3 Mining
- 5.3.4 Pulp and Paper
- 5.3.5 Pharmaceutical
- 5.3.6 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of APAC
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AkzoNobel N.V.
- 6.4.2 American Elements
- 6.4.3 BASF SE
- 6.4.4 Carus Group Inc.
- 6.4.5 Evonik Industries AG
- 6.4.6 Mahalaxmi Enterprise
- 6.4.7 Nikunj Chemicals
- 6.4.8 Noshly Pty Ltd
- 6.4.9 Pioneer Enterprise
- 6.4.10 Shangyu Jie Hua Chemical
- 6.4.11 Solvay SA
- 6.4.12 STP Chem Solutions
- 6.4.13 Sunway Lab
- 6.4.14 Zhengzhou Huize Biochemical Technology Co. Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Increasing Environmental Concern Regarding Soil Remediation and Oil-spill Recovery

 過氧化鈣市場規模、佔有率和趨勢分析報告:按形態、應用、地區和細分市場分類(2026-2033 年)
 2026年全球過氧化鈣市場報告
 過氧化鈣市場規模、佔有率及成長分析(按等級、應用、最終用途及地區分類)-2026-2033年產業預測
 全球過氧化鈣市場