


 |
市場調查報告書
商品編碼
2120305
高階銅箔:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031年)High-End Copper Foil - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
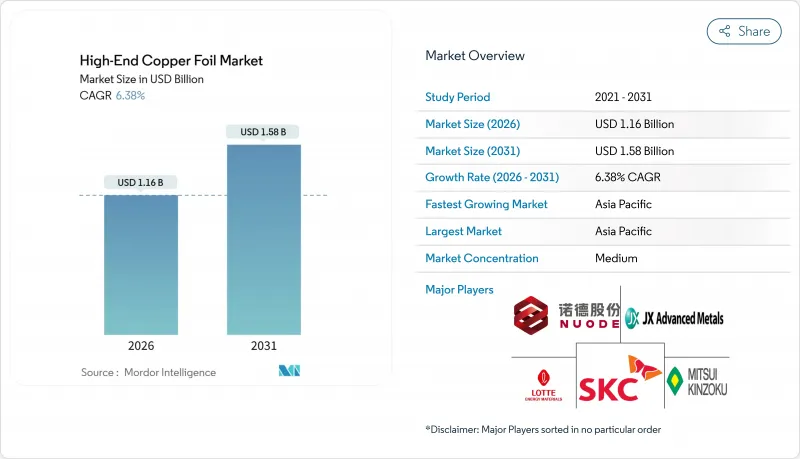
根據 Mordor Intelligence 估計,2026 年高階銅箔市值為 11.6 億美元,預計到 2031 年將達到 15.8 億美元,在預測期(2026-2031 年)內複合年成長率為 6.38%。
本報告按產品類型(軋延銅箔和電解銅箔)、應用領域(電路基板、電池、太陽能和替代能源、消費性電子、醫療及其他)以及地區(亞太地區、北美地區、歐洲地區、南美地區以及中東和非洲地區)進行細分。市場預測以美元計價。
全球高階銅箔市場的趨勢與洞察
電動車電池對超薄、高純度箔的需求
隨著箔材厚度每減少2微米,質量能量密度可提高5-6%,原始設備製造商(OEM)正加速採用6微米和4微米的負極集流體箔材。當中國2025年鋰電池出貨量預計將達到1334吉瓦時,2026年將達到1622吉瓦時,但將於2026年7月生效的純度法規將迫使競爭力較弱的製造商退出高階銅箔市場。歐美超級工廠要求銅箔純度達到99.99%,延伸率偏差小於1%,這使得訂單往往集中在日本和韓國供應商手中。國際能源總署(IEA)警告稱,到2035年,原銅將出現30%的缺口,這進一步凸顯了薄片良率管理的重要性。高品質電解的價格為每公斤 22-28 美元,而標準 8µm 銅箔的價格為每公斤 15-18 美元,因此對於掌握了 6µm 以下厚度電鍍技術的製造商來說,利潤非常豐厚。
5G/HPC 的發展帶動了高頻 PCB 的需求成長。
超大規模資料中心升級至 800G 和 1.6T 乙太網路需要介電常數低於 3.5 的材料,這迫使層壓板製造商使用表面粗糙度小於 0.4µm 的超薄捲材銅箔。由於銅箔供應緊張,羅傑斯公司 (Rogers Corporation) 的 RO4000 層壓板前置作業時間已從 2025 年的 16 週延長至 26 週。如果插入損耗超過每英吋 1dB,人工智慧加速器電路板將失去競爭力,因此買家將提前一年預訂銅箔。 IPC-6018D 設計規範現在規定毫米波電路板必須使用軋延銅箔,現貨溢價為合約價格的 15-20%。擁有軋延和層壓生產線的一體化供應商正在從中獲利。
銅價波動及利潤率承壓
2025年10月,倫敦金屬交易所(LME)現貨銅價上漲至每噸11,200美元,預計2026年第二季將接近每噸12,500美元。由於價格傳導條款的實施延遲了60至90天,導致銅箔生產商的息稅折舊攤提前利潤(EBITDA)下降了2至3個百分點。 2025年第三季度,溢價擴大至每噸280美元時,南亞地區沒有避險計畫的小規模冶煉廠累計了負利潤。國際能源總署(IEA)預測,到2035年,銅供應將出現30%的結構性缺口,這意味著銅價將持續波動。生產商正在簽訂多年期精礦銷售合約並投資廢銅回收,但這些收益需要18至36個月才能實現。
細分市場分析
預計到2025年,軋延銅將佔市場佔有率的59.67%。這主要得益於其均方根粗糙度(RMS)約為0.35µm,以及無與倫比的機械強度,該強度能夠有效降低30-300GHz頻率下基板趨膚效應造成的損耗。電解預計將以8.44%的複合年成長率成長,因為電池製造商正朝著6µm和4µm的厚度方向發展,而電解能夠在1350mm的寬度範圍內實現厚度均勻。每台多級軋延的資本密集度超過1億美元,這導致日本和歐洲生產商形成寡占,他們可以對超光滑產品收取每公斤28-35美元的價格。同時,預計到2024年,中國的電解產能將飆升至每年60萬噸,這將對標準的8µm銅牌造成價格競爭。
電解製程具有高加工能力,且在厚度小於5µm時微裂紋風險較低,這在高階銅箔市場向高能量密度電池轉型之際尤為有利。同時,對5G和AI基板的需求導致軋延銅箔的配額提前12個月預訂,從而形成了雙鏈供應鏈。一體化軋延銅箔製造商正在向上游整合其層壓業務,而電解專家則在超級工廠附近佈局,以實現準時交付。這些不同的經營模式表明,高階銅箔市場正持續兩極化。
區域分析
預計到2025年,亞太地區將佔全球銷售額的69.60%,並將在2031年之前以6.72%的複合年成長率持續成長,這主要得益於中國龐大的生產佔有率和韓國的6微米以下技術。中國將於2026年7月推出的GB標準,迫使大宗商品生產商要麼升級技術,要麼退出市場,這不僅給他們帶來了壓力,也促使他們追求溢價。韓國的SKC、Solus Advanced Materials和LS MTRON正在波蘭和馬來西亞擴大產能,以供應歐盟和東協的超級工廠,而日本企業則優先考慮高純度和軋延等細分領域的品質。
北美和歐洲正轉向本地化生產。隨著《通膨抑制法案》鼓勵對超級工廠的投資,北美高階銅箔市場規模預計將會擴大。然而,到2025年,該地區的電解銅箔產能仍將僅為每年1.8萬噸,在墨西哥和匈牙利的新生產線投入運作之前,進口銅箔的成本將高出12%至15%。歐洲電池法規強制要求使用再生材料,這鼓勵了現場回收利用,並吸引了Redwood Materials和Eumicore等公司的投資。
南美洲、中東和非洲仍然嚴重依賴進口。巴西每年進口約1萬噸銅箔用於家用電子電器,而沙烏地阿拉伯的「2030願景」正在加速建造需要高頻層壓技術的資料中心。儘管南非的礦業基地能夠供應銅精礦,但該地區缺乏銅箔生產能力,這意味著在南部非洲建立電池叢集未來可能成為半成品出口的典範。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電動車電池對超薄、高純度箔的需求
- 由於 5G/HPC 的發展,對高頻 PCB 的需求正在擴大。
- 超級工廠位置區域性繁榮(北美和歐盟)
- 電池級鋁箔閉合迴路回收計劃
- 高頻PCB基板供應緊張,導致對優質箔材的需求增加。
- 市場限制因素
- 銅價波動和利潤壓力
- 由於中國產能過剩,鋰離子電池的價格競爭導致該計畫擱淺。
- 向鈉離子(鋁集電器)的轉變削弱了對銅的需求。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 軋延銅箔
- 電解銅箔
- 透過使用
- 電路基板
- 電池
- 太陽能和替代能源
- 家用電器
- 醫學領域
- 其他
- 按地區
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Chang Chun Petrochemical Co. Ltd
- Co-Tech Development Corporation
- Doosan Corporation Electro-Materials.
- FUKUDA METAL FOIL & POWDER CO., LTD.
- Furukawa Electric Co., Ltd
- JX Advanced Metals Corporation
- Kingboard Holdings
- Londian Wason(Shenzhen)Holdings Group Co., Ltd.
- Lotte Energy Materials
- LS MTRON LTD.
- Mitsui Kinzoku Co., Ltd.
- NAN YA PLASTICS CORPORATION
- Nuode New Materials Co Ltd
- SKC
- Solus Advanced Materials
- Sumitomo Metal Mining Co., Ltd.
- Targray Technology International
- UACJ Foil Corporation
- Wieland
第7章 市場機會與未來展望
According to Mordor Intelligence, the high-End copper foil market size is estimated at USD 1.16 billion in 2026, and is expected to reach USD 1.58 billion by 2031, at a CAGR of 6.38% during the forecast period (2026-2031).
This report is Segmented by Product Type (Rolled Copper Foil and Electrodeposited Copper Foil), Application (Circuit Boards, Batteries, Solar and Alternative Energy, Appliances, Medical, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global High-End Copper Foil Market Trends and Insights
EV Battery Demand for Ultra-Thin High-Purity Foils
Every 2 µm reduction in foil thickness lifts gravimetric energy density by 5-6%, spurring OEMs to adopt 6 µm and 4 µm anode collectors. China shipped 1,334 GWh of lithium batteries in 2025 and is on track for 1,622 GWh in 2026, but July 2026 purity mandates will push marginal mills out of the high-end copper foil market. Western gigafactories demand 99.99% purity and sub-1% elongation variance, tilting awards toward Japanese and Korean suppliers. The International Energy Agency warns of a 30% primary-copper shortfall by 2035, intensifying the importance of thin-foil yield management. Premium electrodeposited grades command USD 22-28 per kg versus USD 15-18 for standard 8 µm foils, rewarding mills that master sub-6 µm deposition.
5G / HPC Push for High-Frequency PCBs
Hyperscale data centers upgrading to 800G and 1.6T Ethernet require dielectric constants below 3.5, forcing laminate makers to use ultra-low-profile rolled foils with surface roughness under 0.4 µm. Rogers Corporation's RO4000 laminate lead times lengthened from 16 to 26 weeks in 2025 because copper-foil supply was constrained. AI accelerator boards lose competitiveness when insertion loss exceeds 1 dB per inch, encouraging buyers to secure foil allocations a year in advance. IPC-6018D design rules now carve out rolled foil for mmWave boards, lifting spot premiums 15-20% above contracts. Integrated suppliers that own both rolling mills and laminate lines capture the value.
Copper Price Volatility and Margin Squeeze
London Metal Exchange spot rose to USD 11,200/t in October 2025, with Q2 2026 forecasts near USD 12,500/t, slashing foil-maker EBITDA by 2-3 percentage points because pass-through clauses lag 60-90 days. Smaller South Asian mills lacking hedge programs posted negative margins in Q3 2025 when premiums widened to USD 280/t. The IEA foresees a structural 30% copper supply deficit by 2035, preserving volatility. Producers are locking multi-year concentrate offtakes and investing in scrap recycling, but benefits accrue only after 18-36 months.
Other drivers and restraints analyzed in the detailed report include:
- Regional Gigafactory Localisation Wave
- Closed-Loop Battery-Grade Foil Recycling Initiatives
- Chinese Over-Capacity-Led Price Wars in Li-Battery Foil
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rolled copper accounted for 59.67% of 2025 value, supported by root-mean-square roughness near 0.35 µm and unrivaled mechanical strength that mitigates skin-effect losses on 30-300 GHz boards. Electrodeposited foil is projected to grow at 8.44% CAGR, driven by battery makers migrating toward 6 µm and 4 µm gauges that electrodeposition can deliver uniformly across 1,350 mm widths. Capital intensity runs above USD 100 million per multi-stage rolling mill, fostering an oligopoly among Japanese and European producers who can charge USD 28-35 / kg for ultra-smooth variants. Conversely, Chinese electrodeposition capacity surged to 600,000 tpa by 2024, sparking price wars in standard 8 µm grades.
Electrodeposited processes allow higher throughput and lower micro-crack risk below 5 µm thickness, an edge as the high-end copper foil market pivots to energy-dense cells. Meanwhile, 5G and AI boards drive pre-booking of rolled-foil allocations 12 months ahead, creating dual supply chains. Integrated rolled-foil mills are forward-integrating into laminates, while electrodeposited specialists co-locate near gigafactories to offer just-in-time delivery. These divergent models illustrate how the high-end copper foil market continues to bifurcate.
Complete Report Scope:
- By Product Type
- Rolled Copper Foil
- Electrodeposited (ED) Copper Foil
- By Application
- Circuit Boards
- Batteries
- Solar and Alternative Energy
- Appliances
- Medical
- Others
- By Geography
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 69.60% of 2025 revenue and is forecast at a 6.72% CAGR through 2031, bolstered by China's large production share and South Korea's sub-6 µm expertise. China's July 2026 GB standard is forcing technical upgrades or exits, squeezing commodity producers but supporting premium price realization. South Korea's SKC, Solus Advanced Materials, and LS MTRON are scaling capacity in Poland and Malaysia to serve EU and ASEAN gigafactories, while Japanese players prioritize quality in high-purity and rolled niches.
North America and Europe are pivoting toward localization. The high-end copper foil market size for North America is set to expand as the Inflation Reduction Act primes gigafactory investment. Yet only 18,000 tpa of regional electrodeposited capacity existed in 2025, necessitating imports at 12-15% cost premiums until greenfield lines in Mexico and Hungary come online. Europe's Battery Regulation layers recycled-content mandates that favor co-located recycling, attracting investments from Redwood Materials and Umicore.
South America, the Middle East, and Africa remain import-dependent. Brazil buys about 10,000 t of copper foil yearly for consumer electronics, while Saudi Arabia's Vision 2030 stimulates data-center builds that demand high-frequency laminates. South Africa's mining base offers concentrates, but the region lacks foil fabrication, hinting at future semi-finished export models if Southern African battery clusters emerge.
- Chang Chun Petrochemical Co. Ltd
- Co-Tech Development Corporation
- Doosan Corporation Electro-Materials.
- FUKUDA METAL FOIL & POWDER CO., LTD.
- Furukawa Electric Co., Ltd
- JX Advanced Metals Corporation
- Kingboard Holdings
- Londian Wason (Shenzhen) Holdings Group Co., Ltd.
- Lotte Energy Materials
- LS MTRON LTD.
- Mitsui Kinzoku Co., Ltd.
- NAN YA PLASTICS CORPORATION
- Nuode New Materials Co Ltd
- SKC
- Solus Advanced Materials
- Sumitomo Metal Mining Co., Ltd.
- Targray Technology International
- UACJ Foil Corporation
- Wieland
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV Battery Demand for Ultra-Thin High-Purity Foils
- 4.2.2 5G / HPC Push for High-Frequency PCBs
- 4.2.3 Regional Gigafactory Localisation Wave (North America and European Union)
- 4.2.4 Closed-Loop Battery-Grade Foil Recycling Initiatives
- 4.2.5 Tight Supply of HF PCB Substrates Drives Premium Foil Demand
- 4.3 Market Restraints
- 4.3.1 Copper Price Volatility and Margin Squeeze
- 4.3.2 Chinese Over-Capacity-Led Price Wars in Li-Battery Foil
- 4.3.3 Sodium-Ion Shift (Al Current Collectors) Cannibalises Copper
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts(Value)
- 5.1 By Product Type
- 5.1.1 Rolled Copper Foil
- 5.1.2 Electrodeposited (ED) Copper Foil
- 5.2 By Application
- 5.2.1 Circuit Boards
- 5.2.2 Batteries
- 5.2.3 Solar and Alternative Energy
- 5.2.4 Appliances
- 5.2.5 Medical
- 5.2.6 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 Japan
- 5.3.1.3 South Korea
- 5.3.1.4 India
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Chang Chun Petrochemical Co. Ltd
- 6.4.2 Co-Tech Development Corporation
- 6.4.3 Doosan Corporation Electro-Materials.
- 6.4.4 FUKUDA METAL FOIL & POWDER CO., LTD.
- 6.4.5 Furukawa Electric Co., Ltd
- 6.4.6 JX Advanced Metals Corporation
- 6.4.7 Kingboard Holdings
- 6.4.8 Londian Wason (Shenzhen) Holdings Group Co., Ltd.
- 6.4.9 Lotte Energy Materials
- 6.4.10 LS MTRON LTD.
- 6.4.11 Mitsui Kinzoku Co., Ltd.
- 6.4.12 NAN YA PLASTICS CORPORATION
- 6.4.13 Nuode New Materials Co Ltd
- 6.4.14 SKC
- 6.4.15 Solus Advanced Materials
- 6.4.16 Sumitomo Metal Mining Co., Ltd.
- 6.4.17 Targray Technology International
- 6.4.18 UACJ Foil Corporation
- 6.4.19 Wieland
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 全球銅箔市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 超薄秤 - 全球市場佔有率和排名、2026-2032年總銷售額和需求預測
 銅箔市場:依產品、應用和最終用途分類-2026-2032年全球市場預測銅箔市場規模、佔有率、成長及全球產業分析:按類型、應用和地區的洞察,2026-2034年的預測電沉積銅箔陰極鼓市場按應用、箔厚、粗糙度等級、最終用途行業和表面處理分類,全球預測,2026-2032年高耐腐蝕電解鎳化學品市場:依配方類型、最終用途產業、應用和物理形態分類,全球預測(2026-2032年)
 銅箔市場規模、佔有率、趨勢及預測(依產品類型、應用、最終用途產業及地區分類),2026-2034年
 2026年全球銅箔市場報告
 2026-2030年全球銅陰極市場全球無硼酸鍍鎳市場(依電鍍方法、鍍層厚度、終端用戶產業、應用與通路分類)預測(2026-2032年)