


 |
市場調查報告書
商品編碼
2119755
5K顯示解析度:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031年)5k Display Resolution - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
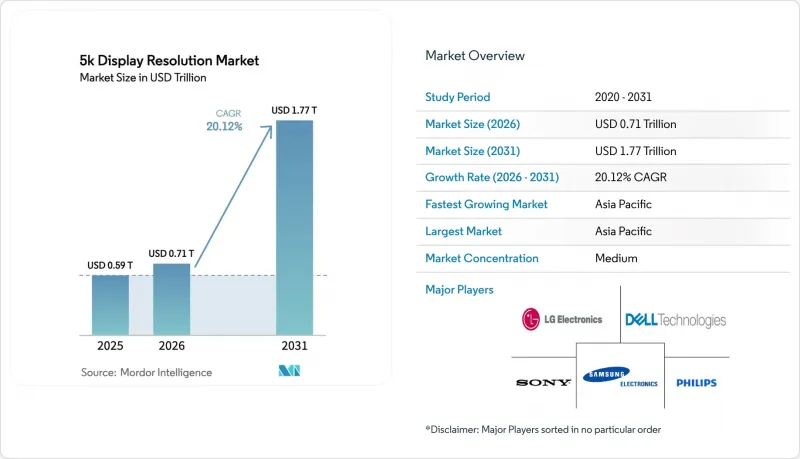
根據 Mordor Intelligence 估計,5K 顯示解析度市場在 2026 年的價值將達到 7,100 億美元,高於 2025 年的 5,900 億美元,預計到 2031 年將達到 1.77 兆美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 20.12%。
本報告按產品類型(顯示器、電視等)、面板技術(LCD、OLED、Mini-LED/Micro-LED)、原始解析度(5120×2880 (16:9) 等)、最終用戶應用(專業內容創作、商業數位電子看板和控制室等)、分銷管道(線上、線下)和地區進行細分。市場預測以美元計價。
全球5K顯示解析度市場趨勢與洞察
好萊塢和韓國的電影公司正在大力推廣使用支援 5K 解析度的 AI 後製工作站。
只有當面板提供 1,470 萬像素的連續畫布時,最先進的生成式填充、鑽機移除和 HDR 色調映射工具才能即時運作。洛杉磯兩家剪輯工作室的初步現場數據顯示,用一台 5K 顯示器替換兩台 4K 顯示器可將套底時間縮短 17%。韓國電視劇剪輯師也看到了類似的效果,他們已訂購了 43000 台 31 吋 IPS 5K 顯示器,預計到 2026 年將投入使用。工作站 OEM 廠商正在將 DisplayPort 2.1 相容卡標準化,這表明頻寬瓶頸已被徹底消除。雲端最後加工公司也在效仿,因為在 10GbE 鏈路上傳輸該解析度的 ProRes 中間資料速率低於 800 Mbps。
隨著海灣合作理事會(GCC)地區機場指揮控制系統的升級,超寬 5K指示牌的擴展也隨之展開。
在阿布達比中場航站樓,一塊長88公尺、解析度為5120 x 1440像素的LED顯示器於2024年11月運作,徹底消除了先前干擾A-SMGCS疊加顯示效果的邊框瑕疵。沙烏地阿拉伯的「2030願景」航空電子設備藍圖計畫到2026年在利雅德和吉達再安裝230塊類似的顯示器。這些超寬螢幕的寬高比與雷達扇區的長寬比匹配,使操作員無需垂直移動視線即可準確感知色彩精確的警告訊息。此外,根據系統整合商稱,現在只需一條DisplayPort 2.1訊號線即可驅動兩塊5K螢幕,從而減少了15%的GPU機架數量並降低了功耗。
5K 面板中 Mini-LED 背光的高昂物料清單 (BOM) 成本,使得消費顯示器的平均售價 (ASP) 保持在較低水準。
一塊32吋的5K螢幕需要2048個調光區域,而4K螢幕只需要1152個。因此,在二次透鏡效率達到92%之前,5K螢幕的背光成本始終比同等級的4K螢幕高出120美元。根據ODM廠商估計,這項成本差異可能要到2026年才能降至65美元以下,這將延緩準專業級產品價格降至799美元以下的進程。因此,注重成本績效的消費者將持續選擇廣色域4K產品,減緩短期內的銷售成長。
細分市場分析
2025年,顯示器市場將佔總銷售額的41.27%,5K解析度顯示器市場規模將達2,435億美元。出貨量主要集中在31.5吋、解析度為5120 x 2880且通過HDR-600認證的IPS面板上。面板製造商正利用成熟氧化物面板的良率優勢,將顯示器玻璃的毛利率推高至19%。 2024年,平均售價(ASP)下降了11%,這推動了自由職業剪輯師和調色師對5K顯示器的需求成長。相較之下,原生5K在筆記型電腦領域的普及速度較慢,但預計在2025年第三季上市的14吋、解析度為5120 x 3200的OLED面板將使5K顯示器以不到2公斤的重量進入行動創作者的工作流程。
預計到2031年,筆記型電腦和平板電腦的需求將以26.4%的複合年成長率成長,成為所有產品類型中成長最快的。 OLED固有的高對比度彌補了輕薄機殼缺乏局部調光的不足,無需笨重的背光陣列即可滿足HDR規範。標配的USB-C介面支援DisplayPort 2.1替代模式,可實現與外部5K參考顯示器的單線連接。這種協同作用使筆記型電腦既可作為訊號源,又可作為外接顯示器,從而使每台設備的可用5K像素面積翻倍。
到2025年,平面轉換(IPS)和垂直排列(VA)液晶顯示器將佔62.88%的市佔率。成熟的基板尺寸、完善的偏光片堆疊技術以及規模經濟將確保液晶顯示器繼續在5K顯示解析度市場中佔據核心地位。由於其具成本效益,即使OLED和Mini-LED的出現導致平均售價(ASP)上漲,液晶顯示器預計仍將在2028年之前保持其出貨量的大部分佔有率。
儘管到2025年,mini-LED/micro-LED的出貨量僅佔總出貨量的9.48%,但其高價位——平均售價(ASP)是LCD的2.1倍以上——將使其成為收入中非常可觀的佔有率。得益於大面積mini-LED背光成本的下降,預計該細分市場將以28.9%的複合年成長率成長。蘋果、京東方和LG在2024年總合新增了35,000個mini-LED鍵合頭,確保了到2026年產能翻倍。因此,在真正的自發光micro-LED成熟並實現量產之前,5K解析度顯示器產業正依賴LCD和mini-LED相結合的混合設計,以實現效能的即時提升。
區域分析
預計到2025年,亞太地區將佔全球消費總額的35.98%,達2,123億美元,銷售量達640萬台。中國面向創作者的筆記型電腦的推出,以及北京和合肥在面板自給自足方面所做的努力,正推動供應鏈向該地區集中。韓國內容出口的激增加速了工作站的升級換代,進一步鞏固了亞太地區作為供應中心和需求驅動力的地位。
北美地區在好萊塢製片廠、3A級遊戲開發商和醫療設備OEM廠商的推動下,位居第二,預計2025年將佔全球銷售額的28.05%。北美5K解析度顯示器市場(僅指顯示器)預計將從2025年的1,184億美元成長到2031年的3,559億美元,複合年成長率達20.1%。聯邦政府針對醫療設備加速折舊的投資扣除政策正在加速醫院對5K手術顯示器的採用。
在德國精密製造業和英國廣播技術產業的支撐下,歐洲在2025年佔了全球支出的21.72%。 BMW和賓士對汽車駕駛座的採用,促成了與當地一級供應商的長期合作。歐盟能源法規正在推動氧化物TFT背板的普及,以降低待機功耗。預計到2028年,傳統的4K控制室顯示陣列將被5K顯示器大規模取代。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 好萊塢和韓國的電影公司正在大力推廣使用支援 5K 解析度的 AI 後製工作站。
- 隨著海灣合作理事會(GCC)地區機場指揮控制系統的升級,超寬 5K指示牌的擴展也隨之展開。
- 日本和德國推廣使用5K手術監視器進行機器人輔助手術
- DisplayPort 2.1 和 Thunderbolt 5 的廣泛應用推動了企業桌上型電腦對 5K 擴充座的需求不斷成長。
- 品牌主導的「以創作者為中心」的筆記型電腦正在中國上市,推動了對原生 5K OLED 面板的需求。
- 高階電動車(如 Lucid、NIO)配備的 5K儀錶群正在加速汽車產業的成長。
- 市場限制因素
- 5K 面板中 Mini-LED 背光的高昂物料成本 (BOM) 拉低了主流顯示器的平均售價 (ASP)。
- 一線城市以外地區 5K內容傳遞網路的滲透率較低。
- 色彩校準的複雜性和 4K 的興起正在推高專業影音整合商的服務成本。
- 高階電影製作設備採購週期中 6K/8K 替代方案的威脅。
- 技術展望
- 波特五力分析
- 投資分析(5K顯示器製造工廠的資本投資趨勢及創業投資的資金籌措)
第5章 市場規模與成長預測
- 依產品類型
- 監視器
- 電視機
- 攝影機和數位電影
- 筆記型電腦和平板電腦
- 智慧型手機
- 投影機和其他
- 面板技術
- LCD(IPS、VA)
- OLED
- Mini-LED/Micro-LED
- 按原生解析度
- 5120×2880 (16:9)
- 5120×3200 (16:10)
- 5120×1440 (21:9)
- 透過最終用戶應用程式
- 專業內容創作
- 商業數位電子看板和控制室
- 消費遊戲和娛樂
- 教育和培訓
- 醫學影像診斷
- 汽車駕駛座顯示器
- 透過分銷管道
- 線上(直銷、電商平台)
- 線下(零售、專業影音系統整合商)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- Strategic Developments
- Vendor Positioning Analysis
- 公司簡介
- Apple Inc.
- Dell Technologies
- HP Inc.
- LG Electronics Inc.
- Samsung Electronics Co. Ltd.
- Sony Group Corp.
- Koninklijke Philips NV
- ASUSTeK Computer Inc.
- Micro-Star International Co. Ltd.
- Red Digital Cinema LLC
- Canon Inc.
- Sharp Corp.
- ViewSonic Corp.
- BOE Technology Group Co. Ltd.
- AU Optronics Corp.
- TCL CSOT
- BenQ Corp.
- EIZO Corp.
- Panasonic Holdings Corp.
- Vizio Holding Corp.
第7章 市場機會與未來展望
According to Mordor Intelligence, the 5k display resolution market size in 2026 is estimated at USD 0.71 trillion, growing from 2025 value of USD 0.590 trillion with 2031 projections showing USD 1.77 trillion, growing at 20.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Monitors, Televisions, and More), Panel Technology (LCD, OLED, Mini-LED/Micro-LED), Native Resolution (5120 X 2880 (16:9), and More), End-User Application (Professional Content Creation, Commercial Digital Signage and Control Rooms, and More), Distribution Channel (Online, Offline), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global 5k Display Resolution Market Trends and Insights
Surging Adoption of 5K-Ready Workstations for AI-Assisted Post-Production in Hollywood and Korean Studios
Cutting-edge generative fill, rig removal and HDR tone-mapping tools now operate in real time only when panels present a contiguous 14.7 million-pixel canvas. Early field data from two Los Angeles suites shows a 17% reduction in conform time after replacing dual 4K monitors with single 5K units. Korean drama editors record similar wins and are ordering 43,000 incremental 31-inch IPS 5K screens through 2026. Workstation OEMs quote DisplayPort 2.1 cards as standard, signaling the final removal of bandwidth bottlenecks, and cloud bureau finishing houses echo the shift to 5K because mezzanine ProRes at that resolution stays below 800 Mbps over 10 GbE links.
Expansion of Ultra-Wide 5K Signage in Airport Command-and-Control Upgrades across GCC
Abu Dhabi's Midfield terminal switched on 88 linear meters of 5,120 X 1,440 LED cabinets in November 2024, eliminating bezel artefacts that previously obstructed A-SMGCS overlays. Saudi Arabia's Vision 2030 avionics roadmap earmarks a further 230 such panels for Riyadh and Jeddah by 2026. Ultra-wide canvases match radar sector aspect ratios, decrypting color-critical warnings without forcing operators to scan vertically. Integrators also report a 15% reduction in GPU rack count as single DisplayPort 2.1 feeds can now drive two 5K canvases, lowering power budgets.
High BOM Cost of Mini-LED Backlights in 5K Panels Limiting Mainstream Monitor ASPs
A 32-inch 5K screen needs 2,048 dimming zones versus 1,152 zones on 4K, holding backlight costs at USD 120 above comparable 4K until secondary lens efficiency hits 92%. ODM quotes suggest the delta may not fall below USD 65 until 2026, delaying prosumer price points below USD 799. Value-oriented buyers consequently stick with wide-gamut 4K, tempering near-term unit growth.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of 5K Surgical Monitors for Robotic-Assisted Procedures in Japan and Germany
- In-Vehicle 5K Instrument Clusters in Premium EVs (Lucid, NIO) Accelerating Automotive Vertical
- Low Penetration of 5K Content Delivery Networks Outside Tier-1 Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The monitor segment generated 41.27% of 2025 revenue, translating to USD 243.5 billion of the 5k display resolution market. Shipments concentrate in 31.5-inch 5,120 X 2,880 IPS panels bundled with HDR-600 certification. Panel makers leverage matured oxide yields, pushing gross margins to 19% on monitor-class glass. Retail ASPs declined 11% in 2024, broadening appeal among freelance editors and colorists. By contrast, the laptop cohort lags in native 5K penetration, but 14-inch 5,120 X 3,200 OLED panels announced for Q3 2025 shipping insert 5K into mobile creator workflows at under 2 kilograms carry weight.
Laptop and tablet demand will pace at 26.4% CAGR through 2031, the highest across product types. OLED's inherent emissive contrast masks the absence of local dimming on thin-and-light form factors, satisfying HDR specifications without bulkier backlight arrays. Bundled DisplayPort 2.1 alternate-mode USB-C ports guarantee single-cable connections to external 5K reference monitors. This synergy ensures laptops act as both source and companion display, doubling the counted 5K pixel footprint per purchase.
LCD in-plane switching (IPS) and vertical alignment (VA) commanded 62.88% revenue share in 2025. Mature substrate sizes, well-understood polarizer stacks and volume economies keep LCD the anchor segment of the 5k display resolution market. Cost efficiencies will help LCD retain a majority unit share through 2028 even as OLED and mini-LED raise blended ASPs.
Mini-LED / micro-LED, while only 9.48% of 2025 units, accounts for an outsized revenue mix due to ASP premiums that exceed LCD by 2.1X. Segment forecasts point to a 28.9% CAGR, aided by converging costs on large-area mini-LED backlights. Apple, BOE and LG collectively added 35,000 mini-LED bonding heads in 2024, providing the throughput to double output by 2026. The 5k display resolution industry thus leans on hybrid LCD-mini-LED designs for immediate performance gains while true emissive micro-LED matures for volume.
Complete Report Scope:
- By Product Type
- Monitors
- Televisions
- Cameras and Digital Cinema
- Laptops and Tablets
- Smartphones
- Projectors and Others
- By Panel Technology
- LCD (IPS, VA)
- OLED
- Mini-LED / Micro-LED
- By Native Resolution
- 5120 X 2880 (16:9)
- 5120 X 3200 (16:10)
- 5120 X 1440 (21:9)
- By End-user Application
- Professional Content Creation
- Commercial Digital Signage and Control Rooms
- Consumer Gaming and Entertainment
- Education and Training
- Healthcare Imaging
- Automotive Cockpit Displays
- By Distribution Channel
- Online (Direct, Marketplaces)
- Offline (Retail, Pro-AV System Integrators)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 35.98% of 2025 spending, equal to USD 212.3 billion and 6.4 million units. Creator laptop launches in China and panel self-sufficiency initiatives in Beijing and Hefei concentrate supply chains in the region. Korea's content export boom amplifies workstation upgrades, further cementing Asia-Pacific's role as both supply hub and demand driver.
North America ranked second at 28.05% of 2025 revenue, led by Hollywood studios, AAA game developers and medical device OEMs. The 5k display resolution market size for North America monitors alone is projected to climb from USD 118.4 billion in 2025 to USD 355.9 billion by 2031 at a 20.1% CAGR. Federal investment allowances covering accelerated depreciation on medical capital equipment speed hospital adoption of 5K surgical monitors.
Europe contributed 21.72% of 2025 outlays, underpinned by Germany's precision manufacturing culture and the United Kingdom's broadcast technology sector. Automotive cockpit wins at BMW and Mercedes-Benz place long-dated contracts on local Tier-1 suppliers. EU energy regulations incentivize oxide TFT backplanes that reduce standby power, prompting widescale replacement of legacy 4K control-room arrays with 5K equivalents by 2028.
- Apple Inc.
- Dell Technologies
- HP Inc.
- LG Electronics Inc.
- Samsung Electronics Co. Ltd.
- Sony Group Corp.
- Koninklijke Philips N.V.
- ASUSTeK Computer Inc.
- Micro-Star International Co. Ltd.
- Red Digital Cinema LLC
- Canon Inc.
- Sharp Corp.
- ViewSonic Corp.
- BOE Technology Group Co. Ltd.
- AU Optronics Corp.
- TCL CSOT
- BenQ Corp.
- EIZO Corp.
- Panasonic Holdings Corp.
- Vizio Holding Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Adoption of 5K-ready Workstations for AI-assisted Post-Production in Hollywood and Korean Studios
- 4.2.2 Expansion of Ultra-Wide 5K Signage in Airport Command-and-Control Upgrades across GCC
- 4.2.3 Proliferation of 5K Surgical Monitors for Robotic-Assisted Procedures in Japan and Germany
- 4.2.4 Roll-out of DisplayPort 2.1 and Thunderbolt 5 Boosting 5K Docks in Enterprise Desktops
- 4.2.5 Brand-led "Creator Class" Laptop Launches in China Driving Native-5K OLED Panel Demand
- 4.2.6 In-vehicle 5K Instrument Clusters in Premium EVs (Lucid, NIO) Accelerating Automotive Vertical
- 4.3 Market Restraints
- 4.3.1 High BOM Cost of Mini-LED Backlights in 5K Panels Limiting Mainstream Monitor ASPs
- 4.3.2 Low Penetration of 5K Content Delivery Networks Outside Tier-1 Cities
- 4.3.3 Color-Calibration Complexity vs 4K Raising Service Costs for Pro-AV Integrators
- 4.3.4 Substitution Threat from 6K/8K in High-End Cinematography Equipment Procurement Cycles
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Buyers
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Investment Analysis (Capex Trends and VC Funding in 5K Display Fabs)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Monitors
- 5.1.2 Televisions
- 5.1.3 Cameras and Digital Cinema
- 5.1.4 Laptops and Tablets
- 5.1.5 Smartphones
- 5.1.6 Projectors and Others
- 5.2 By Panel Technology
- 5.2.1 LCD (IPS, VA)
- 5.2.2 OLED
- 5.2.3 Mini-LED / Micro-LED
- 5.3 By Native Resolution
- 5.3.1 5120 X 2880 (16:9)
- 5.3.2 5120 X 3200 (16:10)
- 5.3.3 5120 X 1440 (21:9)
- 5.4 By End-user Application
- 5.4.1 Professional Content Creation
- 5.4.2 Commercial Digital Signage and Control Rooms
- 5.4.3 Consumer Gaming and Entertainment
- 5.4.4 Education and Training
- 5.4.5 Healthcare Imaging
- 5.4.6 Automotive Cockpit Displays
- 5.5 By Distribution Channel
- 5.5.1 Online (Direct, Marketplaces)
- 5.5.2 Offline (Retail, Pro-AV System Integrators)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Apple Inc.
- 6.3.2 Dell Technologies
- 6.3.3 HP Inc.
- 6.3.4 LG Electronics Inc.
- 6.3.5 Samsung Electronics Co. Ltd.
- 6.3.6 Sony Group Corp.
- 6.3.7 Koninklijke Philips N.V.
- 6.3.8 ASUSTeK Computer Inc.
- 6.3.9 Micro-Star International Co. Ltd.
- 6.3.10 Red Digital Cinema LLC
- 6.3.11 Canon Inc.
- 6.3.12 Sharp Corp.
- 6.3.13 ViewSonic Corp.
- 6.3.14 BOE Technology Group Co. Ltd.
- 6.3.15 AU Optronics Corp.
- 6.3.16 TCL CSOT
- 6.3.17 BenQ Corp.
- 6.3.18 EIZO Corp.
- 6.3.19 Panasonic Holdings Corp.
- 6.3.20 Vizio Holding Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 2026年全球平板電腦和書架市場報告
 LED汽車顯示器市場:按類型、車輛類型、顯示器配置、應用和地區分類
 顯示技術市場:按類型、螢幕大小、面板技術和最終用戶分類-2026-2032年全球市場預測
 全球顯示器市場(至 2032 年):按顯示器技術(LCD、OLED、MicroLED)、量子點顯示器、DirectView LED、面板尺寸(微型顯示器、中小型顯示器、大型顯示器)和產品類型(汽車顯示器、穿戴式裝置、數位電子看板、智慧型手機)分類
 顯示器市場規模及預測(2021-2034)、趨勢及成長機會分析報告:依面板尺寸、面板類型、產品類型、產業及地區分類2026年全球顯示器市場報告平板電腦顯示器市場:按類型、應用程式和地區分類
 全球國防多功能一體機市場2026年全球半導體顯示器市場報告
 教室顯示市場:按類型、應用和地區分類(2026-2034 年)