


 |
市場調查報告書
商品編碼
2119675
汽車前臉:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Automotive Fascia - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
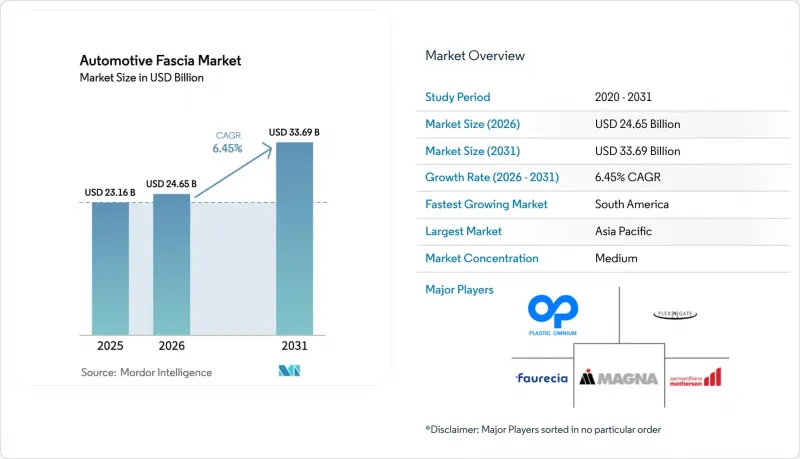
據 Mordor Intelligence 稱,2025 年汽車前臉市值為 231.6 億美元,預計到 2031 年將達到 336.9 億美元,而 2026 年為 246.5 億美元,預測期(2026-2031 年)的複合年成長率為 6.45%。
本報告按地點類型(前保險桿、後保險桿)、材料(塑膠塗層發泡聚苯乙烯、塑膠塗層鋁等)、車輛類型(乘用車等)、銷售管道(原廠配套、售後市場)和地區進行細分。市場預測以美元計價。
全球汽車前臉市場趨勢與洞察
電動汽車和自動駕駛汽車平台的發展
電動車的普及改變了冷卻負荷,並促成了無格柵、開放式設計,供應商被迫重新設計前臉模組,以便在不增加空氣阻力的情況下容納雷射雷達、4D雷達和高解析度攝影機。現代摩比斯發布了一款用於純電動車的整合式前臉組件,將主動式百葉窗、毫米波雷達和攝影機清潔系統整合到一個子組件中。此外,馬瑞利宣布與合賽汽車合作,將感測硬體從保險桿外殼轉移到大燈叢集,方法是將LiDAR整合到頭燈外殼中。同時,高階800伏特電動車需要電磁屏蔽以應對高頻開關,因此前臉面板採用鋁膜和塑膠面漆的組合來實現電磁干擾防護。
減輕重量並符合排放氣體法規
歐盟更嚴格的二氧化碳排放上限和北美的CAFE標準迫使汽車製造商在滿足FMVSS碰撞測試要求的同時,實現輕量化結構。碳纖維增強塑膠(CFRP)與鋼材相比,重量最多可減輕60%,同時維持相同的碰撞能量吸收性能。康斯坦鋁業的M-LightEn聯盟已將超高強度鋁材商業化,其回收率高達80%,使零件的碳纖維強度降低了一半。豐田合成正在檢驗纖維素奈米纖維增強聚丙烯來減輕重量並降低整個生命週期的排放。隨著感測器數量的增加,重量也隨之增加,工程師在設計LiDAR外殼和雷達罩時,需要在減輕重量和增加重量之間取得平衡。
高昂的維護和更換成本
車輛停放時輕微刮擦後,重新校準雷達和相機模組可能會使維修成本增加37%,這對保險公司的獲利能力和消費者的支付意願都構成了挑戰。原廠認證的保險桿塗料必須保持雷達滲透性,這限制了維修塗料的選擇,並促使客戶選擇配備昂貴校準設備的認證維修店。獨立維修店被迫在ADAS校準工位上投入大量資金,加速了市場整合。此外,零件複雜性的增加導致維修延誤時間延長,而更長的租賃期迫使保險公司與一級供應商談判更大的零件折扣。
細分市場分析
到2025年,前保險桿組件將佔據汽車保險桿市場63.78%的佔有率,凸顯其在降低空氣阻力和保護行人方面的重要作用。預計該細分市場將以6.66%的複合年成長率成長,主要驅動力在於需要在不增加正面面積的情況下安裝高解析度攝影機、遠端雷達和清洗噴嘴。在整個設計週期中,清洗液通道和熱源直接整合到保險桿橫樑中,以確保感測器即使在冰凍條件下也能運作。雖然後保險桿系統目前的收入佔比不及前保險桿,但它們也在不斷發展,以容納智慧照明陣列和泊車雷達,從而支援自動泊車軟體。
法雷奧已開始檢驗一種印有嵌入式微型LED矩陣的車身外殼,該外殼可顯示動態轉向訊號和騎行者警告訊息,開創了以資訊溝通為中心的車身外殼設計先河。美國國家公路交通安全管理局(NHTSA)即將修訂的FMVSS 228法規將提高對符合標準的碰撞槽和可變形泡棉材料的需求,這些材料需能將頭部損傷閾值控制在1000 HIC或以下,這將進一步深化聚合物化學家和碰撞模擬工程師之間的合作。具有最佳化蜂窩結構的生物聚丙烯泡沫材料因其兼具能量吸收和可回收性而備受關注。
由於成型成本趨於穩定且全球模具供應充足,預計到2025年,塑膠包覆發泡聚苯乙烯仍將佔據汽車面板市場46.10%的佔有率。然而,隨著電動車製造商利用鋁的導熱性來散發逆變器產生的熱量,預計到2031年,塑膠包覆鋁板的複合年成長率將達到5.96%。厚度為1毫米的鋁基板覆以抗衝擊改性聚丙烯(PP)護套,通過了行人碰撞測試,且比同類PP/EPP發泡體輕15%。新型複合材料護套將生物聚氨酯背襯泡棉與再生鋁膜結合,使汽車製造商能夠突顯其從原料開採到產品出廠的二氧化碳減排效益。
MacDermid Enthone公司推出了一種陽極氧化劑,簡化了金屬和聚合物護套之間的黏合工藝,可實現低溫塑膠包覆成型並防止起泡。 Constellium公司正在其產品等級中利用從飲料罐中回收的鋁廢料,這表明汽車面板行業正朝著循環經濟的方向邁進。鋼橡膠混合材料在重型卡車市場找到了新的定位,在該市場中,抗石擊性能比重量更為重要。
區域分析
到2025年,亞太地區將佔據47.96%的銷售佔有率,鞏固其作為汽車前臉市場製造地的地位。中國將在2024年成為全球最大的汽車生產國之一,並持續擴大其超級鑄造先導計畫。該項目能夠將前臉、防撞樑和電池托盤等部件在一次鋁鑄件成型中完成,從而減少零件數量。印度的汽車零件發展藍圖目標是到2026年實現2,000億美元的銷售額,並輔以與生產連結獎勵計畫,最高可報銷13%的本地增加價值。本田在加拿大投資150億加幣(約110億美元)建造電動車價值鏈,將為亞洲一級模具製造商開闢通往北美的新出口通路。
南美洲是成長最快的地區,複合年成長率達6.98%。 Stellantis公司正在巴西和阿根廷投資56億歐元,用於建造生物混合動力動力總成平台。相容於生質乙醇的保險桿需要使用能夠耐受糖基燃料飛濺的塗層,這迫使當地的複合材料生產商調整其樹脂的化學成分。哥倫比亞已成為該地區第三大組裝基地,而秘魯則利用自由貿易協定,免稅向美國出口塑膠嵌件和鍍鉻裝飾件。外匯波動仍然是成本規劃的一大障礙,導致供應商擴大使用美元對沖樹脂合約的風險。
北美和歐洲在推動監管趨勢方面仍然具有重要的戰略意義。美國國家公路交通安全管理局 (NHTSA) 正在考慮的行人保護條例已被納入2026年北美車型的前臉設計。歐盟的循環經濟行動計畫提倡在裝飾件中使用再生塑膠,並鼓勵引入記錄樹脂來源的數位護照。紅海航線不斷飆升的戰爭風險溢價正促使汽車製造商將前臉模具的生產轉移到墨西哥和東歐等近岸地區。歐洲電動車的快速普及需要快速迭代無格柵設計。同時,美國的需求取決於充電基礎設施的發展,因此,為了降低風險,正在採用分階段模具計劃,在同一生產線上混合生產內燃機汽車 (ICE) 和電動車 (EV) 的前臉。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電動汽車和自動駕駛汽車平台的發展
- 減輕重量並符合排放氣體法規
- 將先進感測技術(LiDAR/雷達)整合到前面板
- 汽車產量和銷售成長
- OEM廠商採用模組化前端模組
- 向再生聚合物和生物基聚合物過渡
- 市場限制因素
- 原物料價格波動
- 高昂的維護和更換成本
- 高級駕駛輔助系統降低了碰撞頻率
- OEM垂直整合扼殺了售後市場。
- 價值供應鏈分析
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按位置類型
- 前筋膜
- 後保險桿
- 材料
- 塑膠塗層發泡聚苯乙烯
- 塑膠塗層鋁
- 其他(鋼、橡膠等)
- 車輛類型
- 搭乘用車
- 輕型商用車
- 中型和重型商用車輛
- 按銷售管道
- OEM
- 售後市場
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Plastic Omnium
- Magna International
- Faurecia SE
- Flex-N-Gate Corporation
- Samvardhana Motherson Group
- Gestamp Automocion
- Toyoda Gosei
- Dongfeng Electronic Technology
- Aisin Corporation
- Benteler Automotive
- Denso Corporation
- Yanfeng Automotive Trim
- Sanko Gosei
- Chiyoda Manufacturing
- Dakkota Integrated Systems
- Revere Plastics Systems
- Inhance Technologies
- Eakas Corporation
- MRC Manufacturing
第7章 市場機會與未來展望
According to Mordor Intelligence, the automotive fascia market size was valued at USD 23.16 billion in 2025 and estimated to grow from USD 24.65 billion in 2026 to reach USD 33.69 billion by 2031, at a CAGR of 6.45% during the forecast period (2026-2031).
This report is Segmented by Position Type (Front Fascia and Rear Fascia), Material (Plastic Covered Styrofoam, Plastic Covered Aluminum, and More), Vehicle Type (Passenger Cars and More), Sales Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Fascia Market Trends and Insights
Growth of EV and Autonomous Vehicle Platforms
Electric vehicles change cooling loads and open grille-less design options, forcing suppliers to redesign fascia modules that can mount LiDAR, 4D radar, and high-resolution cameras without raising drag. Hyundai Mobis has introduced integrated front-face units for battery cars that package active shutters, millimeter-wave radar, and camera cleaning systems into a single sub-assembly. Additionally, Marelli announced a partnership with Hesai to embed LiDAR into headlamp housings, shifting sensing hardware from bumper skins to lighting clusters. Moreover, premium 800-volt EVs need electromagnetic shielding for high-frequency switching, so fascia panels blend aluminum films with plastic topcoats for EMI control.
Light-weighting and Emission-Regulation Compliance
Stricter CO2 caps in the EU and CAFE targets in North America push OEMs toward lighter structures that still pass FMVSS impact tests. Carbon-fiber reinforced plastics cut as much as 60% mass versus steel yet deliver the same crush-energy absorption. Constellium's M-LightEn consortium commercializes ultra-high-strength aluminum grades with 80% recycled content, reducing component carbon intensity by half. Toyoda Gosei is validating cellulose-nanofiber reinforced polypropylene to trim weight and cradle-to-grave emissions. Sensor additions add weight back in, so engineers juggle mass savings with LiDAR housings and radar radomes.
High Maintenance and Replacement Cost
Calibration of radar and camera modules after a minor parking scrape can lift repair bills by 37%, challenging insurer economics and consumer willingness to pay. OEM-approved bumper paints must remain radar-transparent, narrowing repair-paint options and steering work to certified centers with costly alignment rigs. Independent shops face five-figure investments in ADAS calibration bays, prompting market consolidation. The higher part complexity also boosts idle time, raising rental-car days and pushing insurers to negotiate deeper part discounts with Tier 1 vendors.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Advanced Sensing (LiDAR/Radar) into Fascia
- Modular Front-End Modules Adoption by OEMs
- ADAS-Led Fall in Collision Frequency
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Front fascia assemblies represented 63.78% automotive fascia market share in 2025, underscoring their central role in aerodynamic drag reduction and pedestrian protection. This segment is forecast to progress at a 6.66% CAGR, fuelled by the need to mount high-definition cameras, long-range radar and cleaning nozzles without enlarging frontal area. Successive design cycles now route washer-fluid channels and heating elements directly into the bumper beam to guarantee sensor uptime in icy climates. Rear fascia systems trail in revenue but are also evolving to accommodate smart-lighting arrays and parking radars that help automated-parking software.
Valeo has begun validating fascia skins printed with embedded micro-LED matrices that deliver dynamic turn signals and cyclist alerts, a preview of communication-centric exteriors. The upcoming NHTSA FMVSS No. 228 rule changes amplify the need for compliant crush cans and deformable foams that maintain head-injury criteria below 1,000 HIC, driving deeper collaboration between polymer chemists and crash-simulation engineers. Bio-polypropylene foams with tuned cell geometry have emerged as candidates to balance energy absorption with recyclability.
Plastic-covered styrofoam retained a 46.10% slice of the automotive fascia market in 2025 due to mature molding economics and global tooling availability. Yet plastic-covered aluminum panels are on track for a 5.96% CAGR to 2031 as EV makers exploit aluminum's thermal conductivity to dissipate inverter heat. Thin 1 mm aluminum substrates laminated with impact-modified PP outer skins weigh 15% less than comparable PP/EPP foams while passing pedestrian impact. Emerging composite skins blend bio-polyurethane back-foams with recycled aluminum films, allowing OEMs to advertise lower cradle-to-gate CO2.
MacDermid Enthone has released anodizing chemistries that accept low-temperature plastics over-molding without blistering, streamlining joins between metal and polymer skins. Recycled aluminum scrap flows from beverage cans into Constellium grades, proving automotive fascia industry progress toward circularity. Steel and rubber blends hold niche beachheads in heavy-duty trucks where stone-chip resistance outweighs weight concerns.
Complete Report Scope:
- By Position Type
- Front Fascia
- Rear Fascia
- By Material
- Plastic-covered Styrofoam
- Plastic-covered Aluminum
- Other Materials (Steel, Rubber, etc.)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- By Sales Channel
- OEM
- Aftermarket
- By Region
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
In 2025, Asia Pacific secured 47.96% of the revenue share, solidifying its position as the manufacturing epicenter of the automotive fascia market. China is one of the largest producers of vehicles in 2024 and keeps scaling gigacasting pilots that could roll fascia, crash beam, and battery tray into one aluminum shot, reducing part counts. India's auto-components roadmap targets a USD 200 billion turnover by FY26, supported by production-linked incentives that reimburse up to 13% of local value addition. Honda's CAD 15 billion (USD 11 billion) commitment to develop a Canadian EV supply chain will open new North American export routes for Asian Tier 1 tooling firms.
South America is the fastest-growing region, with a 6.98% CAGR as Stellantis channels EUR 5.6 billion into Bio-Hybrid drivetrain platforms built in Brazil and Argentina. Bio-ethanol-compatible bumpers require coatings resistant to sugar-based fuel sprays, prompting local formulators to adapt resin chemistries. Colombia has become the region's third-largest assembler, while Peru leverages free-trade agreements to ship plastic inserts and chrome trims into the United States duty-free. Exchange-rate volatility remains a cost-planning hurdle, so suppliers increasingly hedge resin contracts in USD.
North America and Europe retain strategic importance as regulation trend-setters. NHTSA's pending pedestrian rule is already embedded in 2026 model-year North American fascia designs. The EU Circular Economy Action Plan pushes recyclates into trim components and incentivizes digital passports that log resin genealogy. War-risk premiums on Red Sea freight lanes have nudged OEMs toward near-shoring fascia tool builds in Mexico and Eastern Europe. Europe's EV adoption pace demands fast cycles on grille-less styling; conversely, US demand is tied to charging-infrastructure roll-outs, leading to phased tooling plans that mix ICE and EV fascias on the same line for risk mitigation.
- Plastic Omnium
- Magna International
- Faurecia SE
- Flex-N-Gate Corporation
- Samvardhana Motherson Group
- Gestamp Automocion
- Toyoda Gosei
- Dongfeng Electronic Technology
- Aisin Corporation
- Benteler Automotive
- Denso Corporation
- Yanfeng Automotive Trim
- Sanko Gosei
- Chiyoda Manufacturing
- Dakkota Integrated Systems
- Revere Plastics Systems
- Inhance Technologies
- Eakas Corporation
- MRC Manufacturing
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of EV and Autonomous Vehicle Platforms
- 4.2.2 Light-weighting and Emission-Regulation Compliance
- 4.2.3 Integration of Advanced Sensing (LiDAR/Radar) into Fascia
- 4.2.4 Increasing Vehicle Production and Sales
- 4.2.5 Modular Front-End Modules Adoption by OEMs
- 4.2.6 Shift to Recycled & Bio-Based Polymers
- 4.3 Market Restraints
- 4.3.1 Raw-Material Price Volatility
- 4.3.2 High Maintenance and Replacement Cost
- 4.3.3 ADAS-Led Fall in Collision Frequency
- 4.3.4 OEM Vertical Integration Curbing Aftermarket
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Position Type
- 5.1.1 Front Fascia
- 5.1.2 Rear Fascia
- 5.2 By Material
- 5.2.1 Plastic-covered Styrofoam
- 5.2.2 Plastic-covered Aluminum
- 5.2.3 Other Materials (Steel, Rubber, etc.)
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.4 By Sales Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Egypt
- 5.5.5.4 South Africa
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Plastic Omnium
- 6.4.2 Magna International
- 6.4.3 Faurecia SE
- 6.4.4 Flex-N-Gate Corporation
- 6.4.5 Samvardhana Motherson Group
- 6.4.6 Gestamp Automocion
- 6.4.7 Toyoda Gosei
- 6.4.8 Dongfeng Electronic Technology
- 6.4.9 Aisin Corporation
- 6.4.10 Benteler Automotive
- 6.4.11 Denso Corporation
- 6.4.12 Yanfeng Automotive Trim
- 6.4.13 Sanko Gosei
- 6.4.14 Chiyoda Manufacturing
- 6.4.15 Dakkota Integrated Systems
- 6.4.16 Revere Plastics Systems
- 6.4.17 Inhance Technologies
- 6.4.18 Eakas Corporation
- 6.4.19 MRC Manufacturing
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 汽車飾板市場分析至2035年的預測:類型、技術、組件、應用、材料類型、製程、最終用戶、功能、安裝類型、解決方案
 2026年全球汽車面板市場報告
 汽車前臉市場 - 全球產業規模、佔有率、趨勢、機會及預測(按地點類型、銷售管道、應用、地區和競爭格局分類,2021-2031年)
 2026-2030年全球汽車前臉市場
 汽車前臉市場規模、佔有率和成長分析(材質、車輛類型、安裝位置、銷售管道和地區分類)-2026-2033年產業預測
 全球汽車儀表板市場:依車型、位置類型、材料類型、銷售通路、地區、機會及預測,2018-2032
 全球汽車儀表板市場
 全球汽車面板市場:成長、未來展望與競爭分析(2025-2033 年)汽車儀表板市場 - 全球產業規模、佔有率、趨勢機會和預測,按位置類型、應用程式類型、銷售通路類型、地區和競爭細分,2019-2029F