


 |
市場調查報告書
商品編碼
2119627
庚酸群勃龍:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Trenbolone Enanthate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年群勃龍庚酸酯市場價值為 8,775 萬美元,預計到 2031 年將達到 1.0628 億美元,而 2026 年為 9,060 萬美元,預測期(2026-2031 年)的複合年成長率為 3.25%。
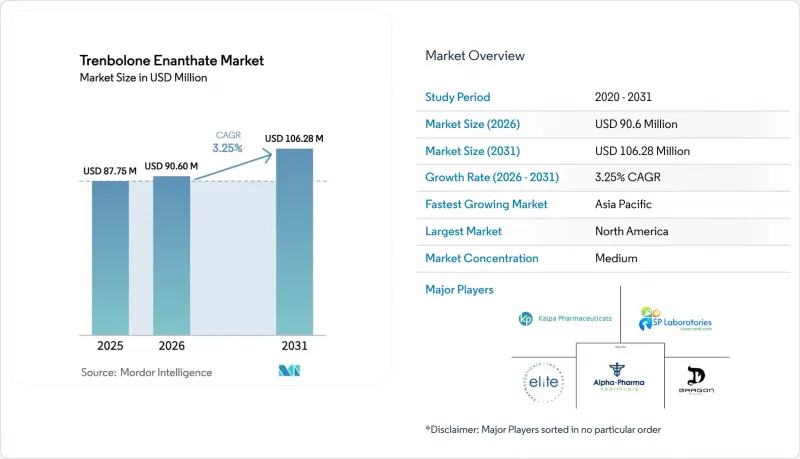
本報告按藥物類型(口服、注射)、應用領域(人用、獸用)、最終用戶(製藥公司、動物用藥品公司、醫院/診所及其他最終用戶)和地區(北美、歐洲、亞太、中東和非洲、南美)進行細分。市場預測以美元計價。
全球庚酸群勃龍市場趨勢與洞察
人們對健美和健身生活方式的興趣日益濃厚
健身文化的興起和社群媒體的普及使得關於興奮劑的討論更加廣泛,也導致健身愛好者和競技健身者對群勃龍的認知度不斷提高。一些網紅經常展示驚人的身材變化,間接地推廣了這種承諾在較短週期內顯著成長肌肉的強效化合物。歐洲的產業調查顯示,每年有數十萬成年男性承認使用合成代謝類固醇,這表明其市場滲透率已遠遠超出精英運動領域。群勃龍的合成代謝作用大約是睪固酮的五倍,使其成為追求更緊實、更精瘦肌肉的高級使用者的首選。這種文化轉變支撐著穩定的零售基礎,即便在打擊力度不斷增加的情況下也是如此。
透過線上和非官方通路擴大獲取途徑。
加密通訊應用程式、小批量代出貨和加密貨幣支付正在簡化消費者獲取注射類藥物的流程。合成代謝類藥物在全球加密貨幣驅動的毒品交易中佔據相當大的佔有率。即使被海關查獲,中國供應商也能透過定期更改產品代碼和運輸標籤來維持出口管道。私人健身社群內的互評系統提高了供應商的信譽度,並降低了首次購買者的進入門檻。這些數位化管道的結合,正在緩解因區域供應中斷而導致的需求激增,並有助於穩定群勃龍庚酸酯市場,即使在打擊行動中也是如此。
加強法律規範和禁令
跨境聯合調查小組正在加強打擊毒品犯罪。例如,國際刑警組織於2025年開展的「盤古行動XVII」繳獲了價值6,500萬美元的非法毒品,並逮捕了769名嫌疑犯。同時,美國緝毒局的「網路果汁行動」搗毀了數十家位於美國的數位毒品供應商,凸顯了對網路分銷日益成長的關注。處罰措施包括沒收資產和長期監禁,迫使地下制毒窩點承擔更高的營運風險和成本。這些打擊行動可能會導致供應緊張、終端用戶價格上漲,並疏遠新用戶,可能減緩群勃龍庚酸酯市場短期內的整體成長動能。
細分市場分析
到2025年,注射用群勃龍庚酸酯將佔58.92%的市場。與口服製劑相比,其更高的生物利用度、8-12天的半衰期以及更低的肝毒性,有助於使用者在牛管理和生長週期中更可靠地堅持用藥。預計到2031年,該細分市場將以6.92%的複合年成長率成長,顯著超過口服製劑。隨著中國契約製造生產商擴大符合GMP標準的填充和包裝生產線,價格競爭力不斷提升,這種成本優勢也惠及獸藥批發商和灰色市場經銷商。此外,獸用植入方案(每個週期只需注射一次)的日益普及,進一步鞏固了注射劑作為首選給藥方式的地位。
對仿冒口服錠劑的打擊力道加大,也促使消費者轉向使用檢驗批號的密封管瓶產品。加之物流效率的提高,這項變化支撐了市場佔有率的穩定成長。儘管部分不願注射的使用者對口服製劑有小眾需求,但由於首過代謝和劑量帶來的肝臟負擔,口服製劑的成長依然緩慢。因此,注射劑仍是庚酸群勃龍市場的主力軍,而口服製劑的銷售量預計將保持在較低水平,主要作為輔助產品。這一趨勢確保了注射劑在庚酸群勃龍市場的整體表現中繼續發揮核心作用。
區域分析
預計到2025年,北美將佔全球銷售額的39.82%。這主要得益於蓬勃發展的健美次文化,該文化帶動了經FDA批准的牛植入和高價注射藥物的銷售。區域獸醫網路受惠於成熟的冷鏈基礎設施,能夠大規模分銷至育肥場和獸藥店。合法的動物產品通路,加上嚴格透明地禁止用於人類用途的執法,共同創造了一個可預測的商業環境。
亞太地區預計將以8.14%的複合年成長率成長,成長速度在所有地區中最高。中國在原料藥成分合成領域的領先地位支撐著其以具有競爭力的價格出口,而印度的契約製造基地則為各種製劑形式提供了柔軟性,從多劑量管瓶到緩釋顆粒劑均有涵蓋。快速的都市化提高了人們的可支配收入,帶動了健身房會員人數的成長,並促使年輕一代廣泛試驗營養補充品。同時,為滿足不斷成長的蛋白質消費需求,國內牛群數量的擴張也推動了對常規獸藥產品的需求,從而刺激了供需雙方的需求。
在歐洲,由於持續禁止在牲畜中使用激素類生長促進劑,因此對該產品持謹慎態度。然而,尤其是在東歐,價格敏感度促使大量進口本地重新包裝的粉末,並透過地下健身房和電子商務等非法管道不斷進行分銷。監管機構正在協調邊境檢查站和郵政樞紐的檢查工作,但執法體系的分散性造成了漏洞,並被跨境網路所利用。這些矛盾導致整體成長乏力。儘管獸用領域的潛在需求疲軟,但人類用藥需求依然強勁,歐洲在群勃龍庚酸酯市場中仍佔據重要佔有率,但受到嚴格監管。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人們對健美和健身生活方式的興趣日益濃厚
- 透過線上和非官方分發管道擴大獲取途徑。
- 在獸醫學領域得到更廣泛的應用
- 正在進行激素缺乏症治療方面的研究和開發
- 基於暗網和加密資產的供應鏈擴張
- 開發中國家肽類固醇的低成本生產
- 市場限制因素
- 加強法律規範和禁令
- 存在更高的不良健康影響風險。
- 過渡到更安全的替代方案,例如選擇性雄性激素受體調變器(SARMs)
- 加強對社群媒體廣告平台的監管
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 依藥物類型
- 口服
- 注射藥物
- 透過使用
- 對人類而言
- 動物利用
- 最終用戶
- 製藥公司
- 動物用藥品和保健公司
- 醫院和診所
- 其他最終用戶
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他亞太國家
- 中東和非洲
- GCC
- 南非
- 其他中東和非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 市佔率分析
- 公司簡介
- Globalanabolic
- Dragon Pharmaceuticals
- Elite Pharmaceuticals
- Kalpa Pharmaceuticals
- SP Laboratories
- Alpha Pharma
- Labdhi Pharmaceuticals
- Euro Pharmacies
- Meditech Pharmaceuticals
- Hilma Biocare
- Pharmacom Labs
- Gen-Shi Laboratories
- British Dragon
- Landerlan
- Magnus Pharmaceuticals
- Balkan Pharmaceuticals
- Thaiger Pharma
- Swiss Remedies
- Pharmatec
- Bayer
第7章 市場機會與未來展望
According to Mordor Intelligence, the trenbolone enanthate market size was valued at USD 87.75 million in 2025 and estimated to grow from USD 90.6 million in 2026 to reach USD 106.28 million by 2031, at a CAGR of 3.25% during the forecast period (2026-2031).
This report is Segmented by Drug Type (Oral, Injectables), Application (Human Use, Animal Use), End User (Pharmaceutical Companies, Veterinary Health Companies, Hospitals & Clinics, Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Trenbolone Enanthate Market Trends and Insights
Surging Interest in Bodybuilding and Fitness Lifestyles
Widespread fitness culture and social-media exposure have normalised discussions around performance-enhancing substances, elevating trenbolone's profile among gym-goers and competitive bodybuilders. Influencers often spotlight dramatic physique transformations, indirectly promoting stronger compounds that promise significant muscle accretion in shorter cycles. Industry surveys in Europe show hundreds of thousands of adult males admitting to anabolic steroid use each year, signalling deep market penetration beyond elite sports. Trenbolone's anabolic potency, roughly quintuple that of testosterone, makes it a favoured option for advanced users seeking dense, lean mass gains. This cultural shift underpins a stable retail base even while enforcement intensity rises.
Wider Access via Online and Informal Distribution Channels
Encrypted messaging apps, small-batch drop-shipping, and cryptocurrency payments have streamlined consumer access to injectable compounds. Global crypto-enabled drug, with anabolic agents occupying a meaningful share. Suppliers in China routinely adapt product codes and shipping labels, sustaining export pipelines despite customs seizures. Peer-review systems inside private fitness groups cultivate perceived vendor reliability, lowering entry barriers for first-time buyers. Collectively, these digital pathways insulate demand spikes from local supply disruptions and help stabilise the trenbolone enanthate market during enforcement sweeps.
Tightening Regulatory Oversight and Bans
Cross-border task forces are scaling up pharmaceutical crime operations, as illustrated by INTERPOL's 2025 Operation Pangea XVII that seized USD 65 million in illicit medicines and arrested 769 suspects. In parallel, the DEA's Cyber Juice raids targeted dozens of US-based digital suppliers, underscoring the growing focus on online distribution. Penalties include asset forfeitures and lengthy prison terms, pushing underground labs to absorb higher operating risks and costs. These crackdowns constrict supply, elevate end-user prices, and may deter novice consumers, tempering short-term momentum across the trenbolone enanthate market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Use in Veterinary Applications
- Ongoing R&D in Hormonal Deficiency Therapies
- Shift Toward Safer Alternatives like Selective Androgen Receptor Modulators (SARMs)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Injectable products represented 58.92% of the trenbolone enanthate market in 2025. Their superior bioavailability, eight-to-twelve-day half-life, and lower hepatotoxicity compared with oral options support solid user adherence in both cattle management and physique-enhancement cycles. The segment is forecast to compound at 6.92% through 2031, comfortably ahead of oral counterparts. Price competitiveness improves as Chinese contract manufacturers scale GMP-compliant fill-finish lines, creating cost advantages that cascade through veterinary distributors and grey-market resellers. Growing acceptance of once-per-cycle veterinary implant programs further entrenches injectables as the preferred delivery system.
Stronger enforcement against counterfeit oral tablets has also nudged consumers toward sealed-vial products with verifiable batch codes. Combined with more efficient logistics, this shift underpins steady share gains. Oral formulations, constrained by first-pass metabolism and dosage-related liver strain, face muted growth despite niche appeal among needle-averse users. Consequently, injectables will continue to anchor the trenbolone enanthate market, while modest oral sales persist largely as ancillary offerings. This dynamic keeps the injectable segment central to overall trenbolone enanthate market performance.
Complete Report Scope:
- By Drug Type
- Oral
- Injectables
- By Application
- Human Use
- Animal Use
- By End User
- Pharmaceutical Companies
- Veterinary Health Companies
- Hospitals & Clinics
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 39.82% of global revenue in 2025, underpinned by FDA-approved cattle implants and a robust bodybuilding subculture that sustains premium-priced injectable sales. Regional veterinary networks benefit from mature cold-chain infrastructure, allowing high-volume distribution directly to feedlots and veterinary pharmacies. Legal avenues for animal-use products, coupled with strict but transparent enforcement on human-use diversion, foster a predictable commercial environment.
Asia-Pacific is forecast to expand at 8.14% CAGR, the quickest among all regions. China's dominance in active ingredient synthesis underpins competitively priced exports, while India's contract-manufacturing base offers formulation flexibility ranging from multi-dose vials to extended-release pellets. Rapid urbanisation lifts disposable incomes, spurring gym membership growth and wider supplement experimentation among younger demographics. Simultaneously, expanding domestic cattle inventories to satisfy growing protein consumption drives legitimate veterinary uptake, reinforcing demand on both supply and consumption fronts.
Europe maintains a cautious stance due to ongoing bans on hormonal growth promoters in livestock. Nevertheless, underground gyms and e-commerce fulfil a consistent illicit stream, particularly in Eastern Europe where price sensitivity favours bulk powder imports repackaged locally. Regulatory bodies coordinate inspections at border crossings and postal hubs, but fragmented enforcement leaves loopholes that cross-border networks exploit. This tension results in modest overall growth, with veterinary potential constrained but human-use demand steady, keeping Europe a significant yet tightly regulated slice of the trenbolone enanthate market.
- Globalanabolic
- Dragon Pharmaceuticals
- Elite Pharmaceuticals
- Kalpa Pharmaceuticals
- SP Laboratories
- Alpha Pharma
- Labdhi Pharmaceuticals
- Euro Pharmacies
- Meditech Pharmaceuticals
- Hilma Biocare
- Pharmacom Labs
- Gen-Shi Laboratories
- British Dragon
- Landerlan
- Magnus Pharmaceuticals
- Balkan Pharmaceuticals
- Thaiger Pharma
- Swiss Remedies
- Pharmatec
- Bayer
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Interest in Bodybuilding and Fitness Lifestyles
- 4.2.2 Wider Access via Online and Informal Distribution Channels
- 4.2.3 Rising Use in Veterinary Applications
- 4.2.4 Ongoing R&D in Hormonal Deficiency Therapies
- 4.2.5 Growth of Dark-Web and Crypto-Based Supply Chains
- 4.2.6 Cost-Effective Peptide/Steroid Manufacturing in Developing Countries
- 4.3 Market Restraints
- 4.3.1 Tightening Regulatory Oversight and Bans
- 4.3.2 High Risk of Adverse Health Effects
- 4.3.3 Shift Toward Safer Alternatives like Selective Androgen Receptor Modulators (SARMs)
- 4.3.4 Increased Scrutiny on Social Media Advertising Platforms
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Drug Type
- 5.1.1 Oral
- 5.1.2 Injectables
- 5.2 By Application
- 5.2.1 Human Use
- 5.2.2 Animal Use
- 5.3 By End User
- 5.3.1 Pharmaceutical Companies
- 5.3.2 Veterinary Health Companies
- 5.3.3 Hospitals & Clinics
- 5.3.4 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Globalanabolic
- 6.3.2 Dragon Pharmaceuticals
- 6.3.3 Elite Pharmaceuticals
- 6.3.4 Kalpa Pharmaceuticals
- 6.3.5 SP Laboratories
- 6.3.6 Alpha Pharma
- 6.3.7 Labdhi Pharmaceuticals
- 6.3.8 Euro Pharmacies
- 6.3.9 Meditech Pharmaceuticals
- 6.3.10 Hilma Biocare
- 6.3.11 Pharmacom Labs
- 6.3.12 Gen-Shi Laboratories
- 6.3.13 British Dragon
- 6.3.14 Landerlan
- 6.3.15 Magnus Pharmaceuticals
- 6.3.16 Balkan Pharmaceuticals
- 6.3.17 Thaiger Pharma
- 6.3.18 Swiss Remedies
- 6.3.19 Pharmatec
- 6.3.20 Bayer
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 水處理特種化學品市場預測至2034年-按化學品類型、處理流程、水源、功能、最終用戶和地區分類的全球分析
 中東和北非特種化學品產業的成長機會:2025-2030 年
 特種化學品市場:2026-2032年全球市場預測(依產品類型、功能、原料、形態、應用及通路分類)特種化學品市場:預測(至2034年)-按產品類型、功能、形態、最終用途產業和地區分類的全球分析
 特種化學品:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 特種化學品市場規模、佔有率和趨勢分析報告:按產品、地區和細分市場分類的預測(2026-2033 年)
 特種化學品市場報告:按類型和地區分類 2026-2034 年
 2026年全球特用化學品分銷市場報告
 2026-2030年全球特用化學品市場特種化學品市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年