


 |
市場調查報告書
商品編碼
2119623
暖氣過濾器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Furnace Filters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
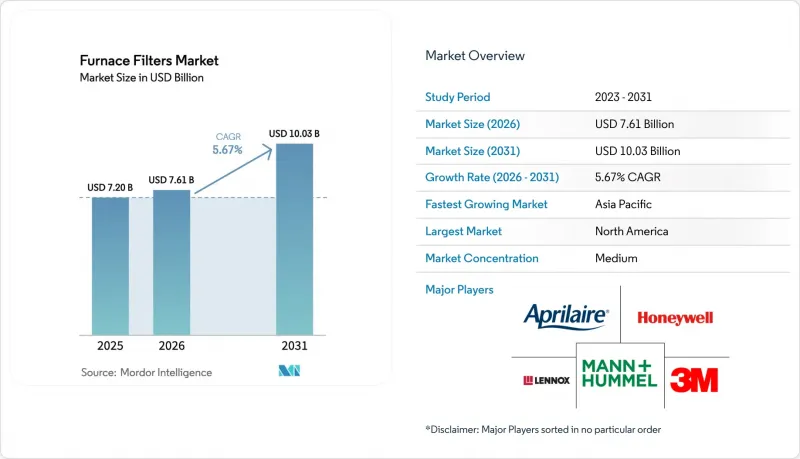
據 Mordor Intelligence 稱,2025 年供暖過濾器市值為 72 億美元,預計到 2031 年將達到 100.3 億美元,而 2026 年為 76.1 億美元,預測期內(2026-2031 年)的複合年預計成長率為 5.67%。
本報告按暖氣設備類型(燃氣、燃油等)、MERV等級(MERV 1-4、MERV 5-8等)、最終用戶(住宅、商業等)、分銷管道(離線零售、線上直銷等)、過濾介質(玻璃纖維、褶皺合成纖維等)和地區(美國、加拿大等)進行細分。市場規模和預測均以美元計價。
全球暖氣濾網市場趨勢及洞察
室內空氣品質(IAQ)正日益受到關注。
美國暖氣、冷氣與空調工程師協會 (ASHRAE) 241 標準正式定義了病原體控制標準,強制要求商業建築安裝 MERV 13 或更高等級的過濾器,以去除近 90% 的亞微米顆粒。美國的醫療機構已經遵循美國職業安全與健康管理局 (OSHA) 的指南,要求使用 MERV 13 或更高等級的過濾器。如今,這項要求也影響著住宅,他們越來越將過濾與呼吸健康聯繫起來。美國西部地區的野火進一步凸顯了傳統 MERV 8 產品的局限性,引發了一波快速升級的浪潮。印度和中國的製藥業也推動了對符合無塵室標準的高效過濾介質的需求。隨著人們對室內空氣品質 (IAQ) 的認知不斷提高,建築物業主越來越將優質過濾器視為風險緩解工具,而不僅僅是可選項。
節能型暖通空調系統維修激增
聯邦和州政府的脫碳獎勵鼓勵業主用變冷劑流量(VRF)系統或熱泵系統取代老舊的組合式空調機組。這些維修要求使用4吋厚的濾材過濾器,以在不造成過大壓力損失的情況下維持MERV 13的性能。麻州的法規規定通風系統的焓回收率必須達到70%,間接增加了對低阻力過濾器的需求,從而提高了能源效率。隨著老舊建築達到新的能源標準,承包商正在將優質過濾器納入可享受補貼的升級套件中,這為過濾器供應商提供了多年持續的收入來源。
高昂的生命週期維修成本
MERV 13 級過濾器的價格大約是玻璃纖維過濾器的 3 到 4 倍,而且更容易堵塞,導致普通家庭每年的更換成本超過 200 美元。在擁有數十台空氣處理機的商業高層建築中,過濾器採購和人事費用每年可能高達數千美元。能源消耗的增加(風扇在相同風量下消耗的功率會增加 15% 到 20%)進一步推高了營運預算。雖然訂閱平台可以平衡每月費用,但總成本通常高於零售通路,這限制了新興市場的升級率,因為在這些市場,資本保值比室內空氣品質 (IAQ) 更為重要。
細分市場分析
到2025年,瓦斯暖氣過濾器將佔暖氣過濾器市場45.38%的佔有率,反映出其在北美住宅中的廣泛應用。相較之下,與熱泵和混合系統相關的加熱過濾器市場預計將以8.05%的複合年成長率成長,反映出電氣化舉措正在縮小營業成本差距。燃油加熱設備僅在管道天然氣無法覆蓋的地區才能繼續存在,而電阻式加熱設備將佔據非常有限的細分市場。
為了確保熱泵全年運作,需要使用更高密度的濾材,例如 MERV 13 級,以防止氣流下降,但這會增加每次安裝的成本。燃氣熱泵通常使用標準的 1 英吋折疊式濾網,但隨著法規的日益標準化,效率要求預計將逐步提高。隨著美國環保署 (EPA) 逐步淘汰 R-410A 冷媒,安裝人員更加重視系統清潔度,這導致對能夠在安裝過程中捕獲灰塵並保護壓縮機的優質過濾器的需求增加。
到2025年,MERV 5-8級過濾器將佔據37.92%的市場佔有率,並在低風險的住宅環境中繼續普及。同時,MERV 13-16級和HEPA產品的暖氣過濾器市場預計將以9.42%的複合年成長率成長至2031年。由於疫情期間人們對煙霧污染和健康的認知不斷提高,更高評級的過濾器正成為新建建築的實際標準。
在易發野火的地區,人們正在使用專為在高粒狀物濃度下仍能保持高效過濾效果而設計的專用濾材。醫療和潔淨製造業的客戶已將採購標準設定為 MERV 13,目前正逐步推廣至零售產品。中價位的 MERV 9-12 產品迎合了注重成本、希望逐步升級的用戶,但更嚴格的法規可能會縮小這項過渡性產品的市場規模。
區域分析
預計到2025年,北美將佔全球銷售額的36.72%,這主要得益於嚴格的能源法規,這些法規強制要求新建建築和大規模維修使用MERV 13級過濾器。加州、奧勒岡州和不列顛哥倫比亞省的野火縮短了過濾器的更換週期,從而促進了銷售。該地區在訂閱服務方面也處於領先地位,FilterBuy等品牌主導了自動化配送服務。
亞太地區是成長最快的地區,預計到2031年複合年成長率將達到7.74%。印度的暖通空調市場預計到2030年將達到300億美元,這將帶動下游市場對符合生產連結獎勵計畫(PLI)計畫的過濾器供應商產生巨大需求。中國佔全球熱泵銷量的四分之一以上,其製定的過濾器標準正在全球推廣。在日本和韓國,人口密集都市區的高層建築實施了嚴格的室內空氣品質(IAQ)標準,MERV 13級或更高等級的過濾器應用已十分普遍。
在歐洲,受「綠色新政」能源指令和不斷提高的碳關稅的推動,市場呈現穩定成長態勢。瑞典強制推行鋼骨建築,體現了歐盟範圍內對可回收材料的廣泛推廣;德國則正在推動一項針對熱泵維修的補貼計畫。隨著沙烏地阿拉伯「2030願景」為需要先進暖通空調系統的大規模建設項目提供資金,中東和非洲市場也開始吸引供應商的目光。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 人們對室內空氣品質(IAQ)的關注度日益提高
- 節能型暖通空調系統維修工程激增。
- 建築規範中對室內空氣品質 (IAQ) 和 MERV 等級提出了更嚴格的要求
- 換用需要更高性能過濾器的熱泵。
- 野火產生的煙霧增加了更換頻率。
- 訂閱式電子商務篩選服務正在推動銷售量。
- 市場限制因素
- 整個生命週期內維護成本高昂
- 原物料價格波動(合成介質)
- 小型分離式(無濾網空調)的普及
- 一次性過濾器的永續性計劃
- 價值供應鏈分析
- 技術展望
- 監理情勢
- 波特五力分析
- 相關人員分析
- 分銷通路分析
- 消費者偏好分析
第5章 市場規模與成長預測
- 按下加熱設備類型
- 氣體
- 油
- 電阻型
- 熱泵/混合動力
- 按MERV等級
- MERV 1~4
- MERV 5~8
- MERV 9~12
- MERV 13–16 和 HEPA
- 最終用戶
- 住宅
- 商業
- 產業
- 透過分銷管道
- 實體零售店(DIY商店、暖通空調批發商)
- 線上直銷
- 訂閱服務
- 透過觀看媒介
- 玻璃纖維
- 褶皺合成纖維
- 靜電
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- UAE
- 土耳其
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Honeywell International Inc.
- 3M Company(Filtrete)
- Nordic Pure LLC
- Rheem Manufacturing Company
- FilterBuy Inc.
- Lennox International Inc.
- AprilAire LLC
- MANN+HUMMEL GmbH
- AAF International(Daikin)
- Camfil AB
- Parker-Hannifin Corp.
- Freudenberg Filtration Technologies SE
- Donaldson Company Inc.
- Koch Filter Corporation
- General Filters Inc.
- KOOL-IT Filtration
- Glasfloss Industries
- PureFilters Canada Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the furnace filters market size was valued at USD 7.2 billion in 2025 and estimated to grow from USD 7.61 billion in 2026 to reach USD 10.03 billion by 2031, at a CAGR of 5.67% during the forecast period (2026-2031).
This report is Segmented by Furnace Type (Gas, Oil and More), MERV Rating (MERV 1-4, MERV 5-8 and More), End User (Residential, Commercial and More), Distribution Channel (Offline Retail, Online Direct-To-Consumer and More), Filter Media (Fiberglass, Pleated Synthetic and More), and Geography (United States, Canada and More). Market Size and Forecasts are Provided in USD.
Global Furnace Filters Market Trends and Insights
Growing Focus on Indoor Air Quality (IAQ)
ASHRAE Standard 241 formalized pathogen-control benchmarks that compel commercial buildings to install MERV 13-plus filters capable of removing nearly 90% of sub-micron particles. U.S. healthcare facilities already follow OSHA guidance that specifies MERV 13 or higher, a requirement now influencing residential buyers who increasingly link filtration to respiratory health. Wild-fire smoke episodes across the western United States further demonstrate the limitations of legacy MERV 8 products, prompting rapid upgrade cycles. Pharmaceutical production in India and China also fuels demand for high-efficiency media that meet clean-room thresholds. As IAQ awareness rises, building owners view premium filters less as discretionary purchases and more as risk-mitigation tools.
Surge in Energy-Efficient HVAC Retrofits
Federal and state decarbonization incentives encourage property owners to swap dated packaged units for variable-refrigerant-flow and heat-pump systems. These retrofits specify deeper 4-inch media filters that retain MERV 13 performance without excessive pressure drop. Massachusetts regulations now require a 70% enthalpy-recovery ratio in ventilation systems, indirectly lifting demand for low-resistance filters that protect energy gains. As older buildings align with new energy codes, contractors bundle premium filters into rebate-eligible upgrade kits, generating multi-year pull-through revenue for filter suppliers.
High Life-Cycle Maintenance Cost
MERV 13 filters cost roughly three to four times more than fiberglass options and load faster, raising annual replacement outlays for households to beyond USD 200. In commercial towers with dozens of air handlers, filter procurement and labor fees reach thousands per year. Elevated energy draw-15-20% higher fan power at comparable airflow-further inflates operating budgets. While subscription platforms smooth monthly payments, total cost often rises versus retail channels, limiting upgrade rates in emerging economies where capital preservation outweighs IAQ priorities.
Other drivers and restraints analyzed in the detailed report include:
- Stricter IAQ and MERV Mandates in Building Codes
- Heat-Pump Conversions Requiring Higher-Grade Filters
- Raw-Material Price Volatility (Synthetic Media)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gas furnaces accounted for 45.38% of the furnace filters market in 2025, underpinned by a vast installed base across North American homes. In contrast, the furnace filters market size linked to heat pump or hybrid systems is projected to grow at an 8.05% CAGR, reflecting electrification incentives that narrow operating-cost gaps. Oil furnaces persist only in geographies lacking pipeline gas, while electric resistance units occupy small niches.
Year-round heat pump operation mandates deeper MERV 13 media to avoid airflow penalties, raising unit revenue per install. Gas models retain standard 1-inch pleated filters, but regulatory convergence will gradually lift their efficiency requirements. As the EPA phases out R-410A, contractors stress system cleanliness, reinforcing demand for premium filters that capture installation debris and safeguard compressors.
With a 37.92% share in 2025, MERV 5-8 filters remain common in low-risk residential settings; however, the furnace filters market size for MERV 13-16 and HEPA products is advancing at a 9.42% CAGR through 2031. Smoke events and pandemic-era health messaging make higher ratings the de facto choice for new builds.
Wild-fire prone regions adopt specialty media engineered to maintain efficiency despite extreme particle loading. Healthcare and clean-manufacturing customers set procurement baselines at MERV 13, a threshold now filtering into retail offerings. Mid-range MERV 9-12 options serve cost-conscious users upgrading in steps, though policy tightening could compress this transitional category.
Complete Report Scope:
- By Furnace Type
- Gas
- Oil
- Electric Resistance
- Heat-Pump / Hybrid
- By MERV Rating
- MERV 1-4
- MERV 5-8
- MERV 9-12
- MERV 13-16 and HEPA
- By End User
- Residential
- Commercial
- Industrial
- By Distribution Channel
- Offline Retail (DIY Stores, HVAC Wholesalers)
- Online Direct-to-Consumer
- Subscription Services
- By Filter Media
- Fiberglass
- Pleated Synthetic
- Electrostatic
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 36.72% of global revenue in 2025, buoyed by stringent energy codes that require MERV 13 filters in new construction and major retrofits. Wild-fire smoke across California, Oregon, and British Columbia shortens replacement cycles and lifts unit volumes. The region also leads subscription adoption, as brands like FilterBuy dominate automated delivery programs.
Asia-Pacific is the fastest-growing territory with a 7.74% CAGR through 2031. India's HVAC market is trending toward USD 30 billion by 2030, creating substantial downstream pull for filter suppliers aligned with the Production Linked Incentive scheme. China's control of more than one-quarter of global heat-pump sales sets filtration standards that ripple worldwide. Japan and South Korea impose strict IAQ limits in dense urban high-rises, cementing MERV 13-plus adoption.
Europe posts steady gains on the back of Green Deal energy directives and escalating carbon tariffs. Sweden's steel-frame mandate signals the bloc's wider push for recyclable materials, while Germany advances subsidy programs for heat-pump retrofits. The Middle East and Africa begin to surface on supplier radars as Saudi Arabia's Vision 2030 funds large-scale building projects requiring advanced HVAC systems.
- Honeywell International Inc.
- 3M Company (Filtrete)
- Nordic Pure LLC
- Rheem Manufacturing Company
- FilterBuy Inc.
- Lennox International Inc.
- AprilAire LLC
- MANN+HUMMEL GmbH
- AAF International (Daikin)
- Camfil AB
- Parker-Hannifin Corp.
- Freudenberg Filtration Technologies SE
- Donaldson Company Inc.
- Koch Filter Corporation
- General Filters Inc.
- KOOL-IT Filtration
- Glasfloss Industries
- PureFilters Canada Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing focus on indoor air quality (IAQ)
- 4.2.2 Surge in energy-efficient HVAC retrofits
- 4.2.3 Stricter IAQ and MERV mandates in building codes
- 4.2.4 Heat-pump conversions requiring higher-grade filters (under-the-radar)
- 4.2.5 Wild-fire smoke events boosting replacement frequency (under-the-radar)
- 4.2.6 Subscription e-commerce filter services driving volume (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 High life-cycle maintenance cost
- 4.3.2 Raw-material price volatility (synthetic media)
- 4.3.3 Mini-split adoption (filterless HVAC) (under-the-radar)
- 4.3.4 Sustainability push against disposable filters (under-the-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Stakeholder Analysis
- 4.9 Distribution Channel Analysis
- 4.10 Consumer Preference Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Furnace Type
- 5.1.1 Gas
- 5.1.2 Oil
- 5.1.3 Electric Resistance
- 5.1.4 Heat-Pump / Hybrid
- 5.2 By MERV Rating
- 5.2.1 MERV 1-4
- 5.2.2 MERV 5-8
- 5.2.3 MERV 9-12
- 5.2.4 MERV 13-16 and HEPA
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.4 By Distribution Channel
- 5.4.1 Offline Retail (DIY Stores, HVAC Wholesalers)
- 5.4.2 Online Direct-to-Consumer
- 5.4.3 Subscription Services
- 5.5 By Filter Media
- 5.5.1 Fiberglass
- 5.5.2 Pleated Synthetic
- 5.5.3 Electrostatic
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 UAE
- 5.6.5.1.3 Turkey
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Honeywell International Inc.
- 6.4.2 3M Company (Filtrete)
- 6.4.3 Nordic Pure LLC
- 6.4.4 Rheem Manufacturing Company
- 6.4.5 FilterBuy Inc.
- 6.4.6 Lennox International Inc.
- 6.4.7 AprilAire LLC
- 6.4.8 MANN+HUMMEL GmbH
- 6.4.9 AAF International (Daikin)
- 6.4.10 Camfil AB
- 6.4.11 Parker-Hannifin Corp.
- 6.4.12 Freudenberg Filtration Technologies SE
- 6.4.13 Donaldson Company Inc.
- 6.4.14 Koch Filter Corporation
- 6.4.15 General Filters Inc.
- 6.4.16 KOOL-IT Filtration
- 6.4.17 Glasfloss Industries
- 6.4.18 PureFilters Canada Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 熱風隧道市場規模、佔有率和成長分析:按產品類型、應用、溫度範圍、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 2026年全球滲碳爐市場報告
 陶瓷滾筒爐灶用捲筒:全球市場佔有率和排名、總收入和需求預測(2026-2032 年)
 隧道窯市場規模、佔有率和成長分析:按燃料類型、應用、溫度範圍、處理能力、最終用戶和地區分類-2026-2033年產業預測2026年全球電陶瓷爐市場報告
 熱水液化市場預測至2034年:按產品、原料、技術、最終用戶和地區分類的全球分析
 脫脂爐市場:按類型、熱源、自動化和產業分類-2026-2032年全球預測高爐市場:依鋼材類型、技術、終端用戶產業、爐型及應用分類-2026-2032年全球市場預測
 爐用過濾器市場規模、佔有率和趨勢分析報告:按過濾器類型、分銷管道、應用、地區和細分市場預測(2026-2033 年)隧道式熱風循環器市場:按類型、通路、應用、最終用戶分類,全球預測(2026-2032)