


 |
市場調查報告書
商品編碼
2119555
海底電纜商業實質審查服務:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Subsea Cable Commercial Due Diligence Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
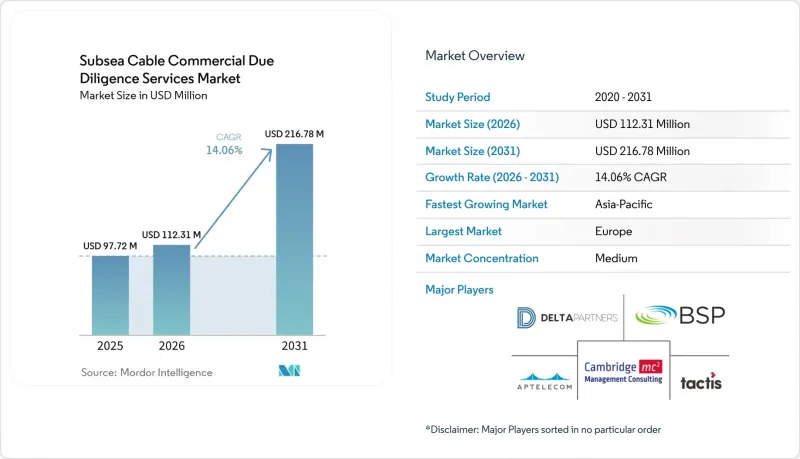
據 Mordor Intelligence 稱,2025 年海底電纜商業實質審查服務的市場規模為 9,772 萬美元,預計到 2031 年將從 2026 年的 1.1231 億美元成長至 2.1678 億美元,預測期(2026-2031 年)的複合年成長率為 14.06%。
本報告按服務類型(商業實質審查、技術實質審查、環境和社會實質審查等)、合約模式(買方實質審查、賣方供應商實質審查等)、客戶類型(離岸風能和能源開發商、電信營運商等)以及地區進行分類。市場預測以美元計價。
全球海底電纜商業實質審查服務市場的趨勢與洞察。
超大規模資料中心業者主導的海底電纜投資正在推動諮詢需求。
私有系統不遵循傳統上支撐商業性估值的聯盟管治和成本分攤機制。因此,買方和貸款方需要分析每項資產的所有權結構、容量利用率、營運成本和收入預測。由於缺乏通用的聯盟文件,私有資產的比較可能較為困難。實質審查必須仔細檢視專用容量的商業性影響以及界定進入許可權的合約條款。由於私有系統需要個人化的估值方法,這項要求正在擴大海底電纜商業實質審查服務市場的範圍。這也提升了能夠將技術證據與財務假設結合的團隊的價值。
併購和基礎設施基金活動的活性化導致交易實質審查案件數量增加。
2026年4月,Cerberus Capital Management完成了由CVC 二次性 Partners主導的規模達23億美元的Subcom單一資產持續投資基金的設立。此交易涉及美國唯一一家提供海底電纜設計、製造、鋪設和維護等全方位服務的綜合供應商。吉寶基礎設施基金也主導收購了Global Marine Group,這是該基金首次投資海底電纜專業公司。這些交易表明,電纜業者正日益被視為核心基礎設施資產,而不僅僅是投資組合的補充。交易團隊必須在投資獲得批准前進行商業性、技術、財務和監管方面的審查。這些發展正在擴大海底電纜商業實質審查服務市場的交易機會。
獨立海底電纜專家的短缺限制了市場訂單的能力。
具備海底電纜工程、商業性估值和財務建模綜合經驗的獨立專業人士數量仍然有限。海底電纜盡職調查需要了解分波多工(WDM) 升級、中繼器故障、登陸權、不可撤銷的使用權協議以及特定線路的海洋環境等知識。這些知識通常透過實務經驗獲得,而非公開可得。如果專家團隊無法準時完成交易,一些交易可能會被推遲甚至取消。高需求的顧問可能會收取更高的費用,而小規模的交易可能無法獲得所需的詳細支援。儘管需求不斷成長,但這些供應限制限制了海底電纜商業實質審查服務市場的容量。
細分市場分析
2025年,技術實質審查佔服務型收入的30.46%。金融機構和股權投資者要求獨立的第三方驗證設備規格、電纜埋設深度、中繼器狀態和操作規程是否符合產業計畫。這項服務在投資前檢驗系統的物理狀況和設計標準。海底電纜商業實質審查服務市場規模龐大,這主要得益於對計畫升級、維護安排和預期容量利用率的檢驗需求。這通常構成更廣泛的商業性和資金籌措的基礎。
監管和授權實質審查預計將成為成長最快的服務類別,到2031年複合年成長率將達到15.64%。這項服務包括在交易完成前審查許可證的有效性、安全批准、環境要求和國家安全要求。 2026年7月,美國聯邦通訊委員會(FCC)通過了第二份報告和命令,為海底電纜終端設備的特定所有者和營運商建立了一套全面的許可框架。商業、財務和模型檢驗服務則著重於市場定位、容量定價、市場競爭、預測假設和收入確認假設。這種多元化的服務組合為海底電纜商業實質審查服務市場提供了支持,滿足了客戶對跨職能證據完整性的需求。
區域分析
2025年,歐洲將佔據海底電纜商業實質審查服務市場34.78%的佔有率。該地區的特點是海底基礎設施交易活躍,且對安全性、韌性和資金籌措有嚴格的要求。歐盟委員會2026年的撥款將用於支持戰略性海底電纜計畫、修復能力以及「符合歐洲利益的指定電纜計畫」。這些項目將要求專案發起人證明其符合技術、環境和監管要求。英國針對海上電力營運商的框架也為受監管的互聯投資帶來了審查工作。
預計到2031年,亞太地區海底電纜商業實質審查服務市場將以15.94%的複合年成長率成長,在所有地區中成長最高。該地區正積極開發印度-新加坡、日本-東南亞以及更廣泛的亞太線路。 2026年1月,日本政府支持的日本國際通訊工程基金(JICT Fund)批准為I-AM海底電纜計畫提供高達7,300萬美元的融資。該項目總投資1500億美元(10億美元),旨在連接日本、馬來西亞和新加坡。印度、新加坡、日本、中國和澳洲是諮詢服務需求的主要樞紐,沿線投資將帶動印度和新加坡的相關活動。
北美仍然是最大的單一國家諮詢市場,總部位於美國的超大規模資料中心業者正在部署全球海底光纜專案組合。美國聯邦通訊委員會 (FCC) 的許可規則增加了對監管和安全合規性審計的需求。隨著海底光纜計畫將區域市場與美國連結起來,南美洲正崛起成為企劃案融資服務的新興市場。由於主權國家對連接亞洲、歐洲和非洲的連接資產和線路進行投資,中東地區的業務活動日益活躍。非洲作為諮詢市場仍處於起步階段,但 Seacom 於 2025 年推出的「Seacom 2.0」舉措已催生了一系列跨司法管轄區的交易。這些地區正在擴大海底光纜商業實質審查服務市場的潛在基本客群。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟因素對市場的影響
- 市場促進因素
- 超大規模資料中心業者主導的海底電纜投資
- 數位基礎設施領域的併購活動和基礎設施基金活動正變得越來越活躍。
- 對路由多樣化和網路容錯能力的需求日益成長。
- 擴大離岸風力發電和海底輸電電纜項目
- 越來越需要檢驗有線電視系統收入和容量的假設的有效性。
- 地緣政治風險和海底電纜線路日益成長的重要性,正在推動董事會層面進行實質審查的需求。
- 市場限制因素
- 獨立海底電纜專家數量有限。
- 電纜容量、定價以及有關故障資料的保密限制。
- 資產層面的所有權分散和資料標準不一致
- 由於海事檢查、授權檢查和安保檢查,交易週期延長。
- 產業生態系分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按服務類型
- 商業實質審查
- 科技實質審查
- 財務和模型檢驗的實質審查
- 監管和授權盡職實質審查
- 環境與社會實質審查
- 對保險、風險和擔保進行實質審查
- 按參與模式
- 買方實質審查
- 賣方實質審查
- 對貸款人和資金籌措進行實質審查
- 由獨立業主工程師提供的諮詢服務
- 關於交易後價值創造的諮詢
- 依客戶類型
- 基礎建設基金和私募股權公司
- 商業銀行和投資銀行
- 電信營運商
- 超大規模資料中心業者和內容提供者
- 電纜系統製造商
- 海上風能和能源開發公司
- 政府機構和主權基金
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 智利
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 挪威
- 法國
- 德國
- 西班牙
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 新加坡
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 阿曼
- 土耳其
- 其他中東國家
- 非洲
- 埃及
- 南非
- 肯亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- David Ross Group Inc.
- AP Telecom LLC
- Cambridge Management Consulting Limited
- Tactis Strategy and Technology SAS
- Broadband Success Partners LLC
- Delta Partners FZ-LLC
- Hardiman Telecommunications Ltd
- Analysys Mason Limited
- McKinsey & Company, Inc.
- The Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Roland Berger Holding GmbH
- OWC Limited
- TGS Marine Consulting LLC
- Ramboll Group A/S
- DNV AS
- Mott MacDonald Group Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the subsea cable commercial due diligence services market size was valued at USD 97.72 million in 2025 and is estimated to grow from USD 112.31 million in 2026 to reach USD 216.78 million by 2031, at a CAGR of 14.06% during the forecast period (2026-2031).
This report is Segmented by Service Type (Commercial Due Diligence, Technical Due Diligence, Environmental and Social Due Diligence, and More), Engagement Model (Buy-Side Due Diligence, Sell-Side Vendor Due Diligence, and More), Client Type (Offshore Wind and Energy Developers, Telecom Operators, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Subsea Cable Commercial Due Diligence Services Market Trends and Insights
Hyperscaler-Led Subsea Cable Investment Drives Advisory Demand
Private systems do not follow the consortium governance and cost-sharing structures that have traditionally supported commercial assessments. Buyers and lenders, therefore, need work that considers ownership structure, capacity use, operating costs, and revenue assumptions for each asset. The lack of common consortium documents can make it harder to compare one private asset with another. Reviews must examine the commercial implications of dedicated capacity and the contractual terms that govern access. This requirement broadens the scope of work in the subsea cable commercial due diligence services market, as private systems require tailored valuation methods. It also increases the value of teams that can link engineering evidence with financial assumptions.
Growing M&A and Infrastructure Fund Activity Expands Transaction Due Diligence Pipeline
Cerberus Capital Management closed a USD 2.3 billion single-asset continuation vehicle for SubCom in April 2026, with CVC Secondary Partners leading the transaction. The transaction involved the only integrated US provider spanning subsea cable engineering, manufacturing, installation, and maintenance. Keppel's infrastructure fund also led the acquisition of Global Marine Group, making its first investment in a subsea cable specialist. These transactions show that cable operators are being treated as core infrastructure holdings rather than occasional portfolio additions. Deal teams need commercial, technical, financial, and regulatory reviews before investment approvals. This activity broadens the assignment pipeline for the subsea cable commercial due diligence services market.
Scarcity of Independent Subsea Cable Specialists Constrains Market Capacity
The number of independent professionals who combine cable engineering, commercial valuation, and financial modeling experience remains limited. Cable reviews require familiarity with wavelength-division multiplexing upgrades, repeater faults, landing rights, indefeasible-right-of-use contracts, and route-specific marine conditions. This knowledge is usually developed through operational involvement rather than public information. Some mandates are delayed or declined when specialist teams cannot meet transaction schedules. High-demand advisors can command higher fees, while smaller transactions may receive less detailed support. The supply constraint limits the capacity of the subsea cable commercial due diligence services market even as demand expands.
Other drivers and restraints analyzed in the detailed report include:
- Rising Route Diversity and Network Resilience Requirements Elevate Diligence Scope
- Offshore Wind and Subsea Power Interconnectors Create a New Diligence Category
- Confidentiality Norms on Cable Capacity and Pricing Limit Diligence Rigor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Technical Due Diligence captured 30.46% of service-type revenue in 2025. Lenders and equity investors require independent confirmation that equipment specifications, cable burial depth, repeater conditions, and operating procedures support the business plan. The service tests a system's physical condition and design basis before capital is committed. The subsea cable commercial due diligence services market size for this service is supported by the need to validate planned upgrades, maintenance arrangements, and expected capacity use. It commonly forms the foundation for wider commercial and financing reviews.
Regulatory and Permitting Due Diligence is projected to be the fastest-growing service type, with a 15.64% CAGR through 2031. This service reviews license standing, security approvals, environmental conditions, and national security requirements before a transaction closes. The Federal Communications Commission adopted a second report and order in July 2026 that established a blanket licensing framework for certain owners and operators of submarine line terminal equipment. Commercial, financial, and model-validation work addresses market positioning, capacity pricing, competition, forecasts, and revenue recognition assumptions. This diversified service mix supports the subsea cable commercial due diligence services market as clients require coordinated evidence across functions.
Complete Report Scope:
- By Service Type
- Commercial Due Diligence
- Technical Due Diligence
- Financial and Model Validation Due Diligence
- Regulatory and Permitting Due Diligence
- Environmental and Social Due Diligence
- Insurance, Risk and Warranty Due Diligence
- By Engagement Model
- Buy-Side Due Diligence
- Sell-Side Vendor Due Diligence
- Lender and Financing Due Diligence
- Independent Owner's Engineer Advisory
- Post-Deal Value Creation Advisory
- By Client Type
- Infrastructure Funds and Private Equity Firms
- Commercial and Investment Banks
- Telecom Operators
- Hyperscalers and Content Providers
- Cable-System Manufacturers
- Offshore Wind and Energy Developers
- Government Agencies and Sovereign Funds
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Norway
- France
- Germany
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Oman
- Turkey
- Rest of Middle East
- Africa
- Egypt
- South Africa
- Kenya
- Rest of Africa
- North America
Geography Analysis
Europe held 34.78% of the subsea cable commercial due diligence services market share in 2025. The region combines active subsea infrastructure transactions with detailed requirements for security, resilience, and funding. The European Commission's 2026 allocation supports strategic submarine cable projects, repair capacity, and designated Cable Projects of European Interest. These programs require project sponsors to demonstrate technical, environmental, and regulatory compliance. The United Kingdom's offshore transmission owner framework also creates work for reviews of regulated interconnector investments.
Asia-Pacific is projected to grow at a 15.94% CAGR through 2031, the highest regional rate in the subsea cable commercial due diligence services market. The region has active development across India-Singapore, Japan-Southeast Asia, and wider Asia-Pacific routes. Japan's government-backed JICT fund approved financing of up to USD 73 million in January 2026 for the I-AM Cable project. The JPY 150 billion (USD 1.0 billion) initiative is designed to connect Japan, Malaysia, and Singapore. India, Singapore, Japan, China, and Australia are important locations for advisory demand, with corridor investments supporting activity in India and Singapore.
North America remains a large single-country advisory location because US-based hyperscalers deploy global cable portfolios. Federal Communications Commission licensing rules increase the need to review regulatory and security compliance. South America is an emerging location for project finance work, as cable projects link regional markets with the United States. The Middle East has growing activity from sovereign investment in connectivity assets and routes linking Asia, Europe, and Africa. Africa remains an early-stage advisory market, but Seacom's 2025 launch of its Seacom 2.0 initiative created a prospective multi-jurisdiction assignment pipeline. These regions broaden the addressable base of the subsea cable commercial due diligence services market.
- David Ross Group Inc.
- AP Telecom LLC
- Cambridge Management Consulting Limited
- Tactis Strategy and Technology SAS
- Broadband Success Partners LLC
- Delta Partners FZ-LLC
- Hardiman Telecommunications Ltd
- Analysys Mason Limited
- McKinsey & Company, Inc.
- The Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Roland Berger Holding GmbH
- OWC Limited
- TGS Marine Consulting LLC
- Ramboll Group A/S
- DNV AS
- Mott MacDonald Group Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Hyperscaler-Led Subsea Cable Investment
- 4.3.2 Growing M&A and Infrastructure Fund Activity in Digital Infrastructure
- 4.3.3 Rising Route Diversity and Network Resilience Requirements
- 4.3.4 Expansion of Offshore Wind and Subsea Power Interconnector Projects
- 4.3.5 Increasing Need to Validate Cable-System Revenue and Capacity Assumptions
- 4.3.6 Geopolitical Exposure and Cable-Route Criticality Increasing Board-Level Diligence Demand
- 4.4 Market Restraints
- 4.4.1 Limited Availability of Independent Subsea Cable Specialists
- 4.4.2 Confidentiality Constraints on Cable Capacity, Pricing and Fault Data
- 4.4.3 Fragmented Ownership and Inconsistent Asset-Level Data Standards
- 4.4.4 Long Transaction Cycles Caused by Marine, Permitting and Security Reviews
- 4.5 Industry Ecosystem Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Commercial Due Diligence
- 5.1.2 Technical Due Diligence
- 5.1.3 Financial and Model Validation Due Diligence
- 5.1.4 Regulatory and Permitting Due Diligence
- 5.1.5 Environmental and Social Due Diligence
- 5.1.6 Insurance, Risk and Warranty Due Diligence
- 5.2 By Engagement Model
- 5.2.1 Buy-Side Due Diligence
- 5.2.2 Sell-Side Vendor Due Diligence
- 5.2.3 Lender and Financing Due Diligence
- 5.2.4 Independent Owner's Engineer Advisory
- 5.2.5 Post-Deal Value Creation Advisory
- 5.3 By Client Type
- 5.3.1 Infrastructure Funds and Private Equity Firms
- 5.3.2 Commercial and Investment Banks
- 5.3.3 Telecom Operators
- 5.3.4 Hyperscalers and Content Providers
- 5.3.5 Cable-System Manufacturers
- 5.3.6 Offshore Wind and Energy Developers
- 5.3.7 Government Agencies and Sovereign Funds
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Chile
- 5.4.2.3 Argentina
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Norway
- 5.4.3.3 France
- 5.4.3.4 Germany
- 5.4.3.5 Spain
- 5.4.3.6 Italy
- 5.4.3.7 Russia
- 5.4.3.8 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 Singapore
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Oman
- 5.4.5.4 Turkey
- 5.4.5.5 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 Egypt
- 5.4.6.2 South Africa
- 5.4.6.3 Kenya
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 David Ross Group Inc.
- 6.4.2 AP Telecom LLC
- 6.4.3 Cambridge Management Consulting Limited
- 6.4.4 Tactis Strategy and Technology SAS
- 6.4.5 Broadband Success Partners LLC
- 6.4.6 Delta Partners FZ-LLC
- 6.4.7 Hardiman Telecommunications Ltd
- 6.4.8 Analysys Mason Limited
- 6.4.9 McKinsey & Company, Inc.
- 6.4.10 The Boston Consulting Group, Inc.
- 6.4.11 Bain & Company, Inc.
- 6.4.12 Roland Berger Holding GmbH
- 6.4.13 OWC Limited
- 6.4.14 TGS Marine Consulting LLC
- 6.4.15 Ramboll Group A/S
- 6.4.16 DNV AS
- 6.4.17 Mott MacDonald Group Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
