


 |
市場調查報告書
商品編碼
2119333
電力變壓器冷卻系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Power Transformer Cooling Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
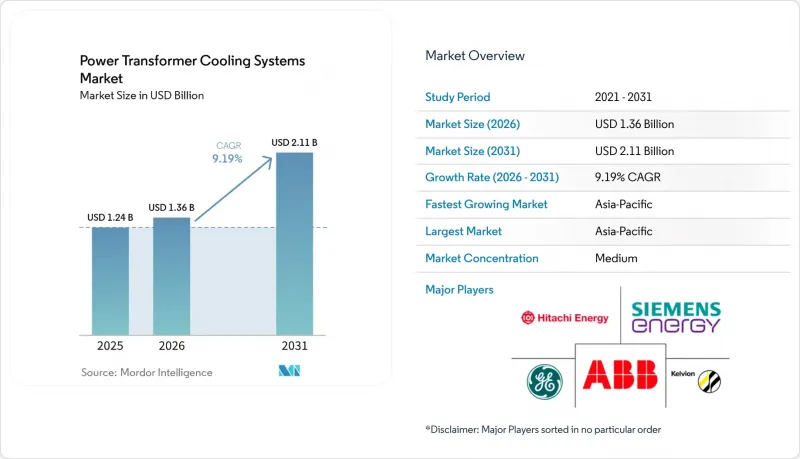
根據 Mordor Intelligence 預測,電力變壓器冷卻系統市場規模將從 2025 年的 12.4 億美元和 2026 年的 13.6 億美元成長到 2031 年的 21.1 億美元,2026 年至 2031 年的複合年成長率為 9.19%。
本報告按冷卻方式(ONAN、ONAF、OFAF、OFWF 等)、冷卻設備(散熱器和冷卻板等)、最終用戶(公共產業、獨立發電企業、工業和採礦業等)以及地區(北美、歐洲、亞太地區、南美以及中東和非洲)進行細分。市場預測以美元計價。
全球電力變壓器冷卻系統市場趨勢及洞察
電網現代化改造和老舊變壓器更換
儘管電網營運商面臨日益成長的需求,但在緊迫的專案工期內獲得大規模的新型變壓器仍然是一項挑戰。第一能源公司宣布了一項2026-2030年360億美元的資本計劃,其中超過190億美元將用於輸電基礎設施建設。截至2025年中期,大型電力變壓器的平均交貨週期為128週,而發電機增壓裝置的交付週期為144週。鑑於這些交付前置作業時間,ONAF到OFAF的轉換套件、替換散熱器組和升級後的控制面板為已在電網上運作的設備提供了切實可行的容量提升解決方案。傳統冷卻系統的數位化圖面和相容的改造設計減少了匹配舊設備介面所需的設計工作量。此外,模組化冷卻系統升級允許電力公司在訂購替換設備的同時提高相關變壓器的額定容量。
可再生能源併網及增加熱力循環
在風能和太陽能發電中,隨著輸出功率的快速增加,變壓器油表面溫度和繞組熱點溫度會重複變化。這種運作模式比傳統發電模式更容易導致累積熱疲勞。併網逆變器產生的諧波電流會增加雜散損耗和渦流損耗,可能會產生局部熱點,而基於穩態運作條件的模型無法預測這些熱點。當發電機升壓變壓器需要採用OFAF冷卻而非ONAF配置時,電力變壓器冷卻系統市場將從中受益。針對可再生能源發電模式、安裝位置和運作時間的研究表明,這些因素與變壓器故障率存在相關性,尤其是在東西向太陽能發電設施所在的地區。這種需求也推動了監測系統的應用,這些系統能夠根據觀測到的溫度狀況啟動冷卻裝置。
冷軋取向矽鋼、銅、鋁及零件的前置作業時間有差異。
原物料價格波動會降低冷卻系統的利潤率,並增加終端用戶的專案成本。根據現有研究,銅和鋁合計佔電力變壓器製造成本的60%以上。此外,據報道,2020年至2025年間,冷軋取向矽鋼(CRGO)的價格從每噸1,700美元上漲至2,300美元,而同期電力變壓器的價格上漲了77%。這些壓力正在縮短散熱器、水泵、風扇和其他冷卻設備供應商報價的有效期限。因此,長期合約可能包含價格調整條款,將投入成本的波動轉嫁到專案價格中。此外,美國聯邦政府資助計畫的國內採購要求可能會進一步限制冷軋取向矽鋼和銅的採購選擇。
細分市場分析
ONAF(被動式空氣冷卻)專為中等負載應用而設計,風扇冷卻即可提供足夠的散熱,預計到2025年將佔據電力變壓器冷卻系統市場36.8%的佔有率。其應用領域包括區域內的高容量配電站、工業用變壓器及商業電網設備。該系統採用強制通風風扇,避免了主動式油循環帶來的成本和維護。由於ONAF系統無需風扇或水泵的輔助電源,因此也常用於低負載和農村地區。其被動式設計也使其維護需求較低。 OFWF(主動式水循環冷卻)的應用範圍則較為有限,包括軌道車輛、抽水蓄能電站和工業爐變壓器。由於水資源豐富,OFWF系統能夠在最大限度地減少面積的同時,實現高散熱性能。
預計從2026年到2031年,OFAF(油導向強制風冷)將以9.8%的複合年成長率成長,是本研究涵蓋的冷卻方式中成長率最高的。 OFAF電力變壓器冷卻系統的市場規模主要得益於離岸風力發電增壓器和資料中心連接設備在持續熱負荷下運作。對於大型緊湊型變壓器,可能沒有足夠的空間來確保ONAF(油導向強制風冷)配置所需的散熱器表面積。根據一項技術評論,在40 MVA至60 MVA的高負荷或波動負荷變壓器中,OFAF和油導向強制風冷系統正得到越來越廣泛的應用。與被動油循環相比,主動油泵能夠提高散熱性能。 IEC 60076-1及其更廣泛的IEC 60076系列標準規定了新設備和升級設備的冷卻等級和工廠熱測試要求。
區域分析
到2025年,亞太地區將佔據電力變壓器冷卻系統市場43.6%的佔有率,預計到2031年將以11.3%的複合年成長率成長。中國1000千伏交流和±800千伏直流超高壓主幹電網的投資,支撐了對用於高容量變壓器的OFAF和OFFWF系統的需求。印度的「配電產業改造計畫」是一項347.6億美元的項目,旨在支持輸配電產業的變壓器採購和冷卻系統升級。日本將於2026年實施變壓器能源效率標準,目標是在24個變壓器類別中實現11.4%的能源效率提升。這些要求正在推動低效率冷卻配置的替換。在印尼、越南和泰國,電網容量擴建正在推進,支撐了新安裝和維修的需求。
本次調查顯示,北美和歐洲是第二大區域叢集,變壓器供應緊張是推動需求成長的主要因素。 2025年9月,日立能源宣佈在美國投資超過10億美元用於製造,其中包括在南波士頓附近投資4.57億美元興建一座大型電力變壓器工廠。在供不應求期間,這些地區的電力變壓器冷卻系統市場也受惠於設備升級和冷卻系統維修。 2025年7月,日立能源與E.ON簽署了一份價值高達7億美元的契約,用於為德國電網基礎設施提供供應。 2025年,卡爾斯魯厄市政電力公司啟動了一項計劃,將在五年內投資超過3600萬歐元(約合3900萬美元),用於開發高壓基礎設施並更換安裝在四個變電站的九台已達到使用壽命的變壓器。北海和波羅的海離岸風力發電的擴張也推動了對100兆伏安以上發電機升壓變壓器用船用OFAF和OFFWF系統的需求。
儘管南美洲和中東及非洲的市場佔有率總合較小,但這些地區對2031年之前的成長仍然至關重要。 WEG宣佈在巴西投資5.43億巴西幣(約9,900萬美元)用於變壓器生產,其中包括可處理高達230千伏電壓等級的變壓器。貝廷工廠的擴建預計將在2026年中期前將產能提高10%。 WEG也向巴西阿西斯變電站交付了三台525千伏單相500兆伏安變壓器。沙烏地阿拉伯的「2030願景」電網規劃、阿拉伯聯合大公國的資料中心發展以及北非的太陽能發電工程都在推動新的變壓器需求。在撒哈拉以南非洲地區,由於電氣化程度的提高和工業投資的增加,長期需求預計將保持穩定。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電網現代化改造和老舊變壓器更換
- 可再生能源併網及增加熱力循環
- 超大規模資料中心和電氣化帶來的負載增加
- 新興經濟體工業和採礦業的電氣化
- 舊款空調圖數位化及改造過程中的兼容性
- 升級模組化冷卻系統以提高變壓器額定功率
- 市場限制因素
- CRGO對鋼材、銅材、鋁材及零件的前置作業時間有差異。
- 高昂的實施成本和對熟練技術人員的需求
- 傳統冷卻器介面的碎片化和認證負擔
- 互聯控制中的網路安全和互通性風險
- 供應鏈分析
- 波特五力分析
- 科技趨勢
- 監理情勢
- 投資分析
第5章 市場規模與成長預測
- 透過冷卻法
- 油自然循環/空氣自然循環系統(ONAN)
- 油自然循環/空氣強制循環系統(ONAF)
- 油壓循環/氣壓循環系統(OFAF)
- 強製油循環/強制水循環法(OFWF)
- 其他冷卻系統
- 透過冷卻裝置
- 散熱器和冷卻面板
- 冷卻風扇和鼓風機
- 油泵和閥門
- 油-空氣熱交換器
- 油水熱交換器
- 冷卻控制面板和監控裝置
- 其他冷卻設備
- 最終用戶
- 公用事業
- 獨立發電機
- 工業和採礦業
- 商業基礎設施和資料中心
- 可再生能源企業
- 鐵路和軌道運輸運營商
- 其他最終用戶
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 義大利
- 西班牙
- 英國
- 波蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 越南
- 泰國
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 埃及
- 南非
- 摩洛哥
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ABB Ltd.
- Alfa Laval AB
- Bharat Heavy Electricals Limited
- CG Power and Industrial Solutions Limited
- GE Vernova Inc.
- Hitachi Energy Ltd.
- Hyosung Heavy Industries Corporation
- Kelvion Holding GmbH
- Luvata Soderkoping AB
- M&I Materials Limited
- Modine Manufacturing Company
- Radiator Manufacturing Company
- Siemens Energy AG
- SPX Technologies, Inc.
- Sterling Thermal Technology
- Tada Electric Co., Ltd.
- Thermofin GmbH
- Toshiba Energy Systems & Solutions Corporation
- Trantech Radiator Products, Inc.
- United Heat Exchanger
- WEG SA
第7章 市場機會與未來展望
According to Mordor Intelligence, the power transformer cooling systems market size is projected to expand from USD 1.24 billion in 2025 and USD 1.36 billion in 2026 to USD 2.11 billion by 2031, at a CAGR of 9.19% between 2026 and 2031.
This report is Segmented by Cooling Method (ONAN, ONAF, OFAF, OFWF, Other), Cooling Equipment (Radiators and Cooling Panels, and More), End User (Utilities, Independent Power Producers, Industrial and Mining, and More), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Power Transformer Cooling Systems Market Trends and Insights
Grid Modernization and Aging Transformer Replacement
Grid operators face rising demand while large new transformers remain difficult to secure within short project schedules. FirstEnergy announced a USD 36 billion capital plan for 2026 through 2030, including more than USD 19 billion for transmission infrastructure. Large power transformers averaged 128 weeks for delivery by mid-2025, and generator step-up units averaged 144 weeks. These lead times make ONAF-to-OFAF conversion kits, replacement radiator banks, and updated control panels practical capacity measures for equipment already operating on the grid. Digitized legacy cooler drawings and compatible retrofit designs can reduce the engineering effort needed to match old equipment interfaces. Modular cooling upgrades also allow utilities to uprate selected transformers while replacement equipment remains on order.
Renewable Energy Integration and Higher Thermal Cycling
Wind and solar generation expose transformers to repeated top-oil and winding hot-spot temperature changes during rapid output ramps. These operating patterns create more cumulative thermal fatigue than conventional generation profiles. Harmonic currents from grid-tied inverters can increase stray and eddy-current losses and create localized hot spots beyond models based on steady operating conditions. The power transformer cooling systems market benefits when generator step-up transformers need OFAF cooling rather than ONAF configurations. Renewable generation patterns were associated with transformer failure rates in research that examined location and operating timing, especially in areas with east-west photovoltaic installations. This need also supports monitoring systems that activate cooling equipment in response to observed thermal conditions.
CRGO Steel, Copper, Aluminum and Component Lead-Time Volatility
Material price changes can reduce cooling system margins and increase the cost of projects for end users. The supplied research states that copper and aluminum together account for more than 60% of power transformer manufacturing costs. It also reports that CRGO silicon steel prices increased from USD 1,700 per ton to USD 2,300 per ton between 2020 and 2025, while power transformer prices rose 77% over that period. These pressures shorten quotation validity periods for suppliers of radiators, pumps, fans, and other cooling equipment. Long-term contracts may therefore include escalation clauses that pass changes in input costs into project pricing. Domestic content conditions for federally funded U.S. projects can further limit sourcing choices for CRGO steel and copper inputs.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale Data Center and Electrification Load Growth
- Industrial and Mining Electrification in Emerging Economies
- High Installed Cost and Skilled-Service Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ONAF held 36.8% of the power transformer cooling systems market share in 2025 because it serves the medium-load range where fan cooling provides sufficient heat removal. Its installed base includes bulk distribution substations, industrial service transformers, and commercial grid equipment across regions. The arrangement uses forced-air fans while avoiding the cost and maintenance needs of active oil circulation. ONAN systems continue to serve lower-load and rural applications because they do not require ancillary power for fans or pumps. Their passive design also has low maintenance requirements. OFWF serves a smaller application group that includes traction, pumped-storage hydro, and industrial furnace transformers. Water availability allows OFWF systems to achieve high heat rejection with a smaller site footprint.
OFAF is projected to expand at a 9.8% CAGR from 2026 through 2031, the fastest rate among cooling methods in the supplied research. The power transformer cooling systems market size for OFAF is supported by offshore wind generator step-up units and data center connections that operate under sustained thermal loads. Large compact transformers can lack enough room for the radiator surface area that an ONAF configuration would require. A technical review found that OFAF and oil-directed air-forced systems are increasingly specified for transformers above 40 MVA to 60 MVA under high or variable loads. Active oil pumping improves thermal performance compared with passive oil circulation. IEC 60076-1 and the wider IEC 60076 series govern cooling classifications and factory thermal testing for new and upgraded units.
Complete Report Scope:
- By Cooling Method
- Oil Natural Air Natural (ONAN)
- Oil Natural Air Forced (ONAF)
- Oil Forced Air Forced (OFAF)
- Oil Forced Water Forced (OFWF)
- Other Cooling Systems
- By Cooling Equipment
- Radiators and Cooling Panels
- Cooling Fans and Blowers
- Oil Pumps and Valves
- Oil-to-Air Heat Exchangers
- Oil-to-Water Heat Exchangers
- Cooling Control Panels and Monitoring Units
- Other Cooling Equipment
- By End User
- Utilities
- Independent Power Producers
- Industrial and Mining
- Commercial Infrastructure and Data Centers
- Renewable Energy Operators
- Rail and Traction Operators
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific accounted for 43.6% of the power transformer cooling systems market share in 2025 and is forecast to grow at an 11.3% CAGR through 2031. China's 1,000 kV AC and +-800 kV DC ultra-high-voltage backbone investments support demand for OFAF and OFWF systems used in high-MVA transformers. India's Revamped Distribution Sector Scheme is a USD 34.76 billion program that supports transformer procurement and cooling upgrades across transmission and distribution. Japan's energy efficiency standards for transformers became effective in 2026 and target an 11.4% improvement across 24 transformer categories. These requirements support the replacement of less efficient cooling configurations. Indonesia, Vietnam, and Thailand are expanding grid capacity, which supports both new installation and retrofit demand.
North America and Europe form the next-largest regional cluster in the supplied research, with demand shaped by transformer supply constraints. Hitachi Energy announced more than USD 1 billion of U.S. manufacturing investment in September 2025, including USD 457 million for a large power transformer facility near South Boston. The power transformer cooling systems market in these regions also benefits from equipment replacement and cooling retrofits during supply shortages. Hitachi Energy signed an agreement worth up to USD 700 million with E.ON in July 2025 for German grid infrastructure delivery. Stadtwerke Karlsruhe began a five-year program in 2025 to invest more than EUR 36 million, or USD 39 million, in high-voltage infrastructure and replace 9 end-of-life transformers across 4 substations. Offshore wind additions in the North Sea and Baltic also support demand for marine-grade OFAF and OFWF systems in generator step-up transformers above 100 MVA.
South America and the Middle East and Africa have smaller combined shares but remain important expansion areas through 2031. WEG announced BRL 543 million, or USD 99 million, of investment in transformer capacity in Brazil, including capacity for voltage classes up to 230 kV. The Betim expansion was expected to add 10% of production capacity by mid-2026. WEG also supplied three single-phase 500 MVA transformers at 525 kV for Brazil's Assis Substation. Saudi Arabia's Vision 2030 grid program, data center development in the UAE, and North African solar projects support new transformer demand. Sub-Saharan Africa offers longer-term potential as electrification and industrial investment increase.
- ABB Ltd.
- Alfa Laval AB
- Bharat Heavy Electricals Limited
- CG Power and Industrial Solutions Limited
- GE Vernova Inc.
- Hitachi Energy Ltd.
- Hyosung Heavy Industries Corporation
- Kelvion Holding GmbH
- Luvata Soderkoping AB
- M&I Materials Limited
- Modine Manufacturing Company
- Radiator Manufacturing Company
- Siemens Energy AG
- SPX Technologies, Inc.
- Sterling Thermal Technology
- Tada Electric Co., Ltd.
- Thermofin GmbH
- Toshiba Energy Systems & Solutions Corporation
- Trantech Radiator Products, Inc.
- United Heat Exchanger
- WEG S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid Modernization and Aging Transformer Replacement
- 4.2.2 Renewable Energy Integration and Higher Thermal Cycling
- 4.2.3 Hyperscale Data Center and Electrification Load Growth
- 4.2.4 Industrial and Mining Electrification in Emerging Economies
- 4.2.5 Legacy Cooler Drawing Digitization and Retrofit Compatibility
- 4.2.6 Modular Cooling Upgrades for Transformer Uprating
- 4.3 Market Restraints
- 4.3.1 CRGO Steel, Copper, Aluminum and Component Lead-Time Volatility
- 4.3.2 High Installed Cost and Skilled-Service Requirements
- 4.3.3 Legacy Cooler Interface Fragmentation and Qualification Burden
- 4.3.4 Cybersecurity and Interoperability Risk in Connected Controls
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Cooling Method
- 5.1.1 Oil Natural Air Natural (ONAN)
- 5.1.2 Oil Natural Air Forced (ONAF)
- 5.1.3 Oil Forced Air Forced (OFAF)
- 5.1.4 Oil Forced Water Forced (OFWF)
- 5.1.5 Other Cooling Systems
- 5.2 By Cooling Equipment
- 5.2.1 Radiators and Cooling Panels
- 5.2.2 Cooling Fans and Blowers
- 5.2.3 Oil Pumps and Valves
- 5.2.4 Oil-to-Air Heat Exchangers
- 5.2.5 Oil-to-Water Heat Exchangers
- 5.2.6 Cooling Control Panels and Monitoring Units
- 5.2.7 Other Cooling Equipment
- 5.3 By End User
- 5.3.1 Utilities
- 5.3.2 Independent Power Producers
- 5.3.3 Industrial and Mining
- 5.3.4 Commercial Infrastructure and Data Centers
- 5.3.5 Renewable Energy Operators
- 5.3.6 Rail and Traction Operators
- 5.3.7 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Alfa Laval AB
- 6.4.3 Bharat Heavy Electricals Limited
- 6.4.4 CG Power and Industrial Solutions Limited
- 6.4.5 GE Vernova Inc.
- 6.4.6 Hitachi Energy Ltd.
- 6.4.7 Hyosung Heavy Industries Corporation
- 6.4.8 Kelvion Holding GmbH
- 6.4.9 Luvata Soderkoping AB
- 6.4.10 M&I Materials Limited
- 6.4.11 Modine Manufacturing Company
- 6.4.12 Radiator Manufacturing Company
- 6.4.13 Siemens Energy AG
- 6.4.14 SPX Technologies, Inc.
- 6.4.15 Sterling Thermal Technology
- 6.4.16 Tada Electric Co., Ltd.
- 6.4.17 Thermofin GmbH
- 6.4.18 Toshiba Energy Systems & Solutions Corporation
- 6.4.19 Trantech Radiator Products, Inc.
- 6.4.20 United Heat Exchanger
- 6.4.21 WEG S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
