


 |
市場調查報告書
商品編碼
2118064
數位音訊平台:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Digital Audio Platforms - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,數位音訊平台市場將從 2025 年的 188 億美元成長到 2026 年的 210.7 億美元,到 2031 年達到 424.9 億美元,2026 年至 2031 年的複合年成長率為 15.06%。
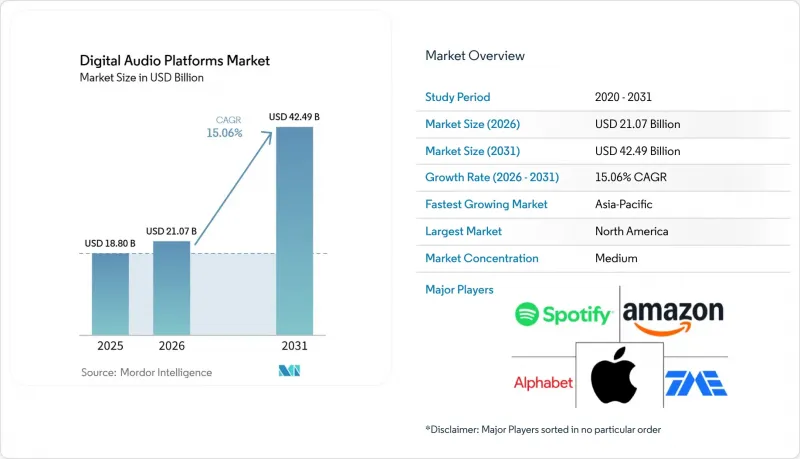
本報告按格式類型(點播音樂串流媒體、線上廣播、播客託管等)、獲利模式(訂閱制、廣告支援制、交易制、混合製等)、裝置(智慧型手機和平板電腦、筆記型電腦和桌上型電腦、智慧音箱和智慧顯示器、聯網汽車等)以及地區進行細分。市場預測以美元計價。
全球數位音訊平台市場趨勢與洞察
最佳化新興經濟體的訂閱定價
2025年,印度擁有1,440萬付費音樂訂閱用戶,而其網路用戶總數超過7億人。該國付費音樂訂閱用戶年增率達37%,音訊訂閱收入超過103億印度盧比(約1.182億美元)。印度用戶年均收入在4美元至10美元之間,而美國則為100美元至140美元。因此,低價策略使得在家庭收入成長之前,就能在大規模的使用者群體中培養出良好的聆聽習慣。這種策略將低價套餐定位為對長期用戶參與的投資,而非短期折扣。預計到2028年,印度的付費用戶數量將成長一倍以上,收入預計將達到220億印度盧比(約2.36億美元)。
電信業者的OTT商品搭售正在推動付費訂閱用戶的成長。
在數位音訊平台市場,由於信用卡限制,直接數位支付受到阻礙,電信業者已成為至關重要的用戶獲取管道。 2026年5月,Reliance Jio推出了一款售價200印度盧比(約2.40美元)的OTT通行證,包含15個串流平台、30GB資料通訊和28天無限量5G網路存取。 2026年6月,CelcomDigi在馬來西亞推出了「StreamMORE」套餐,起價為每月19.90馬來西亞馬幣(約4.50美元)。同樣在2026年6月,Vodafone Idea成為印度首家將Spotify Premium整合到符合條件的後付費方案的電信業者。在此之前,Vodafone Idea已與多家電信業者合作,例如JioSaavn Pro和Apple Music。透過行動套餐獲取的用戶解約率可能較低,因為計費與套餐續約週期掛鉤。
用戶忠誠度成長速度超過了每位用戶平均收入 (ARPU) 的成長速度。
到2025年,內容版稅將佔主要平台收入的65%至68%,限制了毛利率成長的潛力。 Spotify報告稱,2025年其支付的版稅超過110億美元,年增超過10%。 Spotify在2025年第四季的毛利率為32.2%,顯示內容和平台成本在其收入中佔很大比例。美國的「唱片業IV」(Phonorecords IV)框架正在推高歌曲創作和作曲版稅成本,預計將在2027年達到高峰。各大唱片公司在授權談判中也優先考慮用戶細分和提高每位用戶的收入。數位音訊平台市場的低價位部分面臨著尤其巨大的壓力,因為每位聽眾的收入成長速度低於總收聽時長或版稅支付義務的成長速度。
細分市場分析
2025年,點播音樂串流服務佔市場佔有率的52.53%。隨著聽眾從廣播和下載轉向個人化點播服務,數位音訊平台市場正從中受益。至2025年底,全球整體付費音樂串流媒體帳戶數量將達到8.37億。儘管北美和歐洲的用戶用戶成長放緩,但2025年訂閱制串流媒體收入仍成長了8.8%,從而支撐了其持續獲利。在一些西方市場,線上廣播的使用率有所下降,但在新興經濟體的智慧型手機用戶中仍然很受歡迎。
預計2026年至2031年間,有聲書串流服務將以15.16%的複合年成長率成長。 2025年,美國有聲書銷售額成長9%,達到24.3億美元,活躍有聲書數量超過75萬種。 2026年5月,Spotify宣布有聲書收聽時間較去年同期成長60%。 Audiobooks+預計將擁有100萬用戶,並實現1億美元的年度經常性收入(ARR)。現有的智慧型手機和智慧音箱基礎設施降低了觸達已在使用音樂平台的有聲書聽眾的額外成本。
區域分析
2025年,北美市場佔全球市佔率的38.40%。該地區在美國和加拿大擁有較高的用戶人均收入,以及成熟的付費用戶群。墨西哥的錄製音樂市場在2025年成長了13.3%。 Spotify、Apple Music、Amazon Music和YouTube Music正利用獨家播客分銷、硬體整合和個人化功能在美國市場競爭。通用汽車(GM)與Apple Music簽訂的多年合作協議、豐田與Spotify的原生整合以及沃爾沃對Apple Music的採用,都將平台使用權與汽車所有權聯繫起來。儘管南美市場規模仍然較小,但巴西在2025年實現了14.1%的成長。 Claro Musica利用與電信業者的捆綁協議以及巴西、阿根廷和周邊市場的區域音樂庫進行業務拓展。
亞太地區預計將成為數位音訊平台市場成長最快的地區,到2031年複合年成長率(CAGR)預計將達到16.11%。在印度,受價格下降和與電信營運商捆綁合約的推動,付費音樂服務用戶數量在2025年成長了37%,達到1440萬。中國在2025年成長了20.1%,成為全球第四大唱片市場。騰訊音樂娛樂於2026年6月以24億美元完成了對喜馬拉雅的收購,進一步鞏固了其在播客和有聲讀物領域的地位。日本在2025年實現了8.9%的成長,對高品質音訊的需求推動了高階策略的發展。在韓國,現代汽車的平台正在拓展聯網汽車中的音樂收聽管道。歐洲在2025年實現了5.6%的成長,但隱私法規的變化正在促使人們重新評估廣告支援型服務。
中東和非洲地區呈現成長態勢,其中沙烏地阿拉伯和阿拉伯聯合大公國是推動消費成長的主要力量。波灣合作理事會(GCC)成員國智慧型手機普及率超過90%,促進了基於應用程式的直接使用。區域營運商正日益將音訊服務整合到高階後付費方案中。 Anghami正是利用這種營運商模式,在提供全球服務的同時,也建立了區域用戶群。 Boomplay則憑藉其專注於非洲的內容庫、高效的資料通訊串流服務和行動支付,在該地區站穩了腳跟。儘管每用戶收入較低仍然是阻礙因素,但以行動優先、更年輕的用戶群正在支撐數位音訊平台市場的長期成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 最佳化新興市場的訂閱定價
- 電信業者提供的OTT配套服務正在促進付費服務的使用。
- 智慧音箱的部署數量正在迅速增加。
- 在OEM層面整合車載串流功能
- AI語音DJ和生成式播放清單延長了每日收聽時間。
- 基於區塊鏈的版稅支付系統正吸引獨立唱片公司的注意。
- 市場限制因素
- 用戶忠誠度成長速度超過了每位用戶平均收入 (ARPU) 的成長速度。
- 主要唱片公司對內容授權的窗口期控制
- 資料隱私法規限制了廣告定向投放
- 演算法發現偏差正在邊緣化長尾內容創作者。
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按格式類型
- 點播音樂串流
- 線上廣播
- 播客託管
- 有聲書串流媒體
- 其他格式類型
- 透過貨幣化模式
- 訂閱制
- 基於廣告
- 交易基礎
- 混合模式
- 免費增值模式
- 透過裝置
- 智慧型手機和平板電腦
- 筆記型電腦和桌上型電腦
- 智慧電視
- 智慧音箱和智慧顯示螢幕
- 聯網汽車
- 其他設備(穿戴式裝置、物聯網設備等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Spotify Technology SA
- Apple Inc.
- Amazon.com, Inc.
- Alphabet Inc.
- Tencent Music Entertainment Group
- Sirius XM Holdings Inc.
- Deezer SA
- SoundCloud Global Limited and Co. KG
- iHeartMedia, Inc.
- Anghami Plc
- JioSaavn LLC
- Gaana Media Private Limited
- NetEase Cloud Music Inc.
- TIDAL Music AS
- Qobuz SAS
- KKBOX Inc.
- Boomplay Music Group
- Claro Musica
- Napster Group PLC
- Yandex Music
第7章 市場機會與未來展望
According to Mordor Intelligence, the digital audio platforms market size is expected to increase from USD 18.80 billion in 2025 to USD 21.07 billion in 2026 and reach USD 42.49 billion by 2031, growing at a CAGR of 15.06% over 2026-2031.
This report is Segmented by Format Type (On-Demand Music Streaming, Live Internet Radio, Podcast Hosting, and More), Monetization Model (Subscription-Based, Advertising-Based, Transaction-Based, Hybrid, and More), Device (Smartphones and Tablets, Laptops and Desktops, Smart Speakers and Smart Displays, Connected Cars, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Audio Platforms Market Trends and Insights
Subscription Price Rationalization in Emerging Economies
India had 14.4 million paid music subscribers in 2025, compared with an internet user base of more than 700 million people. Paid music subscriptions in the country increased 37% during the year, while audio subscription revenue exceeded INR 10.3 billion (USD 118.2 million). Annual revenue per user in India ranged from USD 4 to USD 10, compared with USD 100 to USD 140 in the United States. Lower prices can therefore build listening habits among large groups before household incomes rise. This approach treats lower-priced tiers as a longer-term engagement investment rather than a short-lived discount. India's paid subscriber base is forecast to more than double by 2028, with revenue forecast to reach INR 22 billion (USD 236 million).
Telco OTT Bundling Pushes Paid Uptake
Telecom operators have become important subscriber channels for the digital audio platforms market where card use limits direct digital payments. In May 2026, Reliance Jio launched an INR 200 (USD 2.40) OTT pass with 15 streaming platforms, 30 GB of data, and unlimited 5G access for 28 days. In June 2026, CelcomDigi introduced StreamMORE plans in Malaysia from MYR 19.90 (USD 4.50) per month. Vodafone Idea also became the first Indian carrier to include Spotify Premium in eligible postpaid plans during June 2026. This model follows earlier carrier relationships involving JioSaavn Pro and Apple Music. Subscribers acquired through a mobile plan can have lower churn because their billing is tied to the plan renewal cycle.
Royalty-Rate Inflation Exceeding ARPU Growth
Content royalties consumed 65% to 68% of major platform revenue in 2025, limiting the room for higher gross margins. Spotify reported paying more than USD 11 billion in royalties during 2025, which was more than 10% higher than the prior year. Spotify's fourth-quarter 2025 gross margin was 32.2%, meaning content and platform costs represented a large share of revenue. The U.S. Phonorecords IV framework continues to increase songwriting royalty costs through its 2027 peak. Major labels are also using consumer segmentation and higher revenue per user as priorities in licensing discussions. Pressure is greatest in lower-priced parts of the digital audio platforms market because revenue per listener grows more slowly than total listening and royalty obligations.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Smart Speaker Install Base Expansion
- OEM-Level In-Car Streaming Integrations
- Content-License Windowing by Major Labels
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
On-demand music streaming held 52.53% of market value in 2025. The digital audio platforms market has benefited as listeners shift from radio and downloads to personalized, on-demand services. Paid music streaming accounts reached 837 million worldwide by the end of 2025. Subscription streaming revenue increased 8.8% during 2025, which supported continuing monetization even as subscriber growth slowed in North America and Europe. Live internet radio has declined in volume across several Western markets but still serves smartphone users in emerging economies.
Audiobook streaming is projected to record a 15.16% CAGR between 2026 and 2031. U.S. audiobook sales increased 9% to USD 2.43 billion in 2025, and more than 750,000 active titles were available. Spotify stated in May 2026 that audiobook listening hours had increased 60% year over year. Audiobooks+ reached 1 million subscribers and was tracking toward USD 100 million in annualized recurring revenue. Existing smartphone and smart speaker infrastructure lowers the added cost of reaching audio listeners who already use a music platform.
Complete Report Scope:
- By Format Type
- On-Demand Music Streaming
- Live Internet Radio
- Podcast Hosting
- Audiobook Streaming
- Other Format Types
- By Monetization Model
- Subscription-Based
- Advertising-Based
- Transaction-Based
- Hybrid Model
- Freemium Model
- By Device
- Smartphones and Tablets
- Laptops and Desktops
- Smart TVs
- Smart Speakers and Smart Displays
- Connected Cars
- Other Devices (Wearable devices, IoT, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 38.40% of global market value in 2025. The region has high revenue per user and mature paid subscriber bases in the United States and Canada. Mexico's recorded-music market grew 13.3% in 2025. Spotify, Apple Music, Amazon Music, and YouTube Music use exclusive podcasts, hardware integration, and personalized features to compete in the United States. General Motors' multiyear Apple Music offer, Toyota's native Spotify access, and Volvo's Apple Music rollout link platform access to vehicle ownership. South America remains smaller, but Brazil grew 14.1% in 2025. Claro Musica uses carrier bundling and regional catalogs across Brazil, Argentina, and nearby markets.
Asia-Pacific is projected to be the fastest-growing region in the digital audio platforms market, with a 16.11% CAGR through 2031. India's paid music subscriber base grew 37% to 14.4 million in 2025 as lower prices and carrier bundles supported conversion. China grew 20.1% in 2025 and became the fourth-largest recorded-music market globally. Tencent Music Entertainment completed its USD 2.4 billion acquisition of Ximalaya in June 2026, extending its position in podcasts and audiobooks. Japan grew 8.9% in 2025, with demand for high-resolution audio supporting premium positioning. South Korea is also expanding the connected-car listening channel through Hyundai's platform. Europe grew 5.6% in 2025, while privacy rules are changing the design of advertising-supported offers.
The Middle East and Africa region grew, with Saudi Arabia and the UAE supporting consumption growth. Smartphone penetration above 90% across Gulf Cooperation Council markets supports direct app-based use. Regional carriers increasingly include audio services in premium postpaid packages. Anghami has used this carrier model to develop a regional subscriber base alongside global services. Boomplay has built a regional position through African catalogs, data-efficient streaming, and mobile money payments. Low revenue per user remains a constraint, but younger mobile-first users support longer-term volume growth for the digital audio platforms market.
- Spotify Technology S.A.
- Apple Inc.
- Amazon.com, Inc.
- Alphabet Inc.
- Tencent Music Entertainment Group
- Sirius XM Holdings Inc.
- Deezer S.A.
- SoundCloud Global Limited and Co. KG
- iHeartMedia, Inc.
- Anghami Plc
- JioSaavn LLC
- Gaana Media Private Limited
- NetEase Cloud Music Inc.
- TIDAL Music AS
- Qobuz SAS
- KKBOX Inc.
- Boomplay Music Group
- Claro Musica
- Napster Group PLC
- Yandex Music
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Subscription Price Rationalization in Emerging Economies
- 4.2.2 Telco OTT Bundling Pushes Paid Uptake
- 4.2.3 Rapid Smart Speaker Install Base Expansion
- 4.2.4 OEM-Level In-Car Streaming Integrations
- 4.2.5 AI Voice DJ and Generative Playlists Extend Daily Listening Time
- 4.2.6 Blockchain-Based Royalty Settlement Attracts Independent Catalogs
- 4.3 Market Restraints
- 4.3.1 Royalty-Rate Inflation Exceeding ARPU Growth
- 4.3.2 Content-License Windowing by Major Labels
- 4.3.3 Data-Privacy Regulations Limiting Ad-Targeting
- 4.3.4 Algorithmic Discovery Bias Marginalizing Long-Tail Creators
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Format Type
- 5.1.1 On-Demand Music Streaming
- 5.1.2 Live Internet Radio
- 5.1.3 Podcast Hosting
- 5.1.4 Audiobook Streaming
- 5.1.5 Other Format Types
- 5.2 By Monetization Model
- 5.2.1 Subscription-Based
- 5.2.2 Advertising-Based
- 5.2.3 Transaction-Based
- 5.2.4 Hybrid Model
- 5.2.5 Freemium Model
- 5.3 By Device
- 5.3.1 Smartphones and Tablets
- 5.3.2 Laptops and Desktops
- 5.3.3 Smart TVs
- 5.3.4 Smart Speakers and Smart Displays
- 5.3.5 Connected Cars
- 5.3.6 Other Devices (Wearable devices, IoT, etc.)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia and New Zealand
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Spotify Technology S.A.
- 6.4.2 Apple Inc.
- 6.4.3 Amazon.com, Inc.
- 6.4.4 Alphabet Inc.
- 6.4.5 Tencent Music Entertainment Group
- 6.4.6 Sirius XM Holdings Inc.
- 6.4.7 Deezer S.A.
- 6.4.8 SoundCloud Global Limited and Co. KG
- 6.4.9 iHeartMedia, Inc.
- 6.4.10 Anghami Plc
- 6.4.11 JioSaavn LLC
- 6.4.12 Gaana Media Private Limited
- 6.4.13 NetEase Cloud Music Inc.
- 6.4.14 TIDAL Music AS
- 6.4.15 Qobuz SAS
- 6.4.16 KKBOX Inc.
- 6.4.17 Boomplay Music Group
- 6.4.18 Claro Musica
- 6.4.19 Napster Group PLC
- 6.4.20 Yandex Music
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 專輯發行服務市場:全球市場預測,2026-2032年音樂演出行程管理軟體市場:全球市場預測,2026-2032年
 2026年全球音樂視覺化市場報告線上點歌軟體市場按設備類型、整合管道、音樂類型偏好、定價模式、用戶年齡層和最終用戶分類,全球預測,2026-2032年