


 |
市場調查報告書
商品編碼
2118062
原創內容:市佔率分析、產業趨勢與統計、成長預測(2026-2031年)Original Content - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,原創內容市場規模預計在 2025 年達到 779.8 億美元,2026 年達到 860.4 億美元,2031 年達到 1301.4 億美元,2026 年至 2031 年的複合年成長率為 8.63%。
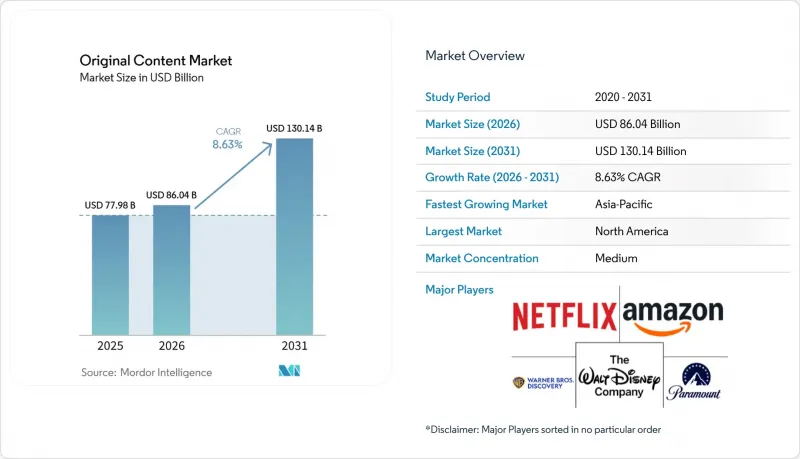
本報告按內容類型(電影、電影長片、原創劇集、網路影集、紀錄片、非虛構類節目等)、內容所有權(原創作品等)、發行管道(OTT串流平台、電視網、廣播公司等)和地區(北美、亞太等)進行細分。市場預測以美元計價。
全球原創內容市場趨勢與洞察
透過獨家經銷實現差異化的需求日益成長。
獨家節目仍然是原創內容市場和用戶留存的核心。這是因為平台需要有充分的理由讓用戶在看完節目後繼續使用其服務。因此,在原創內容市場,那些能夠打造高知名度節目並持續提供這些節目的服務,能夠將節目作為服務的重要組成部分而非一次性發布,就備受青睞。迪士尼已公佈其2026會計年度在娛樂和體育領域的240億美元內容投資計畫。與2022會計年度330億美元的尖峰時段相比,這標誌著其投資策略從追求數量轉向更加精挑細選的系列節目和更高品質的節目。這種轉變有利於那些擁有明確受眾吸引力、高知名度角色以及永續版權的節目,這些版權可以在服務中長期有效利用。而那些缺乏強大的系列節目、本地製作內容或觀眾難以在其他地方找到的獨家劇集的小規模服務,則面臨著更大的壓力。在這種情況下,由於資源有限,且難以將成本分攤到大規模的受眾群體上,購買內容或與內容方合作可能比嘗試維持自己的內容陣容更現實。
透過廣告收入實現獲利可以延長內容的投資回收期。
廣告收入模式拓展了原創節目的收入來源,使其不再局限於訂閱費,從而降低了對單一收入來源的依賴。這種模式支持原創內容市場,即使沒有大量新增用戶,也能透過觀看時間長度和廣告位創造價值。免費的廣告支援型電視節目也反映了這種模式的規模。根據Tubi預測,到2026年3月,其每月有效用戶將超過1億,每月觀看時間將達到10億小時。較長的觀看時間提升了與內容相關的廣告價值,從而支持那些能夠透過重複觀看來保持觀眾興趣的節目。對於中等預算的劇集、紀錄片和非劇本類節目而言,如果收入不僅以即時用戶成長來衡量,還要以多個觀看週期來衡量,那麼這類節目將更具優勢。在這種模式下,觀眾參與度在製作決策中變得更加重要,因為平台可以透過用戶數量、廣告收入和後續節目庫使用情況來評估節目。
內容成本上漲給利潤率帶來了壓力。
人事費用上漲對原創內容市場中優質原創節目的獲利能力帶來壓力,使得製片公司和平台更難制定製作計劃。美國編劇工會(WGA)於2026年5月批准了“2026年最低基本協議”,其中包括在整個合約期間總合工資上漲10.5%,提高高預算訂閱影片的剩餘收益,以及雇主為員工醫療保險計劃繳納2.8億美元。這些條款正在影響許多好萊塢製作的成本基礎,要求買家在決定投資大規模製作項目之前仔細考慮每個項目的總成本。迪士尼將計畫內容投資從2022會計年度的尖峰時段330億美元削減至2026會計年度的240億美元,也反映出其對製作成本的更嚴格控制。高預算劇本節目的風險尤其高,因為每一集都會產生大量的製作和人事費用,而且這些成本並非總是能迅速收回。因此,製作人正將重點放在非虛構類節目、聯合製作和擁有成熟觀眾群的系列節目,同時繼續依靠劇本節目來吸引付費用戶。
細分市場分析
到2025年,原創影集和網路影集將佔原創內容市場的44.47%。連續劇模式鼓勵觀眾反覆觀看,使平台有理由在多次觀看過程中留住觀眾。這種模式比單次觀看更能有效提高觀眾留存率。原創劇集也有助於塑造人物和建構故事世界,從而促進後續節目的推廣。預計到2031年,真人秀和非虛構類內容將以9.11%的複合年成長率成長。與劇本類節目相比,它們的製作成本較低,因此對依賴廣告收入的服務更具吸引力。它們熟悉的模式能夠適應不同的文化背景,並且可以在不增加製作複雜性的情況下進行改版。這使得負責人能夠在推出高人氣劇本類節目的同時,兼顧更廣泛的節目內容。這種內容結構既能為用戶提供永續的價值,又能滿足對製作成本更嚴格控制的需求。即使大規模的經濟效益下降,這種結構也允許服務商靈活調整其節目製作計劃。
電影和長片在原創內容市場仍佔據重要地位,而院線發行能夠帶動後續的串流媒體需求。亞馬遜米高梅印度影業正在擴大其院線發行業務,並宣布將於2026年3月推出55部影片,其中包括印地語、泰米爾語和泰盧固語節目。紀錄片和非劇本類內容能夠在廣告支援的平台上吸引觀眾更長久。它們的製作特點使其成為昂貴的劇本類劇集的實用替代方案。動畫和兒童節目憑藉其角色和故事的價值,能夠長期保持人氣。據迪士尼稱,皮克斯自2017年以來已發行了8部原創電影,這一數字超過了同期除迪士尼以外的主要動畫競爭對手的總合。實況活動、原創體育節目和綜藝特別節目能夠提升觀眾參與度,滿足平台對及時內容的需求。這些形式為用戶提供了使用平台的新理由,並能夠擴大節目涵蓋的受眾群體。因此,內容規劃依賴內容的重複利用、廣告價值和更廣泛的版權組合。由於每種節目形式的作用不同,均衡的節目安排可以減少對特定類型觀眾反應的依賴。
區域分析
2025年,北美原創內容市佔率將達到32.35%。該地區擁有眾多大型製片廠、大規模串流媒體平台以及雄厚的製作資金實力。迪士尼在2026會計年度對娛樂和體育內容的240億美元投資,清楚地展現了該地區主要參與者所擁有的巨大規模。歐洲仍然是重要的製作外包地區,因為本地製作的內容能夠支持國內收視和跨境發行。與歐洲的合作也使製片廠能夠利用成熟的製作人才和公共廣播機構的資源。
預計到2031年,亞太地區的複合年成長率將達到9.32%。這一成長前景得益於行動優先的觀看習慣、日益普及的網路連線以及人們對韓國、印度和日本故事日益成長的興趣。該地區的原創內容市場正受益於本土製作的作品觸達海外觀眾。 CJ ENM與HBO Max在亞太地區17個市場合作推出的TVING項目,為韓國節目在全部區域發行搭建了一條系統化的管道。富士電視台將「FOD SHORT」拓展至北美市場,也反映了日本製作公司海外擴張的趨勢。
南美洲、中東和非洲雖然規模較小,但卻是具有重要戰略意義的製作和觀看中心。在中東,原創內容的製作正在拓展國內娛樂選擇,並促進文化產出。奈及利亞和南非憑藉著行動優先的觀看方式和適應當地情況的劇集形式吸引了人們的注意。盜版阻礙了這些地區的盈利;根據印度資訊與廣播部預測,到2024年,預計將有9000萬用戶訪問盜版影片,造成12億美元的收入損失。該地區的商業機會取決於在改善合法管道的同時,也要兼顧支撐原創節目吸引力的當地實際情況。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 透過專屬訂閱實現差異化的需求日益成長
- 透過廣告實現獲利正在延長內容的投資回報期。
- 在高成長市場中,使用當地語言的原創內容可以提高客戶留存率。
- 合作模式可以降低初期財務風險。
- 人工智慧驅動的開發提高了試運行的效率。
- 基於特許經營的智慧財產權可以降低搜尋成本並提高終身價值。
- 市場限制因素
- 內容成本上漲給利潤率帶來了壓力。
- 受眾群體分散會增加熱門歌曲的幾率。
- 在價格敏感型市場中,盜版正在阻礙獲利。
- 對本地內容、評級和數據使用的監管力道正在加大,合規負擔也不斷加重。
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 技術展望
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 按內容類型
- 電影和電影長片
- 原創影集與網路劇
- 紀錄片和非虛構作品
- 真人秀和非劇本內容
- 動畫和兒童內容
- 其他內容類型
- 按內容所有權
- 原創作品均為內部創作
- 委託製作
- 聯合製作夥伴關係
- 內容取得和授權
- 其他內容所有權形式
- 透過分銷管道
- OTT串流平台
- 電視網路及廣播公司
- 社群媒體平台
- 院線發行與混合發行管道
- 其他分銷管道
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- Vendor Positioning Analysis
- 公司簡介
- Netflix, Inc.
- Amazon.com, Inc.
- The Walt Disney Company
- Warner Bros. Discovery, Inc.
- Comcast Corporation
- Paramount Global
- Apple Inc.
- Sony Group Corporation
- NBCUniversal Media, LLC
- BBC Studios Limited
- ITV plc
- FremantleMedia Limited
- Banijay Entertainment
- TelevisaUnivision, Inc.
- ViX, Inc.
- ZEE Entertainment Enterprises Limited
- JioStar
- Tencent Holdings Limited
- Alibaba Group Holding Limited
- iQIYI, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the original content market was USD 77.98 billion in 2025, USD 86.04 billion in 2026, and is forecast to reach USD 130.14 billion by 2031, at a CAGR of 8.63% during 2026-2031.
This report is Segmented by Content Type (Movies and Feature Films, Original Series and Web Series, Documentary and Non-Fiction, and More), Content Ownership (In-House Original Production, and More), Distribution Channel (OTT Streaming Platforms, Television Networks and Broadcasters, and More), and Geography (North America, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Original Content Market Trends and Insights
Rising Demand for Exclusive Subscription Differentiation
Exclusive programming remains central to the original content market and subscriber retention because platforms need a clear reason for customers to stay after finishing a title. The Original content market therefore rewards services that can build recognizable, repeatable programming and present it as a sustained part of the service rather than a one-time release. Disney reported USD 24 billion in planned fiscal 2026 content investment across entertainment and sports, compared with USD 33 billion at its fiscal 2022 peak, showing a move from volume toward selected franchises and stronger programming choices. The shift favors titles with clear audience appeal, recognizable characters, and durable rights that can be used across a service over an extended period. Smaller services face more pressure when they lack franchises, local production depth, or exclusive series that are difficult for viewers to find elsewhere. In that setting, acquisition or partnership can become more practical than trying to maintain a standalone slate with limited resources and limited ability to spread costs across a large audience.
Ad-Supported Monetization Expands Content Payback Windows
Advertising-supported plans expand the revenue available within the original content market from original programming beyond subscription fees and reduce reliance on a single source of return. This supports the original content market because a title can create value through viewing time and advertising inventory even when it does not bring in a large number of new subscribers. Free, ad-supported television also shows the scale of this model, with Tubi reporting more than 100 million monthly active users and 1 billion monthly streaming hours in March 2026. Longer viewing sessions can increase the value of well-matched advertising and support programs that sustain attention across repeated sessions. Mid-budget series, documentaries, and unscripted programs are better positioned when revenue is measured over more than one viewing window and not only through immediate subscription growth. The model makes audience engagement more important to commissioning decisions because platforms can assess a program through subscription, advertising, and later catalog use.
Content Cost Inflation Compresses Returns
Higher labor costs are tightening returns on premium original programming in the original content market and are making production planning more difficult for studios and platforms. The WGA ratified its 2026 Minimum Basic Agreement in May 2026, including minimum pay increases totaling 10.5% across the contract term, higher residuals for high-budget subscription video, and a USD 280 million employer contribution to the health plan. These terms affect the cost base for many Hollywood productions and require buyers to consider the full cost of a title before committing to a larger slate. Disney's reduction in planned content investment from USD 33 billion at its fiscal 2022 peak to USD 24 billion in fiscal 2026 also reflects greater discipline around production spending. High-budget scripted titles are particularly exposed because each episode carries higher production and labor commitments that cannot always be recovered quickly. Producers are therefore giving more attention to unscripted formats, co-productions, and franchises with established audiences, while continuing to rely on scripted programs for premium subscriber appeal.
Other drivers and restraints analyzed in the detailed report include:
- Local-Language Originals Improve Retention in High-Growth Markets
- Co-Production Models Reduce Upfront Financial Risk
- Audience Fragmentation Raises Hit Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Original series and web series accounted for 44.47% of the original content market size in 2025. Serialized stories encourage repeat viewing and give platforms a reason to keep audiences engaged over multiple sessions. This format can support retention more effectively than a single viewing event. Original series can also establish characters and story worlds that make later programming easier to promote. Reality shows and unscripted content are projected to grow at a 9.11% CAGR through 2031. Their lower production cost relative to scripted programs makes them useful for advertising-supported services. Their familiar formats can work across different cultural settings and can be refreshed without the same production complexity. This gives commissioners a way to balance high-profile scripted releases with a broader flow of programming. The mix responds to the need for durable subscriber value and more disciplined production spending. It also lets services adjust their slate when the economics of a large scripted project become less attractive.
Movies and feature films remain important in the original content market where a theatrical release can support later streaming demand. Amazon MGM Studios India announced a 55-title slate in March 2026 across Hindi, Tamil, and Telugu programming while expanding theatrical activity. Documentary and non-fiction programming can provide longer viewing sessions for advertising-supported platforms. Their production profile can make them a practical complement to expensive scripted series. Animation and kids programming has value because characters and stories can remain relevant for extended periods. Disney reported that Pixar had released 8 original films since 2017, more than other major non-Disney animation competitors combined in that period. Live events, sports originals, and variety specials can strengthen engagement where services need timely programming. These formats provide a different reason to visit a platform and can widen the audience served by a slate. Content planning therefore depends on repeat use, advertising value, and the wider rights portfolio. Each format has a different role, so a balanced slate can reduce dependence on any one type of viewer response.
Complete Report Scope:
- By Content Type
- Movies and Feature Films
- Original Series and Web Series
- Documentary and Non-Fiction
- Reality Shows and Unscripted Content
- Animation and Kids Content
- Other Content Types
- By Content Ownership
- In-House Original Production
- Commissioned Production
- Co-Production Partnerships
- Content Acquisition & Licensing
- Other Content Ownerships
- By Distribution Channel
- OTT Streaming Platforms
- Television Networks and Broadcasters
- Social Media Platforms
- Theatrical and Hybrid Release Channels
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 32.35% of the Original content market share in 2025. The region benefits from major studios, large streaming platforms, and strong access to production finance. Disney's USD 24 billion fiscal 2026 content investment across entertainment and sports illustrates the scale available to leading companies in the region. Europe remains a significant commissioning region because local production supports domestic viewing and cross-border distribution. European partnerships also give studios access to established production talent and public-service media capability.
Asia-Pacific is projected to grow at a 9.32% CAGR through 2031. Mobile-first viewing, expanding connectivity, and interest in Korean, Indian, and Japanese stories support this position. The original content market size in the region benefits when locally produced titles can reach viewers outside their home country. CJ ENM's TVING arrangement with HBO Max in 17 Asia-Pacific markets creates a structured route for Korean programming across the region. Fuji Television's North American launch for FOD SHORT also shows the outward reach of Japanese producers.
South America, the Middle East, and Africa are smaller but strategically important production and viewing corridors. The Middle East is using original content productions to support domestic entertainment options and cultural exports. Nigeria and South Africa are gaining attention through mobile-first consumption and locally relevant drama formats. Piracy limits monetization across these regions, and India's Ministry of Information and Broadcasting reported 90 million users accessed pirated video in 2024, causing USD 1.2 billion in lost revenue. The regional opportunity depends on improving legal access while maintaining the local relevance that gives original programming its appeal.
- Netflix, Inc.
- Amazon.com, Inc.
- The Walt Disney Company
- Warner Bros. Discovery, Inc.
- Comcast Corporation
- Paramount Global
- Apple Inc.
- Sony Group Corporation
- NBCUniversal Media, LLC
- BBC Studios Limited
- ITV plc
- FremantleMedia Limited
- Banijay Entertainment
- TelevisaUnivision, Inc.
- ViX, Inc.
- ZEE Entertainment Enterprises Limited
- JioStar
- Tencent Holdings Limited
- Alibaba Group Holding Limited
- iQIYI, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Exclusive Subscription Differentiation
- 4.2.2 Ad Supported Monetization Expands Content Payback Windows
- 4.2.3 Local Language Originals Improve Retention in High Growth Markets
- 4.2.4 Co Production Models Reduce Upfront Financial Risk
- 4.2.5 AI Assisted Development Improves Commissioning Efficiency
- 4.2.6 Franchise Based IP Reduces Discovery Costs and Improves Lifetime Value
- 4.3 Market Restraints
- 4.3.1 Content Cost Inflation Compresses Returns
- 4.3.2 Audience Fragmentation Raises Hit Risk
- 4.3.3 Piracy Erodes Monetization in Price Sensitive Markets
- 4.3.4 Regulatory Scrutiny on Local Content, Ratings, and Data Use Increases Compliance Burden
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Content Type
- 5.1.1 Movies and Feature Films
- 5.1.2 Original Series and Web Series
- 5.1.3 Documentary and Non-Fiction
- 5.1.4 Reality Shows and Unscripted Content
- 5.1.5 Animation and Kids Content
- 5.1.6 Other Content Types
- 5.2 By Content Ownership
- 5.2.1 In-House Original Production
- 5.2.2 Commissioned Production
- 5.2.3 Co-Production Partnerships
- 5.2.4 Content Acquisition & Licensing
- 5.2.5 Other Content Ownerships
- 5.3 By Distribution Channel
- 5.3.1 OTT Streaming Platforms
- 5.3.2 Television Networks and Broadcasters
- 5.3.3 Social Media Platforms
- 5.3.4 Theatrical and Hybrid Release Channels
- 5.3.5 Other Distribution Channels
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Vendor Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Netflix, Inc.
- 6.4.2 Amazon.com, Inc.
- 6.4.3 The Walt Disney Company
- 6.4.4 Warner Bros. Discovery, Inc.
- 6.4.5 Comcast Corporation
- 6.4.6 Paramount Global
- 6.4.7 Apple Inc.
- 6.4.8 Sony Group Corporation
- 6.4.9 NBCUniversal Media, LLC
- 6.4.10 BBC Studios Limited
- 6.4.11 ITV plc
- 6.4.12 FremantleMedia Limited
- 6.4.13 Banijay Entertainment
- 6.4.14 TelevisaUnivision, Inc.
- 6.4.15 ViX, Inc.
- 6.4.16 ZEE Entertainment Enterprises Limited
- 6.4.17 JioStar
- 6.4.18 Tencent Holdings Limited
- 6.4.19 Alibaba Group Holding Limited
- 6.4.20 iQIYI, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White Space and Unmet Need Assessment

 全球多通路網路市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 百科全書服務市場規模、佔有率和成長分析:按服務類型、內容類型、部署方式、最終用戶、收入模式和地區分類-2026-2033年產業預測
 2034年教育數位內容製作市場預測-按組件、內容類型、部署方式、設備類型、最終用戶和地區分類的全球分析
 數位商品市場規模、佔有率和成長分析:按產品、經營模式、平台、最終用戶、分銷管道、支付模式和地區分類-2026-2033年產業預測
 多通路網路市場規模、佔有率和成長分析:按產品/服務、平台類型、服務類型、應用、最終用戶、收入模式和地區分類-2026-2033年產業預測
 2026年全球數位內容與服務市場報告
 日本智慧財產權相關產品和內容市場規模、佔有率和趨勢報告:按類型、年齡層、性別、分銷管道、地區和細分市場分類的預測(2026-2033 年)
 數位內容製作市場:依內容類型、部署模式、最終用戶和產業分類-2026-2032年全球市場預測
 數位內容創作者市場分析及預測(至2035年):類型、產品類型、服務、技術、組件、應用、設備、部署模式、最終用戶數位內容製作市場分析及預測(至2035年):類型、產品類型、服務、技術、組件、應用、形式、設備、部署形式、最終用戶