


 |
市場調查報告書
商品編碼
2116772
蝶閥:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Butterfly Valve - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
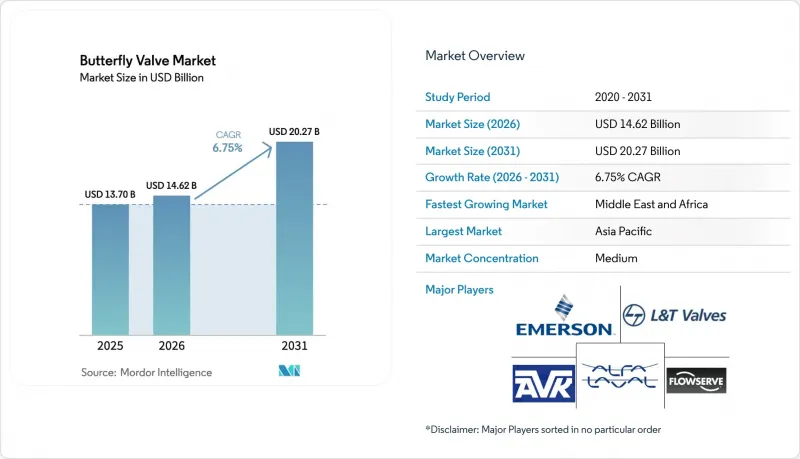
根據 Mordor Intelligence 估計,到 2026 年,蝶閥市值將達到 146.2 億美元,高於 2025 年的 137 億美元,預計到 2031 年將達到 202.7 億美元。
預計 2026 年至 2031 年的複合年成長率為 6.75%。
本報告按類型(高性能蝶閥、襯裡蝶閥、彈性閥座蝶閥、其他)、設計(同心、雙偏心、三偏心)、功能(開/關(關閉)、控制、節流)、最終用戶行業(石油和天然氣、水和污水處理、能源和發電、化學、製藥、其他)和地區進行分類。
全球蝶閥市場趨勢及洞察
增加對石油和氣體純化以及跨境管道的投資
大型管道,例如全長1443公里的東非原油管線,需要65個高壓截止閥站,預計訂單。馬來西亞國家石油公司(Petronas)計劃在2025年至2027年間鑽探400多口油井,預計將維持上游對高壓閥門的需求。長距離油氣運輸使得管道直徑超過48英吋的情況日益增多,迫使供應商擴大鑄造和加工能力。為了抵抗酸性環境的腐蝕,材料選擇正轉向雙相不銹鋼和因科鎳合金(Inconel)。同時,可再生能源的發展也催生了對冷卻迴路的需求,導致蝶閥市場呈現混合格局,既有來自傳統能源領域的訂單,也有來自新能源領域的訂單。
為地方政府和工業企業擴大供水和污水基礎設施
阿克倫市已為其2025年供水計畫累計3.809億美元,其中1.41億美元用於遵守污水處理法規,這帶動了彈性閥座蝶閥的穩定訂單。米德爾塞克斯縣公共產業部門一項耗資2306.6萬美元的維修項目正在用更高效的塞閥替換老舊的蝶閥,這表明閥門更換週期已成定局。 NSF/ANSI認證產品目前在飲用水相關競標佔據主導地位,這推動了無鉛合金的研發。像奧羅拉市這樣的市政當局正在強制執行器安裝標準,以提高操作人員的安全性和資產管理效率。長期資金籌措的穩定性使閥門製造商能夠在最大限度降低風險的同時制定產能擴張計劃。
低壓節流期間的空化和阻塞風險
當壓力損失超過入口壓力的30-40%時,蒸氣氣泡會內爆到下游表面,侵蝕閥瓣或閥座。在先進的工廠中,對噪音和振動的要求低於80分貝,這促使工程師擴大在關鍵迴路中採用截止閥。 Bray的39系列採用碳化矽襯裡來抑制侵蝕,但這與標準塗層相比會增加20-30%的成本。隨著先進控制系統的普及,這種固有的設計限制阻礙了蝶閥在節流應用領域的進一步滲透。
細分市場分析
預計到2025年,高性能產品將佔蝶閥銷售額的54.40%,佔蝶閥市場佔有率的最大部分。這是因為製程工廠優先考慮危險流體的「零洩漏」可靠性。彈性閥座閥在暖通空調和溫和流體應用中銷售仍然強勁,但來自亞洲供應商的價格競爭正在擠壓其利潤空間。襯裡產品正以7.85%的複合年成長率成長,這主要得益於化工、製藥和半導體製造企業對PTFE或PFA等強腐蝕性酸阻隔層的需求。中國製造商目前正在改進膏體擠出技術以提高黏合強度,但現場報告顯示,在低於10巴的運作條件下,襯裡偶爾會出現分層現象。
這項創新的核心在於其模組化閥體和可更換的閥座環,使原始設備製造商 (OEM) 能夠以最少的庫存組裝定製配置。雖然三偏心設計的價格較高,但其金屬對金屬密封件能夠承受熱衝擊,因此在氫氣、液化天然氣 (LNG) 和其他運作條件嚴苛的迴路中越來越受歡迎。這種專業化特性推高了平均售價,從而在蝶閥市場中保持了盈利。
雙偏心閥配置預計在2025年將佔總銷售額的39.30%,並繼續在煉油廠和發電廠的截止應用中佔據主導地位。計算流體力學(CFD)最佳化了閥盤配置,與傳統設計相比,可降低10%至15%的壓力損失。三偏心閥配置預計將實現8.10%的複合年成長率,這主要得益於綠色氫電解槽需要雙向且無氣泡的截止操作以維持效率。同心閥設計在飲用水管領域仍然佔據主導地位,因為該領域壓力保持在16巴以下,但隨著市政部門傾向於選擇高性能閥板以實現長週期更換,其成長速度正在放緩。
Quadax 的四偏置原型機突破了液態氫在 -253 度C低溫傳輸領域的應用極限,預示著一個全新的高階細分市場的到來。模具的複雜性和特殊合金的使用設定了很高的進入門檻,使現有專利擁有者擁有結構性優勢。因此,蝶閥市場正在向少數幾家能夠投資先進加工技術和低溫檢測迴路的公司集中。
區域分析
預計到2025年,亞太地區將佔全球銷售額的39.50%,主要得益於中國國內市場的強勁成長。中國國內市場正以5.86%的複合年成長率快速擴張,市場規模達130億元人民幣(約18億美元)。化工企業貢獻了該地區25%至30%的需求,推動紐威閥門2023年的銷售額成長36.59%。上海電動閥門廠投資10億元人民幣(約1.4億美元)建設智慧工廠,體現了該地區產能的持續擴張。同時,印度的煉油和飲用水供應項目正在加速推進,而日本的經濟重點則放在氫氣供應網路建設上,KITZ公司正在日本擴大其三偏心閥產品線。
中東和非洲正以6.95%的複合年成長率推動市場成長,東非石油天然氣項目(EACOP)和坦尚尼亞液化天然氣項目等大型企劃正朝著最終投資決定(FID)邁進,每個項目都指定使用數百個大口徑蝶閥。海灣國家正在推進氫氣出口走廊建設,需要使用額定負載為600磅的三偏心蝶閥,但只有少數供應商能夠提供認證。強制性的在地採購要求正在推動合資企業的成立,並改變蝶閥市場的籌資策略。
在北美,隨著頁岩氣開發趨於穩定,市政供水事業價值超過10億美元,設備升級主導了這項發展動能。 《通膨控制法案》為電解槽製造提供了獎勵,綠色氫循環閥門的國內訂單也不斷成長。在歐洲,儘管面臨全氟烷基物質(PFAS)相關成本上升的不利影響,但積極的脫碳補貼津貼正在抵消這一影響,這些補貼要求使用高性能的氫兼容設備。南美洲的前景取決於大宗商品週期趨勢,巴西鹽層下油田和阿根廷瓦卡穆埃爾塔盆地為流量控制設備的基準投資提供了支撐。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 增加對石油和氣體純化以及跨境管道的投資
- 為地方政府和工業企業擴大供水和污水基礎設施
- 對具有優異密封性能的高性能閥門的需求
- 在綠色氫氣電解槽中採用三偏心閥
- 利用工業物聯網賦能的智慧執行器降低整體擁有成本
- 輕質熱塑性樹脂閥門支持公共產業,促進脫碳
- 市場限制因素
- 低壓節流期間的空化和阻塞風險
- 低規格彈性閥座的價格商品化
- 氟聚合物襯裡(PTFE/PFA)的供應和成本波動
- 採用物聯網執行器的關鍵資產的網路安全問題
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 高性能蝶閥
- 襯裡蝶閥
- 彈性座蝶閥
- 三偏心蝶閥
- 其他
- 有意為之
- 同心圓
- 雙六型
- 三偏移式
- 按功能
- 開/關(阻塞)
- 控制
- 光圈
- 按最終用戶行業分類
- 石油和天然氣
- 水和污水處理
- 能源和發電
- 化學品
- 製藥
- 飲食
- 暖通空調及建築設備
- 紙漿和造紙
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 南非
- 埃及
- 其他非洲國家
- 非洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Emerson Electric Co.
- Flowserve Corporation
- AVK Holding A/S
- Alfa Laval AB
- L & T Valves Limited
- Crane Co.
- Curtiss-Wright Corporation
- NIBCO Inc.
- Valmet Oyj
- XHVAL Valve Co., Ltd.
- Huamei Machinery Co., Ltd.
- Bray International, Inc.
- AT Controls, Inc.
- Georg Fischer AG(GF Piping Systems)
- Belimo Holding AG
- Aalberts NV(Apollo Valves)
- Parker-Hannifin Corporation
- KSB SE and Co. KGaA
- SAMSON AG
- Dembla Valves Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the butterfly valves market size in 2026 is estimated at USD 14.62 billion, growing from 2025 value of USD 13.7 billion with 2031 projections showing USD 20.27 billion, growing at 6.75% CAGR over 2026-2031.
This report is Segmented by Type (High-Performance Butterfly Valves, Lined Butterfly Valves, Resilient-Seated Butterfly Valves, and More), Design (Concentric, Double Offset, Triple Offset), Function (On/Off (Isolation), Control, Throttling), End-User Industry (Oil and Gas, Water and Wastewater, Energy and Power, Chemical, Pharmaceutical, and More), and Geography.
Global Butterfly Valve Market Trends and Insights
Increasing investments in oil and gas refineries and cross-border pipelines
Mega-pipelines such as the 1,443 km East African Crude Oil Pipeline require 65 high-pressure block-valve stations, creating sizable orders for 20-40 in butterfly valves. PETRONAS plans more than 400 well drills between 2025-2027, sustaining upstream demand for high-pressure valves. Long-distance hydrocarbon transport pushes diameters beyond 48 in, encouraging suppliers to upgrade casting and machining capacity. Material selection is shifting toward duplex stainless and Inconel to resist sour-service corrosion. Concurrent renewables build-outs add cooling-circuit needs, blending traditional and new-energy orders within the butterfly valves market.
Expansion of municipal and industrial water-wastewater infrastructure
The City of Akron earmarked USD 380.9 million for 2025 water projects, including USD 141 million for sewer compliance, placing steady orders for resilient-seated butterfly valves. Middlesex County Utilities Authority's USD 23.066 million upgrade swaps aging butterfly valves for more efficient plug valves, illustrating the periodic replacement cycle. NSF/ANSI-certified products now dominate potable-water bids, driving R&D toward lead-free alloys. Cities such as Aurora mandate actuator orientation standards that enhance operator safety and asset management. Long-term funding certainty enables valve makers to blueprint capacity additions with lower risk.
Cavitation/choke risk under low-pressure throttling
When pressure drop exceeds 30-40% of inlet pressure, vapor bubbles implode on the downstream face, eroding discs and seats. Modern plants seek sub-80 dBA noise and low vibration, so engineers increasingly switch to globe valves in critical loops. Bray's Series 39 adopts silicon-carbide liners to curb erosion, but cost rises by 20-30% versus standard coatings. As advanced control systems proliferate, this inherent design limitation caps deeper penetration of throttling duties for the butterfly valves market.
Other drivers and restraints analyzed in the detailed report include:
- Demand for high-performance valves with tight shut-off and high durability
- Triple-offset valves adopted in green-hydrogen electrolyzers
- Volatile supply and cost of fluoropolymer linings (PTFE/PFA)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-performance products captured 54.40% of 2025 revenue, underpinning the largest slice of the butterfly valves market share because process plants prioritize zero-leak reliability in hazardous media. Resilient-seated valves still move high volume for HVAC and benign fluids, but price competition from Asian suppliers thins margins. Lined variants expand at 7.85% CAGR, buoyed by chemical, pharmaceutical, and semicon fabs that require PTFE or PFA barriers against aggressive acids. Chinese producers now refine paste-extrusion techniques that improve bond strength, yet field reports cite occasional lining delamination under 10 bar service.
Innovation centers on modular bodies that accept interchangeable seat rings, allowing OEMs to assemble custom configurations from lean inventories. Triple-offset designs, though premium-priced, earn rising traction in hydrogen, LNG and severe-service circuits because metal-to-metal seals endure thermal shock. Such specialization lifts the average selling price and sustains profitability in the butterfly valves market.
Double-offset geometry held 39.30% of 2025 sales, retaining mainstream status for refinery and power-plant isolation. Computational fluid-dynamics optimizes disc profiles, slicing pressure drop by 10-15% versus legacy patterns. Triple-offset units are forecast to post 8.10% CAGR, propelled by green-hydrogen electrolyzers that demand bidirectional, bubble-tight shut-off to safeguard efficiency. Concentric designs still dominate potable-water lines where pressures stay below 16 bar, but growth flattens as municipalities favour higher-performance seats for long-cycle replacement.
Quadax's 4-offset prototype pushes application envelopes to -253 °C liquid-hydrogen transfer, hinting at a new top-end niche. Tooling complexity and exotic alloys raise entry barriers, lending established patent holders structural advantage. As a result, the butterfly valves market consolidates around a handful of firms that can finance advanced machining and cryogenic test loops.
Complete Report Scope:
- By Type
- High-Performance Butterfly Valves
- Lined Butterfly Valves
- Resilient-Seated Butterfly Valves
- Triple-Offset Butterfly Valves
- Others
- By Design
- Concentric
- Double Offset
- Triple Offset
- By Function
- On/Off (Isolation)
- Control
- Throttling
- By End-User Industry (Value)
- Oil and Gas
- Water and Wastewater
- Energy and Power
- Chemical
- Pharmaceutical
- Food and Beverage
- HVAC and Building Services
- Pulp and Paper
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- South Africa
- Egypt
- Rest of Africa
- Africa
- Brazil
- Argentina
- Rest of South America
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 39.50% of 2025 revenue, underpinned by China's CNY 13 billion (USD 1.8 billion) domestic market expanding at 5.86% CAGR. Chemical plants drive 25-30% of local demand, prompting Neway Valve to post 36.59% revenue growth in 2023. Shanghai Electric Power Valve Factory's CNY 1 billion (USD 0.14 billion) smart-factory build illustrates ongoing regional capacity scale-up. India accelerates refinery and potable-water schemes, while Japan channels stimulus into hydrogen distribution, where KITZ rolls out triple-offset lines.
The Middle East and Africa lead growth at 6.95% CAGR as mega-projects like EACOP and Tanzania LNG proceed to final investment decisions, each specifying hundreds of large-bore butterfly valves. Gulf states promote hydrogen export corridors, demanding 600-lb-rated triple-offset units that few suppliers can certify. Local-content mandates spur joint ventures, altering sourcing strategies across the butterfly valves market.
North America shows replacement-led momentum as shale development stabilizes and municipalities roll out USD 1 billion-plus water programs . The Inflation Reduction Act funnels incentives toward electrolyzer manufacturing, lifting domestic valve orders for green-hydrogen loops. Europe faces PFAS-related cost headwinds but offsets them with aggressive decarbonization grants that require high-performance hydrogen-ready equipment. South America's outlook hinges on commodity cycles; Brazil's pre-salt fields and Argentina's Vaca Muerta basin sustain baseline investment in flow-control hardware.
- Emerson Electric Co.
- Flowserve Corporation
- AVK Holding A/S
- Alfa Laval AB
- L & T Valves Limited
- Crane Co.
- Curtiss-Wright Corporation
- NIBCO Inc.
- Valmet Oyj
- XHVAL Valve Co., Ltd.
- Huamei Machinery Co., Ltd.
- Bray International, Inc.
- A-T Controls, Inc.
- Georg Fischer AG (GF Piping Systems)
- Belimo Holding AG
- Aalberts NV (Apollo Valves)
- Parker-Hannifin Corporation
- KSB SE and Co. KGaA
- SAMSON AG
- Dembla Valves Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Investments In Oil And Gas Refineries And Cross-Border Pipelines
- 4.2.2 Expansion Of Municipal And Industrial Water Wastewater Infrastructure
- 4.2.3 Demand For High-Performance Valves With Tight Shut-Off And High
- 4.2.4 Triple-Offset Valves Adopted In Green-Hydrogen Electrolyzers
- 4.2.5 IIoT-Enabled Smart Actuators Lowering Total Cost Of Ownership
- 4.2.6 Lightweight Thermoplastic Valves Supporting Decarbonised Utilities
- 4.3 Market Restraints
- 4.3.1 Cavitation/Choke Risk Under Low-Pressure Throttling
- 4.3.2 Price Commoditisation In Low-Spec Resilient Seated Valves
- 4.3.3 Volatile Supply And Cost Of Fluoropolymer Linings (PTFE/PFA)
- 4.3.4 Cyber-Security Concerns In Critical Assets Using IoT Actuators
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 High-Performance Butterfly Valves
- 5.1.2 Lined Butterfly Valves
- 5.1.3 Resilient-Seated Butterfly Valves
- 5.1.4 Triple-Offset Butterfly Valves
- 5.1.5 Others
- 5.2 By Design
- 5.2.1 Concentric
- 5.2.2 Double Offset
- 5.2.3 Triple Offset
- 5.3 By Function
- 5.3.1 On/Off (Isolation)
- 5.3.2 Control
- 5.3.3 Throttling
- 5.4 By End-User Industry (Value)
- 5.4.1 Oil and Gas
- 5.4.2 Water and Wastewater
- 5.4.3 Energy and Power
- 5.4.4 Chemical
- 5.4.5 Pharmaceutical
- 5.4.6 Food and Beverage
- 5.4.7 HVAC and Building Services
- 5.4.8 Pulp and Paper
- 5.4.9 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 South Africa
- 5.5.5.1.2 Egypt
- 5.5.5.1.3 Rest of Africa
- 5.5.5.2 Africa
- 5.5.5.2.1 Brazil
- 5.5.5.2.2 Argentina
- 5.5.5.2.3 Rest of South America
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Emerson Electric Co.
- 6.4.2 Flowserve Corporation
- 6.4.3 AVK Holding A/S
- 6.4.4 Alfa Laval AB
- 6.4.5 L & T Valves Limited
- 6.4.6 Crane Co.
- 6.4.7 Curtiss-Wright Corporation
- 6.4.8 NIBCO Inc.
- 6.4.9 Valmet Oyj
- 6.4.10 XHVAL Valve Co., Ltd.
- 6.4.11 Huamei Machinery Co., Ltd.
- 6.4.12 Bray International, Inc.
- 6.4.13 A-T Controls, Inc.
- 6.4.14 Georg Fischer AG (GF Piping Systems)
- 6.4.15 Belimo Holding AG
- 6.4.16 Aalberts NV (Apollo Valves)
- 6.4.17 Parker-Hannifin Corporation
- 6.4.18 KSB SE and Co. KGaA
- 6.4.19 SAMSON AG
- 6.4.20 Dembla Valves Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 彈性座蝶閥市場規模、佔有率和成長分析:按閥門類型、驅動方式、壓力等級、應用、最終用戶產業和地區分類 - 產業預測,2026-2033年
 鋁製蝶閥市場規模、佔有率和成長分析:按閥門類型、驅動方式、應用、最終用戶、尺寸和地區分類-2026-2033年產業預測
 蝶閥市場-2026-2032年全球市場預測
 工業蝶閥市場規模及預測(2021-2034),全球及區域佔有率、趨勢及成長機會分析報告:依閥瓣關閉類型、結構類型、等級及產業分類
 蝶閥市場規模、佔有率、趨勢和預測:按產品類型、材料類型、設計、功能、最終用途行業和地區分類,2026-2034年
 蝶閥全球市場規模、佔有率、趨勢和成長分析報告(2026-2034)襯裡蝶閥市場:按襯裡材質、閥門尺寸、閥體材質、最終用戶和應用分類-2026-2032年全球市場預測高性能蝶閥市場:按類型、連接方式、驅動方式、壓力等級、閥座材質、閥體材質、尺寸、應用及銷售管道分類-2026-2032年全球市場預測晶片式橡膠襯裡蝶閥市場:按端部連接類型、操作類型、閥門尺寸類別、額定壓力類別、襯裡材料類型和行業分類,全球預測,2026-2032年全球軟密封蝶閥市場規模、佔有率、趨勢及成長分析報告(2026-2034)