


 |
市場調查報告書
商品編碼
2116117
非洲跨境公路貨運:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Africa Cross Border Road Freight Transport - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
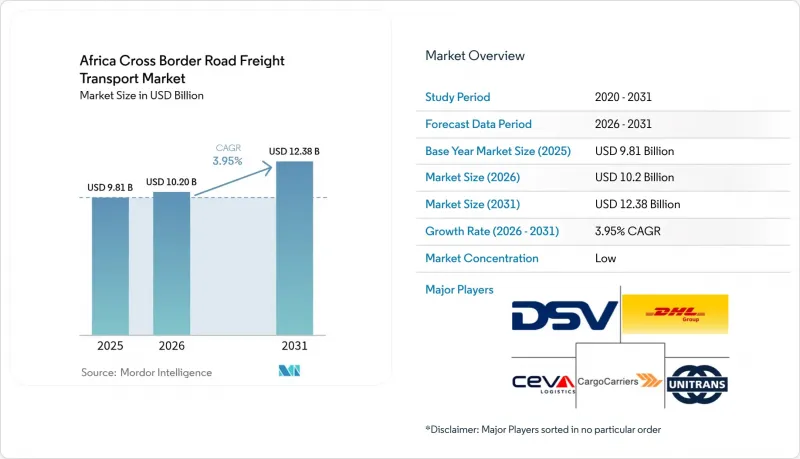
根據 Mordor Intelligence 預測,非洲跨境公路貨運市場規模預計將從 2025 年的 98.1 億美元成長到 2026 年的 102 億美元,然後從 2026 年到 2031 年以 3.95% 的複合年成長率成長,到 2031 年達到 123.8 億美元。
本報告按最終用戶行業(例如建設業)、卡車裝載規格(例如整車裝載)、容器化(例如貨櫃運輸)、運輸距離(長途運輸、短途運輸)、貨物類型(液體貨物、固體貨物)、溫度控制(例如溫控貨物)和地區進行細分。市場預測以美元計價。
非洲跨境公路貨運市場趨勢與洞見。
非洲大陸自由貿易區(AfCFTA)逐步降低關稅,正加速非洲內部的陸上貿易。
54個簽署國的關稅自由化降低了接收成本,並重振了走廊間的貨運。根據聯合國貿發會議2024年的基準調查,同時採用關稅減免和數位化單一窗口系統的國家,其貿易成長率比僅實施關稅減免的國家高出22%。東非共同體(EAC)成員國由於統一了軸重限制,因此受益最大;而奈及利亞引入的SIGMAT系統有望為西非最大的經濟體帶來類似的益處。遵守原產地規則增加了對集散中心的需求,並刺激了對邊境檢查站附近簡化海關手續的倉庫的投資。計劃於2027年實施的最後一輪關稅取消,正在支撐貨運需求,並鞏固非洲跨國公路貨運市場的強勁發展動能。
電子商務履約:快速跨境最後一公里配送的需求
預計到2029年,線上零售市場規模將達到560億美元,每個平台都需要能夠穿梭於多個海關管轄區且不犧牲配送速度的卡車司機。亞馬遜計畫於2024年進軍南非市場,這正是全球品牌將跨國配送時間縮短至2-3天的典型例證。像CloudFret這樣的新創公司已獲得新一輪融資,用於貨物匹配和單據處理的數位化,這表明投資者對能夠提高可靠性的技術表現出濃厚的興趣。國內支付系統(例如2024年在索馬利亞推出的系統)減少了對貨到付款的依賴,並最大限度地降低了退貨風險。隨著藥品和食品雜貨電子商務的擴張,低溫運輸的重要性日益凸顯,Quick International Courier正在投資建造溫控設施,以滿足嚴格的處理要求。
邊境口岸根深蒂固的貪腐與非正式收費
在繁忙的通道,邊境平均等待時間仍可能超過48小時。世界銀行2024年的通道審計報告指出,非正式收費是實現非洲大陸自由貿易區(AfCFTA)便利化目標的最大障礙。 ASYCUDA系統的引進已取得成效,在岡比亞的全面實施使海關收入增加了23%,現金收取量減少。然而,由於電力和網路基礎設施的匱乏,一些檢查站仍然採用人工操作,尋租現象仍然存在。一站式邊境檢查站是一項很有前景的舉措——2024年,在姆瓦米/姆欽吉,一站式檢查站將處理時間縮短了60%——但仍需擴大區域同行評審機制,以消除根深蒂固的弊端。
細分市場分析
到2025年,批發和零售貿易將佔總收入的29.12%,成為成長最快的行業,複合年成長率達4.62%,這表明該領域對貿易量和創新都產生了顯著影響。高頻電子商務貨運正在加速對精準、溫控都市區配送的需求,促使承運商整合即時追蹤和靈活路線規劃。隨著區域價值鏈的成熟,製造業正在成長,尤其是在摩洛哥、南非和衣索比亞的汽車產業叢集。受關鍵礦產需求的推動,礦產出口正在復甦,連接剛果民主共和國和尚比亞銅礦帶和沿海港口的整車運輸專線正在擴大。在農業領域,數位植物檢疫證明書的引入降低了拒收率,並顯著提高了運輸噸位。同時,建築材料運輸量反映了與走廊相關的蓬勃發展的基礎設施建設。藥品和電子產品的物流被歸類為“其他”,對嚴格合規和安全處理服務的要求較高。
由於整車運輸 (FTL) 具有安全優勢且適合運輸大量礦產,其市佔率佔比高達 52.78%。同時,由於技術平台簡化了貨物拼裝和單據流程,預計到 2031 年,零擔運輸 (LTL) 的複合年成長率將達到 4.05%。 Kobo360 模式結合了燃油融資和預測性維護,使零擔運輸成為一種可行的選擇,即使對於那些以前以非正式方式運輸貨物的中小型企業而言也是如此。因此,非洲跨境公路貨運市場正朝著成熟地區常見的網路化模式發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 非洲大陸自由貿易區(AfCFTA)逐步降低關稅,正加速非洲內部的陸上貿易。
- 電子商務履約對快速跨境最後一公里配送的需求
- 汽車和快速消費品製造業中新興的區域價值鏈
- 促進基礎設施資金籌措的多邊走廊計劃
- 數位貨運匹配平台正在降低空車回程運費。
- 礦業主導的「重要礦產走廊」項目
- 市場限制因素
- 邊境口岸根深蒂固的貪腐與非正式收費
- 各國國內航運和軸載法規存在差異
- 在區域避險措施不足的情況下,柴油價格波動劇烈。
- 天氣因素導致南北主要幹道道路受損
- 價值供應鏈分析
- 監管環境(政府法規、貿易協定、計劃)
- 技術展望
- 跨境電子商務洞察
- 主要交通走廊分析
- 製造地和經濟特區
- 波特五力模型
- 新冠疫情與地緣政治事件的影響
第5章 市場規模與成長預測
- 按最終用戶行業分類
- 農業、漁業、林業
- 建造
- 製造業
- 石油和天然氣、採礦和採石
- 批發和零售
- 其他
- 按規格分類的卡車負載容量
- 全軌道公路(FTL)
- 小批量貨物(零擔)
- 透過容器化
- 容器化
- 容器化
- 按距離
- 長途
- 短距離
- 合適的配置
- 流體產品
- 固體產品
- 按類型進行溫度控制
- 無溫度控制
- 溫度控制
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- DSV
- DHL Group
- Unitrans Supply Chain Solutions
- CEVA Logistics
- Cargo Carriers
- Value Logistics
- Rhenus Logistics
- Super Group
- Bidvest Freight
- Grindrod Logistics
- Kuehne+Nagel
- OML Africa Logistics
- Megafreight Services Pty(Ltd)
- BAC Logistics
- Rangel Logistics Solutions
- Unidel Carriers
- OneLogix Cargo Solutions
- Atrax Logistics
- RDM Logistics
- Aeromarine Capital
第7章 市場機會與未來展望
According to Mordor Intelligence, the Africa cross border road freight transport market size is expected to grow from USD 9.81 billion in 2025 to USD 10.2 billion in 2026 and is forecast to reach USD 12.38 billion by 2031 at 3.95% CAGR over 2026-2031.
This report is Segmented by End User Industry (Construction, and More), Truckload Specification (Full-Truck-Load, and More), Containerization (Containerized, and More), Distance (Long-Haul, Short-Haul), Good Configuration (Fluid Goods, Solid Goods), Temperature Control (Temperature Controlled, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Africa Cross Border Road Freight Transport Market Trends and Insights
AfCFTA Tariff Phase-Down Accelerates Intra-African Over-the-Road Trade
Tariff liberalization across 54 signatory states is lowering landed costs and stimulating corridor traffic. UNCTAD's 2024 benchmarking shows countries that pair tariff cuts with digital single-window systems record 22% higher trade growth than those applying tariff relief alone. East African Community (EAC) members with harmonized axle-load limits capture outsized benefits, while Nigeria's SIGMAT rollout positions West Africa's largest economy for similar gains. Rules-of-origin compliance drives up demand for consolidation hubs, catalyzing investment in documentation-ready warehouses near border posts. The final tariff dismantling round scheduled for 2027 sustains freight demand, embedding a positive trajectory for the Africa Cross-Border Road Freight Transport market.
E-commerce Fulfilment Demand for Fast Cross-Border Last-Mile
Online retail is forecast to reach USD 56 billion by 2029, and platforms require truck operators capable of clearing multiple customs jurisdictions without sacrificing delivery speed. Amazon's 2024 South Africa entry exemplifies how global brands re-shape freight expectations toward two- to three-day cross-border delivery windows. Start-ups such as CloudFret secured fresh capital to digitize load matching and paperwork, evidence of investor appetite for technology that improves reliability. National payment switches like Somalia's 2024 launch reduce cash-on-delivery dependencies and shrink reversal risk. Cold chain capability gains prominence as pharmaceutical and grocery e-commerce expand, with Quick International Courier investing in temperature-controlled assets to meet stringent handling requirements.
Persistent Border-Post Corruption and Informal Fees
Average border dwell times can still exceed 48 hours on high-traffic corridors. The World Bank's 2024 corridor audit names informal fees as the chief impediment to AfCFTA facilitation targets. ASYCUDA installations help; Gambia's full rollout drove a 23% customs revenue jump and curbed cash-based collections. Yet electricity and internet gaps keep several posts manual, perpetuating rent-seeking. One-Stop Border Posts show promise-Mwami/Mchinji cut processing times 60% in 2024but regional peer-review mechanisms must scale to neutralize entrenched practices.
Other drivers and restraints analyzed in the detailed report include:
- Emerging Regional Value Chains in Automotive & FMCG Manufacturing
- Multilateral Corridor Programs Unlock Infrastructure Finance
- Cabotage and Axle-Load Policy Fragmentation by Country
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wholesale and Retail Trade makes up 29.12% of 2025 revenue and is the fastest-growing slice at 4.62% CAGR, signaling the segment's dual influence over volume and innovation. High-frequency e-commerce shipments accelerate demand for precise, temperature-controlled urban deliveries, prompting carriers to integrate real-time tracking and flexible routing. Manufacturing follows as regional value chains mature, especially in automotive clusters across Morocco, South Africa, and Ethiopia. Mineral exports rally on critical-minerals demand, pushing dedicated FTL lanes between the DRC-Zambia copper belt and coastal ports. Agriculture tallies sizeable tons as digital phytosanitary certification trims rejection rates, while construction freight mirrors corridor-linked infrastructure booms. Pharmaceutical and electronics flows sit in the "Others" bucket, bringing stringent compliance and secure-handling service premiums.
Full-Truck-Load holds 52.78% share, favored for security and bulk minerals. Yet Less-than-Truck-Load posts a 4.05% CAGR to 2031 as tech platforms simplify load aggregation and documentation. Kobo360's model, which bundles fuel financing and predictive maintenance, makes LTL viable for SMEs whose freight once moved informally. The Africa Cross-Border Road Freight Transport market is, therefore, drawing nearer to network-based models common in more mature geographies.
Complete Report Scope:
- By End User Industry
- Agriculture, Fishing, and Forestry
- Construction
- Manufacturing
- Oil and Gas, Mining and Quarrying
- Wholesale and Retail Trade
- Others
- By Truckload Specification
- Full-Truck-Load (FTL)
- Less-than-Truck-Load (LTL)
- By Containerization
- Containerized
- Non-Containerized
- By Distance
- Long-Haul
- Short-Haul
- By Good Configuration
- Fluid Goods
- Solid Goods
- By Temperature Control
- Non-Temperature Controlled
- Temperature Controlled
List of Companies Covered in this Report:
- DSV
- DHL Group
- Unitrans Supply Chain Solutions
- CEVA Logistics
- Cargo Carriers
- Value Logistics
- Rhenus Logistics
- Super Group
- Bidvest Freight
- Grindrod Logistics
- Kuehne + Nagel
- OML Africa Logistics
- Megafreight Services Pty (Ltd)
- BAC Logistics
- Rangel Logistics Solutions
- Unidel Carriers
- OneLogix Cargo Solutions
- Atrax Logistics
- RDM Logistics
- Aeromarine Capital
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AfCFTA tariff phase-down accelerates intra-African over-the-road trade
- 4.2.2 E-commerce fulfilment demand for fast cross-border last-mile
- 4.2.3 Emerging regional value chains in automotive and FMCG manufacturing
- 4.2.4 Multilateral corridor programmes unlocking infrastructure finance
- 4.2.5 Digital freight-matching platforms cutting empty-backhaul rates
- 4.2.6 Mining-led "critical-minerals corridor" projects
- 4.3 Market Restraints
- 4.3.1 Persistent border-post corruption and informal fees
- 4.3.2 Cabotage and axle-load policy fragmentation by country
- 4.3.3 Diesel price volatility with weak regional hedging instruments
- 4.3.4 Climate-driven road-surface failures on key north-south arterials
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape (Govt. Regulations, Trade Agreements, Initiatives)
- 4.6 Technological Outlook
- 4.7 Cross-Border E-commerce Insights
- 4.8 Key Transport Corridors Analysis
- 4.9 Manufacturing Hubs and Special Economic Zones (SEZs)
- 4.10 Porter's Five Forces
- 4.10.1 Supplier Power
- 4.10.2 Buyer Power
- 4.10.3 Threat of New Entrants
- 4.10.4 Threat of Substitutes (Rail, Coastal Ro-Ro)
- 4.10.5 Competitive Rivalry
- 4.11 Impact of COVID-19 and Geopolitical Events
5 Market Size and Growth Forecasts (Value)
- 5.1 By End User Industry
- 5.1.1 Agriculture, Fishing, and Forestry
- 5.1.2 Construction
- 5.1.3 Manufacturing
- 5.1.4 Oil and Gas, Mining and Quarrying
- 5.1.5 Wholesale and Retail Trade
- 5.1.6 Others
- 5.2 By Truckload Specification
- 5.2.1 Full-Truck-Load (FTL)
- 5.2.2 Less-than-Truck-Load (LTL)
- 5.3 By Containerization
- 5.3.1 Containerized
- 5.3.2 Non-Containerized
- 5.4 By Distance
- 5.4.1 Long-Haul
- 5.4.2 Short-Haul
- 5.5 By Good Configuration
- 5.5.1 Fluid Goods
- 5.5.2 Solid Goods
- 5.6 By Temperature Control
- 5.6.1 Non-Temperature Controlled
- 5.6.2 Temperature Controlled
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DSV
- 6.4.2 DHL Group
- 6.4.3 Unitrans Supply Chain Solutions
- 6.4.4 CEVA Logistics
- 6.4.5 Cargo Carriers
- 6.4.6 Value Logistics
- 6.4.7 Rhenus Logistics
- 6.4.8 Super Group
- 6.4.9 Bidvest Freight
- 6.4.10 Grindrod Logistics
- 6.4.11 Kuehne + Nagel
- 6.4.12 OML Africa Logistics
- 6.4.13 Megafreight Services Pty (Ltd)
- 6.4.14 BAC Logistics
- 6.4.15 Rangel Logistics Solutions
- 6.4.16 Unidel Carriers
- 6.4.17 OneLogix Cargo Solutions
- 6.4.18 Atrax Logistics
- 6.4.19 RDM Logistics
- 6.4.20 Aeromarine Capital
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 離岸供應鏈市場規模、佔有率和成長分析:按服務類型、產業、運輸方式、最終用戶、部署類型和地區分類-2026-2033年產業預測
 多式聯運市場預測(2034 年)—按解決方案類型、運輸方式、部署模式、技術、最終用戶和區域分類的全球分析
 多式聯運市場:依服務、運輸方式、貨物類型、貨運量及最終用戶產業分類-2026-2032年全球市場預測2034年線下交通樞紐市場預測-按樞紐類型、服務內容、所有權/營運模式、最終用戶和區域分類的全球分析
 多式聯運市場報告:按組成部分、運輸方式、最終用戶和地區分類(2026-2034 年)
 2026年全球多式聯運貨運市場報告
 2026-2030年全球多式聯運貨運市場日本貨運市場規模、佔有率、趨勢及預測(按交付類型、運輸方式、最終用途和地區分類),2026-2034年按貨物類型、港口類型、所有權類型、服務類型和應用分類的航運和港口市場 - 2026-2032 年全球預測
 多式聯運:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)