


 |
市場調查報告書
商品編碼
2115919
北美和南美聚丙烯(PP)薄膜:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Americas Polypropylene (PP) Films - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
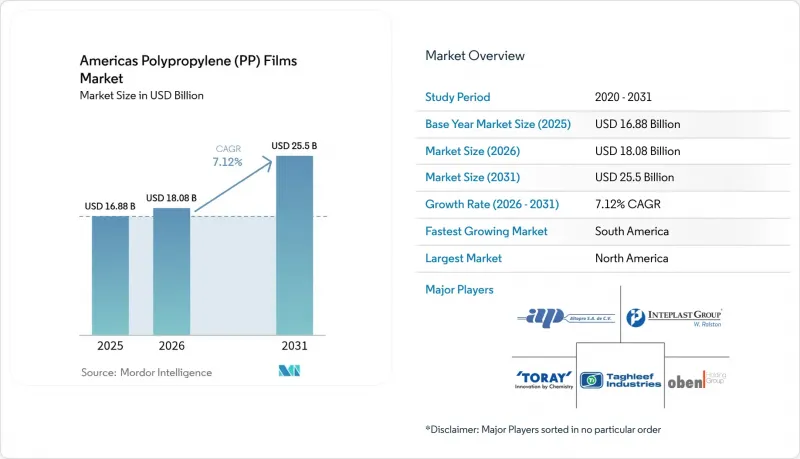
根據 Mordor Intelligence 預測,美洲聚丙烯 (PP) 薄膜市場規模預計將從 2025 年的 168.8 億美元成長到 2026 年的 180.8 億美元,然後從 2026 年到 2031 年以 7.12% 的複合年成長率成長,達到 2031 億美元。
本報告按類型(BOPP、CPP、SPP 等)、厚度(小於 20 微米、20-40 微米、大於 40 微米)、終端用戶行業(食品、飲料、醫藥/醫療、工業等)、應用(包裝、標籤/膠帶、覆膜、圖形覆膜等)和地區進行細分。市場預測以美元計價。
北美和南美聚丙烯(PP)薄膜市場的趨勢和見解。
快速轉向單一材料軟性包裝解決方案
品牌所有者正將多層複合材料整合為單一聚合物形式,以實現可回收性設計目標並避免與生產者延伸責任制 (EPR) 相關的成本。 2024 年,Coveris 和 Borealis 推出了一款符合跌落測試標準的單層聚丙烯寵物食品包裝袋,該包裝袋無需聚乙烯封口層。 Boruge 和 Siegwerk 推出了相容的油墨和黏合劑系統,在保持再生材料純度的同時,實現了每 15 毫米超過 2 牛頓的剝離強度。弗勞恩霍夫研究所的研究表明,複合材料在經過三次機械循環後仍能保持 85% 的拉伸強度,而聚對苯二甲酸乙二醇酯 (PET) 共混物僅為 60%。加州將於 2024 年生效的法規規定,到 2032 年,一次性包裝中必須含有 25% 的消費後再生材料,這將加速這些單一結構材料的普及。這些進步使得美洲的聚丙烯薄膜市場成為閉合迴路包裝專案的理想平台。
透過電子商務拓展生鮮食品配送網路
食材自煮包和線上雜貨服務正在擴展低溫運輸樞紐,這些樞紐更傾向於使用輕便、防穿刺的包裝袋。金屬化澆鑄聚丙烯的防潮性能優於 1 g m⁻² day⁻¹,這對於控制冷藏轉運環境中的冷凝至關重要。軟質包裝可減輕 40% 的運輸重量,並提高 25% 的裝載效率,從而降低人口密集城市的配送成本。 UFlex運作一條年產能 18,000 噸的生產線,為其美國履約中心快速供應客製化印刷產品。可重複使用的拉鍊和吸嘴貼合加工在單一材料薄膜上,既提升了消費者的便利性,又不影響其可回收性。隨著食品訂閱服務的蓬勃發展,這些特性正在推動美洲地區聚丙烯平方公尺市場需求的成長。
丙烯原料價格波動與頁岩氣趨勢有關。
2024年,亨利樞紐的現貨價格跌至每百萬英熱單位2.27美元,但由於墨西哥灣沿岸地區意外停產,價格飆升15%,推高了丙烯基準價格,使簽訂固定價格薄膜合約的加工商陷入困境。英力士公司在2024年初因壓縮機故障宣布不可抗力,2025年1月,其蒸汽裂解裝置又因冬季暴風雪「恩佐」的影響而暫時停產。依賴美國化學品出口的拉丁美洲擠出商不得不支付進口溢價,導致價差收窄。由於樹脂佔成品薄膜成本的55%至65%,價格波動可能會阻礙資本密集的阻隔塗層升級,並在短期內減緩美洲聚丙烯薄膜市場的成長。
細分市場分析
到2025年,雙向拉伸聚丙烯將佔總銷售量的64.78%,憑藉其高拉伸強度和光澤度,為美洲聚丙烯薄膜市場提供支撐,適用於零食、標籤和膠帶等應用。製造商透過在機械方向和橫向拉伸熔融片材,將彈性模量提高到3 GPa以上,從而在不影響抗穿刺性的前提下,實現15微米的厚度減薄。加工商採用二氧化矽塗層,以達到烘焙咖啡所需的氧氣透過率目標(低於1 cc m⁻² day⁻¹),取代聚對苯二甲酸乙二醇酯(PET)結構。隨著藥品泡殼包裝生產線從聚氯乙烯(PVC)轉向聚丙烯(CPP)以符合萃取物法規,以及無菌包裝袋需要更強的密封強度,預計流延聚丙烯將以8.18%的複合年成長率成長。巴西加工商已向南方共同市場成員國的製藥商訂購了 2024 年 Widecast 生產線,這表明 CPP 在北美和南美聚丙烯薄膜市場中日益成長的戰略重要性。
墨西哥、阿根廷和美國的產能快速擴張緩解了CPP長期供不應求的問題,但BOPP仍然是標籤、重疊包裝和透明零食包裝等大規模生產的主要材料。 Vitopel公司2024年擴大的金屬化BOPP產能縮短了對濕度敏感的咖啡包裝袋的前置作業時間。同時,北美加工商已對含有30%再生材料的BOPP合格,以滿足其品牌的永續發展目標。電容器薄膜和全像覆膜等小眾產品由於對厚度公差和介電純度要求高而享有較高的利潤率,但即使加起來,它們在美洲聚丙烯薄膜市場的佔有率也不足2%。
由於其高剛性雙軸拉伸性能,厚度小於20微米的薄膜實現了9.05%的複合年成長率,這使得品牌商能夠在保持抗穿刺性能的同時減少樹脂用量。 12微米的阻隔塗層薄膜與40微米的未塗層薄膜具有相同的氧氣阻隔性能,從而減少40%的材料用量。到2025年,20-40微米厚度範圍的薄膜將佔據52.05%的市場佔有率,並且是藥品泡殼熱成型、高耐久性工業包裝以及泡沫填充密封(FFS)袋等需要一定厚度以確保密封完整性的應用的首選厚度範圍。許多泡殼生產線是針對25微米厚度的薄膜設計的,而維修以適應更薄的厚度則需要新的加熱板和冷卻架,加工商通常會推遲這些改造。
厚度在40微米及以上的聚丙烯薄膜,在需要高剛性的冷凍袋領域與拉伸聚乙烯展開競爭,在透明蒸餾蓋領域則與聚對苯二甲酸乙二醇酯(PET)競爭。儘管該領域的成長正在放緩,但美洲地區對厚聚丙烯薄膜的需求依然強勁,尤其是在建築包裝和合成紙標籤領域,這些領域更注重抗撕裂性和防潮性而非重量。預計咖啡和零嘴零食包裝將轉向15微米塗層薄膜,這將繼續對中等重量薄膜的生產構成壓力,迫使生產商投資超薄拉幅機和高功率捲繞系統。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 快速轉向單一材料軟性包裝解決方案
- 擴大生鮮食品線上配送網路
- 永續包裝領域對高阻隔薄膜的需求不斷成長
- 在藥品泡殼包裝中以聚丙烯薄膜取代PVC和PET
- 拉丁美洲的加工商投資建造先進的雙軸拉伸生產線。
- 快餐店擴大採用可回收透明包裝材料
- 市場限制因素
- 丙烯原料價格波動與頁岩氣趨勢有關。
- 美國主要州對一次性塑膠製品實施嚴格監管
- 區域工廠停工導致供應鏈中斷
- 來自新興生物基和可生物分解薄膜替代品的競爭
- 產業價值鏈分析
- 監理情勢
- 宏觀經濟因素對市場的影響
- 技術展望
- 波特五力分析
- 投資分析
第5章:預測市場規模與成長率
- 按類型
- 雙軸延伸聚丙烯(BOPP)薄膜
- 未取向聚丙烯(CPP)薄膜
- 收縮聚丙烯(SPP)薄膜
- 其他類型
- 按厚度
- 小於20微米
- 20-40微米
- 40微米或以上
- 按最終用戶行業分類
- 食物
- 飲料
- 藥品和醫療保健
- 產業
- 個人護理和化妝品
- 其他終端用戶產業
- 透過使用
- 包裝
- 標籤和膠帶
- 層壓木材
- 圖形疊加
- 其他用途
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Taghleef Industries LLC
- Toray Plastics(America), Inc.
- Jindal Films Americas LLC
- Oben Holding Group SA
- Cosmo Films Ltd.
- Inteplast Group Corporation
- Amcor plc
- CCL Industries Inc.(Innovia Films)
- Uflex Limited
- Sigma Plastics Group
- Vitopel Group
- Profol Inc.
- Treofan Americas
- Altopro SA de CV
- Copol International Ltd.
- Poligal SA
- Cheever Specialty Paper and Film
- Polibak Plastic Film Industry Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the Americas polypropylene films market size is expected to grow from USD 16.88 billion in 2025 to USD 18.08 billion in 2026 and is forecast to reach USD 25.5 billion by 2031 at 7.12% CAGR over 2026-2031.
This report is Segmented by Type (BOPP, CPP, SPP, and More), Thickness (Below 20 Microns, 20-40 Microns, Above 40 Microns), End-User Industry (Food, Beverage, Pharmaceuticals and Medical, Industrial, and More), Application (Packaging, Labelling and Tapes, Laminations, Graphics and Overlays, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Americas Polypropylene (PP) Films Market Trends and Insights
Rapid Shift Toward Mono-Material Flexible Packaging Solutions
Brand owners are collapsing multilayer laminates into single-polymer formats to meet design-for-recycling targets and avoid extended producer responsibility fees. Coveris and Borealis commercialized a mono-polypropylene pet-food pouch in 2024 that eliminates polyethylene tie layers and still passes drop-test protocols. Borouge and Siegwerk have released a compatible ink-adhesive system that delivers peel strengths of above 2 N per 15 mm while preserving the purity of the recycling stream. Fraunhofer research shows that laminates retain 85% of their tensile strength after three mechanical cycles, compared to 60% for polyethylene terephthalate blends. California regulations, effective in 2024, require 25% post-consumer content in single-use packaging by 2032, accelerating the adoption of these mono-structures. Together, these advances make the Americas polypropylene films market a preferred platform for closed-loop packaging programs.
Expansion of E-commerce Fresh Food Delivery Networks
Meal-kit and online grocery services are scaling cold-chain hubs that favor lightweight, puncture-resistant pouches. Metallized cast polypropylene delivers moisture barriers below 1 g m-2 day-1, crucial for condensation control in refrigerated cross-docks. Flexible packs reduce shipping weight by 40% and cube utilization by 25%, trimming courier costs in dense cities. UFlex brought an 18,000 tpa line online in Mexico in H2 FY 2025 to supply U.S. fulfillment centers with rapid-turnaround custom prints. Reclosable zippers and fitment spouts laminated onto mono-material webs add consumer convenience without compromising recyclability. As subscription grocery penetration climbs, that functionality propels incremental square-meter demand in the Americas polypropylene films market.
Volatile Propylene Feedstock Prices Linked to Shale Gas Dynamics
Henry Hub spot prices fell to USD 2.27 per MMBtu in 2024 but spiked 15% during unplanned Gulf Coast outages, sending propylene references higher and squeezing converters locked into fixed-price film contracts. INEOS declared force majeure in early 2024 after a compressor failure, while Winter Storm Enzo temporarily idled steam crackers in January 2025. Latin American extruders reliant on U.S. chemical exports paid import premiums that compressed spreads. Because resin accounts for 55-65% of finished-film cost, volatility discourages capital-intensive barrier-coating upgrades and can slow the Americas polypropylene films market in the short term.
Other drivers and restraints analyzed in the detailed report include:
- Increased Demand for High-Barrier Films in Sustainable Packaging
- Replacement of PVC and PET with Polypropylene Films in Pharmaceutical Blister Packs
- Stringent Single-Use Plastic Regulations in Major U.S. States
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biaxially oriented grades retained 64.78% of 2025 volume, anchoring the Americas polypropylene films market with strong tensile strength and high gloss that suit snack, label, and tape applications. Producers stretch molten sheet in both machine and transverse directions, boosting modulus above 3 GPa and enabling 15 micron downgauging without puncture compromise. Converters overlay silicon-oxide to meet sub-1 cc m-2 day-1 oxygen targets for roasted coffee, displacing polyethylene terephthalate structures. Cast polypropylene is projected to grow at an 8.18% CAGR as pharmaceutical blister lines transition from polyvinyl chloride to comply with extractables rules and as aseptic pouches demand stronger seal integrity. Brazilian converters ordered wide-cast lines in 2024 to serve Mercosur drug makers, underscoring CPP's rising strategic weight in the Americas polypropylene films market.
Rapid output additions in Mexico, Argentina, and the United States ease historic CPP shortfalls, yet BOPP remains the scale workhorse for labels, overwraps, and transparent snacks. Vitopel's metallized BOPP capacity jump in 2024 lowered lead times for moisture-sensitive coffee bags, while North American converters qualified 30% recycled-content BOPP to meet brand sustainability targets. Niche oriented grades, such as capacitor films and holographic overlays, enjoy premium margins thanks to tight thickness tolerance and dielectric purity, but they combined represent less than 2% of Americas polypropylene films market share.
Films under 20 microns post a 9.05% CAGR because high-stiffness biaxial orientation enables brand owners to reduce resin mass while maintaining puncture resistance. Barrier-coated 12-micron webs deliver the same oxygen protection as 40-micron uncoated films, unlocking 40% material savings. The 20-40 micron slot held 52.05% share in 2025, favored for pharmaceutical blister thermoforming, heavy-duty industrial wraps, and form-fill-seal pouches that need caliper for seal integrity. Many blister lines are calibrated for 25-micron webs, and retrofitting for thinner gauges requires new heater plates and cooling racks that converters often defer.
Above 40 microns, polypropylene competes with oriented polyethylene for stiff freezer bags and with polyethylene terephthalate for transparent retort lids. Growth here is muted, yet the Americas polypropylene films market size for thick gauges holds steady because construction wraps and synthetic paper labels value tear and moisture resistance over weight. The anticipated migration of coffee and snack packs to 15-micron coated webs will continue to put pressure on mid-gauge output, prompting producers to invest in ultra-thin tenter frames and high-output winding systems.
Complete Report Scope:
- By Type
- Biaxially Oriented Polypropylene (BOPP) Films
- Cast Polypropylene (CPP) Films
- Shrink Polypropylene (SPP) Films
- Other Types
- By Thickness
- Below 20 Microns
- 20 - 40 Microns
- Above 40 Microns
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Medical
- Industrial
- Personal Care and Cosmetics
- Other End-User Industries
- By Application
- Packaging
- Labelling and Tapes
- Laminations
- Graphics and Overlays
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- North America
List of Companies Covered in this Report:
- Taghleef Industries LLC
- Toray Plastics (America), Inc.
- Jindal Films Americas LLC
- Oben Holding Group S.A.
- Cosmo Films Ltd.
- Inteplast Group Corporation
- Amcor plc
- CCL Industries Inc. (Innovia Films)
- Uflex Limited
- Sigma Plastics Group
- Vitopel Group
- Profol Inc.
- Treofan Americas
- Altopro S.A. de C.V.
- Copol International Ltd.
- Poligal S.A.
- Cheever Specialty Paper and Film
- Polibak Plastic Film Industry Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Shift Toward Mono-Material Flexible Packaging Solutions
- 4.2.2 Expansion of E-commerce Fresh Food Delivery Networks
- 4.2.3 Increased Demand for High-Barrier Films in Sustainable Packaging
- 4.2.4 Replacement of PVC and PET with Polypropylene Films in Pharmaceutical Blister Packs
- 4.2.5 Investment in Advanced Biaxially Oriented Lines by Latin American Converters
- 4.2.6 Rising Adoption of Recyclable Transparent Wraps by Quick-Service Restaurants
- 4.3 Market Restraints
- 4.3.1 Volatile Propylene Feedstock Prices Linked to Shale Gas Dynamics
- 4.3.2 Stringent Single-Use Plastic Regulations in Major U.S. States
- 4.3.3 Supply Chain Disruptions from Regional Plant Outages
- 4.3.4 Competition from Emerging Bio-Based and Biodegradable Film Alternatives
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors on the Market
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Biaxially Oriented Polypropylene (BOPP) Films
- 5.1.2 Cast Polypropylene (CPP) Films
- 5.1.3 Shrink Polypropylene (SPP) Films
- 5.1.4 Other Types
- 5.2 By Thickness
- 5.2.1 Below 20 Microns
- 5.2.2 20 - 40 Microns
- 5.2.3 Above 40 Microns
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Pharmaceuticals and Medical
- 5.3.4 Industrial
- 5.3.5 Personal Care and Cosmetics
- 5.3.6 Other End-User Industries
- 5.4 By Application
- 5.4.1 Packaging
- 5.4.2 Labelling and Tapes
- 5.4.3 Laminations
- 5.4.4 Graphics and Overlays
- 5.4.5 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Taghleef Industries LLC
- 6.4.2 Toray Plastics (America), Inc.
- 6.4.3 Jindal Films Americas LLC
- 6.4.4 Oben Holding Group S.A.
- 6.4.5 Cosmo Films Ltd.
- 6.4.6 Inteplast Group Corporation
- 6.4.7 Amcor plc
- 6.4.8 CCL Industries Inc. (Innovia Films)
- 6.4.9 Uflex Limited
- 6.4.10 Sigma Plastics Group
- 6.4.11 Vitopel Group
- 6.4.12 Profol Inc.
- 6.4.13 Treofan Americas
- 6.4.14 Altopro S.A. de C.V.
- 6.4.15 Copol International Ltd.
- 6.4.16 Poligal S.A.
- 6.4.17 Cheever Specialty Paper and Film
- 6.4.18 Polibak Plastic Film Industry Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球電容器以雙向拉伸聚丙烯薄膜市場研究報告(2026版)
 平版印刷標籤市場規模、佔有率和成長分析:按標籤類型、材料、印刷製程、最終用途產業和地區分類-2026-2033年產業預測
 雙向拉伸聚丙烯(BOPP)介電薄膜市場分析與預測(至2035年):類型、產品、技術、應用、材料類型、最終用戶、功能、安裝類型、設備雙向拉伸聚酯薄膜(BOPET)市場分析及預測(至2035年):類型、產品、技術、應用、材料類型、過程、最終用戶、功能
 BOPA薄膜市場報告:趨勢、預測與競爭分析(至2035年)
 雙向拉伸聚丙烯(BOPP)和雙向拉伸聚酯薄膜(BOPET)市場-2026-2032年全球市場預測無鹵阻燃雙向拉伸聚酯薄膜市場-2026-2032年全球市場預測
 2026年全球可回收雙軸延伸聚丙烯(BOPP)包裝袋市場報告聚酯薄膜市場:2026-2032年全球市場預測(依產品類型、形狀、厚度、塗層和應用分類)電容器金屬化薄膜市場報告:趨勢、預測與競爭分析(至2035年)