


 |
市場調查報告書
商品編碼
2115904
臨時發電:市佔率分析、產業趨勢及統計、成長預測(2026-2031 年)Temporary Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
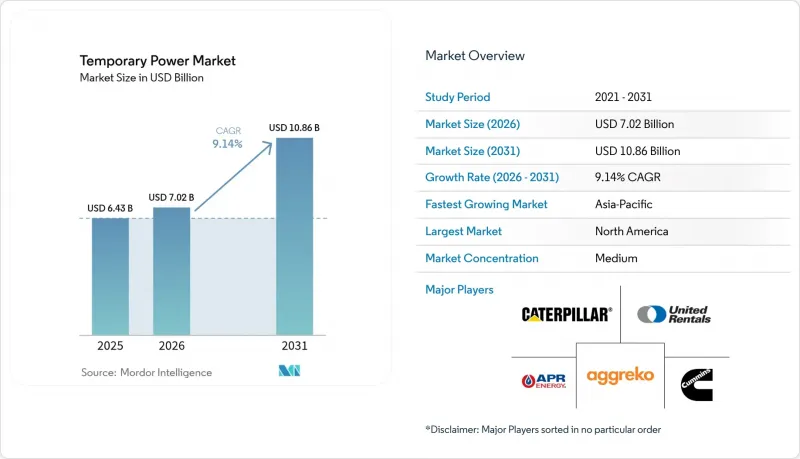
據 Mordor Intelligence 稱,臨時電源(備用電源)市場規模預計在 2026 年達到 70.2 億美元,高於 2025 年的 64.3 億美元,預計到 2031 年將達到 108.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 9.14%。
本報告按燃料類型(柴油、天然氣、混合動力/其他)、額定功率(50 千瓦以下、501-2,000 千瓦、2,000 千瓦以上、其他)、應用(基本負載/連續運行、電網支援/停電、其他)、最終用戶產業(公用事業/電力、石油/細胞分類、資料中心/中東(天然氣/歐洲地區)。
全球臨時電力市場趨勢及洞察
極端天氣導致停電頻率增加
颶風、熱浪、野火和季風引發的洪水導致電網中斷時間延長、頻率增加,每次災害過後,緊急發電機租賃需求都會激增。公共產業和地方政府現在會在風暴季節到來之前預先部署租賃設備,以便供應商重新分配資產並最佳化定價。保險公司也越來越要求醫院、通訊中心和低溫運輸倉庫配備現場備用電源。這些合約保障措施正在將曾經零星的災害相關收入轉變為可預測的季節性需求。隨著氣候變遷加劇,緊急電力服務正成為北美和歐洲各地韌性預算中的常設項目。
新興市場的工業化和建築業蓬勃發展
印度、印尼和海灣合作理事會(GCC)國家規劃的大型企劃需要大容量發電機組,以便在電網中斷或不穩定時為運作、混凝土攪拌站和排水泵供電。雖然當地租賃公司通常提供500千瓦或以下的機組,但跨國承包商現在更傾向於1兆瓦或以上的機組,以降低每千瓦的物流成本。這種規模的轉變使得全球車隊能夠在短時間內交付容器化發電設備。政府對公路、港口和工業走廊的獎勵策略進一步擴大了用戶群體,並支持簽訂長期多年契約,而不是一次性租賃。
更嚴格的全球和區域性發電廠排放標準
歐盟第五階段排放標準強制要求功率在19至560千瓦之間的引擎安裝顆粒物過濾器。印度即將實施的CPCB IV+標準將把適用範圍擴大到800千瓦機組,而加州正在製定提案,預計該標準將比歐盟標準更為嚴格。隨著排放標準的日益收緊,租賃公司的投資報酬率(ROIC)不斷下降,因為資本成本上升,老舊設備的殘值也隨之降低。此外,城市管理部門正在設立低排放氣體區,限制運作時間,從而限制了傳統柴油發電機在大型城市計畫中的使用。雖然可以透過更清潔的技術來彌補銷售量損失,但這種轉型需要資金投入和技術再培訓。
細分市場分析
預計到2025年,柴油發電機組將佔總銷售量的69.85%,這反映出它們在災害救援和離網項目中仍然發揮著重要作用,因為它們擁有廣泛的服務基礎設施、高能量密度和快速響應能力。然而,臨時電力市場正在向混合模式轉型,這種模式結合了太陽能電池陣列、電池組或丙烷引擎,預計到2031年,該類別將以15.05%的年均成長率成長。由Aggreco公司建造的馬丁縣微電網以五台1.3兆瓦的燃氣發電機為核心,展現了在油田作業中推廣清潔燃料的巨大潛力。採用電動挖土機的建設公司也增加了對低噪音太陽能和電池供電發電機的需求,這表明設備電氣化正在臨時電力產業蔓延。隨著成本曲線的下降,混合方案正從試點部署轉向核心租賃服務,歐洲和北美正在重新審視其採購規範。
到2025年,501-2000千瓦頻寬的設備將佔總銷售額的32.35%,主要用於工業流程和大規模建築工地,在這些場所,便攜性與容量同樣重要。預計2000千瓦以上的設備將以11.02%的複合年成長率實現最高成長,這主要得益於超大規模資料中心的運作需求,這些資料中心目前需要100兆瓦或以上的橋接解決方案。 Aggreco公司在馬來西亞的一個資料中心安裝了八台1.5兆伏安的發電機組,這一案例表明,模組化設計使營運商能夠應對不斷成長的負載曲線,而不會造成長時間的停機。同時,50千瓦及以下的細分市場仍然重要,主要用作住宅和小規模商業設施的備用電源,但隨著通訊塔和診所轉向太陽能和電池儲能系統,其市場佔有率正在萎縮。
區域分析
北美在臨時電力市場的主導地位源於其完善的租賃生態系統、與原始設備製造商 (OEM) 和經銷商的牢固夥伴關係,以及嚴格的資產管理實踐。光是聯合租賃公司 (United Rentals) 就經營 1591 個租賃點,管理價值 214 億美元的設備,這使得該公司能夠在風暴威脅墨西哥灣沿岸煉油廠或中西部電力公司宣布更換變壓器時迅速部署電力供應。雖然美國佔據了該地區的大部分需求,但加拿大透過建造液化天然氣 (LNG) 工廠和維修水力發電廠也補充了這一需求。墨西哥則透過近岸外包推動的工廠擴建,進一步提升了電力需求。
由於各國政府多年來對公路、機場和城市交通的持續投資,亞太地區展現出最高的成長動能。中國是總需求的主要驅動力,但一線城市柴油引擎的運作受到政策限制,加速了向天然氣和混合動力引擎的轉型。印度已根據CPCB IV+標準採納了類似的規定,但柴油引擎在農村電氣化和建築領域仍佔據主導地位。在東南亞國協,特別是越南、印尼和菲律賓,電網容錯能力的挑戰日益多樣化,中型貨櫃式解決方案更受青睞。日本和韓國的建築商正在指定使用符合歐五排放標準的引擎,這支撐了該地區的高階需求。
在歐洲市場,遵守排放氣體法規和將可再生能源併入電網至關重要。德國、法國和英國正在大規模部署符合第五階段排放標準的發電機組,並配備電池組,用於低噪音都市區。該地區也率先引進氫動力移動式渦輪機,以彌補北海離岸風力發電的不穩定性。南歐和東歐國家的成長相對緩慢,但由於水力發電廠的維修和天然氣管道的擴建,需求會出現暫時性的激增。在整個歐洲,城市當局正透過允許進入許可權低排放氣體區來鼓勵混合動力租賃方案,從而影響車輛的更換週期。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 極端天氣導致的停電頻率正在增加。
- 新興市場的工業化和建築業蓬勃發展
- 老化的電網基礎設施和計畫內的維護停機
- 多吉瓦資料中心的「公用事業缺口」需求
- 引入可再生能源需要靈活的峰值響應能力。
- 向低排放量和混合動力租賃車輛轉型,並採用ESG(環境、社會和治理)技術
- 市場限制因素
- 柴油價格波動和燃料物流中斷
- 更嚴格的全球和區域性發電廠排放標準
- 電池儲能和微電網正在給發電機的需求帶來壓力。
- 發電機部件供應鏈瓶頸
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章:預測市場規模與成長率
- 按燃料類型
- 柴油引擎
- 氣體
- 混合型及其他
- 按類型分類的額定輸出
- 50千瓦或以下
- 51~280 kW
- 281~500 kW
- 501~2,000 kW
- 超過2000千瓦
- 透過使用
- 基本負載/連續運行
- 電網支援和停電響應
- 災害救援和緊急應變
- 偏遠地區的電氣化
- 按最終用戶行業分類
- 公用事業和電力
- 石油和天然氣
- 建築和採礦
- 製造業和工業
- 活動與娛樂
- 資料中心/資訊通訊技術
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 北歐國家
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 南非
- 埃及
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Aggreko PLC
- Caterpillar Inc.
- Cummins Inc.
- APR Energy Ltd
- Atlas Copco AB
- Kohler Co.
- United Rentals Inc.
- Ashtead Group plc(Sunbelt Rentals)
- Speedy Hire plc
- Generac Holdings Inc.
- Wartsila Corp.
- HIMOINSA SL(Yanmar)
- Rolls-Royce plc(mtu Solutions)
- Multiquip Inc.
- Doosan Portable Power
- JCB Power Products
- Energyst Rental Solutions
- Altaaqa Global Energy Services
第7章 市場機會與未來展望
According to Mordor Intelligence, temporary power market size in 2026 is estimated at USD 7.02 billion, growing from 2025 value of USD 6.43 billion with 2031 projections showing USD 10.86 billion, growing at 9.14% CAGR over 2026-2031.
This report is Segmented by Fuel Type (Diesel, Gas, and Hybrid and Others), Power Rating (Up To 50 KW, 501 To 2, 000 KW, Above 2, 000 KW, and More), Application (Base-load/Continuous, Grid Support and Transmission Outage, and More), End-User Industry (Utilities and Power, Oil and Gas, Data Centres and ICT, and More), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa)
Global Temporary Power Market Trends and Insights
Rising Frequency of Extreme-Weather Outages
Hurricanes, heat waves, wildfires, and monsoon floods are triggering longer and more frequent grid failures, causing emergency generator rentals to spike immediately after each event. Utilities and municipal authorities now pre-stage rental fleets ahead of storm seasons, allowing suppliers to reposition assets and optimize pricing. Insurance underwriters increasingly insist on on-site backup for hospitals, telecom nodes, and cold-chain warehouses. These contractual safeguards convert what was once sporadic, disaster-driven revenue into predictable seasonal demand. As climate variability intensifies, emergency power services have become an embedded line item in North America and Europe's resilience budgets.
Industrialisation & Construction Booms in Emerging Markets
Megaproject pipelines in India, Indonesia, and the Gulf Cooperation Council nations require high-capacity generators to run cranes, concrete plants, and dewatering pumps when grid feeds are absent or unstable. Local rental providers typically supply <= 500 kW units, but multinational contractors now prefer bundled packages of 1 MW and above to lower per-kilowatt logistics costs. The resulting scale shift allows global fleets to deliver containerized plants on accelerated timelines. Government stimulus for roads, ports, and industrial corridors further widens the user base, supporting steady multi-year contracts rather than one-off rentals.
Stricter Global & Local Emission Standards on Gensets
EU Stage V rules oblige particulate filters on 19-560 kW engines; India's forthcoming CPCB IV+ will extend coverage to 800 kW sets, while California is drafting Tier 5 proposals likely to surpass European stringency. Each tightening cycle raises capital costs and compresses residual values of legacy fleets, lowering return on invested capital for rental operators. Urban authorities also deploy low-emission zones that limit runtime hours, constraining traditional diesel utilization in core city projects. Although cleaner technologies can offset lost volumes, the transition demands funding and technical retraining.
Other drivers and restraints analyzed in the detailed report include:
- Ageing Grid Infrastructure & Planned Maintenance Shutdowns
- Multi-Gigawatt Data-Center "Utility-Gap" Demand
- Diesel-Price Volatility & Fuel-Logistics Disruptions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Diesel sets generated 69.85% of 2025 revenue, reflecting ubiquitous service infrastructure, high energy density, and rapid response capabilities that remain indispensable on disaster sites and off-grid projects. Nevertheless, the temporary power market is pivoting toward hybrid formats that combine solar arrays, battery packs, or propane engines, a category forecast to compound at 15.05% annually through 2031. Aggreko's Martin County microgrid, built around five 1.3 MW gas generators, illustrates the scaling potential for cleaner fuels in oilfield operations. Construction firms adopting electric excavators also request low-noise solar-battery generators, signaling how equipment electrification ripples through the broader temporary power industry. As cost curves fall, hybrid packages shift from pilot deployments to core rental offerings, redesigning procurement specifications across Europe and North America.
Sets in the 501-2,000 kW band held 32.35% of 2025 revenue, serving industrial processes and sizeable construction jobs that value transportability alongside capacity. Above-2,000 kW machines deliver the highest forecast growth at 11.02% CAGR, underpinned by hyperscale data-center commissioning schedules that now demand 100 MW-plus bridging solutions. Aggreko's rollout of eight 1.5 MVA gensets for a Malaysian data-center complex exemplifies how modular design lets operators match rising load profiles without extended downtime. Meanwhile, the up-to-50 kW niche retains relevance for residential and small commercial backup, but its share erodes as telecom towers and clinics migrate to solar-battery kits.
Complete Report Scope:
- By Fuel Type
- Diesel
- Gas
- Hybrid and Others
- By Power Rating
- Up to 50 kW
- 51 to 280 kW
- 281 to 500 kW
- 501 to 2,000 kW
- Above 2,000 kW
- By Application
- Base-load/Continuous
- Grid Support and Transmission Outage
- Disaster Relief and Emergency
- Remote-area Electrification
- By End-User Industry
- Utilities and Power
- Oil and Gas
- Construction and Mining
- Manufacturing and Industrial
- Events and Entertainment
- Data Centres and ICT
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America's leadership in the temporary power market rests on a sophisticated rental ecosystem, deep OEM-dealer partnerships, and disciplined asset-management practices. United Rentals alone operates 1,591 locations and manages a USD 21.4 billion equipment fleet, enabling rapid mobilization when storms threaten Gulf Coast refineries or when Midwest utilities announce transformer change-outs. The United States accounts for most regional demand, while Canada supplements with LNG plant builds and hydro dam refurbishments. Mexico adds volume through nearshoring-driven factory expansions.
Asia-Pacific supplies the highest growth trajectory as governments channel multi-year funding into roads, airports, and urban transit. China drives headline volumes but faces policy-induced caps on diesel runtime in tier-1 cities, accelerating migration toward gas and hybrid sets. India adopts similar standards under CPCB IV+ yet remains a diesel stronghold for rural electrification and construction. ASEAN economies, Vietnam, Indonesia, and the Philippines, present diverse grid resiliency challenges, favoring mid-scale containerized solutions. Japanese and Korean contractors specify Stage V-equivalent engines, anchoring premium demand in the region.
Europe's market centres on emission compliance and renewable-grid integration. Germany, France, and the United Kingdom purchase large fleets of Stage V gensets paired with battery pods for low-noise urban applications. The region also pioneers hydrogen-ready mobile turbines to balance offshore wind intermittency in the North Sea. Southern and Eastern European countries grow more modestly but exhibit episodic spikes tied to hydro-dam refurbishments and gas-pipeline expansions. Across the continent, city authorities incentivize hybrid rental packages by granting low-emission-zone access, thereby shaping fleet renewal cycles.
- Aggreko PLC
- Caterpillar Inc.
- Cummins Inc.
- APR Energy Ltd
- Atlas Copco AB
- Kohler Co.
- United Rentals Inc.
- Ashtead Group plc (Sunbelt Rentals)
- Speedy Hire plc
- Generac Holdings Inc.
- Wartsila Corp.
- HIMOINSA S.L. (Yanmar)
- Rolls-Royce plc (mtu Solutions)
- Multiquip Inc.
- Doosan Portable Power
- JCB Power Products
- Energyst Rental Solutions
- Altaaqa Global Energy Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising frequency of extreme-weather outages
- 4.2.2 Industrialisation & construction booms in emerging markets
- 4.2.3 Ageing grid infrastructure & planned maintenance shutdowns
- 4.2.4 Multi-gigawatt data-centre "utility-gap" demand
- 4.2.5 Renewable integration requiring flexible peaking capacity
- 4.2.6 ESG-driven shift toward low-emission & hybrid rental fleets
- 4.3 Market Restraints
- 4.3.1 Diesel-price volatility & fuel-logistics disruptions
- 4.3.2 Stricter global & local emission standards on gensets
- 4.3.3 Battery storage & micro-grids eroding genset demand
- 4.3.4 Generator-component supply-chain bottlenecks
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products & Services
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Fuel Type
- 5.1.1 Diesel
- 5.1.2 Gas
- 5.1.3 Hybrid and Others
- 5.2 By Power Rating
- 5.2.1 Up to 50 kW
- 5.2.2 51 to 280 kW
- 5.2.3 281 to 500 kW
- 5.2.4 501 to 2,000 kW
- 5.2.5 Above 2,000 kW
- 5.3 By Application
- 5.3.1 Base-load/Continuous
- 5.3.2 Grid Support and Transmission Outage
- 5.3.3 Disaster Relief and Emergency
- 5.3.4 Remote-area Electrification
- 5.4 By End-User Industry
- 5.4.1 Utilities and Power
- 5.4.2 Oil and Gas
- 5.4.3 Construction and Mining
- 5.4.4 Manufacturing and Industrial
- 5.4.5 Events and Entertainment
- 5.4.6 Data Centres and ICT
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Aggreko PLC
- 6.4.2 Caterpillar Inc.
- 6.4.3 Cummins Inc.
- 6.4.4 APR Energy Ltd
- 6.4.5 Atlas Copco AB
- 6.4.6 Kohler Co.
- 6.4.7 United Rentals Inc.
- 6.4.8 Ashtead Group plc (Sunbelt Rentals)
- 6.4.9 Speedy Hire plc
- 6.4.10 Generac Holdings Inc.
- 6.4.11 Wartsila Corp.
- 6.4.12 HIMOINSA S.L. (Yanmar)
- 6.4.13 Rolls-Royce plc (mtu Solutions)
- 6.4.14 Multiquip Inc.
- 6.4.15 Doosan Portable Power
- 6.4.16 JCB Power Products
- 6.4.17 Energyst Rental Solutions
- 6.4.18 Altaaqa Global Energy Services
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


