


 |
市場調查報告書
商品編碼
2114762
汽車催化劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Automotive Catalyst - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,汽車催化劑市場將從 2025 年的 117,090 盎司成長到 2026 年的 121,660 盎司,到 2031 年將達到 147,550 盎司,2026 年至 2031 年的複合年成長率為 3.91%。
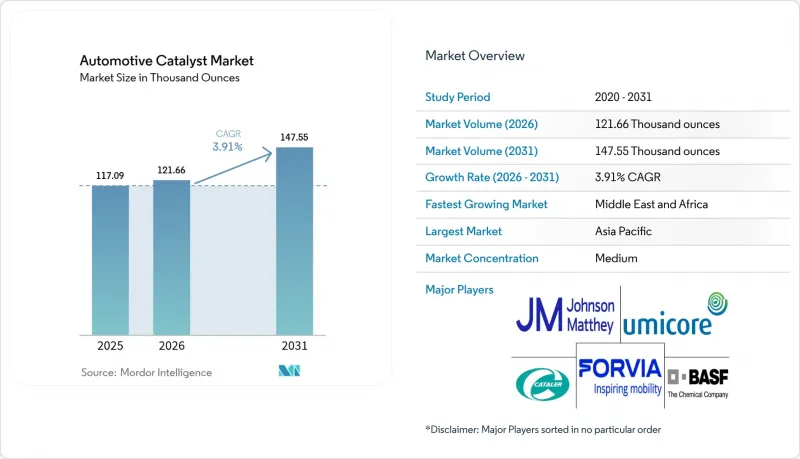
本報告按材料類型(鈀、鉑、銠及其他材料類型)、車輛類型(乘用車、輕型商用車、重型商用車)和地區(亞太地區、北美地區、歐洲地區、南美地區以及中東和非洲地區)進行細分。市場預測以盎司為單位。
全球汽車觸媒市場趨勢及洞察
歐洲7號排放標準和美國2027年排放法規將進一步收緊全球排放氣體標準。
歐盟7排放閾值,並強制要求安裝車輛監控系統,該系統會在排放量超過限值2.5倍時發出警告。柴油輕型車輛將被要求配備封閉式SCR塗層過濾器、功率高達4千瓦的電暖器以及氨逃逸催化劑。與歐6系統相比,這些升級將使催化劑的使用量增加約2.8倍,並將所需的耐久里程延長至16萬公里,從而推高對貴金屬的需求,並增加後處理系統的複雜性。
主要市場內燃機(ICE)混合動力汽車銷售復甦
2024年,中國插電式混合動力車銷量達430萬輛,較去年同期成長84%。同時,歐洲消費者也擴大購買增程器車型以彌補充電限制。混合動力汽車不僅需要傳統的三元觸媒轉換器,還需要能夠承受頻繁熱循環的快速啟動型觸媒轉換器。包括泰國在內的東協國家已推出針對混合動力汽車組裝的投資獎勵措施,進一步提升了該地區對符合標準的觸媒轉換器系統的需求。
電動車價格快速與燃油車持平,將對未來燃油車的銷售構成壓力。
特斯拉計劃在2024年將其Model 3的生產成本降至28,000美元,從而基本消除其與內燃機轎車之間的價格差異。歐盟排放法規規定,每克二氧化碳排放量超過目標值將被處以95歐元的罰款,預計到2025年,罰款總額將達到160億歐元。這迫使汽車製造商加快向純電動車轉型。在中國,純電動車到2024年的市佔率已達35%,顯示政策和成本趨勢可能抑制其長期的市場需求。
細分市場分析
銠在降低汽油車三元觸媒轉換器中的氮氧化物排放方面發揮著不可或缺的作用,預計到2031年將以4.42%的複合年成長率成長。隨著歐7排放標準要求同時降低所有受管制污染物的排放,汽車觸媒中銠的市場預計將比任何其他貴金屬的成長速度更快。鈀仍將保持其在銷售方面的領先地位,到2025年將佔據43.85%的市場佔有率,但價格波動和製裁風險正促使汽車製造商轉向鉑金。由於2024年鉑金的平均現貨價格比鈀金低55%,因此鉑金在汽油車平台上的應用再次擴大,這推動了多項鉑金替代方案的實施。雖然小眾基底金屬和沸石基催化劑加速器在汽車催化劑市場中所佔佔有率較小,但隨著供應商將「原子級高效」的設計商業化,這些設計在不影響耐久性的前提下顯著降低了對貴金屬的依賴,它們的市場佔有率仍在持續成長。
從傳統的塗層設計轉向單原子和雙金屬結構,預計將每克催化劑中貴金屬的使用量減少高達90%。莊信萬豐和BASF正在測試將孤立的鉑原子嵌入氧化鈰-氧化鋯基質中的生產線,從而增加每克催化劑的活性位點數量。同時,透過與汽車切碎機營運商建立閉合迴路夥伴關係,銠的回收率正在提高,緩解了供應短缺問題。這些努力共同作用,即使在長期電氣化進程中,也能維持汽車催化劑市場的穩定。
區域分析
到2025年,亞太地區將佔汽車催化劑市場51.45%的佔有率。中國將生產3,020萬輛汽車,同年插電式混合動力車的銷量將成長84%,這將確保三元催化劑和SCR系統的廣泛應用。本地供應商通常與全球公司合作,在保持成本競爭力的同時,整合先進的塗層技術。在印度,在政府鼓勵發展國內催化劑製造群的措施支持下,汽車產量正在迅速成長。日本和韓國擁有尖端的研發能力,而東協的獎勵也促進了混合動力汽車的生產。
北美市場雖然成熟,但仍蘊藏著巨大機會。美國環保署第三階段排放標準要求汽車製造商維持催化劑的高性能,而完善的回收基礎設施正將鈀和鉑重新納入循環經濟體系。墨西哥產能的擴張正在扶持當地的載體塗層企業,縮短供應鏈並減少前置作業時間。加拿大嚴酷的冬季將降低電池續航里程,因此在許多地區內燃機仍將繼續使用,這也確保了在整個預測期內,催化轉換器將繼續出現在材料清單中。
儘管歐洲計劃在2035年禁止銷售新的內燃機汽車,但歐盟7排放標準的實施支持了短期需求。比利時和德國先進的回收工廠能夠回收高達95%的廢棄貴金屬,從而增強了區域自給自足能力。混合動力汽車車型正在推動催化劑的長期需求,即使在純電動車(BEV)滲透率最高的市場也是如此。由於摩洛哥2023年58.2萬台的產量以及沙烏地阿拉伯29億美元的工業投資,中東和非洲的汽車催化劑市場預計將以4.63%的複合年成長率成長。南非仍然是主要的出口中心,但歐洲純電動車的快速發展可能會在未來幾年減少催化劑的長途運輸。由於宏觀經濟逆風,南美洲的成長速度較慢,但巴西和阿根廷仍在支撐該地區對基礎材料的需求。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 歐洲7號排放標準和美國2027年排放法規將進一步收緊全球排放氣體標準。
- 主要市場內燃機(ICE)混合動力汽車銷售復甦
- 用鈀代替鉑將降低整車製造商催化劑的成本。
- 關於非道路和船用引擎的新規定
- 有效距離式電動車的蓬勃發展支撐了中國和歐洲對鉑族金屬的需求。
- 市場限制因素
- 電動車價格快速與燃油車持平,將對未來燃油車的銷售構成壓力。
- 透過 OEM 和區域型催化劑設計降低成本,減少每輛車使用的 PGM 量。
- 由於對俄羅斯和烏克蘭的供應制裁,鉑族金屬貿易流量中斷
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依材料類型
- 鈀
- 鉑
- 銠
- 其他材料類型
- 按車輛類型
- 搭乘用車
- 輕型商用車
- 大型商用車輛
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- BASF SE
- CATALER CORPORATION
- CDTi Advanced Materials Inc.
- Clariant
- Cummins Inc.
- DCL International Inc.
- Ecocat India Pvt Ltd.
- Forvia SE
- Heraeus Precious Metals
- INTERKAT Catalyst GmbH
- Johnson Matthey
- Klarius Group Ltd.
- NE CHEMCAT CORPORATION
- Solvay
- Tenneco Inc.
- Umicore
第7章 市場機會與未來展望
According to Mordor Intelligence, the automotive catalyst market size is expected to grow from 117.09 Thousand ounces in 2025 to 121.66 Thousand ounces in 2026 and is forecast to reach 147.55 Thousand ounces by 2031 at 3.91% CAGR over 2026-2031.
This report is Segmented by Material Type (Palladium, Platinum, Rhodium, and Other Material Types), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and Heavy Commercial Vehicles), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (Ounces).
Global Automotive Catalyst Market Trends and Insights
Stringent Global Emission Limits Tighten Further Through Euro 7/US 2027 Rules
Euro 7 introduces a particle-number threshold of 10 nanometers and enforces on-board monitoring capable of flagging emission exceedances at 2.5 times the limit. Diesel light-duty vehicles must add close-coupled SCR-coated filters, electric heaters up to 4 kW, and ammonia-slip catalysts. These upgrades enlarge catalyst volumes by nearly 2.8 times versus Euro 6 systems and extend required durability to 160,000 km, driving higher precious-metal demand and more complex aftertreatment architectures.
Re-Acceleration of ICE-Hybrid Sales in Major Markets
China's plug-in hybrid sales surged 84% year-over-year in 2024 to 4.3 million units, while European consumers increasingly purchase range-extender models that offset charging gaps. Hybrid layouts necessitate conventional three-way catalysts alongside rapid light-off formulations that tolerate frequent thermal cycling. Thailand and other ASEAN markets are offering investment incentives for hybrid assembly, reinforcing regional demand for compliant catalyst systems.
Rapid BEV Cost-Parity Squeezes Future ICE Volumes
Tesla reduced Model 3 production cost to USD 28,000 in 2024, erasing much of the traditional price gap with ICE sedans. EU fleet CO2 penalties at EUR 95 per gram above target could total EUR 16 billion in 2025, incentivizing automakers to pivot faster toward battery models. China already achieved a 35% BEV market share in 2024, illustrating how policy and cost trajectories can suppress long-term catalyst demand.
Other drivers and restraints analyzed in the detailed report include:
- Platinum-For-Palladium Substitution Lowers Catalyst Cost for OEMs
- Emerging Mandates on Off-Road and Marine Engines
- OEM Thrifting and Zoned Catalyst Designs Cut PGM Grams/Vehicle
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rhodium plays an irreplaceable role in lowering NOx on gasoline three-way catalysts and is forecast to grow at a 4.42% CAGR to 2031. The automotive catalysts market size for rhodium therefore rises faster than any other precious metal as Euro 7 demands simultaneous reduction of all regulated pollutants. Palladium remains the volume leader due to its 43.85% share in 2025, yet price volatility and sanctions risk encourage OEMs to diversify toward platinum. Platinum's uptake in gasoline platforms is renewing because its average 2024 spot price was 55% lower than palladium, supporting multiple platinum substitution programs. The automotive catalysts market share held by niche base-metal or zeolite promoters is small but growing as suppliers commercialize atom-efficient designs that slash precious-metal dependence without compromising durability.
The shift from conventional washcoats to single-atom and bimetallic architectures enables a potential 90% reduction in precious-metal use per catalyst. Johnson Matthey and BASF are piloting production lines that embed isolated platinum atoms in ceria-zirconia matrices, creating more active sites per gram. At the same time, rhodium recycling rates have improved through closed-loop partnerships with auto shredder operators, easing supply tightness. Collectively, these actions stabilize the automotive catalysts market even under long-term electrification scenarios.
Complete Report Scope:
- By Material Type
- Palladium
- Platinum
- Rhodium
- Other Material Types
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific contributed 51.45% of the automotive catalysts market in 2025. China produced 30.2 million vehicles, and plug-in hybrids grew 84% during the year, ensuring solid uptake of three-way and SCR systems. Local suppliers often partner with global firms to integrate advanced washcoats while maintaining cost competitiveness. India is scaling vehicle output rapidly, aided by government initiatives that encourage domestic catalyst manufacturing clusters. Japan and South Korea provide cutting-edge R&D, while ASEAN incentives sustain hybrid assembly volumes.
North America represents a mature yet opportunity-rich arena. EPA Tier 3 rules force automakers to maintain high catalyst performance, and robust recycling infrastructure feeds palladium and platinum back into the circular economy. Mexico's production growth anchors localized substrate coating operations that shorten supply chains and cut lead times. Canada's cold winters impair battery range, preserving internal-combustion usage in many regions and keeping catalysts on the bill of materials through the forecast horizon.
Europe faces a 2035 new-vehicle ICE ban but near-term demand is buoyed by Euro 7 rollouts. Advanced recycle plants in Belgium and Germany recover up to 95% of spent precious metals, reinforcing regional self-sufficiency. Hybrid models prolong catalyst relevance even in markets with the highest BEV uptake. The Middle East and Africa automotive catalysts market is on track for a 4.63% CAGR thanks to Morocco's 582,000-unit 2023 output and Saudi industrial investments of USD 2.9 billion. South Africa remains a major export hub although BEV momentum in Europe could dilute long-haul catalyst shipments in later years. South America grows more modestly given macroeconomic headwinds, but Brazil and Argentina still underpin regional substrate demand.
- BASF SE
- CATALER CORPORATION
- CDTi Advanced Materials Inc.
- Clariant
- Cummins Inc.
- DCL International Inc.
- Ecocat India Pvt Ltd.
- Forvia SE
- Heraeus Precious Metals
- INTERKAT Catalyst GmbH
- Johnson Matthey
- Klarius Group Ltd.
- N.E. CHEMCAT CORPORATION
- Solvay
- Tenneco Inc.
- Umicore
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Global Emission Limits Tighten Further Through Euro 7/US 2027 Rules
- 4.2.2 Re-Acceleration of ICE-Hybrid Sales in Major Markets
- 4.2.3 Platinum-For-Palladium Substitution Lowers Catalyst Cost for Oems
- 4.2.4 Emerging Mandates on Off-Road And Marine Engines
- 4.2.5 Range-Extender EV Boom Sustains PGM Demand in China and Europe
- 4.3 Market Restraints
- 4.3.1 Rapid BEV Cost-Parity Squeezes Future ICE Volumes
- 4.3.2 OEM Thrifting and Zoned Catalyst Designs Cut PGM Grams/Vehicle
- 4.3.3 Russia-Ukraine Supply Sanctions Disturb PGM Trade Flows
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Material Type
- 5.1.1 Palladium
- 5.1.2 Platinum
- 5.1.3 Rhodium
- 5.1.4 Other Material Types
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Heavy Commercial Vehicles
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)}
- 6.4.1 BASF SE
- 6.4.2 CATALER CORPORATION
- 6.4.3 CDTi Advanced Materials Inc.
- 6.4.4 Clariant
- 6.4.5 Cummins Inc.
- 6.4.6 DCL International Inc.
- 6.4.7 Ecocat India Pvt Ltd.
- 6.4.8 Forvia SE
- 6.4.9 Heraeus Precious Metals
- 6.4.10 INTERKAT Catalyst GmbH
- 6.4.11 Johnson Matthey
- 6.4.12 Klarius Group Ltd.
- 6.4.13 N.E. CHEMCAT CORPORATION
- 6.4.14 Solvay
- 6.4.15 Tenneco Inc.
- 6.4.16 Umicore
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 汽車催化劑市場:按材料類型、車輛類型、燃料類型、技術和最終用戶分類-2026-2032年全球預測
 2026年全球汽車觸媒市場報告
 全球汽車觸媒市場,2026-2030年
 汽車觸媒市場規模、佔有率和成長分析(按產品類型、引擎類型、銷售管道、車輛類型和地區分類)-2026-2033年產業預測Ce-Zr 固溶體汽車觸媒市場(依實體形態、引擎類型、應用、車輛類型和通路分類)-2025-2030 年全球預測
 全球汽車電子燃料市場
 汽車電子燃料市場機會、成長動力、產業趨勢分析及 2025 - 2034 年預測
 汽車催化劑市場 - 2024-2034 年全球產業分析、規模、佔有率、成長、趨勢與預測