


 |
市場調查報告書
商品編碼
2114110
隔膜泵:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Diaphragm Pump - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
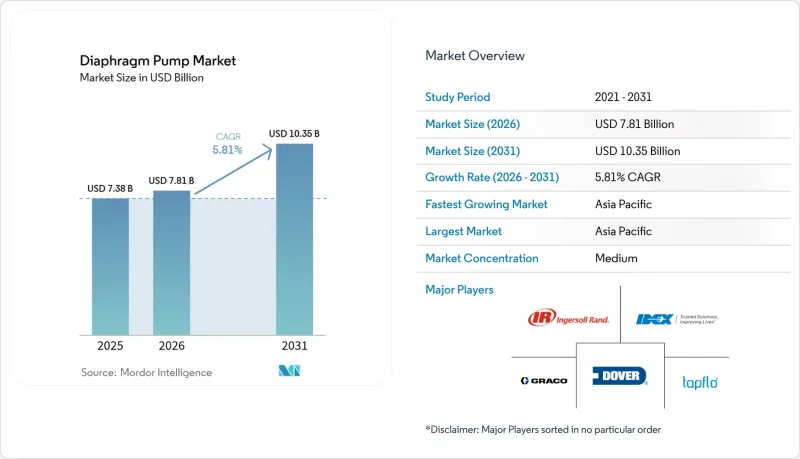
據 Mordor Intelligence 稱,隔膜泵市場預計到 2026 年價值 78.1 億美元,高於 2025 年的 73.8 億美元,預計到 2031 年將達到 103.5 億美元。
預計 2026 年至 2031 年的複合年成長率為 5.81%。
本報告按驅動系統(氣動雙隔膜、電動隔膜等)、本體材質(金屬、塑膠、複合材料)、排氣壓力(小於 80 巴、80-200 巴、大於 200 巴)、最終用戶(供水/污水、石油/天然氣、化學/石化、其他)和地區(北美、歐洲、亞太、供水/污水和非洲)進行分類。
全球隔膜泵市場趨勢及洞察
新興經濟體用水和污水基礎設施的擴建
亞太地區和中東部分地區正在進行的大規模基礎設施建設項目,推動了市政和工業處理設施對高性能流體輸送設備的需求。亞洲開發銀行已批准菲律賓一項價值4,160萬美元的專案。該項目包括一座日處理能力達3000萬升的地表水處理廠,其中廣泛採用隔膜泵來處理不同黏度的流體,並確保無洩漏運作。政府資金支持和更嚴格的排放標準正在加速隔膜泵的普及,因為隔膜泵具有乾運轉能力、抗堵塞性和化學兼容性。城市在維修現有設施時,也出於降低全生命週期成本的考慮,安裝隔膜泵,以避免因廢水洩漏而面臨罰款的風險。
擴大化工和石化產能
在中國、印度、沙烏地阿拉伯和阿拉伯聯合大公國,新型烯烴、聚合物和特種化學品聯合裝置正迅速湧現。根據LEWA的一份報告,液壓驅動隔膜計量泵在加氫裂解、聚合和催化劑注入等製程的應用日益廣泛。在這些製程中,精確的流量控制對於確保產品收率至關重要。操作人員也高度重視驅動單元與製程腔室之間的完全密封隔離,以防止危險物質洩漏。這一趨勢與對高純度中間體和高價值衍生物的大量投資相吻合,從而確保了隔膜泵市場的長期需求。
原物料價格波動會影響平均售價(ASP)。
自2024年以來,不銹鋼、鋁和高品質彈性體的價格波動劇烈,對缺乏避險機制的中小型製造商的利潤率帶來壓力。季度價格調整導致資本預算的不確定性,並造成非緊急專案客戶訂單的延遲。拉丁美洲和非洲部分地區等特種合金供應鏈脆弱的地區,由於運費額外費用加劇了價格波動,成本飆升的影響尤其顯著。
細分市場分析
預計到2025年,氣動雙隔膜幫浦的市場規模將達到34.2億美元,佔全球銷售額的46.40%。這主要歸功於其固有的安全性和易於啟動的特點。雖然電動隔膜泵的市場規模較小,但預計其成長速度將超過所有其他驅動系統,複合年成長率將達到6.89%。根據能源審計數據,這些型號的隔膜泵可降低高達80%的營業成本,並減少與壓縮機相關的二氧化碳排放,從而符合企業的淨零排放承諾。與變頻驅動器整合可實現更精確的計量,尤其是在化學品注入和生物製程發酵槽中。在此背景下,隨著能夠獲得危險場所認證的併網工廠的普及,預計到 2031 年,電動隔膜泵的市場佔有率將超過 27.60%。對於溶劑回收、油漆回收以及有爆炸風險的地區,使用壓縮空氣運作且不會過熱的 AODD(氣動雙向隔膜)設計仍然是主要選擇。
液壓驅動隔膜泵也呈現類似的趨勢,在超過200巴的高壓輸送應用中,例如海上註水撬裝設備和測試設備,需求仍然強勁。儘管成長速度有所放緩,但供應商正在透過配備洩漏檢測感測器和用於捕獲金屬顆粒的磁性材料來改進液壓泵框架。一些二線製造商則透過內建蓄能器的阻尼功能來穩定脈動,從而在壓縮空氣稀缺且使用高壓不切實際的情況下為用戶提供替代方案,以此來提升產品競爭力。
到2025年,不鏽鋼、鑄鐵和鋁製金屬外殼的隔膜泵市場規模將達到38.6億美元,佔銷售額的52.30%。由於其耐磨性、熱穩定性和高壓耐壓性,這些材質的隔膜泵在礦山滲濾液和精煉廠中仍佔據主導地位。同時,塑膠和複合材料製成的泵浦正以7.12%的複合年成長率快速成長。聚丙烯外殼與聚四氟乙烯(PTFE)泵頭結合,可降低酸性輸送迴路(尤其是電池級磷酸鹽管線)的腐蝕。其輕量化結構便於在高處管道支架上安裝,進而降低出口型化工廠的運輸成本。一些製藥業的使用者更傾向於採用符合ASME-BPE電解標準的聚偏氟乙烯(PVDF)材質,從而縮短驗證時間。
同時,金屬幫浦使用者正透過改進表面處理製程(例如採用雙相不銹鋼合金和陶瓷塗層)來應對挑戰,以防止腐蝕性油泥的形成並延長平均故障間隔時間。積層製造(3D列印)技術也被用於製造複雜的閥板,顯著縮短了小批量客製訂單的前置作業時間。這兩個趨勢確保了兩種材料類別的生存,但這種轉變也凸顯了特定應用領域的耐腐蝕性如何影響採購決策。
區域分析
亞太地區隔膜幫浦市場預計到2025年將達到27.1億美元,到2031年將達到38.3億美元,複合年成長率(CAGR)為5.95%[1]。中國電池和石化產業的蓬勃發展、印度的「智慧城市計畫」以及東南亞的污水處理計畫是推動這一成長的主要動力。地方政府對污染控制設備的補貼也促進了無洩漏隔膜泵的普及應用。日本和韓國的成熟製造商則專注於研發緊湊型電動隔膜泵,以滿足高度自動化工廠的需求。
預計到2025年,北美市場規模將達到18.9億美元。美國環保署(EPA)禁止使用甲烷排放的氣動泵,迫使中游業者轉向使用電動泵;同時,主要在美國快速成長的精釀飲料市場,也推動了對符合3-A衛生標準產品的需求。在加拿大,油砂棕地的維修升級也為市場帶來了利好,使用者擴大選擇採用聚四氟乙烯(PTFE)隔膜結構的產品,因為這類產品在低溫環境下具有很高的可靠性。
預計到2025年,歐洲市場規模將達到14.6億美元。德國特種化學品產業的成長推動了高壓計量計畫的發展,而義大利、西班牙和荷蘭對歐盟工業排放指令的修訂則促使離心式幫浦從填料式轉變為隔膜式。此外,與能源效率相關的區域補貼也加速了與工廠分析系統整合的智慧電動幫浦的普及應用。
預計到2025年,中東和非洲地區的市場規模將超過7.3億美元,主要得益於水循環利用和油田注水技術的推動。沙烏地阿拉伯的海水冷卻巨型工廠和阿拉伯聯合大公國的電池前驅體業務等項目,正在刺激對耐氯化物雙相不銹鋼和合金20泵的需求。撒哈拉以南非洲的採礦業雖然目前仍處於相對停滯的狀態,但展現出巨大的發展潛力。
受巴西運作石化工廠和阿根廷鋰鹵水開採計畫的推動,南美市場規模達5.9億美元。當地OEM組裝正與全球授權公司合作以縮短前置作業時間,但由於外匯波動限制了資本投資計劃,短期擴張速度正在放緩。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興國家的用水和污水基礎設施發展
- 擴大化工和石化產品的生產能力
- 加強洩漏排放法規,以支援無洩漏泵
- 需要剪切敏感傳遞的電池電解裝置
- 利用物聯網進行預測性維護的維修正在加速設備的更換。
- 精釀飲料的蓬勃發展正在推動衛生型 AOD(自主有機洗滌劑)的普及。
- 市場限制因素
- 原物料價格波動影響平均售價(ASP)。
- 低黏度應用中離心式幫浦/螺旋泵的替代方案
- 氣動隔膜裝置中壓縮空氣能量的損失
- 關於都市區噪音和振動影響工廠位置的條例
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 透過驅動系統
- 氣動雙隔膜 (AODD)
- 電膜
- 液壓驅動隔膜
- 按身體材質
- 金屬(鋁、不鏽鋼、碳)
- 塑膠和複合材料
- 排氣壓力
- 小於 80 巴
- 80~200 bar
- 200巴或以上
- 最終用戶
- 水和污水處理
- 石油和天然氣
- 化工/石油化工
- 製藥和生物技術
- 食品/飲料
- 採礦和金屬
- 紙漿和造紙
- 其他(油漆、電子設備等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 南非
- 埃及
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Ingersoll Rand PLC(ARO)
- Dover Corporation(PSG/Wilden)
- Idex Corporation(Banjo, Warren Rupp)
- Flowserve Corporation
- Graco Inc.
- Xylem Inc.
- SPX FLOW Inc.
- Grundfos A/S
- Verder Group
- Tapflo Group
- LEWA GmbH
- Yamada Corporation
- KNF Neuberger
- Atlas Copco(Edwards)
- PCM SA
- Schwarzer Precision
- AERZEN Group
- Thomas Pumps
- Gorman-Rupp
- Iwaki Co. Ltd
- Murzan Inc.
- Viking Pump
第7章 市場機會與未來展望
According to Mordor Intelligence, diaphragm pump market size in 2026 is estimated at USD 7.81 billion, growing from 2025 value of USD 7.38 billion with 2031 projections showing USD 10.35 billion, growing at 5.81% CAGR over 2026-2031.
This report is Segmented by Mechanism (Air-Operated Double Diaphragm, Electrically Driven Diaphragm, and More), Body Material (Metal and Plastic and Composite), Discharge Pressure (Below 80 Bar, 80 To 200 Bar, and Above 200 Bar), End-User (Water and Wastewater, Oil and Gas, Chemical and Petrochemical, and More), and Geography (North America, Europe, Asia Pacific, South America, and Middle East and Africa).
Global Diaphragm Pump Market Trends and Insights
Water & Wastewater Build-outs in Emerging Economies
Large-scale infrastructure programs across Asia-Pacific and parts of the Middle East are boosting demand for robust fluid-transfer equipment in municipal and industrial treatment plants. The Asian Development Bank approved a USD 41.6 million project in the Philippines that includes a 30 million L per day surface-water facility relying heavily on diaphragm pumps for varied fluid viscosities and leak-free operation. Government funding and stricter discharge guidelines accelerate specification of diaphragm pumps because they offer dry-running capability, clog resistance, and chemical compatibility. Cities upgrading legacy plants treat diaphragm pumps as a life-cycle cost hedge against fines that stem from effluent leaks.
Expansion of Chemical & Petrochemical Capacity
New olefins, polymers, and specialty-chemical complexes continue to surface across China, India, Saudi Arabia, and the United Arab Emirates. LEWA reports rising installations of hydraulically actuated diaphragm metering pumps for hydrocracking, polymerization, and catalyst injection, where precise flow control safeguards product yield. Operators also value hermetic separation between drive and process chambers that prevents hazardous spills. The trend aligns with broader investments in high-purity intermediates and value-added derivatives, ensuring long-run pull for the diaphragm pump market.
Raw-Material Price Volatility Impacting ASPs
Stainless steel, aluminum, and high-grade elastomer prices have moved erratically since 2024, compressing margins for smaller manufacturers that lack hedging mechanisms. Quarterly list-price adjustments propagate into capital budget uncertainty, delaying customer orders for projects not under schedule pressure. Regions with thin specialty alloy supply chains, including parts of Latin America and Africa, feel cost spikes more acutely because freight surcharges compound volatility.
Other drivers and restraints analyzed in the detailed report include:
- Tightening Fugitive-Emission Rules Favoring Leak-Free Pumps
- Battery-Grade Electrolyte Plants Demanding Shear-Sensitive Transfer
- Substitution by Centrifugal / Peristaltic Pumps in Low-Viscosity Duties
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The diaphragm pump market size for air-operated double diaphragm units stood at USD 3.42 billion in 2025, or 46.40 % of global revenue, largely due to intrinsic safety and ease of start-up. Electrically driven diaphragm pumps, though smaller in base, are forecast to post a 6.89 % CAGR, outpacing all other mechanisms. Energy-audit data show these models cut operating costs by as much as 80 % and curb compressor-related CO2 emissions, aligning with corporate net-zero pledges. Integration with variable-frequency drives allows finer dosing accuracy, especially in chemical injection and bioprocess fermenters. Against this backdrop, the diaphragm pump market share of electric models is expected to cross 27.60 % by 2031, supported by grid-connected plants where hazardous-location certification is feasible. AODD designs still dominate in solvent recovery, paint circulation, and explosion-prone zones because they run on shop air and stall without overheating.
A similar pattern emerges in hydraulically driven diaphragm pumps, which retain pockets of demand in high-pressure transfer above 200 bar, such as offshore injection skids and testing rigs. Despite slower growth, vendors enhance hydraulic frames with leak-detection sensors and magnetites to capture metal debris. Tier-two producers differentiate through integrated accumulator dampening that steadies pulsation, offering users an alternative when compressed air is scarce and high voltage is impractical.
Metal casings-stainless steel, cast iron, and aluminum-represented USD 3.86 billion of diaphragm pump market size in 2025, equal to a 52.30 % revenue share. They remain dominant for abrasion resistance, thermal stability, and high-pressure integrity in mining leachate and refinery units. Yet plastic and composite pumps are expanding at 7.12 % CAGR. Polypropylene housings coupled with PTFE heads mitigate corrosion in acid-transfer circuits, notably in battery-grade phosphate lines. Lightweight builds ease installation on elevated pipe racks and reduce freight bills for export-oriented chemical plants. Some pharmaceutical users prefer PVDF constructions that meet ASME-BPE electropolish criteria, shrinking validation time.
Metal users respond by upgrading surface treatments, such as duplex stainless alloys and ceramic coatings, to fend off corrosive sludge and extend mean time between failures. Additive manufacturing also gains traction for complex valve plates, slashing lead time on custom low-volume orders. This dual track keeps both material categories viable, yet the shift underscores how application-specific corrosion resistance shapes procurement.
Complete Report Scope:
- By Mechanism
- Air-Operated Double Diaphragm (AODD)
- Electrically Driven Diaphragm
- Hydraulically Driven Diaphragm
- By Body Material
- Metal (Al, SS, CI)
- Plastic and Composite
- By Discharge Pressure
- Below 80 bar
- 80 to 200 bar
- Above 200 bar
- By End-User
- Water and Wastewater
- Oil and Gas
- Chemical and Petrochemical
- Pharmaceutical and Biotechnology
- Food and Beverage
- Mining and Metals
- Pulp and Paper
- Others (Paints, Electronics, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held USD 2.71 billion of diaphragm pump market size in 2025 and is expected to reach USD 3.83 billion by 2031, equivalent to a 5.95 % CAGR [1]. China's rising battery and petrochemical complexes, India's Smart Cities Mission, and Southeast Asia's wastewater programs reinforce momentum. Provincial subsidies for pollution-control equipment amplify uptake of leak-free units. Mature producers in Japan and South Korea focus on compact electric designs compatible with heavily automated factories.
North America contributed USD 1.89 billion in 2025. The EPA's ban on methane-venting pneumatic pumps prompts midstream operators to adopt electric ranges, while the craft-beverage surge, mainly in the United States, elevates 3-A sanitary demand. Canada benefits from brownfield oil sands retrofits where low-temperature reliability steers users toward PTFE diaphragm constructions.
Europe generated USD 1.46 billion in 2025. Germany's specialty-chemicals growth sustains high-pressure metering projects, whereas EU Industrial Emissions Directive upgrades in Italy, Spain, and the Netherlands encourage replacement of packed-gland centrifugal units with diaphragm technology. Regional grants linked to energy-efficiency drive adoption of smart electric pumps integrated with factory analytics.
The Middle East and Africa surpassed USD 0.73 billion in 2025 fueled by water reclamation and oil-field injection. Saudi Arabia's seawater cooling mega-plants and the United Arab Emirates' battery-precursor ventures stimulate demand for duplex-stainless and alloy-20 pumps capable of high chloride resistance. Sub-Saharan Africa's mining sector remains intermittent but promising.
South America reached USD 0.59 billion, led by Brazil's petrochemical restart initiatives and Argentina's lithium brine extraction. Local OEM assemblers partner with global licensors to shorten lead times, but currency volatility restrains capex schedules, tempering near-term expansion.
- Ingersoll Rand PLC (ARO)
- Dover Corporation (PSG/Wilden)
- Idex Corporation (Banjo, Warren Rupp)
- Flowserve Corporation
- Graco Inc.
- Xylem Inc.
- SPX FLOW Inc.
- Grundfos A/S
- Verder Group
- Tapflo Group
- LEWA GmbH
- Yamada Corporation
- KNF Neuberger
- Atlas Copco (Edwards)
- PCM SA
- Schwarzer Precision
- AERZEN Group
- Thomas Pumps
- Gorman-Rupp
- Iwaki Co. Ltd
- Murzan Inc.
- Viking Pump
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Water & wastewater build-outs in emerging economies
- 4.2.2 Expansion of chemical & petrochemical capacity
- 4.2.3 Tightening fugitive-emission rules favouring leak-free pumps
- 4.2.4 Battery-grade electrolyte plants demanding shear-sensitive transfer
- 4.2.5 IoT-enabled predictive-maintenance retrofits accelerating replacement
- 4.2.6 Craft-beverage boom driving sanitary AODD installations
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility impacting ASPs
- 4.3.2 Substitution by centrifugal / peristaltic pumps in low-viscosity duties
- 4.3.3 Compressed-air energy penalties for AODD units
- 4.3.4 Urban noise-vibration ordinances hindering plant siting
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Mechanism
- 5.1.1 Air-Operated Double Diaphragm (AODD)
- 5.1.2 Electrically Driven Diaphragm
- 5.1.3 Hydraulically Driven Diaphragm
- 5.2 By Body Material
- 5.2.1 Metal (Al, SS, CI)
- 5.2.2 Plastic and Composite
- 5.3 By Discharge Pressure
- 5.3.1 Below 80 bar
- 5.3.2 80 to 200 bar
- 5.3.3 Above 200 bar
- 5.4 By End-User
- 5.4.1 Water and Wastewater
- 5.4.2 Oil and Gas
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Pharmaceutical and Biotechnology
- 5.4.5 Food and Beverage
- 5.4.6 Mining and Metals
- 5.4.7 Pulp and Paper
- 5.4.8 Others (Paints, Electronics, etc.)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Russia
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Ingersoll Rand PLC (ARO)
- 6.4.2 Dover Corporation (PSG/Wilden)
- 6.4.3 Idex Corporation (Banjo, Warren Rupp)
- 6.4.4 Flowserve Corporation
- 6.4.5 Graco Inc.
- 6.4.6 Xylem Inc.
- 6.4.7 SPX FLOW Inc.
- 6.4.8 Grundfos A/S
- 6.4.9 Verder Group
- 6.4.10 Tapflo Group
- 6.4.11 LEWA GmbH
- 6.4.12 Yamada Corporation
- 6.4.13 KNF Neuberger
- 6.4.14 Atlas Copco (Edwards)
- 6.4.15 PCM SA
- 6.4.16 Schwarzer Precision
- 6.4.17 AERZEN Group
- 6.4.18 Thomas Pumps
- 6.4.19 Gorman-Rupp
- 6.4.20 Iwaki Co. Ltd
- 6.4.21 Murzan Inc.
- 6.4.22 Viking Pump
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 隔膜泵市場-2026-2032年全球市場預測
 隔膜泵市場規模、佔有率和成長分析:按類型、運作方式、排放壓力、應用、材質、最終用戶和地區分類-2026-2033年產業預測
 隔膜泵市場報告:按機構、運作方式、排出壓力、終端用戶產業和地區分類(2026-2034 年)氣動雙隔膜幫浦市場:按泵浦類型、材質、流量和最終用戶分類-2026-2032年全球預測機械隔膜計量泵市場:按泵類型、材質、排放壓力、相數、分配管道和最終用途行業分類-全球預測,2026-2032年不銹鋼氣動隔膜泵市場:按類型、流量範圍、壓力範圍、終端用戶行業和銷售管道,全球預測,2026-2032年
 全球隔膜泵市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球隔膜泵市場報告
 氣動雙隔膜幫浦市場預測(至 2032 年):按閥門類型、材質、壓力等級、尺寸、應用、最終用戶和地區進行的全球分析
 氣動雙隔膜幫浦市場-全球產業規模、佔有率、趨勢、機會與預測(按壓力、按應用、按地區、按競爭細分,2020-2030 年)