


 |
市場調查報告書
商品編碼
2113997
鑽頭:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Drill Bit - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
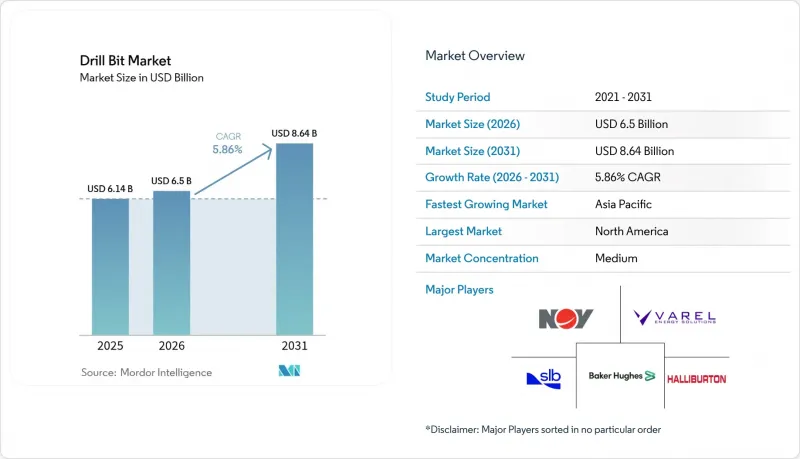
根據 Mordor Intelligence 估計,到 2026 年,鑽頭市值將達到 65 億美元,高於 2025 年的 61.4 億美元,預計到 2031 年將達到 86.4 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.86%。
本報告按類型(滾錐鑽頭、固定切削鑽頭、混合鑽頭、特殊鑽頭)、安裝地點(陸上和海上)、應用領域(石油天然氣、採礦、地熱、油井和土木工程)以及地區(北美、歐洲、亞太、南美以及中東和非洲)進行細分。市場規模和預測均以美元計價。
全球鑽頭市場趨勢與洞察
北美頁岩氣復興
頁岩氣產量的擴張正在推動全球鑽頭市場的發展,預計美國天然氣產量將從2025年的7.2兆立方英尺增加到2050年的8.8兆立方英尺。強勁的液化天然氣出口計畫維持了鑽機的強勁需求,美國60%的陸上鑽機集中在二疊紀盆地。單次鑽井超過2萬英尺的水平隧道推動了對先進PDC鑽頭設計的需求。阿根廷的瓦卡穆埃爾塔頁岩層正透過設定2030年日產量100萬桶的目標,並撥款超過10億美元用於採購特種鑽頭,從而拓展業務機會。人工智慧驅動的鑽探平臺提高了生產效率,進一步增強了頁岩氣領域全球鑽頭市場的前景。
深海探勘與生產(E&P)資本支出(CAPEX)增加
深海領域的資本投資提高了鑽井鑽機的運轉率,這些鑽井平台的日租金超過40萬美元,從而擴大了全球鑽頭市場。巴西石油公司(Petrobras)授予SLB一份價值8億美元的整合契約,涵蓋100多口油井,凸顯了巴西鹽層下地區對鑽頭的強勁需求。雪佛龍公司的「Anchor」計畫和伍德賽德公司的「Trion」計畫均採用20,000 psi的海底系統,對鑽頭的耐久性提出了極高的要求。西非的深海項目,包括安哥拉的Camino FPSO,正在部署低排放量鑽井系統,這需要高性能鑽頭。隨著這些技術複雜的油井專案不斷推進,製造商正致力於開發具有卓越熱穩定性、能夠承受超高壓環境的PDC鑽頭。
原油價格波動限制了鑽機的數量。
布蘭特原油價格徘徊在每桶65美元至74美元之間,抑制了探勘預算,並對全球鑽頭市場造成了影響。貝克休斯公司的鑽孔機數據顯示,每當油價跌破下行觸發點時,新的油井工程就會暫停。沙烏地阿美公司在2024年運作了20多個自升式鑽井,這清楚地表明了這家國有石油公司如何在低油價環境下調整其產能。獨立生產商對價格波動仍然非常敏感,並減少了對低獲利能力油田的鑽頭運作。雖然資本紀律削弱了油價與鑽井鑽機營運數量之間的直接相關性,但大宗商品價格波動仍在減緩高規格工具的採購週期。
細分市場分析
至2025年,固定切削鑽頭技術將佔全球鑽頭市場佔有率的44.30%。市場需求主要集中在PDC切削鑽頭上,其鑽井量已佔全球鑽井總長度的75-80%,構成了此類鑽頭全球市場規模的基礎。混合鑽頭結合了滾錐鑽頭的耐用性和鑽石鑽頭的鑽速,預計到2031年將以8.25%的複合年成長率成長,這反映了作業者對一次性解決方案的需求。
無催化劑鑽石結合技術的持續實驗室進步拓展了熱極限,使得PDC產品能夠應用於以往只能使用滾錐鑽頭的地層。像NOV這樣的製造商已在PDC領域深耕半個世紀,如今,人工智慧驅動的應力映射技術已被整合到產品設計生命週期中。因此,全球鑽頭市場正經歷良性循環:刀具壽命的延長減少了停產時間,這與重視效率和安全的作業者的需求不謀而合。
區域分析
2025年,北美在全球鑽頭市場將維持36.40%的佔有率,主要得益於先進的頁岩氣鑽井設計和墨西哥灣的持續開發。人工智慧驅動的鑽井技術使平均鑽井速度提高了30%,加快了高價鑽頭的投資回報。加拿大油砂開發和墨西哥的Trion超深海計畫進一步刺激了市場需求,並增強了該地區的規模經濟優勢。
亞太地區是全球鑽頭市場成長最快的地區,預計到2031年將以7.65%的複合年成長率成長。中國在陸上鑽機數量方面位居榜首,印度計劃將鑽機數量從2024年的111座增加到2028年的142座。這些發展趨勢正在推動對鑽頭的需求成長。預計到2025年,海上資本投資,尤其是在中國海域的投資,將超過3,000億美元,這將對該地區關鍵金屬和合成鑽石的供應鏈帶來壓力。
在中東和非洲,需求趨勢喜憂參半,但都發揮著至關重要的作用。阿布達比國家石油公司鑽井業務的銷售額實現了兩位數的成長,但由於沙烏地阿拉伯鑽機的運作,其運轉率指標有所放緩。西非的深海項目正在推動對超高壓鑽頭的需求,而歐洲的地熱開發項目則在一定程度上抵消了北海需求的下降。南美洲的瓦卡穆爾塔計畫是近十年來最大的非傳統資源開發項目之一,擴大了全球鑽頭市場在該半球的佔有率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 北美頁岩氣復興
- 深海探勘與生產(E&P)資本支出(CAPEX)增加
- 快速過渡到PDC鑽頭以提高ROP
- 地熱井鑽探激勵措施
- 天然氫氣探勘需求的萌芽
- 採用基於數位孿生技術最佳化的位元設計。
- 市場限制因素
- 原油價格波動限制了鑽井鑽機的數量。
- 加強環境法規和燃燒排放法規
- 合成鑽石的供應鏈風險
- 透過回收利用現有產品來獲取市場佔有率
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 滾錐鑽頭
- 固定切削刀頭
- 混合比特
- 特殊鑽頭(鑽孔岩心、擴孔)
- 按安裝位置
- 陸上
- 離岸
- 透過使用
- 石油和天然氣
- 礦業
- 地熱
- 水井和土木工程
- 地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 挪威
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 南非
- 埃及
- 奈及利亞
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Schlumberger Ltd(Smith Bits)
- Halliburton Co.(Security DBS)
- Baker Hughes Co.
- National Oilwell Varco Inc.
- Varel Energy Solutions
- Sandvik AB
- Ulterra Drilling Technologies
- Rockpecker Ltd
- Xi'an Landrill Oil Tools
- Epiroc AB
- Atlas Copco AB
- Drill Master International
- Torquato Drilling Accessories
- PDB Tools Inc.
- Kingdream Public Ltd Co.
- Sichuan Chuanshi Diamond Bits
- NewTech Drilling Products
- Cougar Drilling Solutions
- Baker SPD(specialty)
- Taurex Drill Bits
第7章 市場機會與未來展望
According to Mordor Intelligence, drill bit market size in 2026 is estimated at USD 6.5 billion, growing from 2025 value of USD 6.14 billion with 2031 projections showing USD 8.64 billion, growing at 5.86% CAGR over 2026-2031.
This report is Segmented by Type (Roller-Cone Bits, Fixed-Cutter Bits, Hybrid Bits, and Specialty Bits), Location of Deployment (Onshore and Offshore), Application (Oil and Gas, Mining, Geothermal, and Water-Well and Civil Construction), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Drill Bit Market Trends and Insights
Shale Gas Revival in North America
Shale output momentum lifts the Global Drill Bit market as U.S. natural-gas production is set to rise from 7.2 trillion cubic feet in 2025 toward 8.8 trillion cubic feet by 2050. Robust LNG export plans keep rig demand high, with the Permian Basin hosting 60% of U.S. onshore rigs. Longer laterals that exceed 20,000 feet in single runs foster demand for advanced PDC designs. Argentina's Vaca Muerta formation broadens the opportunity pool, targeting 1 million barrels per day by 2030 and allocating more than USD 1 billion for specialised bit procurement. Productivity gains stemming from AI-enabled drilling platforms further strengthen the Global Drill Bit market outlook within shale domains.
Deep-Water E&P CAPEX Upswing
Capital commitments for deepwater are improving the utilisation of rigs that command day rates above USD 400,000, thereby expanding the Global Drill Bit market. Petrobras awarded SLB a USD 800 million integrated contract covering more than 100 wells, underlining strong bit demand in Brazil's pre-salt cluster. Chevron's Anchor project and Woodside's Trion programme rely on 20,000 psi subsea systems that place premium requirements on cutter resilience. West Africa's deep-water projects, including Angola's Kaminho FPSO, are adopting low-emission drilling systems that require high-performance bits. This sustained pipeline of technically complex wells is pushing manufacturers to innovate thermal-stable PDC cutters that can endure ultra-high-pressure conditions.
Oil-Price Volatility Curbing Rig Counts
A Brent range of USD 65-74 per barrel tempers exploration budgets and sways the Global Drill Bit market. Baker Hughes rig data show pauses in new-well programs whenever prices breach downside triggers. Saudi Aramco's 2024 suspension of more than 20 jackups illustrates how national oil companies adjust their capacity in low-price environments. Independent producers remain especially price sensitive, curbing bit orders for marginal acreage. Even as capital discipline lessens the direct linkage between price and rig activity, commodity swings still stall procurement cycles for high-specification tools.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Switch to PDC Bits for Higher ROP
- Geothermal Well Drilling Incentives
- Stricter Environment & Flaring Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed-cutter technology held 44.30% of the Global Drill Bit market in 2025. Demand gravitates to PDC cutters that already drill 75-80% of worldwide footage, anchoring the Global Drill Bit market size for this class. Hybrid bits, which combine the durability of roller cones with the speed of diamonds, are projected to grow at an 8.25% CAGR through 2031, reflecting operator demand for single-run solutions.
Continued laboratory gains in catalyst-free diamond bonding have stretched thermal limits, making PDC products viable in formations once restricted to roller cones. Manufacturers such as NOV mark half a century of PDC innovation, pointing to design lifecycles that now incorporate AI-driven stress mapping. As a result, the Global Drill Bit market enjoys a virtuous cycle whereby improved cutter life reduces non-productive time, echoing operator priorities for efficiency and safety.
Complete Report Scope:
- By Type
- Roller-Cone Bits
- Fixed-Cutter Bits
- Hybrid Bits
- Specialty Bits (Core, Reaming)
- By Location of Deployment
- Onshore
- Offshore
- By Application
- Oil and Gas
- Mining
- Geothermal
- Water-Well and Civil Construction
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Norway
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Egypt
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 36.40% of the Global Drill Bit market in 2025, owing to advanced shale designs and ongoing developments in the Gulf of Mexico. AI-guided drilling increased average penetration rates by 30%, resulting in rapid paybacks on premium bits. Canadian oil-sands activity and Mexico's Trion ultra-deepwater campaign add incremental demand, reinforcing the region's scale advantage.
The Asia-Pacific region represents the fastest-growing market for the Global Drill Bit market, posting an 7.65% CAGR through 2031. China leads land-rig counts, while India plans to lift its fleet from 111 units in 2024 to 142 by 2028, moves that swell bit procurement pipelines. Offshore CAPEX that exceeds USD 300 billion in 2025, particularly in Chinese waters, tightens regional supply chains for critical metals and synthetic diamonds.
The Middle East and Africa deliver mixed but pivotal demand. ADNOC Drilling records double-digit revenue growth, yet Saudi rig suspensions temper utilisation metrics. West African deep-water projects drive demand for ultra-high-pressure bits, while Europe's geothermal initiatives help offset some of the decline in the North Sea. South America's Vaca Muerta programme offers one of the decade's largest unconventional prospects, enlarging the Global Drill Bit market footprint across the hemisphere.
- Schlumberger Ltd (Smith Bits)
- Halliburton Co. (Security DBS)
- Baker Hughes Co.
- National Oilwell Varco Inc.
- Varel Energy Solutions
- Sandvik AB
- Ulterra Drilling Technologies
- Rockpecker Ltd
- Xi'an Landrill Oil Tools
- Epiroc AB
- Atlas Copco AB
- Drill Master International
- Torquato Drilling Accessories
- PDB Tools Inc.
- Kingdream Public Ltd Co.
- Sichuan Chuanshi Diamond Bits
- NewTech Drilling Products
- Cougar Drilling Solutions
- Baker SPD (specialty)
- Taurex Drill Bits
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shale gas revival in North America
- 4.2.2 Deep-water E&P CAPEX upswing
- 4.2.3 Rapid switch to PDC bits for higher ROP
- 4.2.4 Geothermal well drilling incentives
- 4.2.5 Nascent natural-hydrogen exploration demand
- 4.2.6 Digital-twin-optimised bit design adoption
- 4.3 Market Restraints
- 4.3.1 Oil-price volatility curbing rig counts
- 4.3.2 Stricter environment & flaring rules
- 4.3.3 Synthetic-diamond supply-chain risk
- 4.3.4 Re-manufactured bit cannibalisation
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Roller-Cone Bits
- 5.1.2 Fixed-Cutter Bits
- 5.1.3 Hybrid Bits
- 5.1.4 Specialty Bits (Core, Reaming)
- 5.2 By Location of Deployment
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Application
- 5.3.1 Oil and Gas
- 5.3.2 Mining
- 5.3.3 Geothermal
- 5.3.4 Water-Well and Civil Construction
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Norway
- 5.4.2.6 Russia
- 5.4.2.7 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Egypt
- 5.4.5.6 Nigeria
- 5.4.5.7 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Schlumberger Ltd (Smith Bits)
- 6.4.2 Halliburton Co. (Security DBS)
- 6.4.3 Baker Hughes Co.
- 6.4.4 National Oilwell Varco Inc.
- 6.4.5 Varel Energy Solutions
- 6.4.6 Sandvik AB
- 6.4.7 Ulterra Drilling Technologies
- 6.4.8 Rockpecker Ltd
- 6.4.9 Xi'an Landrill Oil Tools
- 6.4.10 Epiroc AB
- 6.4.11 Atlas Copco AB
- 6.4.12 Drill Master International
- 6.4.13 Torquato Drilling Accessories
- 6.4.14 PDB Tools Inc.
- 6.4.15 Kingdream Public Ltd Co.
- 6.4.16 Sichuan Chuanshi Diamond Bits
- 6.4.17 NewTech Drilling Products
- 6.4.18 Cougar Drilling Solutions
- 6.4.19 Baker SPD (specialty)
- 6.4.20 Taurex Drill Bits
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 礦業和建築鑽探工具市場分析及預測(至2035年):按類型、產品、服務、技術、應用、材料類型、最終用戶、設備和解決方案分類
 礦用鑽頭市場規模、佔有率和成長分析:按產品類型、材質、採礦方法、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 全球礦業鑽頭市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 PDC鑽頭市場-全球產業規模、佔有率、趨勢、機會、預測:按產品、最終用戶、地區和競爭對手分類,2021-2031年安全夾具市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、產品類型、地點、地區和競爭格局分類,2021-2031年
 2034年礦業鑽頭市場預測-按類型、材質、應用、鑽頭尺寸、最終用戶和地區分類的全球分析
 鑽頭市場規模、佔有率和成長分析:按產品類型、材質、尺寸、進入地點、最終用途產業、分銷管道和地區分類-2026-2033年產業預測
 石油和天然氣行業鑽頭市場:按產品和地區分類拋物線齒廓齒輪市場預測至2034年-按類型、材料、應用和地區分類的全球分析鑽頭市場:按產品類型、安裝位置、應用和地區分類