


 |
市場調查報告書
商品編碼
2113319
IC插座:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)IC Socket - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
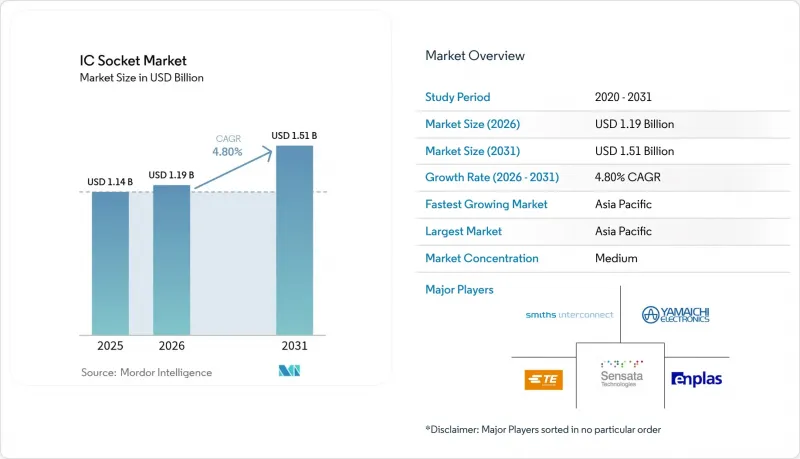
據 Mordor Intelligence 稱,IC 插座市場預計到 2026 年價值 11.9 億美元,高於 2025 年的 11.4 億美元,預計到 2031 年將達到 15.1 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.8%。
本報告按插槽類型(測試和老化、闆對板連接/通孔、高密度 PGA/LGA 等)、IC 封裝類型(DIP、QFP/SOP 等)、應用(CPU 和處理器、內存模組等)、終端用戶行業(家用電子電器、汽車等)以及地區(北美、南美、亞太等)進行細分。市場預測以美元 (USD) 為單位。
全球IC插座市場趨勢與洞察
5G網路的部署正在推動對射頻設備的需求。
全球5G基礎設施的部署正在改變射頻組件插座的設計,其頻率已達到100 GHz,這要求材料既能降低插入損耗,又能保持嚴格的電阻控制。從4G到5G的過渡使每個基地台的射頻組件數量幾乎增加了兩倍,導致最終產品認證和系統級檢驗中對插座的需求增加。毫米波模組中系統級封裝(SiP)的採用進一步擴大了需求,尤其是在北美和歐洲等早期採用地區。
汽車區域架構ECU的普及
將分散式汽車ECU整合到集中式處理中心會增加引腳數量和熱負載,從而推動對符合AEC-Q100標準且能承受更高電流密度的車規級插座的需求。德國、日本和美國支援軟體定義汽車(SDV)的監管政策正在加速這些專用解決方案的普及。
初始模具和探針卡的高成本。
先進的探針卡每套配置的成本超過 50 萬美元,而且由於其亞微米級的接觸幾何形狀,前置作業時間為 16 至 20 週。像 CoWoS 這樣的新型封裝形式需要新的模具,這為無法通過大規模生產攤銷固定成本的小眾插座供應商設置了更高的進入門檻。
細分市場分析
到2025年,測試和老化插座將佔IC插座市場佔有率的33.40%,這反映了業界對品質保證的重視。預計以7.1%的複合年成長率成長的細間距BGA/CSP/WLCSP插座,正在滿足對小型化設備和先進封裝的需求。隨著行動和穿戴式裝置尺寸的不斷縮小,細間距IC插座市場預計將顯著成長。
即使間距小於 0.35 毫米,先進製程節點允許的測試循環次數減少,製造商仍在投資研發高耐久性接點,以延長使用壽命。預測性維護和模組化插件有助於控制整體擁有成本 (TCO),同時保持與不斷發展的測試設備生態系統的兼容性。
由於其散熱效率高、佈線密度高,BGA/μBGA封裝預計在2025年仍將佔據IC插座市場40.40%的佔有率。同時,LGA/PGA/CGA插座的市場佔有率將以6.6%的複合年成長率成長,因為伺服器和汽車設計人員傾向於優先考慮現場可更換的組件。
目前,插座具備可程式設計引腳映射和自適應接觸力功能,使其能夠在單一處理裝置中處理不同類型的封裝,從而減少停機時間和模具成本。儘管供應商為了符合 RoHS 和 REACH 法規而努力保持傳統的電氣性能,但材料的選擇正轉向無鈹合金。
區域分析
預計到2025年,亞太地區將佔據IC插座市場44.40%的佔有率,並在2031年之前以6.3%的複合年成長率成長,這主要得益於區域代工廠的擴張以及政府對半導體自給自足的支持。中國在家用電子電器組裝佔據主導地位,而台灣和韓國則在先進的記憶體和邏輯節點方面展現出優勢。在激勵政策的推動下,印度正逐漸成為注重成本的封裝解決方案的替代方案。
北美佔據第二大市場佔有率,這主要得益於汽車、航太和資料中心產業的需求。台積電在亞利桑那州的工廠和英特爾在俄亥俄州的擴建等國內製造項目預計將擴大本地插槽的採購量。矽谷人工智慧加速器的開發正在推動對高顯存(HBM)封裝的插槽提出一些最嚴格的規格要求。
在歐洲,汽車和工業應用是優先考慮的領域。德國一級供應商正在尋求具有強大熱循環能力的AEC-Q認證插座。法國和荷蘭正在為高密度互連技術的研究和開發做出貢獻。同時,歐洲在環境標準方面的監管主導正促使歐洲買家轉向使用無鈹接觸材料。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 智慧型手機和平板電腦的產量正在激增。
- 5G網路的部署正在推動對射頻設備的需求。
- 配備區域架構的汽車ECU的普及
- AI加速器中的高腳位ASIC
- 晶片封裝技術的快速普及
- OSAT 的已知良好晶片服務的線上測試插座
- 市場限制因素
- 初始模具和探針卡的成本相對較高。
- 先進的節點架構縮短了套接字的生命週期。
- 陶瓷基板供不應求對供應鏈的影響
- 關於鈹銅合金的環境法規
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 價格分析
第5章 市場規模與成長預測
- 按套接字類型
- 測試和老化
- 基板間連接/通孔(DIP、SIP)
- 高密度(PGA/LGA)
- 細間距 BGA/CSP/WLCSP
- 依積體電路封裝類型
- DIP
- QFP/SOP
- BGA/μBGA
- LGA/PGA/CGA
- 透過使用
- CPU 和處理器
- 記憶體模組(DRAM、NAND)
- 感測器設備
- 射頻和類比組件
- 光電子/光子積體電路
- 按最終用戶行業分類
- 家用電子產品
- 車
- 工業自動化
- 電訊和資料通訊
- 航太/國防
- 醫療保健和醫療設備
- 地區
- 北美洲
- 南美洲
- 歐洲
- 亞太地區
- 中東
- 非洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TE Connectivity PLC
- Smiths Interconnect Inc.
- Yamaichi Electronics Co., Ltd.
- Enplas Corporation
- ISC Co., Ltd.
- Sensata Technologies Holding plc
- Ironwood Electronics, Inc.
- Plastronics Socket Company, Inc.
- INNO Global Inc.
- 3M Company
- Amphenol Corp.
- Molex LLC(Koch Industries)
- Foxconn Interconnect Technology Ltd.
- Samtec Inc.
- Loranger International Corp.
- Aries Electronics Inc.
- Mill-Max Manufacturing Corp.
- WinWay Technology Co., Ltd.
- Cohu, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, IC socket market size in 2026 is estimated at USD 1.19 billion, growing from 2025 value of USD 1.14 billion with 2031 projections showing USD 1.51 billion, growing at 4.8% CAGR over 2026-2031.
This report is Segmented by Socket Type (Test and Burn-In, Board-to-Board/Through-Hole, High-Density PGA/LGA, and More), IC Package Type (DIP, QFP/SOP, and More), Application (CPU and Processors, Memory Modules, and More), End-User Industry (Consumer Electronics, Automotive, and More), and Geography (North America, South America, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global IC Socket Market Trends and Insights
5G Network Roll-outs Boosting RF Device Demand
Global 5G infrastructure deployment is reshaping RF component socket design, with frequencies now reaching 100 GHz and requiring materials that reduce insertion loss while maintaining tight impedance control. The shift from 4G to 5G multiplies RF components per base station by roughly three, elevating socket use in both final product qualification and system-level validation. System-in-package adoption for millimeter-wave modules further magnifies demand, particularly across early-adopter regions in North America and Europe.
Automotive Zonal-Architecture ECU Proliferation
Consolidation of distributed automotive ECUs into centralized processing hubs raises pin counts and thermal loads, driving the need for automotive-grade sockets qualified under AEC-Q100 and capable of higher-current densities. Regulatory momentum behind software-defined vehicles in Germany, Japan, and the United States quickens the uptake of these specialized solutions.
High Initial Tooling and Probe-Card Costs
Advanced probe cards exceed USD 500,000 per configuration, with 16-20-week lead times due to sub-micron contact geometries. Emerging packaging formats such as CoWoS demand fresh tooling, raising entry barriers for niche socket providers unable to amortize fixed costs across large volumes.
Other drivers and restraints analyzed in the detailed report include:
- Higher Pin-Count ASICs in AI Accelerators
- Rapid Adoption of Chiplet-Based Packaging
- Supply-Chain Exposure to Ceramic Substrate Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Test and burn-in sockets controlled 33.40% of the IC socket market share in 2025, mirroring the industry's quality-assurance focus. Fine-pitch BGA/CSP/WLCSP sockets, projected at a 7.1% CAGR, cater to device miniaturization and advanced packaging demands. The IC socket market size for fine-pitch variants is forecast to widen notably as mobile and wearable devices shrink form factors.
Manufacturers invest in sub-0.35 mm pitch capabilities and durable contacts that extend useful life across fewer allowable test cycles at advanced nodes. Predictive maintenance and modular inserts help control the total cost of ownership while supporting compatibility with evolving test-handler ecosystems.
BGA/μBGA packages retained 40.40% of the IC socket market size in 2025, linked to their thermal efficiency and interconnect density. LGA/PGA/CGA sockets are gaining at a 6.6% CAGR as server and automotive designers prioritize field-replaceable units.
Sockets now feature programmable pin mapping and adaptive contact force to accommodate mixed package types within a single handler, reducing downtime and tooling spend. Compliance with RoHS and REACH is steering material choices toward beryllium-free alloys, even as suppliers strive to match legacy electrical performance.
Complete Report Scope:
- By Socket Type
- Test and Burn-in
- Board-to-Board / Through-Hole (DIP, SIP)
- High-Density (PGA/LGA)
- Fine-pitch BGA / CSP / WLCSP
- By IC Package Type
- DIP
- QFP / SOP
- BGA / μBGA
- LGA / PGA / CGA
- By Application
- CPU and Processors
- Memory Modules (DRAM, NAND)
- Sensor Devices
- RF and Analog Components
- Optoelectronic / Photonic ICs
- By End-User Industry
- Consumer Electronics
- Automotive
- Industrial and Automation
- Telecommunications and Datacom
- Aerospace and Defense
- Healthcare and Medical Devices
- Geography
- North America
- South America
- Europe
- Asia-Pacific
- Middle East
- Africa
Geography Analysis
Asia-Pacific captured 44.40% of the IC socket market in 2025 and is set to climb at a 6.3% CAGR through 2031 as regional foundries expand and governments subsidize semiconductor self-sufficiency. China dominates consumer electronics assembly, while Taiwan and South Korea excel in advanced memory and logic nodes. India is surfacing as a cost-sensitive packaging alternative, buoyed by incentive schemes.
North America ranks second, anchored by automotive, aerospace, and data-center demand. Domestic manufacturing projects such as TSMC's Arizona fab and Intel's Ohio build-out are poised to increase localized socket procurement. AI accelerator development in Silicon Valley drives some of the most challenging socket specifications for HBM-rich packages.
Europe emphasizes automotive and industrial applications. German tier-1 suppliers require AEC-Q qualified sockets with robust thermal cycling performance. France and the Netherlands contribute to research and development on high-density interconnects. Meanwhile, regulatory leadership in environmental standards pushes European buyers toward beryllium-free contact materials.
- TE Connectivity PLC
- Smiths Interconnect Inc.
- Yamaichi Electronics Co., Ltd.
- Enplas Corporation
- ISC Co., Ltd.
- Sensata Technologies Holding plc
- Ironwood Electronics, Inc.
- Plastronics Socket Company, Inc.
- INNO Global Inc.
- 3M Company
- Amphenol Corp.
- Molex LLC (Koch Industries)
- Foxconn Interconnect Technology Ltd.
- Samtec Inc.
- Loranger International Corp.
- Aries Electronics Inc.
- Mill-Max Manufacturing Corp.
- WinWay Technology Co., Ltd.
- Cohu, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging smartphone and tablet production
- 4.2.2 5G network roll-outs boosting RF device demand
- 4.2.3 Automotive zonal-architecture ECU proliferation
- 4.2.4 Higher pin-count ASICs in AI accelerators
- 4.2.5 Rapid adoption of chiplet-based packaging
- 4.2.6 In-line test sockets for OSAT "known-good-die" services
- 4.3 Market Restraints
- 4.3.1 High initial tooling and probe-card costs
- 4.3.2 Socket life-cycle shortened by advanced nodes
- 4.3.3 Supply-chain exposure to ceramic substrate shortages
- 4.3.4 Environmental regulation on beryllium-copper alloys
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Pricing Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Socket Type
- 5.1.1 Test and Burn-in
- 5.1.2 Board-to-Board / Through-Hole (DIP, SIP)
- 5.1.3 High-Density (PGA/LGA)
- 5.1.4 Fine-pitch BGA / CSP / WLCSP
- 5.2 By IC Package Type
- 5.2.1 DIP
- 5.2.2 QFP / SOP
- 5.2.3 BGA / μBGA
- 5.2.4 LGA / PGA / CGA
- 5.3 By Application
- 5.3.1 CPU and Processors
- 5.3.2 Memory Modules (DRAM, NAND)
- 5.3.3 Sensor Devices
- 5.3.4 RF and Analog Components
- 5.3.5 Optoelectronic / Photonic ICs
- 5.4 By End-User Industry
- 5.4.1 Consumer Electronics
- 5.4.2 Automotive
- 5.4.3 Industrial and Automation
- 5.4.4 Telecommunications and Datacom
- 5.4.5 Aerospace and Defense
- 5.4.6 Healthcare and Medical Devices
- 5.5 Geography
- 5.5.1 North America
- 5.5.2 South America
- 5.5.3 Europe
- 5.5.4 Asia-Pacific
- 5.5.5 Middle East
- 5.5.6 Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TE Connectivity PLC
- 6.4.2 Smiths Interconnect Inc.
- 6.4.3 Yamaichi Electronics Co., Ltd.
- 6.4.4 Enplas Corporation
- 6.4.5 ISC Co., Ltd.
- 6.4.6 Sensata Technologies Holding plc
- 6.4.7 Ironwood Electronics, Inc.
- 6.4.8 Plastronics Socket Company, Inc.
- 6.4.9 INNO Global Inc.
- 6.4.10 3M Company
- 6.4.11 Amphenol Corp.
- 6.4.12 Molex LLC (Koch Industries)
- 6.4.13 Foxconn Interconnect Technology Ltd.
- 6.4.14 Samtec Inc.
- 6.4.15 Loranger International Corp.
- 6.4.16 Aries Electronics Inc.
- 6.4.17 Mill-Max Manufacturing Corp.
- 6.4.18 WinWay Technology Co., Ltd.
- 6.4.19 Cohu, Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


