


 |
市場調查報告書
商品編碼
2100620
體育領域的人工智慧:市場佔有率分析、產業趨勢與統計數據及成長預測(2026-2031)Artificial Intelligence In Sports - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
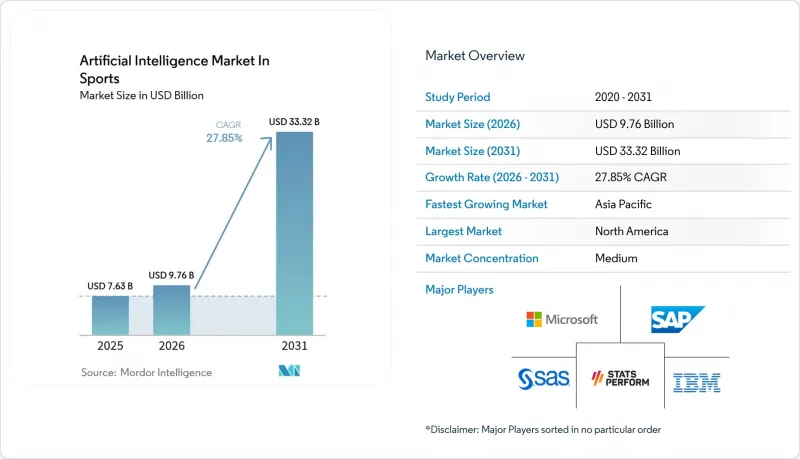
據 Mordor Intelligence 稱,2025 年體育人工智慧 (AI) 市場價值為 76.3 億美元,預計到 2031 年將達到 333.2 億美元,而 2026 年為 97.6 億美元,預測期(2026-2031 年)的複合年成長率為 27.85%。
本報告按應用領域(例如,球員分析、球迷互動、教練指導和比賽策略)、組件(軟體、服務)、部署方式(本地部署、雲端部署)、技術(例如,機器學習和深度學習)以及地區(北美、歐洲、亞太、南美以及中東和非洲)進行細分。市場預測以美元計價。
體育人工智慧市場洞察與趨勢
即時效能分析的需求日益成長
即時分析正從賽後數據看板轉向邊緣運算系統,為教練提供逐秒回饋。 Sportradar 2024 年第一季季營收年增 28%,凸顯了即時資料饋送的商業性發展動能。洛杉磯公羊隊與 SprintAI 合作,部署了 Google Cloud 平台,集中存儲生物識別數據和戰術影片,使工作人員即使在比賽進行中也能調整戰術。邊緣設備在體育場內處理敏感數據,使球隊能夠在不增加資料外洩風險的前提下提高處理速度。這項措施在競爭優勢和隱私合規之間取得了平衡,加速了人工智慧在對抗性運動中的應用,因為在這些運動中,瞬間的決策往往決定勝負。
人工智慧驅動的粉絲互動解決方案的快速普及
如今,廣播公司和聯賽正將投注Widgets、自動生成的精彩集錦和聊天機器人整合到直播內容中,將被動觀眾轉化為付費的熱情粉絲。 Genius Sports 的「GeniusIQ」平台結合了光學追蹤和生成式內容技術,為「BetVision」提供支持,將NFL直播影像與互動投注相結合。 ESPN正在利用生成式人工智慧技術製作長曲棍球和女子足球比賽的即時摘要,在降低編輯成本的同時提升了觀眾參與度。像Cerebro Sports這樣的新創公司正在將人工智慧聊天機器人應用於基層籃球賽事,拓展獲取球迷數據的途徑。獲利模式主要依賴定向廣告和微交易,而互動軟體則是核心收入來源。
端對端實施成本高昂
全面實施人工智慧需要攝影機、感測器、雲端容量和熟練的專業人員,導致總成本超過初始授權費用。將硬體和軟體即服務 (SaaS) 結合的混合服務,例如 TrackMan 的模擬器和軟體訂閱服務,可以緩解高額前期成本帶來的衝擊,但同時也讓使用者需要支付多年費用。遷移到雲端可以減輕財務負擔,但整合和變更管理仍然需要外部顧問,而這些顧問的費用可能會對半專業團隊的預算造成負擔。
細分市場分析
在運動人工智慧市場中,「提升運動表現」佔最大佔有率,預計到2025年將達到31.70%,顯示各隊伍正優先考慮透過數據驅動的洞察來提升競爭優勢。同時,「傷病預防」領域預計將以33.25%的複合年成長率成長,因為各俱樂部都在量化關鍵球員缺席所帶來的成本。與健康分析密切相關的體育人工智慧市場預計將進一步擴張,因為預測演算法能夠及早發現疲勞,使醫務人員能夠在輕微肌肉拉傷惡化之前進行干預。自動產生精彩集錦影像、基於聊天功能的球迷服務和裁判輔助工具也在推動市場需求,但這些領域的支出仍然落後於提升運動表現和傷害預防模組。
向預防性健康管理的轉變反映了保險經濟的原則。穿戴式遙測技術與電腦視覺技術結合,能夠識別肌肉斷裂領先身體失衡和減速的突然變化。設有薪資上限的聯賽可以直接受益於避免高薪球員的長期缺陣,從而推動了這項技術在各組織中的應用。同時,球迷互動機器人能夠從比賽資料集中學習,並產生符合各俱樂部獨特風格的內容,從而在運動和商業上都取得成功。
由於成熟的分析套件,軟體已佔據體育人工智慧 (AI) 市場 60.85% 的佔有率,預計到 2025 年將達到 46.5 億美元。然而,服務領域預計將以 33.10% 的複合年成長率快速成長,超過純產品銷售的成長速度。各俱樂部現在意識到,僅靠儀錶板不足以確保勝利,他們需要資料工程師、運動科學家和轉型經理。在體育 AI 市場,隨著供應商將持續最佳化和合規性監控功能整合到其平台中,託管服務的市場佔有率正在不斷成長。
SprintAI 的服務模式包括配備駐場績效顧問,與教練團隊並肩工作。實踐證明,業務收益通常超過許可費。客製化整合方案可連接來自 GPS 背心、體育場館雷射雷達攝影機和電子健康記錄(EMR) 系統的資料饋送。由於這些部署需要投入大量精力,即使軟體模組變得更加方便用戶使用,預計到 2031 年,對該服務的需求仍將持續存在。
區域分析
2024年,北美地區的運動支出最高,這主要得益於成熟的職業聯賽、強勁的贊助收入以及對雲端分析技術的早期應用。隨著專有資料集支持微投注和即時商品銷售提案等新的收入來源,特許經營權的估值也隨之飆升。擁有者、廣播公司和體育博彩公司之間的合作進一步加速了商業化的良性循環。儘管監管力度仍然不足,但提案即將訂定的聯邦隱私立法,各俱樂部正在加強加密和用戶許可管理的投資。
在亞太地區,政府主導的基礎建設和本土設備供應鏈正在降低成本,從而推動市場快速擴張。政府津貼支持在全國各地培訓中心建立人工智慧研究實驗室,通訊業者也提供與體育賽事專屬服務等級協定 (SLA) 捆綁的 5G 邊緣服務。智慧型手機的高普及率使得面向粉絲的發送類型內容成為可能,從而能夠觸達此前無法透過傳統電視觸及的本地受眾,並實現盈利。隨著香港啟德體育公園等類似場館的開放,公共採購中採用人工智慧遙測平台將成為一項強制性要求,這將進一步擴大該地區在體育人工智慧市場的佔有率。
在歐洲,創新與嚴格的隱私法正在融合。俱樂部需要根據GDPR的限制來建立人工智慧系統,這推動了對本地處理和聯合分析的需求。國家足球聯賽正與供應商合作開發隱私保護的影像識別模型,這些模型能夠在源頭移除攝影機拍攝影片中的識別碼。歐盟委員會對「可信任人工智慧實驗室」的支持為可解釋演算法的開發提供津貼,使得能夠對其模型進行認證的供應商獲得合規性優勢。語言多樣性和跨境版權協議增加了複雜性,同時也推動了對自動在地化和多語言說明機器人的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 即時效能分析的需求日益成長
- 人工智慧驅動的粉絲互動解決方案的快速普及
- 擴展價格合理的雲端人工智慧服務
- 利用穿戴式裝置和物聯網的運動員追蹤科技的普及
- 數位孿生評估模型在偵察領域的興起
- 透過人工智慧產生的短內容實現獲利
- 市場限制因素
- 端到端實施成本相對較高。
- 體育人工智慧領域人才短缺
- 關於生物識別資料的新隱私法規
- GPU供應鏈集中化與成本波動
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過使用
- 球員分析
- 粉絲互動
- 教練和比賽策略
- 廣播和媒體製作
- 裁判和營運支持
- 營運和場地管理
- 按組件
- 軟體
- 服務
- 託管服務
- 專業服務
- 不同的發展
- 現場
- 雲
- 透過技術
- 機器學習和深度學習
- 電腦視覺
- 自然語言處理
- 數據分析平台
- 邊緣人工智慧和即時串流媒體
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Stats Perform
- Sportradar AG
- IBM Corporation
- SAP SE
- Catapult Group International Ltd
- SAS Institute Inc.
- TruMedia Networks Inc.
- Salesforce Inc.(Tableau)
- Microsoft Corporation
- Meta Platforms Inc.
- Hudl(Agile Sports Technologies)
- Kinexon GmbH
- TrackMan A/S
- Zebra Technologies Corp.
- Kitman Labs Ltd
- Oracle Corp.
- Zebra Technologies Corp.
- Orreco Ltd
- Zebra Technologies Corp.
- PlaySight Interactive Ltd
- EXL Service Holdings Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the artificial intelligence market size in sports market was valued at USD 7.63 billion in 2025 and estimated to grow from USD 9.76 billion in 2026 to reach USD 33.32 billion by 2031, at a CAGR of 27.85% during the forecast period (2026-2031).
This report is Segmented by Application (Player Analysis, Fan Engagement, Coaching and Game Strategy, and More), Component (Software, Services), Deployment (On-Premises, Cloud), Technology (Machine Learning and Deep Learning, and More), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Insights and Trends of Artificial Intelligence Market In Sports
Growing demand for real-time performance analytics
Real-time analytics has migrated from post-game dashboards to edge-enabled systems that deliver second-by-second feedback to coaches. Sportradar's 28% year-over-year revenue jump in Q1 2024 underscores commercial traction for live data feeds. The Los Angeles Rams collaborated with SprintAI on a Google Cloud platform that centralizes biometrics and tactical video, letting staff adjust workloads mid-drive. Edge devices process sensitive data in-stadium, so teams gain speed without risking leaks. This practice blends competitive advantage with privacy compliance, accelerating adoption across contact sports where split-second calls decide outcomes.
Rapid adoption of AI-driven fan-engagement solutions
Broadcasters and leagues now embed betting widgets, auto-generated highlights, and chatbots into streams to convert passive spectators into paying superfans. Genius Sports' GeniusIQ platform fuses optical tracking with generative content to power BetVision, integrating live NFL video and interactive wagers. ESPN applies generative AI to craft real-time recaps for lacrosse and women's soccer, cutting editing costs while lifting engagement. Start-ups such as Cerebro Sports bring AI chatbots to grassroots basketball, widening the fan-data funnel. Monetization stems from targeted ads and micro-transactions, turning engagement software into a core revenue pillar.
High end-to-end implementation cost
Comprehensive AI rollouts demand cameras, sensors, cloud capacity, and skilled staff, lifting total cost beyond initial license fees. Hybrid offerings that bundle hardware and SaaS, such as TrackMan's simulator plus software subscription, mitigate sticker shock yet lock buyers into multi-year payments. Cloud migration eases capital strain, but integration and change management still require external consultants whose fees weigh on semi-pro budgets.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of affordable cloud-based AI services
- Proliferation of wearables and IoT athlete tracking
- Shortage of sports-AI talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Performance Improvement captured the largest slice of the Artificial Intelligence Market in sports, with a market share of 31.70% in 2025, indicating that teams prioritize a competitive edge from data-driven insights. Injury Prevention, however, will expand at a 33.25% CAGR as clubs quantify the cost of sidelined stars. The Artificial Intelligence Market in Sports, tied to health analytics, is projected to multiply as predictive algorithms flag fatigue early, allowing medical staff to intervene before minor strains escalate. Automated highlight creation, chat-based fan services, and referee assistance tools further boost demand but still trail performance and injury modules in spending.
The shift toward preemptive health management reflects the economics of insurance. Wearable telemetry integrates with computer vision video to identify asymmetries and deceleration spikes that precede muscle tears. Salary-cap leagues reap direct financial benefits when high-paid athletes avoid lengthy layoffs, thereby incentivizing enterprise-wide buy-in. Meanwhile, fan-engagement bots draw lessons from performance datasets to generate content in a voice authentic to each club, blending both sporting and commercial outcomes.
Software retained 60.85% of the Artificial Intelligence Market in sports, with a market size of $4.65 billion in 2025, thanks to established analytics suites. However, services will surge at a 33.10% CAGR, outstripping pure product sales. Clubs now understand that dashboards alone do not translate into wins; they need data engineers, sports scientists, and change managers. The Artificial Intelligence Market in Sports; market share for managed services, therefore, rises as vendors wrap continuous optimization and compliance monitoring around their platforms.
SprintAI's delivery model includes onsite performance consultants embedded with coaching staff, illustrating how services revenue often eclipses licensing fees. Custom integrations align feeds from GPS vests, LIDAR stadium cameras, and medical EMR systems. The labor-intensive nature of these rollouts underpins sustained demand for services through 2031, even as software modules become more user-friendly.
Complete Report Scope:
- By Application
- Player Analysis
- Fan Engagement
- Coaching and Game Strategy
- Broadcast and Media Production
- Refereeing and Officiating Support
- Operations and Venue Management
- By Component
- Software
- Services
- Managed Services
- Professional Services
- By Deployment
- On-Premises
- Cloud
- By Technology
- Machine Learning and Deep Learning
- Computer Vision
- Natural Language Processing
- Data-Analytics Platforms
- Edge AI and Real-Time Streaming
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated the highest spending in 2024, driven by established professional leagues, robust sponsorship dollars, and early adoption of cloud analytics. Franchise valuations balloon when proprietary datasets underpin new revenue categories such as micro-betting and real-time merchandise offers. Collaborations among rights-holders, broadcasters, and sportsbooks sharpen the commercialization flywheel. Regulatory oversight remains light-touch, but looming federal privacy proposals prompt clubs to invest in encryption and consent management.
The Asia-Pacific region is scaling swiftly as state-sponsored infrastructure and domestic device supply chains cut costs. Government grants subsidize AI labs in national training centers, and telecom operators bundle 5G edge services with sports-specific SLAs. High smartphone penetration enables direct-to-fan micro-content that monetizes rural viewers who were previously unreachable through linear TV. The region's share of the Artificial Intelligence in Sports market size is expected to widen once Kai Tak Sports Park in Hong Kong and similar complexes open, as public procurement often mandates AI telemetry platforms.
Europe blends innovation with stringent privacy statutes. Clubs must architect AI systems around GDPR constraints, elevating demand for on-premise processing and federated analytics. National football leagues partner with tech vendors on privacy-preserving vision models that strip identifiers at the camera source. The European Commission's backing for trustworthy AI labs channels grants toward the development of explainable algorithms, making compliance a competitive edge for vendors able to certify their models. Language diversity and cross-border rights deals add complexity, yet also drive demand for automated localization and multilingual commentary bots.
- Stats Perform
- Sportradar AG
- IBM Corporation
- SAP SE
- Catapult Group International Ltd
- SAS Institute Inc.
- TruMedia Networks Inc.
- Salesforce Inc. (Tableau)
- Microsoft Corporation
- Meta Platforms Inc.
- Hudl (Agile Sports Technologies)
- Kinexon GmbH
- TrackMan A/S
- Zebra Technologies Corp.
- Kitman Labs Ltd
- Oracle Corp.
- Zebra Technologies Corp.
- Orreco Ltd
- Zebra Technologies Corp.
- PlaySight Interactive Ltd
- EXL Service Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for real-time performance analytics
- 4.2.2 Rapid adoption of AI-driven fan-engagement solutions
- 4.2.3 Expansion of affordable cloud-based AI services
- 4.2.4 Proliferation of wearables and IoT athlete tracking
- 4.2.5 Rise of digital-twin valuation models for scouting
- 4.2.6 Monetisation via AI-generated short-form content
- 4.3 Market Restraints
- 4.3.1 High end-to-end implementation cost
- 4.3.2 Shortage of sports-AI talent
- 4.3.3 Emerging biometric-data privacy restrictions
- 4.3.4 GPU supply-chain concentration and cost volatility
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Player Analysis
- 5.1.2 Fan Engagement
- 5.1.3 Coaching and Game Strategy
- 5.1.4 Broadcast and Media Production
- 5.1.5 Refereeing and Officiating Support
- 5.1.6 Operations and Venue Management
- 5.2 By Component
- 5.2.1 Software
- 5.2.2 Services
- 5.2.2.1 Managed Services
- 5.2.2.2 Professional Services
- 5.3 By Deployment
- 5.3.1 On-Premises
- 5.3.2 Cloud
- 5.4 By Technology
- 5.4.1 Machine Learning and Deep Learning
- 5.4.2 Computer Vision
- 5.4.3 Natural Language Processing
- 5.4.4 Data-Analytics Platforms
- 5.4.5 Edge AI and Real-Time Streaming
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Italy
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Israel
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 United Arab Emirates
- 5.5.5.1.4 Turkey
- 5.5.5.1.5 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Stats Perform
- 6.4.2 Sportradar AG
- 6.4.3 IBM Corporation
- 6.4.4 SAP SE
- 6.4.5 Catapult Group International Ltd
- 6.4.6 SAS Institute Inc.
- 6.4.7 TruMedia Networks Inc.
- 6.4.8 Salesforce Inc. (Tableau)
- 6.4.9 Microsoft Corporation
- 6.4.10 Meta Platforms Inc.
- 6.4.11 Hudl (Agile Sports Technologies)
- 6.4.12 Kinexon GmbH
- 6.4.13 TrackMan A/S
- 6.4.14 Zebra Technologies Corp.
- 6.4.15 Kitman Labs Ltd
- 6.4.16 Oracle Corp.
- 6.4.17 Zebra Technologies Corp.
- 6.4.18 Orreco Ltd
- 6.4.19 Zebra Technologies Corp.
- 6.4.20 PlaySight Interactive Ltd
- 6.4.21 EXL Service Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球運動人工智慧市場:機會與策略展望(至2035年)
 2034年體育分析人工智慧市場預測:全球分析(按組件、技術、部署模式、運動項目、應用、最終用戶和地區分類)
 體育領域人工智慧市場:按組件、部署、應用和區域分類
 體育領域人工智慧市場:按交付方式、技術類型、應用和最終用戶分類的全球市場預測 – 2026-2032 年2026年全球運動領域生成式人工智慧市場報告
 體育領域人工智慧市場規模、佔有率和趨勢分析報告:按服務類型、技術、運動項目、地區和細分市場分類的預測(2026-2033 年)
 全球虛擬體育市場規模、佔有率、趨勢和成長分析報告(2026-2034)虛擬運動市場-2026-2031年預測
 體育領域人工智慧市場規模、佔有率和成長分析(按組件、應用、部署和地區分類)—產業預測,2026-2033年
 全球虛擬運動市場