


 |
市場調查報告書
商品編碼
2097180
KVM切換器:市佔率分析、產業趨勢與統計、成長預測(2026-2031年)KVM Switch - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年 KVM 切換器市值為 8.6 億美元,預計到 2031 年將從 2026 年的 8.9 億美元成長至 10.2 億美元,預測期(2026-2031 年)的複合年成長率為 2.85%。
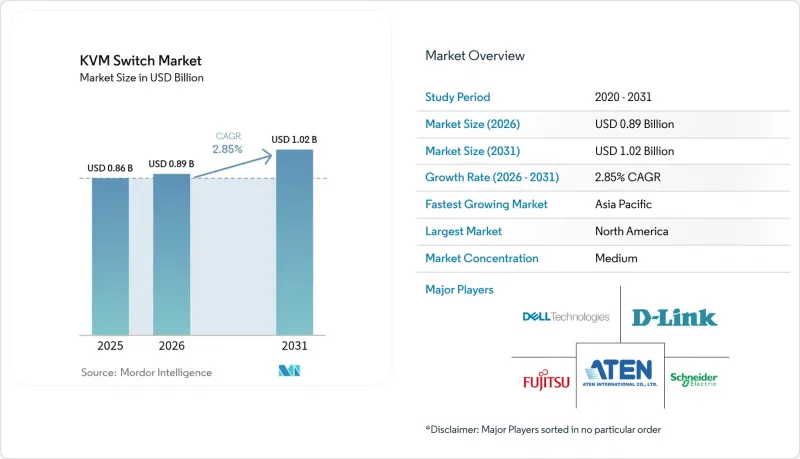
本報告按產品類型(標準桌上型電腦、安全桌上型電腦、機架式等)、用戶類型(單一用戶、多用戶)、最終用戶產業(IT/電信/資料中心、工業自動化等)、連接介面(類比(VGA)、數位(DVI/HDMI)等)和地區進行細分。市場預測以美元(USD)計價。
全球KVM切換器市場趨勢及洞察
雲端遷移和超大規模資料中心擴展
由於軟體無法在網路故障期間控制 BIOS 等級或電源重新啟動操作,超大規模營運商仍在持續採購硬體 KVM 平台。 Vertiv 在 2024 年第三季實現了 37% 的有機訂單成長,其中與需要帶外訪問的 AI 設施相關的累積訂單高達 74 億美元。私募股權交易,例如黑石集團以 160 億美元收購 AirTrunk,清楚地表明了投資者對與軟體編配相輔相成的實體管理層的信心。根據 CommScope 的報告,光纖密度正迅速向 400G、800G 和 1.6T 轉變,這增加了基礎設施的複雜性,並推動了對可靠本地交換架構的需求。
擴大國防和政府機構安全桌面系統的應用
公部門機構依賴經NIAP認證的硬體來維護空氣間隙和敏感環境,而依賴網路的工具無法通過安全審計。 Raritan提供符合美國和歐盟國防要求的FIPS 140-2加密和通用存取卡(CAC)登入功能。 Adder Technologies的主機允許指揮中心在單一操作員桌面上可視化不同保密等級的數據,從而避免混合保密資訊造成的污染風險。採購週期緩慢且以價值為導向。系統部署後,即使經過五年以上的更新周期,仍能保持運行,從而確保隨著認證標準的演變,系統能夠持續更新。
軟體遠端桌面替代方案的激增。
注重成本的企業現在正考慮採用整合虛擬機器管理程式的主機,這種控制台無需單獨的硬體。惠普企業(HPE)在VMware調整價格後推出的KVM為基礎的解決方案,標誌著向訂閱模式的轉變。軟體產品組合更新速度更快,並與監控套件整合,降低了簡單任務的營運成本。然而,由於持續面臨網路故障、延遲峰值以及網路攻擊目標範圍擴大等風險,其在關鍵任務機架中的應用受到限制。
細分市場分析
預計到2025年,標準桌面平台將佔總銷售額的23.05%,反映出市場對簡單、低成本伺服器存取的持續需求。雖然安全桌面設備的絕對數量較小,但隨著政府機構加強工作站集群的安全性以及企業正式實施零信任藍圖,預計到2031年,其市場佔有率將超過標準桌面平台。政府框架強制要求通用準則認證,這反過來又推動了對FIPS認證晶片組和防篡改電路的採購,從而推高了它們的標價。採用專有壓縮技術的高效能設備在廣播攝影棚、模擬實驗室和航太測試設備等領域越來越受歡迎,因為在這些領域,幀完整性和亞毫秒延遲對於操作效率至關重要。同時,機架式設備在對密度要求嚴格的託管資料中心也越來越受歡迎,因為這些資料中心通常採用機架式交換器佈局,且電纜長度有限。
Raritan 的加密設計表明,向安全桌面格式的過渡使得以前在通用硬體上無法使用的程式得以應用,從而保護敏感資料流免受惡意 USB 注入攻擊和螢幕抓取惡意軟體的侵害。
至2025年,單一用戶架構將佔全球支出的52.20%,主要用於獨立機架、小規模實驗室或安全機房等封閉式環境。隨著大型企業集中管理其支援團隊,具備矩陣交換和動態會話切換功能的多用戶框架正以4.85%的複合年成長率快速成長。雲端服務供應商目前提供全天候維護服務,並由多個大洲的團隊進行管理,這要求不同班次的負責人能夠同時直接存取同一台實體主機。
Guntermann 和 Drunck 的「FreeSeating」功能可實現操作員之間的無縫切換,降低登入延遲,並在非工作時間釋放未使用的運算資源。隨著託管服務供應商將硬體整合到打包式託管服務中,針對多用戶設備的 KVM 切換器市場預計將進一步擴張,為客戶提供無需人工干預的遠端控制,同時保持空氣間隙隔離。在安全允許的情況下,透過共用矩陣將多個管理員集中起來,可以降低每個席位的資本成本,提高利用率,並提升託管資料中心的整體盈利。
區域分析
到2025年,北美將佔全球整體銷售額的23.20%。該地區的需求與超大規模園區更新周期、聯邦網路安全指令的合規性以及國防設施的持續升級密切相關。 Vertiv 2025年第一季20.4億美元的銷售額凸顯了公共雲端的持續擴張,以及人工智慧硬體的普及,而這些硬體需要可靠的外層支援。在加拿大,永續資料中心的投資激勵措施正在推動需求成長;而在墨西哥,面向出口的製造地正在部署KVM解決方案,以支援遠端生產線診斷。
亞太地區是成長最快的地區,預計到2031年複合年成長率將達到3.55%。該地區的裝置容量已超過12.2吉瓦,KKR和貝恩資本等機構投資者持續在新加坡、中國和印尼收購資產,為多年建設計畫奠定基礎。隨著超大規模資料中心開發商指定硬體控制點以滿足災害復原合規性要求,KVM切換器市場正從中直接受益。同時,印度和東協的通訊業者正在部署與5G切片連接的邊緣微型設施,這推動了對能夠承受戶外高溫高濕環境的堅固耐用設備的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 雲端遷移和超大規模資料中心擴展
- 擴大國防和政府部門安全桌面系統的應用
- 遠端IT運維對KVM over IP的需求正在激增。
- 邊緣資料中心和微型資料中心的部署推動了對強大、高效能 KVM 的需求。
- 人工智慧驅動的預測性維護帶來的新價值。
- 市場限制因素
- 軟體遠端桌面替代方案的激增。
- 遺留站點整合的初始成本高且複雜。
- 高解析度視訊專用積體電路(ASIC)半導體供應鏈的波動
- KVM over IP部署中的網路延遲和頻寬限制
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 供應商的議價能力
- 消費者議價能力
- 新進入者的威脅
- 競爭公司之間的競爭
- 替代品的威脅
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 依產品類型
- 標準桌面
- 安全桌面
- 內拉克
- KVM-over-IP
- 其他類型
- 依使用者類型
- 單一用戶
- 多用戶
- 按最終用戶行業分類
- IT/電信/資料中心
- 工業自動化
- 政府/國防
- 衛生保健
- 媒體與娛樂
- 其他
- 連接介面
- 模擬(VGA)
- 數位(DVI/HDMI)
- DisplayPort/USB-C
- KVM-over-IP
- NIAP認證安全
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ATEN International
- Fujitsu Limited
- D-Link Corporation
- Dell Technologies Inc.
- Schneider Electric SE
- Hewlett Packard Enterprise
- Belkin International Inc.
- Vertiv Group(Avocent)
- Tripp Lite
- Guntermann and Drunck GmbH
- IHSE GmbH
- Black Box Corporation
- Raritan(Legrand)
- Adder Technology Ltd.
- Rose Electronics
- IOGEAR
- Tesla Elec Technology Co., Ltd.
- Rextron International Inc.
- SmartAVI Inc.
- Thinklogical LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the KVM switch market size was valued at USD 0.86 billion in 2025 and estimated to grow from USD 0.89 billion in 2026 to reach USD 1.02 billion by 2031, at a CAGR of 2.85% during the forecast period (2026-2031).
This report is Segmented by Product Type (Standard Desktop, Secure Desktop, in Rack, and More), User Type (Single-User, Multi-User), End User Industry (IT and Telecom/Data Centers, Industrial Automation, and More), Connectivity Interface (Analog (VGA), Digital (DVI/HDMI), and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global KVM Switch Market Trends and Insights
Cloud Migration and Hyperscale Data-Center Build-Outs
Hyperscale operators continue to procure hardware KVM platforms because software cannot provide BIOS-level or power-cycle control during network outages. Vertiv recorded 37% organic orders growth in Q3 2024 and a USD 7.4 billion backlog linked to AI-ready facilities where out-of-band access is mandatory. Private-equity transactions such as Blackstone's USD 16 billion AirTrunk acquisition illustrate investor confidence in physical management layers that complement software orchestration. CommScope reports fiber densities moving rapidly toward 400G, 800G, and 1.6T, compounding infrastructure complexity and reinforcing demand for reliable local switching fabric.
Rising Secure-Desktop Adoption in Defense and Government
Public-sector agencies rely on NIAP-certified hardware to maintain air-gapped and classified environments where network-dependent tools fail security audits. Raritan offers FIPS 140-2 encryption and Common Access Card log-ins that meet U.S. and EU defense requirements. Adder Technology's consoles help command centers visualize multi-classification data on a single operator desk without risking crossover contamination. Procurement cycles are slower but value-focused; once installed, systems remain in service beyond five-year refresh periods, locking in a steady replacement pipeline as certification standards evolve.
Proliferation of Software-Based Remote-Desktop Alternatives
Cost-driven enterprises now consider hypervisor-embedded consoles that eliminate discrete hardware; Hewlett Packard Enterprise's KVM-based solution, launched after VMware's pricing reset, exemplifies the shift toward subscription-style models. Software portfolios iterate faster and integrate with monitoring suites, lowering operating overhead for uncomplicated tasks. However, they remain exposed to network failures, latency spikes, and broader cyber-attack surfaces that limit use in mission-critical racks.
Other drivers and restraints analyzed in the detailed report include:
- Demand Surge for KVM-over-IP for Remote IT Operations
- Edge Micro-Data-Center Deployments Driving Ruggedized High-Performance KVM
- High Upfront Cost and Integration Complexity in Legacy Sites
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard desktop platforms delivered 23.05% of 2025 revenue, reflecting ongoing demand for straightforward, low-priced server access. Secure-desktop devices, though smaller in absolute terms, are set to outpace them through 2031 as agencies harden workstation fleets and enterprises formalize zero-trust roadmaps. Government frameworks mandate Common Criteria certifications, pushing procurement toward FIPS-validated chipsets and tamper-resistant circuitry that justify list-price premiums. High-performance units with proprietary compression rise in broadcast studios, simulation labs and aerospace test rigs where frame integrity and sub-millisecond latency govern operator effectiveness. In-rack models meanwhile capture density-focused colocation halls where cable length constraints meet top-of-rack switch layouts.
Raritan's crypto-enabled designs exemplify how moving to secure-desktop formats can unlock programs previously closed to generic hardware, shielding sensitive data flows from unauthorized USB injection attacks and screen-scraping malware
Single-user architectures claimed 52.20% of global spending in 2025, favored for isolated racks, small labs or enclave-style secure rooms. Multi-user frames, hosting matrix switching and dynamic session hand-offs, are expanding at a 4.85% CAGR as large enterprises centralize support teams. Cloud operators now run around-the-clock maintenance windows administered from multiple continents, necessitating concurrent doorstep access to the same physical host from different shifts.
Guntermann and Drunck's FreeSeating function showcases seamless transition between operators, reducing log-in delays and freeing unused compute cycles during off-hours. The KVM switch market size for multi-user equipment is projected to widen further as managed-service providers fold hardware into packaged colocation offers, giving customers hands-off remote control while preserving air-gapped independence. Where security allows, pooling several admins through a shared matrix lowers capital cost per seat and improves utilization, supporting the overall profitability of managed data-center footprints.
Complete Report Scope:
- By Product Type
- Standard Desktop
- Secure Desktop
- In-rack
- KVM-over-IP
- Other Types
- By User Type
- Single-User
- Multi-User
- By End-User Industry
- IT and Telecom / Data Centers
- Industrial Automation
- Government and Defense
- Healthcare
- Media and Entertainment
- Others
- By Connectivity Interface
- Analog (VGA)
- Digital (DVI/HDMI)
- DisplayPort / USB-C
- KVM-over-IP
- NIAP-certified Secure
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 23.20% of global revenue in 2025. Demand here is tied to refresh cycles in hyperscale campuses, compliance with federal cybersecurity directives and ongoing upgrades in defense facilities. Vertiv's USD 2.04 billion Q1 2025 revenue underscores sustained public-cloud expansions coupled with AI hardware rollouts that require dependable out-of-band layers. Canada contributes incremental volume through investment incentives for sustainable data centers, while Mexico's manufacturing corridors adopt KVM solutions to support remote line diagnostics in export-oriented plants.
Asia-Pacific is the fastest-growing territory at a 3.55% CAGR through 2031. Regional capacity has already exceeded 12.2 GW, and institutional investors such as KKR and Bain Capital continue to acquire assets across Singapore, China and Indonesia, anchoring multi-year build pipelines. The KVM switch market benefits directly as hyperscale developers specify hardware control points for disaster-recovery compliance. In parallel, telcos in India and ASEAN roll out edge micro-facilities tied to 5G slices, spurring demand for ruggedized units able to tolerate outdoor heat and humidity.
- ATEN International
- Fujitsu Limited
- D-Link Corporation
- Dell Technologies Inc.
- Schneider Electric SE
- Hewlett Packard Enterprise
- Belkin International Inc.
- Vertiv Group (Avocent)
- Tripp Lite
- Guntermann and Drunck GmbH
- IHSE GmbH
- Black Box Corporation
- Raritan (Legrand)
- Adder Technology Ltd.
- Rose Electronics
- IOGEAR
- Tesla Elec Technology Co., Ltd.
- Rextron International Inc.
- SmartAVI Inc.
- Thinklogical LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud migration and hyperscale data-center build-outs
- 4.2.2 Rising secure-desktop adoption in defense and government
- 4.2.3 Demand surge for KVM-over-IP for remote IT operations
- 4.2.4 Edge micro-data-center deployments driving ruggedized high-perf KVM
- 4.2.5 AI-driven predictive-maintenance integration unlocking new value
- 4.3 Market Restraints
- 4.3.1 Proliferation of software-based remote-desktop alternatives
- 4.3.2 High upfront cost and integration complexity in legacy sites
- 4.3.3 Semiconductor supply-chain volatility for high-res video ASICs
- 4.3.4 Network latency and bandwidth limitations for KVM-over-IP deployments
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Force Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 Assesment of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Standard Desktop
- 5.1.2 Secure Desktop
- 5.1.3 In-rack
- 5.1.4 KVM-over-IP
- 5.1.5 Other Types
- 5.2 By User Type
- 5.2.1 Single-User
- 5.2.2 Multi-User
- 5.3 By End-User Industry
- 5.3.1 IT and Telecom / Data Centers
- 5.3.2 Industrial Automation
- 5.3.3 Government and Defense
- 5.3.4 Healthcare
- 5.3.5 Media and Entertainment
- 5.3.6 Others
- 5.4 By Connectivity Interface
- 5.4.1 Analog (VGA)
- 5.4.2 Digital (DVI/HDMI)
- 5.4.3 DisplayPort / USB-C
- 5.4.4 KVM-over-IP
- 5.4.5 NIAP-certified Secure
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Southeast Asia
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ATEN International
- 6.4.2 Fujitsu Limited
- 6.4.3 D-Link Corporation
- 6.4.4 Dell Technologies Inc.
- 6.4.5 Schneider Electric SE
- 6.4.6 Hewlett Packard Enterprise
- 6.4.7 Belkin International Inc.
- 6.4.8 Vertiv Group (Avocent)
- 6.4.9 Tripp Lite
- 6.4.10 Guntermann and Drunck GmbH
- 6.4.11 IHSE GmbH
- 6.4.12 Black Box Corporation
- 6.4.13 Raritan (Legrand)
- 6.4.14 Adder Technology Ltd.
- 6.4.15 Rose Electronics
- 6.4.16 IOGEAR
- 6.4.17 Tesla Elec Technology Co., Ltd.
- 6.4.18 Rextron International Inc.
- 6.4.19 SmartAVI Inc.
- 6.4.20 Thinklogical LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 可攜式KVM切換器市場規模、佔有率和成長分析:按產品類型、介面、連接方式、最終用戶、銷售管道和地區分類-2026-2033年產業預測
 安全KVM切換器市場規模、佔有率和成長分析:按安全認證、連接埠數量、介面、最終用戶、銷售管道和地區分類-2026-2033年產業預測
 KVM切換器市場規模、佔有率、成長率、全球產業分析、區域趨勢及2026年至2034年預測。
 KVM切換器市場:按介面類型、類型、連接埠數量、應用程式和最終用戶分類 - 2026-2032年全球預測
 KVM切換器市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、外形、最終用戶及功能分類
 高效能鍵盤、視訊和滑鼠 (KVM) 切換器全球市場報告(2026 年)
 2025-2029年全球鍵盤視訊滑鼠(KVM)切換器市場
 KVM切換器市場 - 全球產業規模、佔有率、趨勢、機會及預測(按類型、公司規模、最終用戶、地區和競爭格局分類,2021-2031年)射頻視訊分配器市場按類型、輸出埠、介面和應用分類 - 全球預測 2026-2032KVM切換器市場-2026-2031年預測