


 |
市場調查報告書
商品編碼
2063328
感測電纜:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Sensing Cable - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
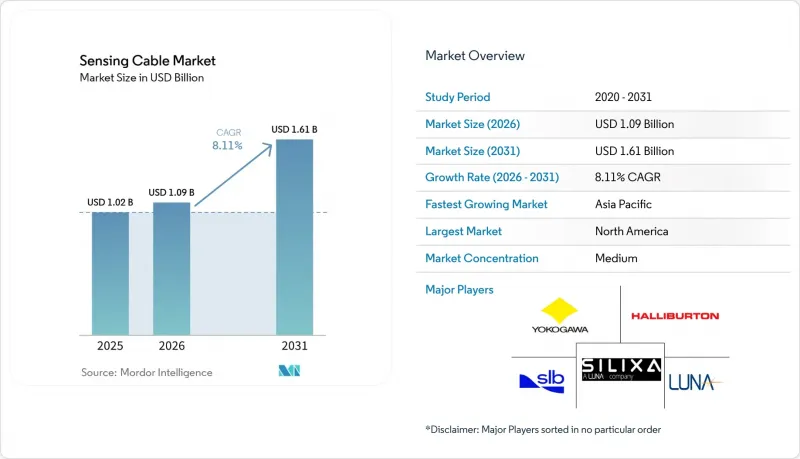
據 Mordor Intelligence 稱,2025 年感測電纜市值為 10.2 億美元,預計到 2031 年將達到 16.1 億美元,而 2026 年為 10.9 億美元,預測期(2026-2031 年)的複合年成長率為 8.11%。
本報告按電纜類型(光纖感測電纜、電纜/同軸電纜及其他)、感測技術(分散式應變/壓力感測及其他)、應用領域(結構完整性和地質監測及其他)、終端用戶產業(石油天然氣、電力和公共產業、國防安全及其他)以及地區進行細分。市場預測以美元計價。
全球感測電纜市場趨勢與洞察
擴大分散式光纖感測技術在非常規資源的應用
永久性光纖串使頁岩鑽井作業者能夠在壓裂階段即時可視化作業性能和儲存流量,從而減少停機時間並提高採收率。哈里伯頓公司2025年獲得的裸光纖干預技術許可表明,作業者可以在增產作業期間捲繞光纖,而無需中斷泵浦的運作。採用週期性屈光調變的增強型散射光纖可將訊號雜訊比提高15 dB,將單一詢問器的傳輸距離延長至50公里以上,並減少所需的硬體數量。一家中東國有石油公司正在尋求對碳酸鹽岩非均質性導致流體難以探測的長距離油井進行類似的監測,並已獲得一份多年期契約,這將擴大感測電纜市場。
危險品管洩漏檢測強制性規定
美國管道危險材料安全管理局 (PHMSA) 現要求液體輸送管線的營運商在嚴格的時間和流量限制內檢測洩漏,而 API RP 1130 標準指定分散式光纖感測為符合要求的檢測方法。在歐洲,《塞維索III指令》擴大了適用範圍,將化學品輸送路線納入其中,並鼓勵對老舊輸送管線進行維修。 AP Sensing 公司於 2025 年實施的 1300 公里 BRUA 項目,實現了亞公里級的洩漏定位精度,滿足了監管要求,同時也提供了用於事故報告的詳細數據。隨著連續光纖覆蓋消除了盲區,營運商正在加速用光纖取代定期進行的空中勘測,並將感測電纜市場納入正常的預算週期。
遠距離部署中詢問器成本高昂
詢問器5萬至20萬美元的價格區間,對於融資緊張的公共產業公司和中型企業而言,是開展覆蓋數百公里的大規模部署的一大障礙。 AP Sensing公司計劃在2025年實現300公里的海底覆蓋,但支撐這一目標的連貫網格雷射和低噪音檢測器顯著增加了資本投資預算。託管服務模式旨在分攤用戶成本,但這需要高密度的資產走廊,而大多數地區都缺乏這種設施。雖然矽光電原型顯示晶圓級價格下降,但商業化仍需兩年時間。在此之前,高昂的初始成本將阻礙新興市場的應用,並限制全球感測電纜市場的成長軌跡。
細分市場分析
截至2025年,光纖電纜的支出將佔感測電纜市場佔有率的51.78%,但聚合物光纖預計將以9.06%的複合年成長率成長,這主要得益於全氟化梯度折射率纖芯即使在160 度C以上仍能保持透明度。隨著煉油廠和化工廠對不受電磁干擾的解決方案的需求日益成長,聚合物感測電纜市場預計將再創新高。由於矽基電纜能夠實現超過100公里的單次詢問器距離,且衰減僅為0.2 dB/km,因此在長距離傳輸領域仍佔據主導地位。
在離岸風力發電中,由於偏遠節點無法連接電網,電力和光纖結合的混合結構正在興起。儘管電纜和同軸電纜在傳統的火災迴路維修項目中仍然佔據主導地位,但成本差距的縮小以及鹵素護套的禁用正促使買家轉向光纖替代方案。製造商正在試驗性地採用TOPAS和CYTOP纖芯以逐步提高效率,而不含PFAS的包層則是為了應對歐洲即將訂定的化學品法規。隨著材料科學的進步,感測電纜市場湧現出更多具有耐熱性、耐化學性和耐機械性的產品,以滿足特定應用的需求。
預計到2025年,分散式溫度感測將佔銷售額的43.12%,凸顯其在管道和電力電纜健康管理項目中的重要作用;而分佈式聲學感測預計將以9.09%的複合年成長率成長,超越所有競爭產品。聲學系統分析連貫瑞利散射,以千赫茲為單位提供振動訊息,從而實現入侵、洩漏和地震的即時檢測。隨著邊緣人工智慧降低原始數據頻寬並減少網路整合成本,用於聲學平台的感測電纜市場正在不斷擴大。
結合拉曼、Brillouin和瑞利通道的多參數測量設備能夠對關鍵基礎設施進行全面可視化,但其價格超過30萬美元。海洋觀測站目前已使用超過900公里的聲學電纜來繪製海底地震圖。在預測期內,整合溫度和振動測量功能的電纜封裝預計將在中型管道中廣泛應用,感測電纜的市場佔有率也可能向多功能聲學主導電纜束傾斜。
區域分析
亞太地區在日本地震監測、中國加強管線安全措施以及印度人力資源發展計畫的支持下,預計到2025年將佔全球銷售額的31.73%。隨著大都會圈擴大將高壓和通訊線路埋入地下,需要即時熱監測,該地區的感測電纜市場正在成長。日本相關機構正在津輕-南海海底光纜上安裝探測器,並建造高密度地震預警網路,凸顯了光纖感測作為國家災害應變措施的有效性。
北美約佔市場佔有率的28%,這主要得益於管道危險材料安全管理局 (PHMSA) 的監管,分散式感測已成為液體輸送管線的標準做法。維吉尼亞和德克薩斯州的超大規模建設帶動了消防迴路升級訂單的成長,而「Digital 395」計畫則展示了電信光纖在地震監測和網路服務中的應用。加拿大油砂的熱監測仍在繼續,但由於資金限制,進展速度有所放緩。在墨西哥,預算限制促使人們關注那些承擔資本風險的「感測即服務」供應商,這表明感測電纜市場正在發生以服務主導的轉變。
歐洲約佔總銷售額的24%,這主要得益於海底高壓直流輸電線路整合的連續溫度感測功能。 NKT價值20億歐元(21.6億美元)的SSEN輸電合約採用了整合光纖的525千伏電纜,凸顯了該地區在北海電氣化方面所做的努力。中東是成長最快的地區,複合年成長率達9.21%,主要得益於Ducab的高壓光纖產品以及國營石油公司的強制部署。同時,由於政策不完善和資金不足,南美和非洲大部分地區的採用率低於5%,不過,隨著感測器成本的降低,巴西海上油田的部署計畫顯示出了發展潛力。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大分散式光纖感測技術在非常規資源的應用
- 危險品管洩漏檢測強制性規定
- 整合人工智慧分析功能可降低營運成本和誤報率。
- 在超大規模資料中心部署被動式火災偵測電纜
- 將用於通訊和感測雙重應用的暗纖商業化。
- 隨著海底高壓直流輸電線路的發展,需要持續的溫度監測。
- 市場限制因素
- 熟練光纖安裝工人短缺
- 遠端部署中詢問器單元成本高昂
- 由於網路安全要求提高,核准流程有所延誤。
- 高溫井中聚合物感測電纜的劣化
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按電纜類型
- 光纖感測電纜
- 電氣/同軸感測電纜
- 聚合物光纖(POF)感測電纜
- 混合(電力+光纖)感測電纜
- 透過感測技術
- 分佈式溫度感測(DTS)
- 分佈式聲波感測(DAS)
- 分散式應變/壓力感測
- 混合多參數感測
- 透過使用
- 洩漏/流出檢測
- 結構完整性和地質監測
- 對電力電纜和輸電網資產進行監測
- 周界和安全入侵偵測
- 火災偵測和安全系統
- 按最終用戶行業分類
- 石油和天然氣
- 電力/公共產業
- 民用基礎設施和建築
- 工業製造和流程
- 國防安全
- 資料中心和商業建築
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- AP Sensing GmbH
- Bandweaver Technology Ltd.
- Omnisens SA
- Luna Innovations Incorporated
- Silixa Ltd.
- Fotech Solutions Ltd.
- Schlumberger Limited
- Halliburton Company
- Yokogawa Electric Corporation
- OFS Fitel, LLC
- Brugg Kabel AG
- AFL Telecommunications LLC
- NKT Photonics A/S
- Micron Optics, Inc.
- OptaSense Ltd.
- FISO Technologies Inc.
- Ziebel AS
- Future Fibre Technologies Limited
- Sensornet Limited
- LIOS Technology GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the sensing cable market size was valued at USD 1.02 billion in 2025 and estimated to grow from USD 1.09 billion in 2026 to reach USD 1.61 billion by 2031, at a CAGR of 8.11% during the forecast period (2026-2031).
This report is Segmented by Cable Type (Fiber-Optic Sensing Cables, Electrical/Coaxial Sensing Cables, and More), Sensing Technology (Distributed Strain/Pressure Sensing, and More), Application (Structural Health and Geotechnical Monitoring, and More), End-User Industry (Oil and Gas, Power and Utilities, Defense and Security, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sensing Cable Market Trends and Insights
Rising Deployment of Distributed Fiber-Optic Sensing in Unconventionals
Permanent fiber strings let shale drillers visualize frac-stage performance and reservoir flow in real time, trimming non-productive time and boosting recovery factors. Halliburton's 2025 license for bare-fiber intervention technology demonstrated that operators could spool fibers during stimulation without halting pumping operations. Enhanced-scattering fibers that add periodic refractive-index modulation improve signal-to-noise by 15 dB, extend single-interrogator reach beyond 50 km, and reduce hardware count. National oil companies in the Middle East demand similar surveillance for extended-reach wells, where carbonate heterogeneity masks flow, locking in multi-year orders that expand the sensing cable market.
Mandatory Leak-Detection Regulations for Hazardous Pipelines
The U.S. Pipeline and Hazardous Materials Safety Administration now compels liquid-line operators to spot leaks within tight time and volume windows, and API RP 1130 names distributed fiber sensing as a compliant method. In Europe, the Seveso III Directive widens the net to chemical corridors, prodding retrofits of aging transmission lines. AP Sensing's 1,300 km BRUA project in 2025 demonstrated sub-kilometer localization that meets regulatory requirements while providing forensic data for incident reporting. Because continuous fiber coverage removes blind spots, operators accelerate replacement of periodic flyovers, nudging the sensing cable market into routine budget cycles.
High Interrogator-Unit Cost for Long-Reach Deployments
Price tags between USD 50,000 and USD 200,000 per interrogator deter cash-strapped utilities and midstream firms from blanketing hundreds of kilometers. AP Sensing delivered 300 km submarine coverage in 2025, but the coherent Rayleigh lasers and low-noise detectors behind that feat inflate capital budgets. Managed service models aim to amortize costs across users but require dense asset corridors that few regions possess. Silicon-photonics prototypes hint at wafer-scale price breaks, though commercial launches remain two years away. Until then, high upfront costs temper emerging-market adoption and cap the global sensing cable market's trajectory.
Other drivers and restraints analyzed in the detailed report include:
- Integration of AI Analytics Lowers OPEX and False Alarms
- Adoption of Passive Fire-Detection Cables in Hyperscale Data Centers
- Scarcity of Trained Fiber-Optic Installation Workforce
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Spending on fiber-optic formats accounted for 51.78% of the sensing cable market share in 2025, yet polymer optical fibers are forecast to grow at a 9.06% CAGR, driven by perfluorinated graded-index cores that remain transparent beyond 160 °C. The sensing cable market for polymer lines is poised to reach new heights as refiners and chemical plants seek solutions immune to electromagnetic interference. Silica-based cables still dominate long-haul assets because 0.2 dB/km attenuation enables single-interrogator spans over 100 km.
Hybrid power-plus-fiber constructions emerge for offshore wind farms where remote nodes lack grid feeds. Electrical and coaxial forms persist in legacy fire-loop retrofits, but shrinking cost differentials and the ban on halogenated jackets are pushing buyers toward fiber alternatives. Manufacturers experimenting with TOPAS and CYTOP cores drive incremental efficiency gains, while PFAS-free claddings address looming European chemical restrictions. As material science evolves, the sensing cable market welcomes a broader portfolio that aligns thermal, chemical, and mechanical resilience with application-specific needs.
Distributed temperature sensing accounted for 43.12% of 2025 revenue, underscoring its role in pipeline and power-cable health programs, yet distributed acoustic sensing is projected to outgrow all rivals at a 9.09% CAGR. Acoustic systems parse coherent Rayleigh backscatter to deliver kilohertz-rate vibration insights that spot intrusions, leaks, and seismic tremors in real time. The sensing cable market for acoustic platforms grows as edge AI reduces raw-data bandwidth, easing network integration costs.
Multi-parameter interrogators combine Raman, Brillouin, and Rayleigh channels, yielding holistic visibility for critical infrastructure but ringing in at price points above USD 300,000. Ocean observatories already harness acoustic spans longer than 900 km for subsea quake mapping. Over the forecast window, integrated temperature-vibration packages will filter down to mid-tier pipelines, tilting the sensing cable market share mix in favor of versatile acoustic-led bundles.
Geography Analysis
Asia-Pacific anchored 31.73% of 2025 revenue, underpinned by seismic monitoring in Japan, pipeline safety upgrades in China, and workforce acceleration programs in India. The sensing cable market in the region is growing as megacities bury more HV and telecom lines that require real-time thermal supervision. Japanese agencies mount interrogators on the Tsugaru and Nankai submarine cables, weaving a dense quake-alert net that validates fiber sensing for national disaster readiness.
North America held a roughly 28% share as PHMSA mandates made distributed sensing standard practice for liquids transmission lines. Hyperscale construction in Virginia and Texas is channeling orders toward fire-loop upgrades, while the Digital 395 project showcased the dual use of telecom fibers for seismic and network services. Canada's oil sands continue thermal monitoring, but the pace slows with capital discipline. Mexico's constrained budgets are attracting sensing-as-a-service providers that absorb capital risk, signaling a service-driven shift in the sensing cable market.
Europe represented about 24% of turnover, buoyed by subsea HVDC links that embed continuous temperature sensing. NKT's EUR 2 billion (USD 2.16 billion) SSEN Transmission contract packages 525 kV cable with embedded fibers, underscoring the region's push to electrify the North Sea. The Middle East is growing fastest at a 9.21% CAGR, with Ducab's high-voltage fiber offerings and national oil company mandates driving adoption. Meanwhile, policy gaps and capital scarcity leave most of South America and Africa below 5% penwith penetration etrationot programs in Brazil's offshore fields hint at latent potential once interrogator costs fall.
- AP Sensing GmbH
- Bandweaver Technology Ltd.
- Omnisens SA
- Luna Innovations Incorporated
- Silixa Ltd.
- Fotech Solutions Ltd.
- Schlumberger Limited
- Halliburton Company
- Yokogawa Electric Corporation
- OFS Fitel, LLC
- Brugg Kabel AG
- AFL Telecommunications LLC
- NKT Photonics A/S
- Micron Optics, Inc.
- OptaSense Ltd.
- FISO Technologies Inc.
- Ziebel AS
- Future Fibre Technologies Limited
- Sensornet Limited
- LIOS Technology GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Deployment of Distributed Fiber-Optic Sensing in Unconventionals
- 4.2.2 Mandatory Leak-Detection Regulations for Hazardous Pipelines
- 4.2.3 Integration of AI Analytics Lowers OPEX and False Alarms
- 4.2.4 Adoption of Passive Fire-Detection Cables in Hyperscale Data Centers
- 4.2.5 Monetization of Dark Fiber for Dual Telecom-Sensing Use
- 4.2.6 Sub-Sea HVDC Growth Demanding Continuous Thermal Monitoring
- 4.3 Market Restraints
- 4.3.1 Scarcity of Trained Fiber-Optic Installation Workforce
- 4.3.2 High Interrogator-Unit Cost for Long-Reach Deployments
- 4.3.3 Cyber-Hardening Requirements Delaying Approvals
- 4.3.4 Polymer Sensing-Cable Degradation in High-Temperature Wells
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cable Type
- 5.1.1 Fiber-Optic Sensing Cables
- 5.1.2 Electrical/Coaxial Sensing Cables
- 5.1.3 Polymer Optical Fiber (POF) Sensing Cables
- 5.1.4 Hybrid (Power + Fiber) Sensing Cables
- 5.2 By Sensing Technology
- 5.2.1 Distributed Temperature Sensing (DTS)
- 5.2.2 Distributed Acoustic Sensing (DAS)
- 5.2.3 Distributed Strain/Pressure Sensing
- 5.2.4 Hybrid Multi-Parameter Sensing
- 5.3 By Application
- 5.3.1 Leak and Spill Detection
- 5.3.2 Structural Health and Geotechnical Monitoring
- 5.3.3 Power Cable and Grid Asset Monitoring
- 5.3.4 Perimeter and Security Intrusion Detection
- 5.3.5 Fire Detection and Safety Systems
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Power and Utilities
- 5.4.3 Civil Infrastructure and Construction
- 5.4.4 Industrial Manufacturing and Process
- 5.4.5 Defense and Security
- 5.4.6 Data Centers and Commercial Buildings
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 AP Sensing GmbH
- 6.4.2 Bandweaver Technology Ltd.
- 6.4.3 Omnisens SA
- 6.4.4 Luna Innovations Incorporated
- 6.4.5 Silixa Ltd.
- 6.4.6 Fotech Solutions Ltd.
- 6.4.7 Schlumberger Limited
- 6.4.8 Halliburton Company
- 6.4.9 Yokogawa Electric Corporation
- 6.4.10 OFS Fitel, LLC
- 6.4.11 Brugg Kabel AG
- 6.4.12 AFL Telecommunications LLC
- 6.4.13 NKT Photonics A/S
- 6.4.14 Micron Optics, Inc.
- 6.4.15 OptaSense Ltd.
- 6.4.16 FISO Technologies Inc.
- 6.4.17 Ziebel AS
- 6.4.18 Future Fibre Technologies Limited
- 6.4.19 Sensornet Limited
- 6.4.20 LIOS Technology GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


