


 |
市場調查報告書
商品編碼
2061665
鎂合金:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Magnesium Alloys - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
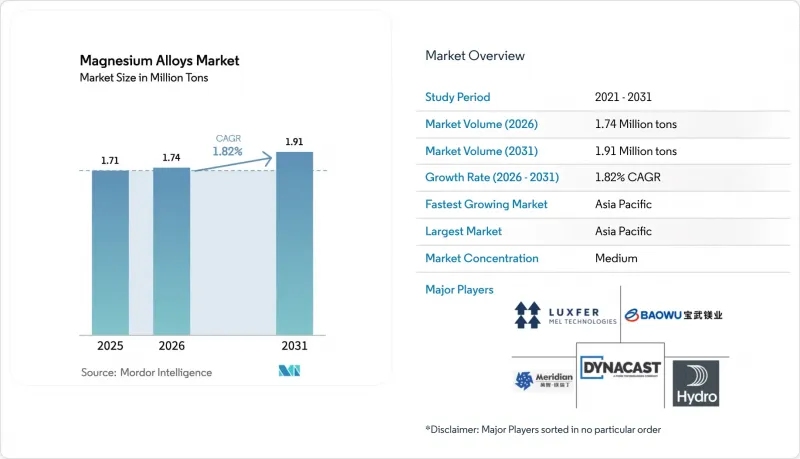
根據 Mordor Intelligence 預測,鎂合金市場規模將從 2025 年的 171 萬噸成長到 2026 年的 174 萬噸,到 2031 年將達到 191 萬噸,2026 年至 2031 年的複合年成長率為 1.82%。
本報告按合金類型(鑄造合金和鍛造合金)、加工技術(壓鑄、擠壓、鍛造、粉末冶金和積層製造原料)、應用(底盤和結構件等)、終端用戶行業(汽車、航太等)和地區(亞太地區等)進行細分。市場預測以噸為單位。
全球鎂合金市場趨勢及洞察
電動車強制減重將提振對鎂合金的需求。
由於電池式電動車(BEV)比內燃機車更重,汽車製造商被迫減輕車身結構重量以彌補續航里程的損失。中國2027年新能源車法規規定,在中控續航里程標準下,純電動車的最低續航里程為500公里,使得輕量化車身本體成為必要。透過使用比鋁更輕的鎂合金擠壓件和Megacast副車架,汽車製造商無需增加電池尺寸即可實現這些目標。符合ISO 16220腐蝕測試標準的AZ31B前懸吊的認證縮短了認證時間。目前,豪華車型承擔了成本差異,但隨著回收技術的進步,鎂合金的應用預計將進一步普及,並滲透到中檔車型市場。
歐盟二氧化碳排放標準正在加速鍛造鎂擠壓件的採用。
歐盟已設定2025年的排放上限,並將於2030年前逐步收緊。每超過上限一克,都將受到處罰。這使得減重不再是一種選擇,而是必然。透過使用直接冷鑄和熱擠壓的ZK60型材,製造商可以在保持200 MPa以上屈服強度的同時,減輕零件的重量。麥格納在奧地利推出了一條新的生產線,並為奧迪PPE底盤的各種零件供應鎂合金。這些不含六價鉻且通過ISO 10074認證的塗層不僅減輕了REACH法規的負擔,還加快了供應商進入市場的速度,並提升了鎂合金市場的成長前景。
潮濕環境中電流腐蝕和點蝕的挑戰
鎂的電位為-2.37 V,具有極高的陽極性能。因此,當含鹽水分接觸到不同金屬的連接處時,會隨著時間的推移而發生點蝕。雖然等離子電解氧化處理可以延長鎂合金在鹽霧試驗中的耐腐蝕壽命,但這需要大量的資金投入。與稀土元素合金化雖然有一定的優勢,但其價格波動較大。因此,腐蝕仍然是鎂合金在主流汽車中廣泛應用的最大障礙。
細分市場分析
預計到2025年,鑄造合金將佔出貨量的68.17%,這反映了壓鑄製程在製造複雜外殼形狀方面的高效性。然而,鍛造合金的出貨量正以6.36%的複合年成長率快速成長。 BMW的「新時代」平台採用了擠壓成型的AZ31B和ZK60合金零件,每輛車的重量僅22公斤,進一步提升了輕量化優勢,這對於最佳化鋰離子電池的續航里程至關重要。在汽車產業之外,擠壓成型的ZK60A合金也被用於直升機變速箱殼體和無人機(UAV)機架的減震,凸顯了鎂合金市場的進一步多元化。在電子產業,壓鑄LA141合金仍然是5G行動電話機殼的首選。然而,積層製造粉末技術能夠製造出具有鈦合金無法實現的生物力學相容性的晶格結構填充植入,從而拓展了設計的可能性。
到2025年,一種取得專利的、稀土元素的鍛造材料將問世,從而解決供應問題並降低材料成本。儘管積層製造中採用氣體霧化法生產的WE43粉末目前仍處於小眾市場,但其需求正在提升盈利並刺激研發。政府對原料回收的補貼政策促使鑄造廢料更多地被重熔為鍛坯。這不僅縮短了供應鏈,也增強了鎂合金市場對永續性的承諾。
壓鑄製程仍佔總產量的55.18%,這得益於其45-90秒的成型週期和高達百萬次的模具壽命。中國汽車製造商已訂購大型壓平機,並計劃從2027年開始測試鎂合金後底盤零件的單件生產。同時,麥格納在奧地利為奧迪運作個人防護裝備的新生產線正在擴大其擠壓件的市場佔有率。此外,壓機潤滑劑的進步使得使用更長的AZ31型材成為可能。
積層製造(AM)正以6.82%的複合年成長率成長。 EOS M290採用WE43材料,可直接從粉末床獲得高密度和高屈服強度,使其適用於製造承重踝關節鋼板。基於ATEX 2014/34/EU的安全標準正在推動德國和德克薩斯州各地惰性氣體保護型積層製造工廠的投資。儘管鍛造和粉末冶金仍是小眾領域,但鎂合金市場在製造流程方面保持多樣性,這得益於對直升機旋翼輪圈和輕量化自行車曲柄的需求。
區域分析
預計到2025年,亞太地區將佔全球鎂合金出貨量的46.19%,並將維持最高的成長率,到2031年複合年成長率將達到6.87%。 2025年,中國寶武集團將運作新的產能,鞏固在關鍵市場的佔有率,進一步強化其市場主導地位。同時,比亞迪旗下的「Seal」轎車已開始使用鎂合金零件。值得一提的是,日本豐田和Panasonic正在合作開發鎂基鋰電池機殼,預示著未來跨產業的協同效應。韓國主要行動電話製造商將在2025年獲得LA合金的供應,有效填補鎂合金市場的供需缺口。
北美市場佔有率主要由行業巨頭福特和通用汽車以及WE43螺絲在醫療領域的日益普及所驅動。美國鎂業公司位於大鹽湖的工廠為原始設備製造商 (OEM) 抵禦地緣政治不確定性提供了緩衝。以醫療領域的成長動能為例,Syntelix在獲得FDA批准僅一年後便在橈骨遠端固定市場佔據了市場佔有率。在加拿大,龐巴迪和CAE在其模擬設備中使用擠壓成型的ZK60;在墨西哥,瓜納華託的一家壓鑄製造商正在將鎂應用於奧迪Q5 e-tron的載體中。
歐洲正努力應對日益嚴格的二氧化碳排放法規。 2025年,德國消耗了大量的鎂,主要得益於麥格納和海德魯等公司為減少碳足跡所採取的回收舉措。歐盟強制要求使用再生材料,這促使原始設備製造商(OEM)簽訂再生原料採購契約,加強了該地區在鎂合金市場對循環經濟的承諾。
南美洲、中東和非洲雖然規模較小,但也取得了顯著進展。巴西國家金屬加工和冶金工業聯合會(INMETRO)已將其國內標準與ISO 16220接軌,為國內供應商向原始設備製造商(OEM)供貨鋪平了道路。沙烏地阿拉伯具有前瞻性地計劃在2028年之前使其朱拜勒冶煉廠運作,從而為市場增加新的初級生產能力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 強制降低電動車重量的措施將提振對鎂合金的需求。
- 歐盟平均二氧化碳排放法規正在加速鍛造鎂擠壓件的採用。
- 美國FDA的批准正在推動對由生物可吸收鎂製成的整形外科固定裝置的需求。
- 5G智慧型手機製造商採用鎂鋰鑄造製程實現電磁干擾屏蔽
- 閉合迴路廢料回收利用降低了鎂合金的實際成本。
- 市場限制因素
- 潮濕環境中電流腐蝕和點蝕的挑戰
- 鋁合金和鈦合金的焊接脆性
- 高強度 6xxx 系列鋁擠型材正在取代鎂合金,用於碰撞相關零件。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按合金類型
- 鑄造合金
- 加工合金
- 透過加工技術
- 壓鑄
- 擠壓
- 鍛造
- 粉末冶金
- 積層製造的原料
- 透過使用
- 底盤和結構部件
- 動力傳動系統和傳動系統部件
- 汽車內裝和外觀部件
- 電子設備機殼
- 整形外科和心血管植入
- 其他
- 按最終用途行業分類
- 車
- 航太
- 電子設備
- 醫學領域
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AE Group
- AMACOR
- Baowu Magnesium Technology Co., Ltd.
- Dead Sea Magnesium Ltd.
- Dynacast
- Fugu County Industrial Magnesium Ltd.
- ICL
- Ka Shui International Holdings Ltd
- Luxfer MEL Technologies
- MAGONTEC Group
- Meridian Lightweight Technologies
- m-tec powder GmbH
- NIPPON KINZOKU co.,ltd.
- Norsk Hydro ASA
- Rima Group
- Shanghai Regal Metal Materials Co., Ltd.
- Shanxi Yinguang Huasheng Magnesium Industry Co., LTD
- Smiths Advanced Metals
- US Magnesium LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the magnesium alloys market size is expected to grow from 1.71 million tons in 2025 to 1.74 million tons in 2026 and is forecast to reach 1.91 million tons by 2031 at a 1.82% CAGR over 2026-2031.
This report is Segmented by Alloy Type (Cast Alloys and Wrought Alloys), Processing Technology (Die Casting, Extrusion, Forging, Powder Metallurgy, and Additive Manufacturing Feedstock), Application (Chassis and Structural Components, and More), End-Use Industry (Automotive, Aerospace, and More), and Geography (Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Magnesium Alloys Market Trends and Insights
Mandatory EV Lightweighting Mandates Boost Magnesium Alloy Demand
Battery-electric vehicles (BEVs) are heavier than their combustion counterparts, prompting OEMs to reduce structural mass to reclaim lost range. China's 2027 New Energy Vehicle mandate sets a minimum range of 500 km on the CLTC, effectively necessitating a reduction in body-in-white weight. By utilizing magnesium extrusions and mega-cast subframes, which are lighter than aluminum, automakers can achieve these targets without enlarging their batteries. Following ISO 16220 corrosion-testing standards, certification for AZ31B front-end carriers has streamlined qualification timelines. While premium models currently shoulder the cost disparity, advancements in recycling hint at a broader acceptance of magnesium alloys, potentially penetrating deeper into mid-volume segments.
EU CO2 Fleet-Average Rules Accelerate Wrought Mg Extrusions Adoption
The EU has set a limit for emissions for 2025, which will gradually tighten by 2030. For every gram over the limit, there's a penalty. This has made light-weighting not just an option, but a necessity. Using direct-chill-cast and hot-extruded ZK60 profiles, manufacturers can reduce component mass while still achieving a yield strength of over 200 MPa. Magna has launched a new line in Austria, providing magnesium for each Audi PPE chassis. Coatings free from hexavalent chromium and certified under ISO 10074 not only alleviate REACH pressures but also expedite supplier onboarding, bolstering the growth outlook for the magnesium alloys market.
Galvanic and Pitting Corrosion Challenges in Humid Environments
Magnesium's -2.37 V potential renders it highly anodic. Consequently, when salt-laden moisture connects joints of dissimilar metals, pits develop over time. While plasma-electrolytic oxidation can prolong the salt-spray life, it comes with a significant capital expenditure. Although rare-earth alloying offers some benefits, its susceptibility to price fluctuations poses challenges. As a result, corrosion remains the primary hurdle preventing the broader adoption of magnesium alloys in mainstream vehicles.
Other drivers and restraints analyzed in the detailed report include:
- US FDA Clearances Spur Bio-Resorbable Mg Orthopedic Fixation Demand
- 5G Handset Makers Shift to Mg-Li Casting for EMI Shielding
- Welding Brittleness Versus Al and Ti Alloys
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cast alloys supplied 68.17% of shipments in 2025, reflecting their die-casting efficiency for intricate housings. Nonetheless, wrought grades are sprinting ahead at 6.36% CAGR. BMW's Neue Klasse platform will embed 22 kg of extruded AZ31B and ZK60 per car, sharpening the weight-saving edge essential to lithium-ion range optimization. Beyond cars, helicopter gearbox housings and UAV frames now specify ZK60A extrusions for vibration damping, underscoring broader diversification of the magnesium alloys market. Electronics still favor die-cast LA141 shells for 5G handsets, yet the design window is widening as additive-manufacturing powders enable lattice-filled implants that deliver biomechanical compatibility unmatchable by titanium.
In 2025, patented rare-earth-free wrought compositions emerged, addressing supply concerns and reducing material costs. While niche, the demand for gas-atomized WE43 powders in additive manufacturing enhances profitability and fuels research and development. Regulatory subsidies for recycling feedstock have led to an uptick in re-melting cast scrap into wrought billets. This not only shortens supply loops but also bolsters the sustainability credentials of the magnesium alloys market.
Die casting still commands 55.18% of throughput thanks to 45-90 s cycles and million-shot tooling life. Chinese OEMs are set to trial single-piece magnesium rear underbodies starting in 2027, having placed orders for large presses. Meanwhile, Magna's new line in Austria, catering to Audi's PPE, bolsters extrusions' market share. Additionally, advancements in press lubricants now facilitate the use of long AZ31 profiles.
Additive manufacturing grows at a 6.82% CAGR. EOS M290, utilizing WE43, achieves high density and yield strength directly from the powder bed, making it suitable for load-bearing ankle plates. Safety codes under ATEX 2014/34/EU have spurred investment in inert-gas print farms across Germany and Texas. Forging and powder metallurgy remain niche but benefit from demand in helicopter rotor hubs and lightweight bicycle cranks, keeping the magnesium alloys market diversified across processes.
Geography Analysis
Asia Pacific retains 46.19% of 2025 shipments and posts the fastest 6.87% CAGR through 2031. In 2025, China's Baowu bolstered its dominance by bringing new capacity online and cementing its primary market share. Meanwhile, BYD's Seal sedan is already integrating magnesium components. In a notable collaboration, Japan's Toyota and Panasonic are co-developing magnesium-lithium battery enclosures, hinting at a future cross-industry synergy. South Korea's leading handset manufacturers secured LA alloys in 2025, effectively bridging the supply-demand gap in the magnesium alloys market.
North America's market share is largely driven by industry giants Ford and GM, alongside the growing medical adoption of WE43 screws. US Magnesium's Great Salt Lake facility acts as a buffer for OEMs against geopolitical uncertainties. Highlighting the medical sector's momentum, Syntellix captured a share of the distal-radius fixation market just a year post-FDA approval. In Canada, Bombardier and CAE are utilizing extruded ZK60 for their simulation rigs, while in Mexico, Guanajuato die-casters are embedding magnesium into Q5 e-tron carriers.
Europe is navigating stringent CO2 regulations. In 2025, Germany, bolstered by recycling initiatives from Magna and Hydro that cut carbon footprints, consumed a notable amount of magnesium. The EU's mandate for recycled content is steering OEMs towards secondary feedstock contracts, reinforcing the region's commitment to circularity in the magnesium alloys market.
While South America and the Middle East and Africa may be smaller players, they are making significant strides. Brazil's INMETRO has harmonized local standards with ISO 16220, paving the way for domestic suppliers to cater to OEMs. In a forward-looking move, Saudi Arabia is set to unveil a Jubail smelter by 2028, adding new primary capacity to the market.
- AE Group
- AMACOR
- Baowu Magnesium Technology Co., Ltd.
- Dead Sea Magnesium Ltd.
- Dynacast
- Fugu County Industrial Magnesium Ltd.
- ICL
- Ka Shui International Holdings Ltd
- Luxfer MEL Technologies
- MAGONTEC Group
- Meridian Lightweight Technologies
- m-tec powder GmbH
- NIPPON KINZOKU co.,ltd.
- Norsk Hydro ASA
- Rima Group
- Shanghai Regal Metal Materials Co., Ltd.
- Shanxi Yinguang Huasheng Magnesium Industry Co., LTD
- Smiths Advanced Metals
- US Magnesium LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandatory EV light-weighting mandates boost Magnesium Alloy demand
- 4.2.2 EU CO2 fleet-average rules accelerate wrought Mg extrusions adoption
- 4.2.3 US FDA clearances spur bio-resorbable Mg orthopedic fixation demand
- 4.2.4 5G handset makers shift to Mg-Li casting for EMI shielding
- 4.2.5 Closed-loop scrap recycling lowers effective cost of Mg alloys
- 4.3 Market Restraints
- 4.3.1 Galvanic and pitting corrosion challenges in humid environments
- 4.3.2 Welding brittleness versus Al and Ti alloys
- 4.3.3 High-strength 6xxx Al extrusions displace Mg for crash-relevant parts
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Alloy Type
- 5.1.1 Cast Alloys
- 5.1.2 Wrought Alloys
- 5.2 By Processing Technology
- 5.2.1 Die Casting
- 5.2.2 Extrusion
- 5.2.3 Forging
- 5.2.4 Powder Metallurgy
- 5.2.5 Additive Manufacturing Feedstock
- 5.3 By Application
- 5.3.1 Chassis and Structural Components
- 5.3.2 Powertrain and Drivetrain Components
- 5.3.3 Interior and Exterior Automotive Parts
- 5.3.4 Electronic Device Housings
- 5.3.5 Orthopedic and Cardiovascular Implants
- 5.3.6 Others
- 5.4 By End-use Industry
- 5.4.1 Automotive
- 5.4.2 Aerospace
- 5.4.3 Electronics
- 5.4.4 Medical
- 5.4.5 Other End-user Industries
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 AE Group
- 6.4.2 AMACOR
- 6.4.3 Baowu Magnesium Technology Co., Ltd.
- 6.4.4 Dead Sea Magnesium Ltd.
- 6.4.5 Dynacast
- 6.4.6 Fugu County Industrial Magnesium Ltd.
- 6.4.7 ICL
- 6.4.8 Ka Shui International Holdings Ltd
- 6.4.9 Luxfer MEL Technologies
- 6.4.10 MAGONTEC Group
- 6.4.11 Meridian Lightweight Technologies
- 6.4.12 m-tec powder GmbH
- 6.4.13 NIPPON KINZOKU co.,ltd.
- 6.4.14 Norsk Hydro ASA
- 6.4.15 Rima Group
- 6.4.16 Shanghai Regal Metal Materials Co., Ltd.
- 6.4.17 Shanxi Yinguang Huasheng Magnesium Industry Co., LTD
- 6.4.18 Smiths Advanced Metals
- 6.4.19 US Magnesium LLC
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Increasing 3D Printing and Additive Manufacturing


