


 |
市場調查報告書
商品編碼
2120564
企業應用整合:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Enterprise Application Integration - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
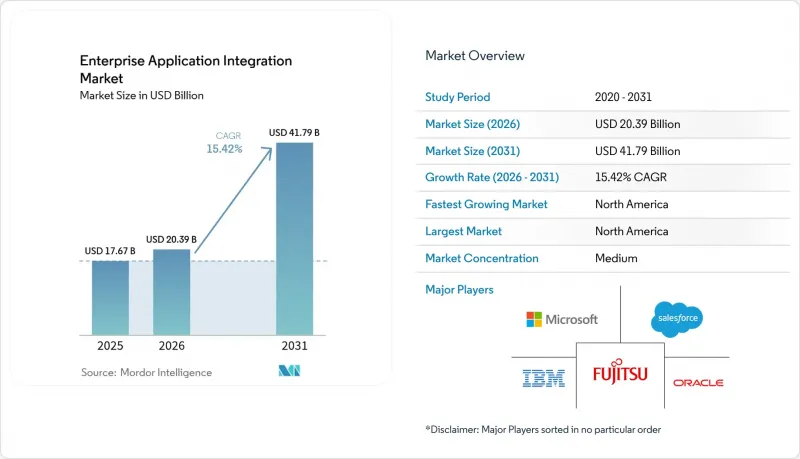
根據 Mordor Intelligence 估計,企業應用整合市場規模從 2025 年的 176.7 億美元成長到 2026 年的 203.9 億美元,預計到 2031 年將達到 417.9 億美元。
預計 2026 年至 2031 年的複合年成長率為 15.42%。
本報告按部署模式(本地部署、雲端部署、混合部署)、整合平台類型(企業服務匯流排(ESB) 及其他)、組織規模(大型企業、中小企業)、應用領域(CRM 整合及其他)、最終用戶產業(銀行、金融服務和保險 (BFSI)、IT 和電信及其他)以及地區進行細分。市場預測以美元 (USD) 為單位。
全球企業應用整合市場趨勢與洞察
透過 API主導的連接加速 SaaS 的普及
可重複使用的 API 資產如今已成為一項策略性元件,有助於縮短發布週期並降低維護成本。採用此模式的公司報告稱,整合時間縮短了 40% 至 60%,從而釋放了預算用於投資新的數位服務。 MuleSoft 在 Salesforce 產品組合中的成長以及 Microsoft API Gateway 的不斷擴展部署表明,主要供應商正在將重心轉向可組合的整合架構。
雲端原生 iPaaS 作為事實上的整合式骨幹網路標準
容器化微服務、無伺服器運行時引擎和自動化擴展功能使雲端原生整合平台即服務 (iPaaS) 平台能夠將整體擁有成本 (TCO) 降低高達 70%,遠低於傳統中間件。 Oracle 在其近期發布的雲端收入報告中重點強調了這一點。除了這些經濟優勢之外,內建的可觀測性和可操作性也正促使即使是風險規避型企業也轉向多重雲端整合架構。
開放原始碼ESB替代方案導致授權收入減少
Apache Camel、WSO2 和類似的框架對擁有強大的內部工程團隊的組織極具吸引力,因為它們無需支付許可費用即可提供強大的整合功能。因此,商業平台強調差異化的 AI編配、託管服務和安全認證,以證明其高級套餐的價值。
細分市場分析
混合環境的複合年成長率 (CAGR) 為 17.78%,展現了本地控制和雲端敏捷性之間的最佳架構平衡。隨著遷移風險的降低和雲端服務經濟效益的持續提升,預計到 2027 年以後,與混合部署相關的企業應用整合市場支出將超過本地部署支出。銀行和受監管的醫療保健機構正在透過在私有雲端上部署輕量級連接器,並透過安全的 VPN 或 SD-WAN 隧道連接大型主機和 SaaS,從而實現兩者的整合。整合了主動路由、加密和即時可觀測性的部署工具包可減少操作摩擦,使混合整合成為持續監管報告的理想選擇。 IBM 已整合其近期收購的 HashiCorp 的 Terraform 模組,以實現跨雲端叢集配置的自動化,從而簡化全球企業的管治。
本地部署仍然佔據主導地位,但它們正在演變而不是衰落。企業正在將其底層訊息匯流排遷移到本地 Kubernetes叢集上的容器平台,僅在因延遲或主權要求而必須進行本地處理時才更新硬體。這種分階段的現代化改造避免了徹底替換系統的大規模項目,減少了意外的資本支出 (Capex),並保持了關鍵業務工作流程的連續性,因為在這些流程中,超過幾秒鐘的停機時間是不可接受的。對於全球製造商而言,工廠內本地整合的設備可提供確定性的延遲,而基於雲端的事件中心則聚合資料以用於預測分析模型。
預計到 2025 年,iPaaS 將佔總收入的 33.10%,並且是那些優先考慮訂閱經濟而非永久授權模式的公司戰略構想的核心。該細分市場預計將以 24.95% 的複合年成長率成長,這得益於連接器庫的持續擴展、託管運行時補丁以及透過服務等級協定 (SLA) 提供的正常運轉率保證,這些措施使客戶擺脫了中間件修補程式的負擔。微軟、Oracle、SAP 和 Salesforce 等公司正在將 iPaaS 功能直接整合到其雲端套件中,從而簡化採購流程並實現跨應用層的統一身分模型。
同時,企業服務總線(ESB)平台在電信業者和國防相關企業複雜的軸輻式拓樸結構中仍佔據重要地位。支援這些環境的供應商現在提供運行在 Kubernetes 中的容器化運行時,從而在資料中心撤離成為必然時,能夠輕鬆地將資料「遷移」到私有雲端。具有下推式 ELT 管道的數據整合工具也透過向需要高吞吐量批量攝取的湖倉式架構提供數據,凸顯了其重要性。
區域分析
預計到2025年,北美將維持37.60%的收入佔有率。這主要得益於超大規模雲端區域的整合、由創業投資支持的SaaS生態系統以及美國強大的API經濟文化。聯邦和州政府機構也在撥款用於採購、稅務和福利系統的現代化改造,從而創造了對安全、整合閘道器的長期需求。加拿大也呈現類似的成長勢頭,但更注重數據駐留,因此更多地使用本地雲端區域和混合邊緣設備。墨西哥目前仍處於起步階段,但隨著企業對其ERP和支付基礎設施進行現代化改造,並擴大利用近岸服務供應商從雙語人才中心提供整合服務,墨西哥市場正在快速成長。
歐洲蘊藏著巨大的商業機遇,GDPR、《數位營運彈性法案》以及新興的碳足跡揭露機制正在指南平台審計工作。在德國的汽車和工業叢集中,邊緣到雲端連接器正被部署用於將機器遙測資料傳輸到預測性維護模型。英國正在資助一項開放銀行藍圖,以擴大API管理套件的目標市場。法國正在支持一項主權雲端計劃,該計劃鼓勵歐洲供應商提供全面的合規性交付成果。在雲端技術應用已經成熟的北歐國家,整合引擎正率先採用碳友善路由,在尖峰時段將運算資源轉移到可再生能源可用的地區。
亞太地區正經歷最快的成長,預計到2031年複合年成長率將達到16.05%,因為企業正在跨越傳統ESB架構,直接利用iPaaS。中國正在投資大規模的工業網際網路項目和人工智慧加速晶片,這些晶片會傳輸大量的遙測數據,需要高吞吐量的整合架構。印度的數位公共基礎設施(例如Aadhaar、統一支付介面等)正在推動數百萬公民使用API,促使當地系統整合商專注於安全、高容量的連接器。日本和韓國正在投資智慧工廠計劃,利用邊緣仲介即時同步機器人和ERP系統。東南亞國家正在利用雲端優先的監管沙箱來加速金融科技創新,並為輕量級整合運行時創造利基市場。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 透過 API主導的連接加速 SaaS 的普及
- 雲端原生 iPaaS 作為事實上的整合式骨幹網路標準
- 事件驅動架構,可實現即時分析
- 利用生成式人工智慧的映射和測試工具
- 強制性工作負載路由,需考慮碳排放意識。
- 面向微型SaaS的獨立供應商市場
- 市場限制因素
- 開放原始碼ESB替代方案導致授權收入減少
- 由於缺乏具備綜合技能的人員,專案成本不斷上升。
- 超大規模雲端運算中隱藏出口費用的經濟學
- 遺留技術債對 API 安全態勢的負面影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按部署模式
- 現場
- 雲
- 混合
- 按整合平台類型
- 企業服務匯流排(ESB)
- iPaaS(Integration-Platform-as-a-Service)
- API 閘道管理套件
- 資料 ETL/ELT 工具
- 按組織規模
- 大公司
- 小型企業
- 應用:滑
- CRM整合
- ERP系統與財務系統的整合
- 供應鍊和物流整合
- 人力資源和勞動力整合
- 商業智慧與分析的整合
- 按最終用戶行業分類
- BFSI
- IT/通訊
- 衛生保健
- 零售與電子商務
- 政府
- 製造業
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- IBM Corporation
- Microsoft Corporation
- Oracle Corporation
- SAP SE
- Salesforce Inc.(MuleSoft LLC)
- Software AG
- TIBCO Software Inc.
- Fujitsu Ltd.
- iTransition Group
- Dell Boomi LLC
- Informatica LLC
- SnapLogic Inc.
- Workato Inc.
- Celigo Inc.
- Jitterbit Inc.
- Talend SA
- Red Hat Inc.
- WSO2 Inc.
- Cleo Communications Inc.
- OpenLegacy Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the enterprise application integration market size in 2026 is estimated at USD 20.39 billion, growing from 2025 value of USD 17.67 billion with 2031 projections showing USD 41.79 billion, growing at 15.42% CAGR over 2026-2031.
This report is Segmented by Deployment Model (On-Premise, Cloud, Hybrid), Integration Platform Type (Enterprise Service Bus, and More), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), Application Area (CRM Integration, and More), End-User Industry (BFSI, IT and Telecom, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise Application Integration Market Trends and Insights
API-led Connectivity Accelerating SaaS Adoption
Reusable API assets now serve as strategic building blocks, shortening release cycles and reducing maintenance overhead. Enterprises adopting the model routinely report integration timeline cuts of 40-60%, which frees budget for incremental digital services. MuleSoft's growth inside the Salesforce portfolio, combined with Microsoft's expanding API gateway footprint, illustrates how large vendors are pivoting toward composable integration fabrics.
Cloud-native iPaaS as De-facto Integration Backbone
Containerized microservices, serverless runtime engines, and automated elasticity enable cloud-native iPaaS platforms to deliver up to 70% total cost of ownership (TCO) savings compared to traditional middleware, as highlighted by Oracle in its recent cloud revenue disclosures. These economics, coupled with built-in observability and policy enforcement, are steering even risk-averse enterprises toward multi-cloud integration fabrics.
Open-source ESB Alternatives Eroding License Revenue
Apache Camel, WSO2, and similar frameworks offer robust integration without licensing costs, appealing to organizations with capable internal engineering teams. Commercial platforms, therefore, emphasize differentiated AI orchestration, managed services, and security certifications in order to justify premium tiers.
Other drivers and restraints analyzed in the detailed report include:
- Event-Driven Architectures Enabling Real-time Analytics
- Generative-AI-Assisted Mapping and Testing Tools
- Shortage of Integration-Skill Talent Inflating Project Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid environments accounted for 17.78% CAGR, evidencing the architectural sweet spot between on-premise control and cloud agility. The enterprise application integration market size tied to hybrid roll-outs will likely surpass on-premise outlays after 2027, as migration risk is mitigated while cloud services continue to improve their economics. Banks and regulated healthcare providers integrate mainframes with SaaS by dropping lightweight connectors into private clouds and linking them via secure VPN or SD-WAN tunnels. Deployment toolkits that bundle policy-driven routing, encryption, and real-time observability reduce operational friction, making hybrid integration attractive for continuous regulatory reporting. IBM bundled its recently acquired HashiCorp Terraform modules to automate cluster provisioning across clouds, which simplifies governance for global corporations.
Despite ongoing dominance, on-premise implementations are evolving rather than fading. Organizations migrate their foundational message buses toward container platforms on internal Kubernetes clusters, refreshing hardware only where latency or sovereignty requirements necessitate local processing. This incremental modernization prevents wholesale rip-and-replace projects, lowers capex surprises, and maintains continuity for mission-critical workflows that cannot risk outage windows longer than a few seconds. For global manufacturers, local integration appliances in factories offer deterministic latency while cloud event hubs aggregate data for predictive analytics models.
iPaaS generated 33.10% revenue in 2025 and sits at the center of enterprise blueprints that prioritize subscription economics over perpetual licenses. The segment's 24.95% CAGR is underpinned by continuous connector library expansion, managed runtime patches, and SLA-bound uptime commitments that free customers from the burdens of middleware patching. Microsoft, Oracle, SAP, and Salesforce deliver bundled iPaaS capability directly in their cloud suites, reducing procurement steps and providing consistent identity models across application layers.
Conversely, ESB platforms retain hold in complex hub-and-spoke topologies within telecom carriers and defense contractors. Vendors supporting these estates now ship containerized runtimes that run inside Kubernetes, thereby easing the lift-and-shift to private clouds when a data center exit is mandated. Data integration tools with pushdown ELT pipelines also claim relevance by feeding lakehouse architectures that demand high-throughput batch ingestion.
Complete Report Scope:
- By Deployment Model
- On-premise
- Cloud
- Hybrid
- By Integration Platform Type
- Enterprise Service Bus (ESB)
- Integration Platform-as-a-Service (iPaaS)
- API-Gateway / Management Suites
- Data and ETL/ELT Tools
- By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises
- By Application Area
- CRM Integration
- ERP and Finance Integration
- Supply-Chain / Logistics Integration
- HR and Workforce Integration
- Business Intelligence and Analytics Integration
- By End-user Industry
- BFSI
- IT and Telecom
- Healthcare
- Retail and E-commerce
- Government
- Manufacturing
- Other End-user Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America maintained a 37.60% revenue share in 2025, anchored by the United States, where hyperscale cloud regions, venture capital-funded SaaS ecosystems, and robust API economy cultures converge. Federal and state agencies also allocate funds to modernize procurement, taxation, and benefit systems, generating prolonged demand for secure integration gateways. Canada exhibits similar momentum but places a stronger emphasis on data residency, prompting the usage of local-region cloud zones and hybrid edge appliances. Mexico sits at an earlier stage yet climbs swiftly as enterprises modernize ERP and payment rails, often leveraging near-shore service providers that deliver integration services from bilingual talent hubs.
Europe represents a sizable opportunity, as the GDPR, the Digital Operational Resilience Act, and emerging carbon footprint disclosures guide platform audits. Germany's automotive and industrial clusters deploy edge-to-cloud connectors that transport machine telemetry into predictive maintenance models. The United Kingdom finances open-banking roadmaps that enlarge the addressable pool for API management suites. France backs sovereign-cloud initiatives that favor European vendors bundling comprehensive compliance artefacts. Nordic countries, already mature in cloud adoption, pioneer carbon-aware routing where integration engines shift compute to regions with renewable energy availability during peak windows.
The Asia-Pacific region demonstrates the fastest growth, with a 16.05% CAGR through 2031, as enterprises skip legacy ESB generations and consume iPaaS directly. China invests in large-scale industrial Internet projects and AI acceleration chips that stream vast amounts of telemetry, requiring high-throughput integration fabrics. India's digital-public-infrastructure stack, including Aadhaar and Unified Payments Interface, normalizes API consumption for millions of citizens and drives local SI firms to specialize in secure, high-volume connectors. Japan and South Korea are investing resources in smart factory initiatives, where edge brokers synchronize robots with ERP systems in real-time. Southeast Asian nations utilize cloud-first regulatory sandboxes to jump-start fintech innovation, creating niches for lightweight integration runtimes.
- IBM Corporation
- Microsoft Corporation
- Oracle Corporation
- SAP SE
- Salesforce Inc. (MuleSoft LLC)
- Software AG
- TIBCO Software Inc.
- Fujitsu Ltd.
- iTransition Group
- Dell Boomi LLC
- Informatica LLC
- SnapLogic Inc.
- Workato Inc.
- Celigo Inc.
- Jitterbit Inc.
- Talend S.A.
- Red Hat Inc.
- WSO2 Inc.
- Cleo Communications Inc.
- OpenLegacy Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 API-Led Connectivity Accelerating Saas Adoption
- 4.2.2 Cloud-Native Ipaas as De-Facto Integration Backbone
- 4.2.3 Event-Driven Architectures Enabling Real-Time Analytics
- 4.2.4 Generative-AI Assisted Mapping and Testing Tools
- 4.2.5 Carbon-Aware Workload Routing Mandates
- 4.2.6 Vendor-Agnostic Integration Marketplaces for Micro-Saas
- 4.3 Market Restraints
- 4.3.1 Open-Source ESB Alternatives Eroding Licence Revenue
- 4.3.2 Shortage of Integration-Skill Talent Inflating Project Costs
- 4.3.3 Hidden Egress-Fee Economics In Hyperscale Clouds
- 4.3.4 Legacy Technical-Debt Penalties on API Security Posture
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 On-premise
- 5.1.2 Cloud
- 5.1.3 Hybrid
- 5.2 By Integration Platform Type
- 5.2.1 Enterprise Service Bus (ESB)
- 5.2.2 Integration Platform-as-a-Service (iPaaS)
- 5.2.3 API-Gateway / Management Suites
- 5.2.4 Data and ETL/ELT Tools
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-sized Enterprises
- 5.4 By Application Area
- 5.4.1 CRM Integration
- 5.4.2 ERP and Finance Integration
- 5.4.3 Supply-Chain / Logistics Integration
- 5.4.4 HR and Workforce Integration
- 5.4.5 Business Intelligence and Analytics Integration
- 5.5 By End-user Industry
- 5.5.1 BFSI
- 5.5.2 IT and Telecom
- 5.5.3 Healthcare
- 5.5.4 Retail and E-commerce
- 5.5.5 Government
- 5.5.6 Manufacturing
- 5.5.7 Other End-user Industry
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Spain
- 5.6.2.5 Italy
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Israel
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 United Arab Emirates
- 5.6.5.1.4 Turkey
- 5.6.5.1.5 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Microsoft Corporation
- 6.4.3 Oracle Corporation
- 6.4.4 SAP SE
- 6.4.5 Salesforce Inc. (MuleSoft LLC)
- 6.4.6 Software AG
- 6.4.7 TIBCO Software Inc.
- 6.4.8 Fujitsu Ltd.
- 6.4.9 iTransition Group
- 6.4.10 Dell Boomi LLC
- 6.4.11 Informatica LLC
- 6.4.12 SnapLogic Inc.
- 6.4.13 Workato Inc.
- 6.4.14 Celigo Inc.
- 6.4.15 Jitterbit Inc.
- 6.4.16 Talend S.A.
- 6.4.17 Red Hat Inc.
- 6.4.18 WSO2 Inc.
- 6.4.19 Cleo Communications Inc.
- 6.4.20 OpenLegacy Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 應用整合市場:全球市場預測,2026-2032年
 企業應用整合市場預測至2034年-按組件、部署模式、整合類型、組織規模、最終用戶和地區分類的全球分析
 2026年全球應用整合與協作市場報告2026年下一代營運支援系統(OSS)和業務支撐系統(BSS)全球市場報告2026年全球企業應用整合市場報告2026年全球應用整合市場報告企業應用整合市場:按組件、整合方法、應用、產業、部署模式和企業規模分類-全球預測,2026-2032年
 應用整合市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶、解決方案和功能分類
 應用整合市場規模、佔有率和成長分析(按整合類型、部署模式、組件、組織規模、最終用戶產業和地區分類)-2026-2033年產業預測
 HubSpot諮詢服務:全球市場佔有率和排名、總收入和需求預測(2025-2031)