

 |
市場調查報告書
商品編碼
2174825
後量子密碼市場:按解決方案分類 - 全球預測至 2031 年Post-Quantum Cryptography Market by Solution (Cryptographic Discovery, Risk & Migration Management Software, Quantum-Safe Key Management & Cryptographic Infrastructure, PKI, Digital Signatures & Identity Security Solutions) - Global Forecast to 2031 |
||||||

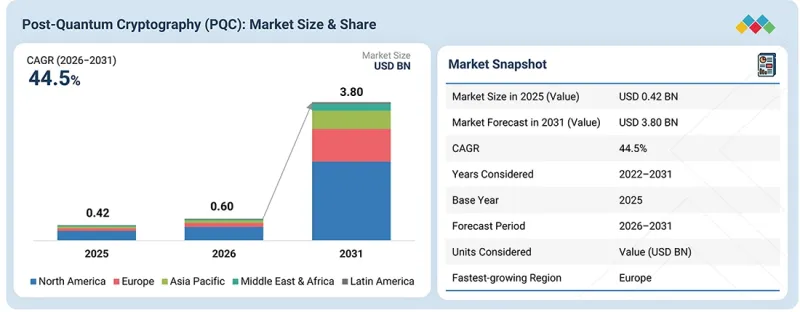
預計後量子密碼(PQC)市場將從 2026 年的 6 億美元成長到 2031 年的 38 億美元,在預測期內複合年成長率將達到 44.5%。
日益成長的網路安全風險、數位基礎設施的現代化以及保護長期儲存的敏感資訊的需要,促使各組織重新評估其加密環境。
| 調查範圍 | |
|---|---|
| 調查期 | 2022-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 10億美元 |
| 部分 | 產品/服務、組織規模、產業和地區 |
| 目標區域 | 北美洲、歐洲、亞太地區、中東和非洲、拉丁美洲 |
根據ITPro 2026年7月發布的報告(其中包含DigiCert的一項調查),85%的受訪IT和安全高管認為量子計算可能在10年內威脅到現有的安全標準,而僅有7%的受訪者表示已部署了抗量子證書。報告也顯示,近九成受訪者正在規劃、測試或實施抗量子密碼(PQC)舉措。這些發現凸顯了認知與實施之間的差距,為抗量子解決方案、密碼分析工具、遷移管理軟體和專業部署服務創造了商機。
“預計在預測期內,服務業將錄得最高的複合年成長率。”
組織機構需要專家服務來識別易受攻擊的加密資產、評估遷移優先級,並將抗量子攻擊技術整合到舊有系統、雲端平台和企業網路中。設計和諮詢服務有助於制定遷移計劃,而部署和遷移服務則有助於應用程式、憑證和通訊協定的升級。量子風險評估使組織機構能夠評估其風險敞口並確定關鍵系統的優先順序。根據 DigiCert 發布的《2026 年量子就緒展望》,87% 的受訪組織機構正在規劃、測試或實施 PQC(抗量子加密)舉措,但只有 7% 的機構已大規模部署了抗量子證書或混合證書。這一差距凸顯了將就緒計畫轉化為實際部署所需的專業知識的重要性。
“從組織規模的細分來看,預計到 2026 年,大型企業將佔據最大的市場佔有率。”
由於加密資產分散在舊有應用程式、雲端平台、網路、數位憑證和第三方系統中,大型企業面臨複雜的加密資產遷移需求。這種環境需要協調一致的資產識別、風險優先排序、互通性測試和分階段部署。根據 DigiCert 發布的《2026 年量子就緒展望》,雖然 87% 的受訪組織正在規劃、測試或實施加密資產舉措,但只有 7% 的組織大規模部署了抗量子或混合證書。這一差距凸顯了組織在從規劃過渡到部署過程中所面臨的實施挑戰。大型企業預計需要加密資產發現工具、集中式金鑰管理、抗量子安全解決方案和專業的遷移服務,才能在維持業務連續性的同時實現基礎設施現代化。
“從區域分類來看,預計歐洲在預測期內將實現最高的複合年成長率。”
隨著各國政府和關鍵基礎設施營運商為向抗量子密碼技術過渡做好準備,歐洲的量子密碼(PQC)市場預計將會擴張。 2025年6月,歐盟成員國通過了一項協調部署藍圖,建議所有成員國在2026年底前開始向PQC過渡;對於高風險用例,過渡應儘早進行,最遲不得晚於2030年底。這些里程碑預計將加速政府、金融服務、電信和其他關鍵領域的加密評估、過渡規劃和部署。各組織需要識別易受攻擊的加密資產,評估其對技術的依賴程度,測試互通性,並規分類階段升級。隨著歐洲各組織為實現該地區協調一致的過渡目標做好準備,對加密資產發現工具、抗量子身分解決方案、金鑰管理、安全通訊和專業過渡服務的需求預計將會增加。
受訪者構成
本次調查匯集了來自各行各業專家的見解,包括元件供應商、一級供應商和整車製造商。主要受訪者組成如下:
- 按公司類型分類:一級供應商 - 25%,二級供應商 - 30%,三級供應商 - 45%
- 按職位分類:首席級別主管 - 40%,經理及其他職位- 60%
- 按地區分類:北美 -35%,歐洲 -25%,亞太地區 -30%,中東和非洲 -5%,拉丁美洲 -5%
本研究對 PQC 市場的主要參與者進行了詳細的競爭分析,包括公司簡介、近期發展和主要市場策略。
調查範圍
本報告按產品(解決方案(抗量子硬體、PQC 加密軟體、庫、SDK 和 IP、加密分析、風險和遷移管理軟體、抗量子 PKI、數位簽章和身分安全解決方案、抗量子金鑰管理和加密基礎設施、抗量子網路和通訊安全解決方案、PQC 應用、韌體和設備安全解決方案以及其他專用 PQC解決方案)、服務(設計、實施和諮詢、遷移服務、量子風險評估))、組織規模(大型企業、中小企業)、行業(銀行、金融服務和保險 (BFSI)、政府和國防、醫療保健、IT 和 ITES、零售和電子商務以及其他行業(汽車、電信、能源和公共產業、媒體和娛樂、運輸和物流、教育)和美國地區(北美、歐洲和亞太市場)。
此外,本研究還包括對市場主要參與者的詳細競爭分析,涵蓋公司簡介、產品和服務的主要觀察、近期發展和主要市場策略。
購買本報告的主要好處
本報告透過提供整個PQC市場及其細分市場最準確的市場收入預測,為市場領導者和新參與企業提供協助。它有助於相關人員了解競爭格局,更好地定位自身業務,並制定有效的打入市場策略。此外,報告還深入分析了市場趨勢、關鍵促進因素、挑戰和機會。
本報告深入分析了以下幾點:
對關鍵促進因素(量子抗性密碼演算法的整合、混合 PQC 機制的採用、網路安全和資料隱私意識的提高、對量子運算威脅的日益關注、對密碼學現代化日益成長的需求、產學研合作)、阻礙因素(PQC 部署和遷移的高成本、升級傳統密碼基礎設施的複雜性)、機遇(PQC整合到區塊鏈網路中、為聯網設備提供量子抗性保護、開發量子抗性密碼產品、政府和國防部門的遷移舉措、密碼發現和遷移管理、關鍵基礎設施的量子抗性解決方案)以及挑戰(密鑰長度的增加及其對性能的潛在影響、與現有密碼系統的整合、兼容性和互通性問題、缺乏 PQC 專業知識)的分析。
- 產品開發/創新:深入了解 PQC 市場的未來技術、研發活動、新產品和服務推出。
- 市場發展:盈利市場的全面資訊-本報告分析了各個地區的 PQC 市場。
- 市場多元化:全面介紹 PQC 市場的新產品和服務、未開發的市場、近期趨勢和投資機會。
- 競爭分析:對 PQC 市場主要參與者的市場佔有率、成長策略和服務產品進行詳細評估。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 後量子密碼市場為企業提供了極具吸引力的機會
- 後量子密碼市場:透過提供
- 後量子密碼市場:按解決方案分類
- 後量子密碼市場:依產業分類
- 後量子密碼學市場:按地區分類
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 相互關聯的市場
- 跨產業機遇
- 一級/二級/三級主要公司的策略性舉措
- 各層級戰略模式
- 策略趨勢
第5章 產業趨勢
- 運用波特五力模型進行分析
- 新進入者的威脅
- 替代品的威脅
- 供應商的議價能力
- 買方的議價能力
- 競爭公司之間的競爭強度
- 總體經濟指標
- GDP趨勢與預測
- 全球資訊通訊技術產業趨勢
- 價值鏈分析
- 技術基礎設施提供者
- 後量子密碼學提供商
- 應用開發公司
- 系統整合商
- 按行業
- 生態系分析
- 價格分析
- 主要後量子密碼學供應商按解決方案分類的平均售價
- 主要參與者的參考價格分析
- 貿易分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢和顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 案例研究
- 美國關稅對2025年後量子密碼學市場的影響
- 主要關稅稅率
- 價格影響分析
- 對國家和地區的影響
- 對產業的影響
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要技術
- 互補技術
- 鄰近技術
- 技術和產品藍圖
- 短期(2026-2027 年)| 基礎設施建設和初步商業化
- 中期計畫(2027-2030 年)| 技術成熟與產品整合
- 長期(2030-2035 年及以後)| 自主加密管理與持續保障
- 專利分析
- 未來應用
- 符合 PQC 標準的企業網路和安全通訊
- 抗量子攻擊的雲和資料保護
- 後量子數位身分和公鑰基礎設施
- 物聯網、嵌入式系統和關鍵基礎設施的品質控制
- 密碼技術的發現、過渡和密碼敏捷性。
- 人工智慧/生成式人工智慧對後量子密碼市場的影響
- 後量子密碼學市場的最佳實踐
- 相互關聯的鄰近生態系及其對市場參與者的影響
- 後量子密碼市場中客戶對生成式人工智慧應用的準備情況
- 成功案例和實際應用
- Cloudflare:網路通訊的後量子保護
- AKAMAI:用於TLS連接的後量子密碼學
第7章 監理情勢
- 區域法規和合規性
- 與PQC產品相關的關稅
- 監管機構、政府機構和其他組織
- 業界標準
第8章 消費者趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 採購過程中涉及的關鍵相關人員
- 購買標準
- 實施障礙和內部挑戰
- 各終端用戶產業未滿足的需求
第9章:後量子密碼市場:依產品/服務分類
- 解決方案
- 服務
第10章 後量子密碼市場:依組織規模分類
- 小型企業
- 大公司
第11章:後量子密碼市場:依產業分類
- 銀行、金融服務和保險(BFSI)
- 政府/國防
- 醫療保健
- 資訊科技與資訊科技服務
- 零售與電子商務
- 其他行業
第12章 後量子密碼學(PQC)市場:按地區分類
- 北美洲
- 北美:市場促進因素
- 美國
- 加拿大
- 歐洲
- 歐洲:市場促進因素
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 亞太地區:市場促進因素
- 中國
- 日本
- 印度
- 亞太其他地區
- 中東和非洲
- 中東和非洲:市場促進因素
- 中東
- 非洲
- 拉丁美洲
- 拉丁美洲:市場促進因素
- 巴西
- 墨西哥
- 其他拉丁美洲
第13章 競爭格局
- 主要參與企業的策略/優勢,2021-2025年
- 2022-2025年收入分析
- 市佔率分析(2025 年)
- 品牌對比
- 企業估值矩陣:現有公司
- 明星公司
- 新興領導者
- 玩家種類繁多
- 參與企業
- 企業企業發展:現有公司
- 企業估值矩陣:後量子密碼專家/新創公司
- 星星
- 一位冉冉升起的領導者
- 具有廣泛影響力的公司
- 參與企業
- 競爭基準分析:後量子密碼專家/新創公司
- 企業估值和財務指標
- 2025 年企業估值
- 使用EV/EBITDA的財務指標
- 競爭格局
- 產品發布和功能增強
- 交易
第14章:公司簡介
- 大公司
- NXP SEMICONDUCTORS
- THALES
- AWS
- IDEMIA
- PALO ALTO NETWORKS
- ST ENGINEERING
- PQCEE
- DIGICERT
- KLOCH
- PATERO
- POST-QUANTUM
- PQSHIELD
- ENTRUST
- IBM
- QNU LABS
- UTIMACO
- JISA SOFTECH
- QUANTUM XCHANGE
- 其他主要公司
- QUANTROPI
- ARQIT
- CRYPTO QUANTIQUE
- CRYPTO4A
- CRYPTONEXT
- QRYPT
- ENQUANTUM
- XIPHERA
- SIXSCAPE
- KEYFACTOR
- RESQUANT
- RAMBUS
- ARCHON
- KEYSIGHT TECHNOLOGIES
第15章:調查方法
第16章附錄
The post-quantum cryptography (PQC) market is projected to grow from USD 0.60 billion in 2026 to USD 3.80 billion by 2031, registering a CAGR of 44.5% during the forecast period. Increasing cybersecurity risks, the modernization of digital infrastructure, and the need to protect long-lived sensitive information are encouraging organizations to reassess their cryptographic environments.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | USD Billion |
| Segments | Offering, Organization Size, Vertical, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
In a July 2026 ITPro report covering DigiCert research, 85% of surveyed IT and security leaders believed quantum computing could compromise existing security standards within a decade, while only 7% reported deploying quantum-safe certificates. The report also found that nearly nine in ten respondents were planning, testing, or implementing PQC initiatives. These findings highlight the gap between awareness and implementation, creating opportunities for quantum-safe solutions, cryptographic discovery tools, migration management software, and specialized implementation services.
"By offering, the services segment is expected to witness the highest CAGR during the forecast period."
Organizations require specialized services to identify vulnerable cryptographic assets, assess migration priorities, and integrate quantum-resistant technologies across legacy systems, cloud platforms, and enterprise networks. Design and consulting services support migration planning, while implementation and migration services help upgrade applications, certificates, and communication protocols. Quantum risk assessments enable organizations to evaluate exposure and prioritize critical systems. According to DigiCert's 2026 Quantum Readiness Outlook, 87% of surveyed organizations were planning, testing, or implementing PQC initiatives, but only 7% had deployed quantum-safe or hybrid certificates at scale. This gap highlights the need for specialized expertise to translate readiness plans into practical deployments.
"By organization size, the large enterprises segment is projected to hold the largest market share in 2026."
Large enterprises face complex PQC migration requirements because cryptographic assets are distributed across legacy applications, cloud platforms, networks, digital certificates, and third-party systems. These environments require coordinated asset discovery, risk prioritization, interoperability testing, and phased deployment. DigiCert's 2026 Quantum Readiness Outlook found that 87% of surveyed organizations were planning, testing, or implementing PQC initiatives, while only 7% had deployed quantum-safe or hybrid certificates at scale. This gap highlights the implementation challenges organizations face when moving from readiness planning to deployment. Large enterprises are expected to require cryptographic discovery tools, centralized key management, quantum-safe security solutions, and specialized migration services to modernize infrastructure while maintaining operational continuity.
"By region, Europe is expected to grow at the highest CAGR during the forecast period."
Europe's PQC market is expected to expand as governments and critical infrastructure operators prepare for the transition to quantum-resistant cryptography. In June 2025, EU member states adopted a coordinated implementation roadmap recommending that all member states begin transitioning to PQC by the end of 2026, with high-risk use cases transitioned as soon as possible and no later than the end of 2030. These milestones are expected to accelerate cryptographic assessments, migration planning, and deployment across public administration, financial services, telecommunications, and other critical sectors. Organizations will need to identify vulnerable cryptographic assets, evaluate technology dependencies, test interoperability, and plan phased upgrades. This is expected to increase demand for cryptographic discovery tools, quantum-safe identity solutions, key management, secure communications, and specialized migration services as European organizations prepare for the region's coordinated transition targets.
Breakdown of Primaries
The study draws insights from a range of industry experts, including component suppliers, Tier 1 companies, and OEMs. The breakdown of the primaries is as follows:
- By Company Type: Tier 1 - 25%, Tier 2 - 30%, and Tier 3 - 45%
- By Designation: C-level Executives - 40%, Managers and Other Levels - 60%
- By Region: North America - 35%, Europe - 25%, Asia Pacific - 30%, Middle East & Africa - 5%, Latin America - 5%
Major vendors in the PQC market include NXP Semiconductors (Netherlands), Thales (France), AWS (US), IDEMIA (France), Palo Alto Networks (US), ST Engineering (Singapore), DigiCert (US), Kloch (US), Patero (US), Post-Quantum (UK), PQShield (UK), Entrust (US), IBM (US), QNu Labs (India), Utimaco (Germany), JISA Softech (India), pQCee (Singapore), Quantum XChange (US), Keysight Technologies (US), Quantropi (Canada), Arqit (UK), Crypto Quantique (UK), Crypto4A (Canada), CryptoNext Security (France), Qrypt (US), EnQuantum (Israel), Xiphera (Finland), Sixscape (Singapore), Keyfactor (US), ResQuant (Poland), and Rambus (US). The study includes an in-depth competitive analysis of the key players in the PQC market, their company profiles, recent developments, and key market strategies.
Research Coverage
The report segments the PQC market and forecasts its size based on offering (solutions (quantum-safe hardware, PQC cryptographic software, libraries, SDKs & IP, cryptographic discovery, risk & migration management software, quantum-safe PKI, digital signatures & identity security solutions, quantum-safe key management & cryptographic infrastructure, quantum-safe network & communication security solutions, PQC application, firmware & device security solutions, and other specialized PQC solutions), services (design, implementation & consulting, migration services, and quantum risk assessment)), organization size (large enterprises, SMEs), vertical (BFSI, government & defense, healthcare, IT & ITES, retail & e-commerce, and other verticals (automotive, telecommunications, energy & utilities, media & entertainment, transportation & logistics, and education)), and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America).
The study also includes an in-depth competitive analysis of the market's key players, including company profiles, key observations on product and business offerings, recent developments, and key market strategies.
Key Benefits of Buying the Report
The report will help market leaders/new entrants with the closest available revenue estimates for the overall PQC market and its subsegments. This report helps stakeholders understand the competitive landscape and gain insights to better position their businesses and plan effective go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
Analysis of critical drivers (Integration of quantum-resistant cryptographic algorithms, Adoption of hybrid PQC mechanisms, Growing awareness of cybersecurity and data privacy, Increasing concerns about quantum computing threats, Rising demand for cryptographic modernization, Collaboration between industry, academia, and government), restraints (High PQC implementation and migration costs, Complexity of upgrading legacy cryptographic infrastructure), opportunities (PQC integration in blockchain networks, Quantum-safe protection for connected devices, Development of quantum-safe cryptographic products, Government and defense migration initiatives, Cryptographic discovery and migration management, Quantum-safe solutions for critical infrastructure), and challenges (Larger key sizes and potential performance impacts, Integration with existing cryptographic systems, Compatibility and interoperability issues, Shortage of specialized PQC expertise).
- Product Development/Innovation: Detailed insights on upcoming technologies, research and development activities, new products, and service launches in the PQC market.
- Market Development: Comprehensive information about lucrative markets - the report analyzes the PQC market across varied regions.
- Market Diversification: Exhaustive information about new products and services, untapped geographies, recent developments, and investments in the PQC market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as Patero (US), pQCee (Singapore), JISA Softech (India), PQShield (UK), NXP Semiconductors (Netherlands), Thales (France), IBM (US), Crypto4A (Canada), Quantropi (Canada), and Utimaco (Germany), among others, in the PQC market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN POST-QUANTUM CRYPTOGRAPHY MARKET
- 3.2 POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING
- 3.3 POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION
- 3.4 POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL
- 3.5 POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Integration of innovative cryptographic algorithms
- 4.2.1.2 Hybrid PQC mechanisms
- 4.2.1.3 Growing awareness of cybersecurity and data privacy
- 4.2.1.4 Increasing awareness of quantum computing threats
- 4.2.1.5 Rising demand for optimized PQC implementations to handle global encryption workloads
- 4.2.1.6 Collaboration between academia, industry, and government on PQC adoption
- 4.2.2 RESTRAINTS
- 4.2.2.1 High implementation costs
- 4.2.2.2 Lack of standardized algorithms
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 PQC integration in blockchain networks
- 4.2.3.2 Advancements in high-performance computing architectures
- 4.2.3.3 Emerging demand for PQC products and specialized consulting services
- 4.2.3.4 Government and defense contracts
- 4.2.3.5 Migration to post-quantum cryptography
- 4.2.4 CHALLENGES
- 4.2.4.1 Significantly large key sizes and performance implications
- 4.2.4.2 Implementation challenges
- 4.2.4.3 Lack of skilled workforce
- 4.2.4.4 Vulnerabilities due to advancements in quantum technology
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 CROSS-TIER STRATEGIC PATTERNS
- 4.5.2 STRATEGIC TRENDS
- 4.5.2.1 Shift from algorithm standardization toward enterprise deployment
- 4.5.2.2 Growing emphasis on cryptographic discovery and risk-based migration
- 4.5.2.3 Integration of PQC into existing security infrastructure
- 4.5.2.4 Expansion of crypto-agility and hybrid cryptographic deployments
- 4.5.2.5 Increasing focus on performance, validation, and interoperability
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES MODEL ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL ICT INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 TECHNOLOGY INFRASTRUCTURE PROVIDERS
- 5.3.2 POST-QUANTUM CRYPTOGRAPHY PROVIDERS
- 5.3.3 APPLICATION DEVELOPERS
- 5.3.4 SYSTEM INTEGRATORS
- 5.3.5 VERTICALS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF KEY POST-QUANTUM CRYPTOGRAPHY VENDORS, BY SOLUTION
- 5.5.2 INDICATIVE PRICING ANALYSIS FOR KEY PLAYERS
- 5.6 TRADE ANALYSIS
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 CASE STUDIES
- 5.10.1.1 Thales and pQCee secure quantum key distribution connectivity using HSMs
- 5.10.1.2 Post-quantum cryptography for defense and government applications
- 5.10.1.3 Adoption of BIO-key's identity-bound biometrics solution as part of passwordless authentication strategy
- 5.10.1.4 Wells Fargo, Thales, and Quantinuum - Quantum entropy for stronger cryptographic keys
- 5.10.1.5 World's leading payment infrastructure partnered with QNu Labs to achieve 100% PQC compliance
- 5.10.1.6 Quantum-resilient data security in healthcare: A critical imperative
- 5.10.1 CASE STUDIES
- 5.11 IMPACT OF 2025 US TARIFF - POST-QUANTUM CRYPTOGRAPHY MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 North America
- 5.11.4.1.1 US
- 5.11.4.1.2 Canada
- 5.11.4.1.3 Mexico
- 5.11.4.2 Europe
- 5.11.4.2.1 Germany
- 5.11.4.2.2 France
- 5.11.4.2.3 UK
- 5.11.4.3 Asia Pacific
- 5.11.4.3.1 China
- 5.11.4.3.2 Japan
- 5.11.4.3.3 India
- 5.11.4.1 North America
- 5.11.5 IMPACT ON INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Lattice-based cryptography
- 6.1.1.2 Code-based cryptography
- 6.1.1.3 Hash-based cryptography
- 6.1.1.4 Multivariate cryptography
- 6.1.1.5 Symmetric key quantum resistance
- 6.1.1.6 Isogeny-based cryptography
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Quantum-resistant hardware accelerators
- 6.1.2.2 Cloud-based PQC
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Quantum computing
- 6.1.3.2 Post-quantum cybersecurity
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT-TERM (2026-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.2.2 MID-TERM (2027-2030) | TECHNOLOGY MATURATION & PRODUCT INTEGRATION
- 6.2.3 LONG-TERM (2030-2035+) | AUTONOMOUS CRYPTOGRAPHIC MANAGEMENT & CONTINUOUS ASSURANCE
- 6.3 PATENT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 PQC-ENABLED ENTERPRISE NETWORKS AND SECURE COMMUNICATIONS
- 6.4.2 QUANTUM-SAFE CLOUD AND DATA PROTECTION
- 6.4.3 POST-QUANTUM DIGITAL IDENTITY AND PKI
- 6.4.4 PQC FOR IOT, EMBEDDED SYSTEMS, AND CRITICAL INFRASTRUCTURE
- 6.4.5 CRYPTOGRAPHIC DISCOVERY, MIGRATION, AND CRYPTO-AGILITY
- 6.5 IMPACT OF AI/GEN AI ON POST-QUANTUM CRYPTOGRAPHY MARKET
- 6.5.1 BEST PRACTICES IN POST-QUANTUM CRYPTOGRAPHY MARKET
- 6.5.2 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN POST-QUANTUM CRYPTOGRAPHY MARKET
- 6.6 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.6.1 CLOUDFLARE: POST-QUANTUM PROTECTION FOR NETWORK COMMUNICATIONS
- 6.6.2 AKAMAI: POST-QUANTUM CRYPTOGRAPHY FOR TLS CONNECTIONS
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 TARIFF RELATED TO PQC PRODUCTS
- 7.1.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.3 INDUSTRY STANDARDS
8 CONSUMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
9 POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: POST-QUANTUM CRYPTOGRAPHY MARKET DRIVERS
- 9.2 SOLUTIONS
- 9.2.1 QUANTUM-SAFE HARDWARE
- 9.2.1.1 Rising need for secure hardware-based key storage and accelerated PQC adoption across devices
- 9.2.2 PQC CRYPTOGRAPHIC SOFTWARE, LIBRARIES, SDKS, & IP
- 9.2.2.1 Growing demand for standardized cryptographic software supporting enterprise PQC integration
- 9.2.3 CRYPTOGRAPHIC DISCOVERY, RISK, & MIGRATION MANAGEMENT SOFTWARE
- 9.2.3.1 Growing complexity of enterprise cryptographic environments increasing need for automated discovery and migration planning
- 9.2.4 QUANTUM-SAFE PKI, DIGITAL SIGNATURES, & IDENTITY SECURITY SOLUTIONS
- 9.2.4.1 Need to preserve digital trust accelerating transition to quantum-resistant signatures and identity systems
- 9.2.5 QUANTUM-SAFE KEY MANAGEMENT & CRYPTOGRAPHIC INFRASTRUCTURE
- 9.2.5.1 Growing need for centralized cryptographic control accelerating quantum-safe key management modernization
- 9.2.6 QUANTUM-SAFE NETWORK & COMMUNICATION SECURITY SOLUTIONS
- 9.2.6.1 Growing need to secure encrypted network traffic driving market growth
- 9.2.7 PQC APPLICATION, FIRMWARE, & DEVICE SECURITY SOLUTIONS
- 9.2.7.1 Growing need for quantum-resistant firmware authentication driving market growth
- 9.2.8 OTHER SPECIALIZED PQC SOLUTIONS
- 9.2.1 QUANTUM-SAFE HARDWARE
- 9.3 SERVICES
- 9.3.1 DESIGN, IMPLEMENTATION, & CONSULTING
- 9.3.1.1 Design, implementation, and consulting driving PQC adoption as enterprises need expert integration support
- 9.3.2 MIGRATION
- 9.3.2.1 Migration services fueling growth as organizations shift from legacy to quantum-safe standards
- 9.3.3 QUANTUM RISK ASSESSMENT
- 9.3.3.1 Quantum risk assessment accelerating adoption as businesses seek to uncover and mitigate vulnerabilities early
- 9.3.1 DESIGN, IMPLEMENTATION, & CONSULTING
10 POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE
- 10.1 INTRODUCTION
- 10.1.1 ORGANIZATION SIZE: POST-QUANTUM CRYPTOGRAPHY MARKET DRIVERS
- 10.2 SMALL & MEDIUM-SIZED ENTERPRISES
- 10.2.1 NEED FOR AFFORDABLE, EASY-TO-INTEGRATE QUANTUM-SAFE SOLUTIONS DRIVING MARKET GROWTH
- 10.3 LARGE ENTERPRISES
- 10.3.1 PROTECTION OF INTELLECTUAL PROPERTY AND SENSITIVE CUSTOMER DATA FUELING MARKET GROWTH
11 POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL
- 11.1 INTRODUCTION
- 11.1.1 VERTICAL: POST-QUANTUM CRYPTOGRAPHY MARKET DRIVERS
- 11.2 BANKING, FINANCIAL SERVICES, AND INSURANCE (BFSI)
- 11.2.1 SECURING DIGITAL BANKING, PAYMENTS, AND FINANCIAL RECORDS DRIVING MARKET GROWTH
- 11.3 GOVERNMENT & DEFENSE
- 11.3.1 INCREASING FOCUS ON NATIONAL SECURITY AND RESILIENT COMMUNICATIONS DRIVING MARKET GROWTH
- 11.4 HEALTHCARE
- 11.4.1 GROWING NEED TO PROTECT PATIENT DATA AND ELECTRONIC HEALTH RECORDS DRIVING PQC SOLUTIONS ADOPTION
- 11.5 IT & ITES
- 11.5.1 EXPANDING ADOPTION OF CLOUD AND ENTERPRISE INFRASTRUCTURE SECURITY FUELING MARKET GROWTH
- 11.6 RETAIL & E-COMMERCE
- 11.6.1 RISING IMPORTANCE OF SAFEGUARDING E-COMMERCE AND DIGITAL IDENTITIES DRIVING MARKET GROWTH
- 11.7 OTHER VERTICALS
12 POST-QUANTUM CRYPTOGRAPHY (PQC) MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 NORTH AMERICA: MARKET DRIVERS
- 12.2.2 US
- 12.2.2.1 Driving PQC adoption through federal mandates, national standards, and public-private partnerships
- 12.2.3 CANADA
- 12.2.3.1 Advancing PQC leadership with government funding, university research, and enterprise-level collaborations
- 12.3 EUROPE
- 12.3.1 EUROPE: MARKET DRIVERS
- 12.3.2 UK
- 12.3.2.1 Strengthening PQC readiness through national initiatives and cybersecurity integration programs
- 12.3.3 GERMANY
- 12.3.3.1 Accelerating PQC innovation with public research investment and industrial partnerships
- 12.3.4 FRANCE
- 12.3.4.1 Expanding PQC capabilities through academic excellence and government-backed projects
- 12.3.5 ITALY
- 12.3.5.1 Strengthening PQC readiness through national cybersecurity initiatives and quantum technology research
- 12.3.6 REST OF EUROPE
- 12.4 ASIA PACIFIC
- 12.4.1 ASIA PACIFIC: MARKET DRIVERS
- 12.4.2 CHINA
- 12.4.2.1 Leading PQC development through state-backed investment and enterprise deployment
- 12.4.3 JAPAN
- 12.4.3.1 Driving PQC applications with strong government support and industry engagement
- 12.4.4 INDIA
- 12.4.4.1 Scaling PQC adoption with national strategy, startups, and academic participation
- 12.4.5 REST OF ASIA PACIFIC
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 MIDDLE EAST & AFRICA: MARKET DRIVERS
- 12.5.2 MIDDLE EAST
- 12.5.2.1 GCC
- 12.5.2.1.1 Accelerating quantum-safe adoption with cybersecurity priorities and digital transformation
- 12.5.2.1.2 KSA
- 12.5.2.1.3 UAE
- 12.5.2.1.4 Rest of GCC
- 12.5.2.2 Rest of Middle East
- 12.5.2.1 GCC
- 12.5.3 AFRICA
- 12.5.3.1 Building PQC foundations through national quantum initiatives, regional collaboration, and academic research
- 12.6 LATIN AMERICA
- 12.6.1 LATIN AMERICA: MARKET DRIVERS
- 12.6.2 BRAZIL
- 12.6.2.1 Expanding PQC adoption with university research and fintech ecosystem initiatives
- 12.6.3 MEXICO
- 12.6.3.1 Developing PQC capabilities through academic partnerships and financial services applications
- 12.6.4 REST OF LATIN AMERICA
13 COMPETITIVE LANDSCAPE
- 13.1 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2021-2025
- 13.2 REVENUE ANALYSIS, 2022-2025
- 13.3 MARKET SHARE ANALYSIS, 2025
- 13.4 BRAND COMPARISON
- 13.5 COMPANY EVALUATION MATRIX: ESTABLISHED PLAYERS
- 13.5.1 STARS
- 13.5.2 EMERGING LEADERS
- 13.5.3 PERVASIVE PLAYERS
- 13.5.4 PARTICIPANTS
- 13.5.5 COMPANY FOOTPRINT: ESTABLISHED PLAYERS
- 13.5.5.1 Company footprint
- 13.5.5.2 Regional footprint
- 13.5.5.3 Offering footprint
- 13.5.5.4 Vertical footprint
- 13.6 COMPANY EVALUATION MATRIX: POST-QUANTUM CRYPTOGRAPHY SPECIALISTS/STARTUPS
- 13.6.1 STARS
- 13.6.2 EMERGING LEADERS
- 13.6.3 PERVASIVE PLAYERS
- 13.6.4 PARTICIPANTS
- 13.6.5 COMPETITIVE BENCHMARKING: POST-QUANTUM CRYPTOGRAPHY SPECIALISTS/STARTUPS
- 13.6.5.1 Detailed list of key post-quantum cryptography specialists/startups
- 13.6.5.2 Competitive benchmarking of key post-quantum cryptography specialists/startups
- 13.7 COMPANY VALUATION AND FINANCIAL METRICS
- 13.7.1 COMPANY VALUATION, 2025
- 13.7.2 FINANCIAL METRICS USING EV/EBITDA
- 13.8 COMPETITIVE SCENARIO
- 13.8.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 13.8.2 DEALS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 NXP SEMICONDUCTORS
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product launches/enhancements
- 14.1.1.3.2 Deals
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 THALES
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches/enhancements
- 14.1.2.3.2 Deals
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 AWS
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Product launches/enhancements
- 14.1.3.4 Deals
- 14.1.3.5 MnM view
- 14.1.3.5.1 Key strengths
- 14.1.3.5.2 Strategic choices
- 14.1.3.5.3 Weaknesses and competitive threats
- 14.1.4 IDEMIA
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches/enhancements
- 14.1.4.3.2 Deals
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 PALO ALTO NETWORKS
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Product launches/enhancements
- 14.1.5.3.2 Deals
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 ST ENGINEERING
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Product launches/enhancements
- 14.1.6.3.2 Deals
- 14.1.7 PQCEE
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches/enhancements
- 14.1.7.3.2 Deals
- 14.1.8 DIGICERT
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Product launches/enhancements
- 14.1.8.3.2 Deals
- 14.1.9 KLOCH
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.10 PATERO
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services Offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Product launches/enhancements
- 14.1.10.3.2 Deals
- 14.1.11 POST-QUANTUM
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.12 PQSHIELD
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.12.3 Recent developments
- 14.1.12.3.1 Product launches/enhancements
- 14.1.12.3.2 Deals
- 14.1.13 ENTRUST
- 14.1.13.1 Business overview
- 14.1.13.2 Products/Solutions/Services offered
- 14.1.13.3 Recent developments
- 14.1.13.3.1 Product launches/enhancements
- 14.1.14 IBM
- 14.1.14.1 Business overview
- 14.1.14.2 Products/Solutions/Services offered
- 14.1.14.3 Recent developments
- 14.1.14.3.1 Product launches/enhancements
- 14.1.14.3.2 Deals
- 14.1.15 QNU LABS
- 14.1.15.1 Business overview
- 14.1.15.2 Products/Solutions/Services offered
- 14.1.15.3 Recent developments
- 14.1.15.3.1 Product launches/enhancements
- 14.1.15.3.2 Deals
- 14.1.16 UTIMACO
- 14.1.16.1 Business overview
- 14.1.16.2 Products/Solutions/Services offered
- 14.1.16.3 Recent developments
- 14.1.16.3.1 Product launches/enhancements
- 14.1.16.3.2 Deals
- 14.1.17 JISA SOFTECH
- 14.1.17.1 Business overview
- 14.1.17.2 Products/Solutions/Services offered
- 14.1.17.3 Recent developments
- 14.1.17.3.1 Product launches/enhancements
- 14.1.17.3.2 Deals
- 14.1.17.3.3 Expansions
- 14.1.18 QUANTUM XCHANGE
- 14.1.18.1 Business overview
- 14.1.18.2 Products/Solutions/Services offered
- 14.1.18.3 Recent developments
- 14.1.18.3.1 Product launches/enhancements
- 14.1.18.3.2 Deals
- 14.1.1 NXP SEMICONDUCTORS
- 14.2 OTHER PLAYERS
- 14.2.1 QUANTROPI
- 14.2.2 ARQIT
- 14.2.3 CRYPTO QUANTIQUE
- 14.2.4 CRYPTO4A
- 14.2.5 CRYPTONEXT
- 14.2.6 QRYPT
- 14.2.7 ENQUANTUM
- 14.2.8 XIPHERA
- 14.2.9 SIXSCAPE
- 14.2.10 KEYFACTOR
- 14.2.11 RESQUANT
- 14.2.12 RAMBUS
- 14.2.13 ARCHON
- 14.2.14 KEYSIGHT TECHNOLOGIES
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Breakup of primary profiles
- 15.1.2.2 Key industry insights
- 15.2 DATA TRIANGULATION
- 15.3 MARKET SIZE ESTIMATION
- 15.4 MARKET FORECAST
- 15.5 RESEARCH ASSUMPTIONS
- 15.6 RESEARCH LIMITATIONS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS
List of Tables
- TABLE 1 USD EXCHANGE RATES, 2022-2025
- TABLE 2 UNMET NEEDS AND WHITE SPACES IN POST-QUANTUM CRYPTOGRAPHY MARKET
- TABLE 3 STRATEGIC MOVES BY PLAYERS IN POST-QUANTUM CRYPTOGRAPHY MARKET
- TABLE 4 CROSS-TIER STRATEGIC PATTERNS OF VENDORS
- TABLE 5 IMPACT OF PORTER'S FIVE FORCES ON POST-QUANTUM CRYPTOGRAPHY MARKET
- TABLE 6 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2030
- TABLE 7 ROLE OF COMPANIES IN POST-QUANTUM CRYPTOGRAPHY MARKET ECOSYSTEM
- TABLE 8 AVERAGE SELLING PRICE OF KEY POST-QUANTUM CRYPTOGRAPHY VENDORS, BY SOLUTION, 2025 (USD)
- TABLE 9 INDICATIVE PRICING OF POST-QUANTUM CRYPTOGRAPHY OFFERINGS, BY KEY PLAYER, 2025 (USD)
- TABLE 10 POST-QUANTUM CRYPTOGRAPHY MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 11 KEY TARIFF RATES
- TABLE 12 LIST OF TOP PATENTS IN POST-QUANTUM CRYPTOGRAPHY MARKET, 2024-2026
- TABLE 13 TOP USE CASES AND MARKET POTENTIAL
- TABLE 14 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 15 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 16 TARIFF RELATED TO PQC PRODUCTS, 2025
- TABLE 17 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 LATIN AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 GLOBAL INDUSTRY STANDARDS IN POST-QUANTUM CRYPTOGRAPHY MARKET
- TABLE 23 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- TABLE 24 KEY BUYING CRITERIA FOR TOP THREE VERTICALS
- TABLE 25 UNMET NEEDS IN POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL
- TABLE 26 POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 27 POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 28 SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 29 SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 30 SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 31 SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 32 QUANTUM-SAFE HARDWARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 33 QUANTUM-SAFE HARDWARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 34 PQC CRYPTOGRAPHIC SOFTWARE, LIBRARIES, SDKS, & IP: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 35 PQC CRYPTOGRAPHIC SOFTWARE, LIBRARIES, SDKS, & IP: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 36 CRYPTOGRAPHIC DISCOVERY, RISK, AND MIGRATION MANAGEMENT SOFTWARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 37 CRYPTOGRAPHIC DISCOVERY, RISK, AND MIGRATION MANAGEMENT SOFTWARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 38 QUANTUM-SAFE PKI, DIGITAL SIGNATURES, AND IDENTITY SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 39 QUANTUM-SAFE PKI, DIGITAL SIGNATURES, AND IDENTITY SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 40 QUANTUM-SAFE KEY MANAGEMENT & CRYPTOGRAPHIC INFRASTRUCTURE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 41 QUANTUM-SAFE KEY MANAGEMENT & CRYPTOGRAPHIC INFRASTRUCTURE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 42 QUANTUM-SAFE NETWORK & COMMUNICATION SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 43 QUANTUM-SAFE NETWORK & COMMUNICATION SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 44 PQC APPLICATION, FIRMWARE, & DEVICE SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 45 PQC APPLICATION, FIRMWARE, & DEVICE SECURITY SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 46 OTHER SPECIALIZED PQC SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 47 OTHER SPECIALIZED PQC SOLUTIONS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 48 SERVICES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 49 SERVICES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 50 SERVICES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 51 SERVICES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 52 DESIGN, IMPLEMENTATION, & CONSULTING: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 53 DESIGN, IMPLEMENTATION, & CONSULTING: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 54 MIGRATION: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 55 MIGRATION: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 56 QUANTUM RISK ASSESSMENT: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 57 QUANTUM RISK ASSESSMENT: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 58 POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 59 POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 60 SMALL & MEDIUM-SIZED ENTERPRISES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 61 SMALL & MEDIUM-SIZED ENTERPRISES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 62 LARGE ENTERPRISES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 63 LARGE ENTERPRISES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 64 POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 65 POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 66 BFSI: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 67 BFSI: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 68 GOVERNMENT & DEFENSE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 69 GOVERNMENT & DEFENSE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 70 HEALTHCARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 71 HEALTHCARE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 72 IT & ITES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 73 IT & ITES: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 74 RETAIL & E-COMMERCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 75 RETAIL & E-COMMERCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 76 OTHER VERTICALS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 77 OTHER VERTICALS: POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 78 POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 79 POST-QUANTUM CRYPTOGRAPHY MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 80 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 81 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 82 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 83 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 84 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 85 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 86 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 87 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 88 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 89 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 90 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 91 NORTH AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 92 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 93 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 94 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 95 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 96 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 97 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 98 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 99 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 100 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 101 US: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 102 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 103 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 104 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 105 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 106 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 107 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 108 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 109 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 110 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 111 CANADA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 112 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 113 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 114 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 115 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 116 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 117 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 118 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 119 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 120 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 121 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 122 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 123 EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 124 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 125 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 126 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 127 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 128 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 129 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 130 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 131 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 132 UK: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 133 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 134 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 135 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 136 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 137 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 138 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 139 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 140 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 141 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 142 GERMANY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 143 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 144 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 145 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 146 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 147 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 148 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 149 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 150 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 151 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 152 FRANCE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 153 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 154 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 155 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 156 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 157 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 158 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 159 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 160 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 161 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 162 ITALY: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 163 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 164 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 165 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 166 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 167 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 168 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 169 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 170 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 171 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 172 REST OF EUROPE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 173 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 174 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 175 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 176 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 177 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 178 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 179 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 180 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 181 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 182 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 183 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 184 ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 185 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 186 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 187 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 188 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 189 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 190 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 191 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 192 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 193 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 194 CHINA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 195 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 196 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 197 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 198 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 199 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 200 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 201 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 202 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 203 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 204 JAPAN: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 205 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 206 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 207 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 208 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 209 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 210 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 211 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 212 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 213 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 214 INDIA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 215 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 216 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 217 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 218 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 219 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 220 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 221 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 222 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 223 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 224 REST OF ASIA PACIFIC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 225 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 226 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 227 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 228 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 229 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 230 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 231 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 232 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 233 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 234 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 235 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SUB-REGION, 2022-2025 (USD MILLION) MIDDLE EAST & AFRICA
- TABLE 236 MIDDLE EAST & AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SUB-REGION, 2026-2031 (USD MILLION)
- TABLE 237 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 238 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 239 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 240 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 241 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 242 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 243 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 244 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 245 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 246 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 247 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 248 GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 249 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 250 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 251 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 252 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 253 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 254 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 255 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 256 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 257 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 258 KSA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 259 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 260 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 261 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 262 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 263 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 264 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 265 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 266 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 267 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 268 UAE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 269 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 270 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 271 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 272 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 273 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 274 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 275 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 276 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 277 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 278 REST OF GCC: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 279 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 280 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 281 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 282 REST OF MIDDLE: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 283 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 284 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 285 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 286 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 287 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 288 REST OF MIDDLE EAST: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 289 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 290 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 291 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 292 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 293 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 294 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 295 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 296 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 297 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 298 AFRICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 299 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 300 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 301 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 302 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 303 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 304 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 305 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 306 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 307 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 308 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 309 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 310 LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 311 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 312 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 313 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 314 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 315 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 316 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 317 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 318 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 319 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 320 BRAZIL: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 321 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 322 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 323 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 324 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 325 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 326 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 327 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 328 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 329 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 330 MEXICO: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 331 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 332 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY OFFERING, 2026-2031 (USD MILLION)
- TABLE 333 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2022-2025 (USD MILLION)
- TABLE 334 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SOLUTION, 2026-2031 (USD MILLION)
- TABLE 335 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2022-2025 (USD MILLION)
- TABLE 336 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY SERVICE, 2026-2031 (USD MILLION)
- TABLE 337 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2022-2025 (USD MILLION)
- TABLE 338 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY ORGANIZATION SIZE, 2026-2031 (USD MILLION)
- TABLE 339 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2022-2025 (USD MILLION)
- TABLE 340 REST OF LATIN AMERICA: POST-QUANTUM CRYPTOGRAPHY MARKET, BY VERTICAL, 2026-2031 (USD MILLION)
- TABLE 341 OVERVIEW OF STRATEGIES ADOPTED BY KEY POST-QUANTUM CRYPTOGRAPHY VENDORS, 2021-2025
- TABLE 342 POST-QUANTUM CRYPTOGRAPHY MARKET: DEGREE OF COMPETITION
- TABLE 343 POST-QUANTUM CRYPTOGRAPHY MARKET: REGION FOOTPRINT
- TABLE 344 POST-QUANTUM CRYPTOGRAPHY MARKET: OFFERING FOOTPRINT
- TABLE 345 POST-QUANTUM CRYPTOGRAPHY MARKET: VERTICAL FOOTPRINT
- TABLE 346 POST-QUANTUM CRYPTOGRAPHY MARKET: SPECIALISTS/STARTUPS
- TABLE 347 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPETITIVE BENCHMARKING OF KEY POST-QUANTUM CRYPTOGRAPHY SPECIALISTS/STARTUPS (OFFERING AND REGION)
- TABLE 348 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPETITIVE BENCHMARKING OF KEY POST-QUANTUM CRYPTOGRAPHY SPECIALISTS/STARTUPS (VERTICAL)
- TABLE 349 POST-QUANTUM CRYPTOGRAPHY MARKET: PRODUCT LAUNCHES/ENHANCEMENTS, JANUARY 2024-OCTOBER 2026
- TABLE 350 POST-QUANTUM CRYPTOGRAPHY MARKET: DEALS, JANUARY 2024-OCTOBER 2026
- TABLE 351 NXP SEMICONDUCTORS: COMPANY OVERVIEW
- TABLE 352 NXP SEMICONDUCTORS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 353 NXP SEMICONDUCTORS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 354 NXP SEMICONDUCTORS: DEALS
- TABLE 355 THALES: COMPANY OVERVIEW
- TABLE 356 THALES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 357 THALES: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 358 THALES: DEALS
- TABLE 359 AWS: COMPANY OVERVIEW
- TABLE 360 AWS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 361 AWS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 362 AWS: DEALS
- TABLE 363 IDEMIA: COMPANY OVERVIEW
- TABLE 364 IDEMIA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 365 IDEMIA: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 366 IDEMIA: DEALS
- TABLE 367 PALO ALTO NETWORKS: COMPANY OVERVIEW
- TABLE 368 PALO ALTO NETWORKS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 369 PALO ALTO NETWORKS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 370 PALO ALTO NETWORKS: DEALS
- TABLE 371 ST ENGINEERING: COMPANY OVERVIEW
- TABLE 372 ST ENGINEERING: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 373 ST ENGINEERING: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 374 ST ENGINEERING: DEALS
- TABLE 375 PQCEE: COMPANY OVERVIEW
- TABLE 376 PQCEE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 377 PQCEE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 378 PQCEE: DEALS
- TABLE 379 DIGICERT: COMPANY OVERVIEW
- TABLE 380 DIGICERT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 381 DIGICERT: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 382 DIGICERT: DEALS
- TABLE 383 KLOCH: COMPANY OVERVIEW
- TABLE 384 KLOCH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 385 PATERO: COMPANY OVERVIEW
- TABLE 386 PATERO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 387 PATERO: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 388 PATERO: DEALS
- TABLE 389 POST-QUANTUM: COMPANY OVERVIEW
- TABLE 390 POST-QUANTUM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 391 PQSHIELD: COMPANY OVERVIEW
- TABLE 392 PQSHIELD: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 393 PQSHIELD: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 394 PQSHIELD: DEALS
- TABLE 395 ENTRUST: COMPANY OVERVIEW
- TABLE 396 ENTRUST: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 397 ENTRUST: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 398 IBM: COMPANY OVERVIEW
- TABLE 399 IBM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 400 IBM: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 401 IBM: DEALS
- TABLE 402 QNU LABS: COMPANY OVERVIEW
- TABLE 403 QNU LABS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 404 QNU LABS: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 405 QNU LABS: DEALS
- TABLE 406 UTIMACO: COMPANY OVERVIEW
- TABLE 407 UTIMACO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 408 UTIMACO: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 409 UTIMACO: DEALS
- TABLE 410 JISA SOFTECH: COMPANY OVERVIEW
- TABLE 411 JISA SOFTECH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 412 JISA SOFTECH: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 413 JISA SOFTECH: DEALS
- TABLE 414 JISA SOFTECH: EXPANSIONS
- TABLE 415 QUANTUM XCHANGE: COMPANY OVERVIEW
- TABLE 416 QUANTUM XCHANGE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 417 QUANTUM XCHANGE: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 418 QUANTUM XCHANGE: DEALS
- TABLE 419 FACTOR ANALYSIS
- TABLE 420 RESEARCH ASSUMPTIONS
List of Figures
- FIGURE 1 MARKET SEGMENTATION AND REGIONS COVERED
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 POST-QUANTUM CRYPTOGRAPHY MARKET, 2022-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN POST-QUANTUM CRYPTOGRAPHY MARKET, 2022-2026
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF POST-QUANTUM CRYPTOGRAPHY MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN POST-QUANTUM CRYPTOGRAPHY MARKET, 2026-2031
- FIGURE 7 EUROPE TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 8 NIST PQC STANDARDS, GOVERNMENT MIGRATION INITIATIVES, AND RISING CRYPTOGRAPHIC RISKS ACCELERATING MARKET GROWTH
- FIGURE 9 SOLUTIONS SEGMENT TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 10 QUANTUM-SAFE HARDWARE SEGMENT TO HOLD LARGEST MARKET SHARE DURING FORECAST PERIOD
- FIGURE 11 BFSI SEGMENT TO HOLD LARGEST SHARE DURING FORECAST PERIOD
- FIGURE 12 EUROPE TO EMERGE AS MOST SIGNIFICANT MARKET FOR NEXT FIVE YEARS
- FIGURE 13 POST-QUANTUM CRYPTOGRAPHY MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 POST-QUANTUM CRYPTOGRAPHY MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 POST-QUANTUM CRYPTOGRAPHY MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 POST-QUANTUM CRYPTOGRAPHY MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 AVERAGE SELLING PRICE OF KEY POST-QUANTUM CRYPTOGRAPHY VENDORS, BY SOLUTION, 2025 (USD)
- FIGURE 18 IMPORT DATA, BY KEY COUNTRY, 2020-2024 (USD MILLION)
- FIGURE 19 EXPORT DATA, BY KEY COUNTRY, 2020-2024 (USD MILLION)
- FIGURE 20 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 21 LEADING GLOBAL POST-QUANTUM CRYPTOGRAPHY VENDORS, BY TOTAL FUNDING VALUE AND NUMBER OF FUNDING ROUNDS
- FIGURE 22 PATENTS APPLIED AND GRANTED IN POST-QUANTUM CRYPTOGRAPHY MARKET, 2017-2026
- FIGURE 23 REGIONAL ANALYSIS OF PATENTS GRANTED IN POST-QUANTUM CRYPTOGRAPHY MARKET
- FIGURE 24 FUTURE APPLICATIONS: POST-QUANTUM CRYPTOGRAPHY MARKET
- FIGURE 25 POST-QUANTUM CRYPTOGRAPHY MARKET: DECISION-MAKING FACTORS
- FIGURE 26 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE VERTICALS
- FIGURE 27 KEY BUYING CRITERIA FOR TOP THREE VERTICALS
- FIGURE 28 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 29 SERVICES SEGMENT TO GROW AT HIGHER RATE DURING FORECAST PERIOD
- FIGURE 30 CRYPTOGRAPHIC DISCOVERY, RISK, & MIGRATION MANAGEMENT SOFTWARE SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 31 MIGRATION SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 32 SMES SEGMENT TO REGISTER HIGHER CAGR DURING FORECAST PERIOD
- FIGURE 33 IT & ITES SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 34 EUROPE TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 35 NORTH AMERICA: MARKET SNAPSHOT
- FIGURE 36 EUROPE: MARKET SNAPSHOT
- FIGURE 37 SEGMENTAL REVENUE ANALYSIS OF TOP FIVE MARKET PLAYERS, 2022-2025 (USD MILLION)
- FIGURE 38 POST-QUANTUM CRYPTOGRAPHY MARKET: SHARE OF LEADING COMPANIES, 2025
- FIGURE 39 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPARATIVE ANALYSIS OF VENDOR BRANDS
- FIGURE 40 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPANY EVALUATION MATRIX (ESTABLISHED PLAYERS), 2025
- FIGURE 41 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPANY FOOTPRINT
- FIGURE 42 POST-QUANTUM CRYPTOGRAPHY MARKET: COMPANY EVALUATION MATRIX, POST-QUANTUM CRYPTOGRAPHY SPECIALISTS/STARTUPS
- FIGURE 43 POST-QUANTUM CRYPTOGRAPHY MARKET: VALUATION OF KEY VENDORS (USD BILLION)
- FIGURE 44 POST-QUANTUM CRYPTOGRAPHY MARKET: FINANCIAL METRICS OF KEY VENDORS
- FIGURE 45 NXP SEMICONDUCTORS: COMPANY SNAPSHOT
- FIGURE 46 THALES: COMPANY SNAPSHOT
- FIGURE 47 AWS: COMPANY SNAPSHOT
- FIGURE 48 PALO ALTO NETWORKS: COMPANY SNAPSHOT
- FIGURE 49 ST ENGINEERING: COMPANY SNAPSHOT
- FIGURE 50 IBM: COMPANY SNAPSHOT
- FIGURE 51 POST-QUANTUM CRYPTOGRAPHY MARKET: RESEARCH DESIGN
- FIGURE 52 BREAKUP OF PRIMARY PROFILES, BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 53 KEY INSIGHTS FROM INDUSTRY
- FIGURE 54 DATA TRIANGULATION
- FIGURE 55 POST-QUANTUM CRYPTOGRAPHY MARKET: RESEARCH FLOW
- FIGURE 56 APPROACH 1 (SUPPLY-SIDE ANALYSIS): REVENUE OF SOLUTIONS/SERVICES IN PQC MARKET
- FIGURE 57 MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 1, SUPPLY-SIDE ANALYSIS
- FIGURE 58 APPROACH 2, BOTTOM-UP (SUPPLY SIDE): COLLECTIVE REVENUE FROM ALL OFFERINGS IN PQC MARKET
- FIGURE 59 APPROACH 2: BOTTOM-UP (DEMAND SIDE)
- FIGURE 60 RESEARCH LIMITATIONS


