

 |
市場調查報告書
商品編碼
2151257
遠端保健和遠端照護市場:按功能、應用、最終用戶和地區分類-全球預測至2031年Telehealth and Telemedicine Market by Function, Application, End User & Region - Global Forecast to 2031 |
||||||

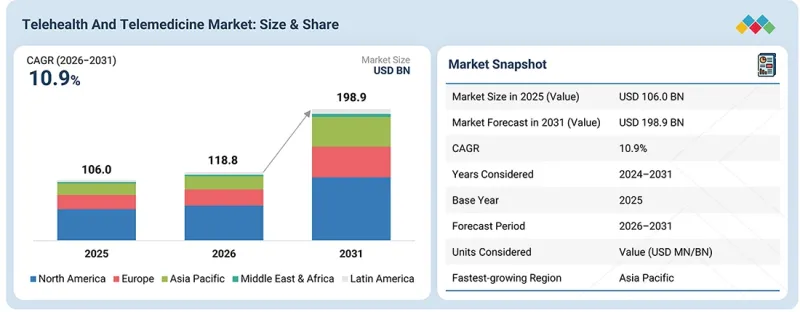
預計到 2031 年,遠端保健遠端照護市場規模將達到 1,989 億美元,而 2026 年為 1,188 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 10.9%。
該市場正經歷強勁成長,主要促進因素包括老年人口和醫療服務不足人群(尤其是在農村和偏遠地區)的增加、慢性病患病率的上升,以及在醫生和其他醫療專業人員長期短缺的情況下,人們對便捷醫療服務的需求日益成長。此外,通訊基礎設施的進步、智慧型手機和網際網路的廣泛普及、基於雲端的醫療平台以及遠端患者監護(RPM)系統的日益普及,也進一步推動了市場成長。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(10億美元) |
| 部分 | 組件、功能、應用程式、年齡層、最終用戶和地區 |
| 目標區域 | 北美、歐洲、亞太地區、拉丁美洲、中東和非洲 |
人工智慧醫療設備、數位健康平台和線上諮詢的日益融合,也提升了遠端醫療服務的擴充性和效率。醫療服務提供者、保險公司和科技公司正擴大採用遠端保健解決方案,以改善醫療服務的可近性,支持疾病的持續管理,減少不必要的就診,並實現更個人化的病人參與。然而,區域監管差異、醫療系統內部日益成長的詐欺和濫用問題、資料隱私和網路安全風險、互通性挑戰以及人們對新技術的心理抵觸,預計將在預測期內抑制市場成長。
在遠端保健遠端照護市場中,患者群體正成為成長最快的終端用戶。
從終端用戶來看,預計在預測期內,患者群體將實現最快成長,這主要得益於消費者對虛擬諮詢、遠端患者監護和數位化醫療服務的接受度不斷提高。人們對便利醫療服務的需求日益成長,尤其是在老年人、慢性疾病患者以及居住在農村或醫療服務不足地區的人群中,這促使更多患者直接使用遠端保健平台。智慧型手機、連線健診設備和方便用戶使用的數位醫療應用程式的日益普及,進一步加速了患者參與遠端醫療。此外,基層醫療、後續觀察、行為醫學和慢性病管理等領域對線上諮商的接受度不斷提高,預計將在2031年之前加速患者群體的成長。
按組件分類,預計到 2025 年,軟體部分將佔據遠端保健和遠端照護市場的最大佔有率。
從各組成部分來看,軟體領域預計將佔據最大的市場佔有率,並在預測期內實現最快成長。這一主導地位主要得益於遠距遠端保健平台、線上諮詢應用程式、遠端患者監護軟體、與電子健康記錄(EHR) 的整合以及數位化護理管理解決方案的日益普及。醫療服務提供者正擴大採用軟體平台來簡化虛擬諮詢、改善臨床工作流程、實現即時患者監護並加強患者與醫療服務提供者之間的溝通。此外,人工智慧、雲端運算、數據分析和互通性的進步也提升了遠端保健軟體解決方案的功能和擴充性。對整合化、方便用戶使用且安全的數位化醫療平台日益成長的需求預計將進一步推動軟體領域在 2031 年前的擴張。
預計亞太地區在預測期內將錄得最高的成長率。
從區域來看,亞太地區預計將在預測期內實現最快成長,這主要得益於龐大且快速老齡化的人口帶來的醫療保健需求不斷成長、慢性病患病率上升以及都市區醫療服務獲取方面的巨大差距。對數位醫療基礎設施的投資增加、網際網路和智慧型手機普及率的提高以及遠距醫療和遠距遠端患者監護的日益普及,都進一步推動了全部區域的市場擴張。此外,中國、印度、日本、韓國和澳洲等國政府為促進數位健康、發展遠距遠端醫療基礎設施以及加大對醫療技術的投資而採取的舉措,也為市場成長創造了有利環境。預計到2031年,該地區龐大的患者群體以及對價格合理且便捷的醫療保健服務日益成長的需求,將進一步加速遠端醫療和遠端保健解決方案的普及。
主要參會公司組成如下:
- 依公司類型分類:一級供應商(38%)、二級供應商(33%)、三級供應商(29%)
- 按職位:總監(35%)、經理(40%)、其他(25%)
- 按地區分類:北美(45%)、歐洲(30%)、亞太地區(20%)、拉丁美洲(3%)、中東和非洲(2%)
大公司
遠端保健遠端照護市場的主要參與者包括:荷蘭皇家飛利浦公司(Koninklijke Philips NV)、愛爾蘭美敦力公司(Medtronic)、美國通用電氣醫療集團(GE Healthcare)、美國Epic系統公司(Epic Systems Corporation)、美國甲骨文公司(Oracle)、美國Doximity Healthers、美國Teladoc Healthers)、美國甲骨文公司(Oracle)、美國Doximity Healthers、美國Teladoc Healthers)公司、美國西門醫療公司(西門醫療公司)、美國銀行醫療公司(Siadoc Health) Systems Inc.)、美國Included Health公司(旗下擁有Doctor on Demand公司)(Included Health, Inc. (Doctor on Demand, Inc.))、美國AMC 遠端保健公司(AMC Health)、美國併購公司、美國遠端照護公司(Walgreen Co.)( ...
調查範圍
本研究報告按組件、功能、應用、年齡層、最終用戶和地區對遠端保健遠端照護市場進行細分。報告詳細分析了影響遠端保健遠端照護市場成長的關鍵因素,包括促進因素、限制因素、挑戰和機會。透過對主要行業參與者的深入分析,報告揭示了他們的業務概況、提供的服務以及在遠端保健遠端醫療市場中的關鍵策略,例如收購、夥伴關係、合併、產品/服務推出和改進以及監管批准。此外,報告還對遠端保健遠端醫療市場生態系統中的新興新創公司進行了競爭考察。
購買本報告的理由
本報告將幫助現有企業、新參與企業和中小企業了解市場趨勢並擴大市場佔有率。購買本報告的企業可以透過運用以下一種或多種策略來鞏固其市場地位。
本報告深入分析了以下幾點:
- 對影響遠距醫療市場成長的關鍵遠端保健(遠端患者監護(RPM) 系統的擴展)、阻礙因素(高投資成本和缺乏 IT 專業知識)、機會(在遠端照護護理中更多地使用穿戴式裝置、應用程式和感測器)以及挑戰(資料安全問題)進行分析。
- 產品開發與創新:深入了解遠端保健和遠端照護市場的未來技術、研發活動以及新產品/服務的推出。
- 市場發展:提供盈利市場的全面資訊。本報告分析了各個地區的遠端保健和遠端照護市場。
- 市場多元化:提供有關遠端保健和遠端照護市場的新產品和服務、未開發的市場、近期趨勢和投資的全面資訊。
- 競爭分析:對遠端保健和遠端照護市場主要參與者的市場佔有率、成長策略和服務產品進行詳細評估,包括 Koninklijke Philips NV(荷蘭)、Medtronic(愛爾蘭)、GE Healthcare(美國)、Epic Systems Corporation(美國)、Oracle(美國)、Doximity, Inc.(美國)和 Teladoc Health, Inc.(美國)。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 遠端保健和遠端照護市場概覽
- 按最終用戶和地區分類的遠端保健和遠端照護市場
- 遠端保健和遠端照護市場:區域概覽
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級主要公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 新進入者的威脅
- 替代品的威脅
- 買方的議價能力
- 供應商的議價能力
- 競爭公司之間的競爭
- 總體經濟指標
- 價值鏈分析
- 生態系分析
- 定價分析
- 2026年遠端保健和遠端照護解決方案各組件參考價格
- 2026年各地區遠端保健遠端照護設備參考價格
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢和顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 費用和法規分析
- 價格數據分析
第6章:透過採用技術、專利、數位化和人工智慧實現策略轉型
- 產業趨勢
- 主要新興技術
- 視訊會議和即時通訊平台
- 人工智慧和機器學習
- 虛擬助理和聊天機器人
- 語音辨識與自然語言處理(NLP)
- 與電子健康記錄(EHR) 整合
- 遠端患者監護系統
- 互補技術
- 邊緣運算
- 雲端運算
- 行動醫療(行動醫療)應用程式
- 穿戴式裝置、感測器和物聯網
- 相關技術
- 數位療法
- 區塊鏈技術
- 擴增實境(AR)和虛擬實境(VR)
- 技術和產品藍圖
- 專利分析
- 遠端保健和遠端照護領域的專利公開趨勢
- 洞察:司法管轄區和主要申請人分析
- 未來應用
- 遠端患者監護和慢性病管理
- 人工智慧驅動的個人化醫療
- 虛擬醫院及居家醫院護理
- 人工智慧/通用人工智慧對遠端保健和遠端照護市場的影響
- 主要用例
- 主要案例研究
- 人工智慧/通用人工智慧對互聯生態系統和鄰近生態系統的影響
- 使用者接受度和影響評估
第7章 監理情勢
- 區域法規和合規性
- 監管機構、政府機構和其他組織
- 監管標準
- 法律規範
- 業界標準
第8章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 採購過程中的關鍵相關人員
- 主要採購標準
- 實施障礙和內部挑戰
- 未滿足的需求和最終用戶分析
- 未滿足的需求
- 最終用戶期望
- 市場盈利
第9章遠端保健與遠端照護市場:按年齡層別分類
- 兒童
- 成人
- 老年人
第10章:遠端保健與遠端照護市場:按應用分類
- 基層醫療
- 專業醫療護理
- 遠距ICU
- 虛擬坐診與護理
- 其他用途
第11章遠端保健與遠端照護市場:按組成部分分類
- 硬體
- 軟體
第12章遠端保健與遠端照護市場:按最終用戶分類
- 醫療保健提供者
- 醫療保健支付方
- 病人
- 製藥和生物技術公司
- 醫療設備公司
- 其他最終用戶
第13章:遠端保健與遠端照護市場:按功能分類
- 臨床護理管理
- 預防保健管理
- 診斷和治療
- 遠端患者監護/病患監測
- 復健與恢復
- 管理工作
- 分析/報告
- 患者參與
- 其他功能
第14章遠端保健與遠端照護市場:按地區分類
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 亞太其他地區
- 拉丁美洲
- 透過數位創新擴大獲取管道
- 巴西
- 墨西哥
- 其他拉丁美洲
- 中東和非洲
- 政府措施支持遠端保健和遠端照護解決方案的市場成長
- 海灣合作理事會國家
- 其他中東和非洲地區
第15章 競爭格局
- 概述
- 主要參與企業的策略/優勢
- 遠端保健和遠端照護市場主要參與者的策略概覽
- 收入分析(2021-2025)
- 市佔率分析(2025 年)
- 企業估值和財務指標
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 先進公司
- 應對力的公司
- 充滿活力的公司
- 起始點
- 競爭標竿分析:新創企業/中小企業,2025 年
- 品牌/軟體比較分析
- 競爭格局
- 產品上市及核准
- 交易
- 業務拓展
- 其他趨勢
第16章:公司簡介
- 大公司
- MEDTRONIC
- TELADOC HEALTH, INC.
- CISCO SYSTEMS, INC.
- DEALS
- KONINKLIJKE PHILIPS NV
- ZOOM COMMUNICATIONS, INC.
- GE HEALTHCARE
- EPIC SYSTEMS CORPORATION
- ORACLE
- DOXIMITY, INC.
- AMERICAN WELL
- SIEMENS HEALTHINEERS AG
- INCLUDED HEALTH, INC.(DOCTOR ON DEMAND, INC.)
- AMC HEALTH
- TELESPECIALISTS
- WALGREENS BOOTS ALLIANCE, INC.(WALGREEN CO.)
- CAREGILITY
- CVS HEALTH
- EVERNORTH HEALTH, INC.
- ELATION
- IRON BOW TECHNOLOGIES
- 其他主要公司
- TIMEDOC, INC.
- CEREBRAL INC.
- KINDBODY
- TRANSCARENT
- CARESIMPLE INC.
第17章調查方法
第18章附錄
The telehealth and telemedicine market is projected to reach USD 198.9 billion by 2031 from USD 118.8 billion in 2026, at a CAGR of 10.9% from 2026 to 2031. The market is witnessing strong expansion, primarily driven by the growing geriatric and medically underserved populations, particularly in rural and remote areas, the rising prevalence of chronic diseases, and the increasing need for accessible healthcare amid persistent shortages of physicians and other healthcare professionals. In addition, advancements in telecommunications infrastructure, wider smartphone and internet penetration, cloud-based healthcare platforms, and the expanding adoption of remote patient monitoring (RPM) systems are further supporting market growth.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Component, Function, Application, Age Group, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa |
The growing integration of AI-enabled medical devices, digital health platforms, and virtual consultations is also improving the scalability and efficiency of remote healthcare delivery. Healthcare providers, payers, and technology companies are increasingly adopting telehealth solutions to improve access to care, support continuous disease management, reduce unnecessary hospital visits, and enable more personalized patient engagement. However, regulatory variations across regions, growing concerns surrounding fraud and abuse within healthcare systems, data privacy and cybersecurity risks, interoperability challenges, and behavioral reluctance to adopt new technologies are expected to restrain market growth during the forecast period.
The patients segment is emerging as the fastest-growing end user in the telehealth and telemedicine market.
By end user, the patients segment is projected to register the fastest growth during the forecast period, supported by increasing consumer adoption of virtual consultations, remote patient monitoring, and digitally enabled healthcare services. Growing demand for convenient and accessible care, particularly among elderly individuals, patients with chronic conditions, and populations in rural or underserved areas, is encouraging more patients to directly engage with telehealth platforms. The increasing availability of smartphones, connected health devices, and user-friendly digital healthcare applications is further facilitating patient participation in remote care. In addition, the growing acceptance of virtual visits for primary care, follow-up consultations, behavioral health, and chronic disease management is expected to accelerate the expansion of the patients segment through 2031.
By component, the software segment accounted for the largest share of the telehealth and telemedicine market in 2025.
By component, the software segment is projected to account for the largest market share and register the fastest growth during the forecast period. The increasing adoption of telehealth platforms, virtual consultation applications, remote patient monitoring software, electronic health record integration, and digital care management solutions primarily drives this dominance. Healthcare providers are increasingly deploying software platforms to facilitate virtual consultations, streamline clinical workflows, enable real-time patient monitoring, and improve communication between patients and healthcare professionals. In addition, advancements in artificial intelligence, cloud computing, data analytics, and interoperability are enhancing the functionality and scalability of telehealth software solutions. The growing demand for integrated, user-friendly, and secure digital healthcare platforms is expected to further support the expansion of the software segment through 2031.
Asia Pacific is expected to register the highest growth during the forecast period.
By region, Asia Pacific (APAC) is projected to register the fastest growth during the forecast period, driven by the expanding healthcare needs of its large and rapidly aging population, rising prevalence of chronic diseases, and significant disparities in healthcare access across urban and rural areas. Increasing investments in digital healthcare infrastructure, improving internet and smartphone penetration, and the growing adoption of virtual consultations and remote patient monitoring are further supporting market expansion across the region. In addition, government initiatives promoting digital health, the development of telemedicine infrastructure, and increasing healthcare technology investments in countries such as China, India, Japan, South Korea, and Australia are creating favorable conditions for market growth. The region's large patient population and growing demand for affordable and accessible healthcare services are expected to further accelerate the adoption of telehealth and telemedicine solutions through 2031.
The breakdown of primary participants is as mentioned below:
- By Company Type: Tier 1 (38%), Tier 2 (33%), and Tier 3 (29%)
- By Designation: Directors (35%), Managers (40%), and Others (25%)
- By Region: North America (45%), Europe (30%), Asia Pacific (20%), Latin America (3%), and the Middle East & Africa (2%)
Key Players
The prominent players operating in the telehealth and telemedicine market include Koninklijke Philips N.V. (Netherlands), Medtronic (Ireland), GE Healthcare (US), Epic Systems Corporation (US), Oracle (US), Doximity, Inc. (US), Teladoc Health, Inc. (US), American Well (US), Siemens Healthineers AG (Germany), Cisco Systems Inc. (US), Included Health, Inc. (Doctor on Demand, Inc.) (US), AMC Health (US), TeleSpecialists (US), Walgreen Co. (US), and Caregility (US), among others. These companies have adopted strategies such as strategic partnerships, collaborations, product launches, platform enhancements, investments in AI, mergers and acquisitions, and geographic expansion to strengthen their market presence in the telehealth and telemedicine market.
Research Coverage
This research report categorizes the telehealth and telemedicine market by component {hardware [telehealth kits, carts, and stations; patient monitoring devices (cardiac monitoring devices, neurological monitoring devices, respiratory monitoring devices, blood glucose monitoring devices, fetal & neonatal monitoring devices, weight monitoring devices, multiparameter monitoring devices, pulse oximeter devices, and other monitoring devices)], software [modality (EHR-centric and non-EHR-centric), integration type (integrated software and standalone software), type (remote patient monitoring, virtual care platforms (real-time interaction, store & forward), video conferencing platforms, virtual sitting & nursing), deployment (on-premise model and cloud-based model), and services], function [clinical care management (including teleconsultation & follow-up), preventive care management, diagnostics & treatment, remote patient monitoring/patient monitoring, rehabilitation & recovery, administrative, analytics & reporting, patient engagement, other functions (clinical trials, education, training, and others)], application [primary care, specialty care (teleradiology, telecardiology, teleneurology, diabetes, respiratory disorders, hypertension, teledermatology, telestroke, telepsychiatry, and other specialty care applications), teleICU, virtual sitting & nursing, and other applications], age group (pediatrics, adults, and geriatrics), end user [healthcare providers (hospitals, ambulatory surgical centers, long-term care & assisted living facilities, home healthcare, and other healthcare providers), healthcare payers (public payers and private payers), patients, pharmaceutical & biotechnology companies, medtech companies, and other end users], and region. The report covers detailed information on major factors, such as drivers, restraints, challenges, and opportunities, influencing the growth of the telehealth & telemedicine market. A thorough analysis of key industry players provides insights into their business overview, offerings, and key strategies such as acquisitions, collaborations, partnerships, mergers, product/service launches & enhancements, and approvals in the telehealth and telemedicine market. This report covers a competitive analysis of upcoming startups in the telehealth and telemedicine market ecosystem.
Reasons to Buy the Report
This report will help established firms and new entrants/smaller firms gauge the pulse of the market, which can help them gain greater market share. Firms that purchase the report can use one or more of the following strategies to strengthen their market position.
This report provides insights on:
- Analysis of key drivers (expansion of remote patient monitoring (RPM) systems), restraints (high investment costs and lack of IT expertise), opportunities (growing use of wearables, apps, and sensors for virtual care), and challenges (data security concerns) influencing the growth of the telehealth and telemedicine market.
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the telehealth and telemedicine market.
- Market Development: Comprehensive information about lucrative markets; the report analyzes the telehealth and telemedicine market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the telehealth and telemedicine market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players such as Koninklijke Philips N.V. (Netherlands), Medtronic (Ireland), GE Healthcare (US), Epic Systems Corporation (US), Oracle (US), Doximity, Inc. (US), Teladoc Health, Inc. (US), etc., in the telehealth and telemedicine market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 TELEHEALTH
- 1.2.2 TELEMEDICINE
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 TELEHEALTH & TELEMEDICINE MARKET OVERVIEW
- 3.2 TELEHEALTH & TELEMEDICINE MARKET, BY END USER & REGION
- 3.3 TELEHEALTH & TELEMEDICINE MARKET: GEOGRAPHIC SNAPSHOT
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing geriatric population and increasing need for advanced healthcare infrastructure
- 4.2.1.2 Rising prevalence of chronic diseases
- 4.2.1.3 Demonstrated time and cost savings
- 4.2.1.4 Advancements in telecommunication technologies
- 4.2.1.5 Shortage of skilled healthcare professionals
- 4.2.1.6 Increased government support and favorable regulatory policies
- 4.2.1.7 Expansion of remote patient monitoring systems
- 4.2.2 RESTRAINTS
- 4.2.2.1 High investment costs for B2B models and lack of IT expertise
- 4.2.2.2 State-to-state and inter-country regulatory variations
- 4.2.2.3 Behavioral reluctance to adopt new technologies
- 4.2.2.4 Rise in fraud and abuse in healthcare systems
- 4.2.2.5 Adherence to patient privacy, confidentiality, medical ethics
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing use of wearables, applications, and sensors for virtual care
- 4.2.3.2 Emergence of AI and ML
- 4.2.3.3 Increasing shift toward outpatient care models
- 4.2.3.4 High utility of telemedicine against infectious communicable diseases and epidemics
- 4.2.3.5 Expansion of hospital-at-home (HaH) initiatives
- 4.2.3.6 Demand for electronic medical record-based telehealth services
- 4.2.3.7 Rising incidence of mental illnesses and growing focus on emotional well-being
- 4.2.4 CHALLENGES
- 4.2.4.1 Data security and confidentiality concerns
- 4.2.4.2 Limited data accessibility
- 4.2.4.3 Inability to maintain patient hygiene and cleanliness standards
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 INDICATIVE PRICE FOR TELEHEALTH & TELEMEDICINE SOLUTIONS, BY COMPONENT, 2026
- 5.5.2 INDICATIVE PRICING OF TELEHEALTH & TELEMEDICINE DEVICES, BY REGION, 2026
- 5.6 KEY CONFERENCES & EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER'S BUSINESS
- 5.8 INVESTMENT & FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.10 TARIFF AND REGULATORY ANALYSIS
- 5.10.1 TARIFF DATA ANALYSIS
- 5.10.1.1 Tariff data for HS code 9018
- 5.10.1.2 Tariff data for HS code 9021
- 5.10.1.3 Tariff data for HS code 9022
- 5.10.1 TARIFF DATA ANALYSIS
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
- 6.1 INDUSTRY TRENDS
- 6.2 KEY EMERGING TECHNOLOGIES
- 6.2.1 VIDEO CONFERENCING AND REAL-TIME COMMUNICATION PLATFORMS
- 6.2.2 AI AND ML
- 6.2.3 VIRTUAL ASSISTANTS AND CHATBOTS
- 6.2.4 VOICE RECOGNITION AND NATURAL LANGUAGE PROCESSING (NLP)
- 6.2.5 EHR INTEGRATION
- 6.2.6 REMOTE PATIENT MONITORING SYSTEMS
- 6.3 COMPLEMENTARY TECHNOLOGIES
- 6.3.1 EDGE COMPUTING
- 6.3.2 CLOUD COMPUTING
- 6.3.3 MOBILE HEALTH (MHEALTH) APPLICATIONS
- 6.3.4 WEARABLE DEVICES, SENSORS, AND IOT
- 6.4 ADJACENT TECHNOLOGIES
- 6.4.1 DIGITAL THERAPEUTICS
- 6.4.2 BLOCKCHAIN TECHNOLOGY
- 6.4.3 AUGMENTED REALITY AND VIRTUAL REALITY
- 6.5 TECHNOLOGY / PRODUCT ROADMAP
- 6.6 PATENT ANALYSIS
- 6.6.1 PATENT PUBLICATION TRENDS FOR TELEHEALTH & TELEMEDICINE
- 6.6.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.7 FUTURE APPLICATIONS
- 6.7.1 REMOTE PATIENT MONITORING AND CHRONIC DISEASE MANAGEMENT
- 6.7.2 AI-ENABLED PERSONALIZED HEALTHCARE
- 6.7.3 VIRTUAL HOSPITALS AND HOSPITAL-AT-HOME CARE
- 6.8 IMPACT OF AI/GEN AI IN TELEHEALTH & TELEMEDICINE MARKET
- 6.8.1 KEY USE CASES
- 6.8.2 MAJOR CASE STUDIES
- 6.8.3 IMPACT OF AI/GEN AI ON INTERCONNECTED AND ADJACENT ECOSYSTEMS
- 6.8.3.1 Healthcare IT and EHR systems
- 6.8.3.2 Pharmaceuticals & drug discovery
- 6.8.3.3 Mental health tech
- 6.8.3.4 Healthcare analytics and insights
- 6.8.4 USER READINESS & IMPACT ASSESSMENT
- 6.8.4.1 User readiness
- 6.8.4.1.1 User A: Hospitals
- 6.8.4.1.2 User B: Ambulatory surgery centers
- 6.8.4.2 Impact assessment
- 6.8.4.2.1 User A: Hospitals
- 6.8.4.2.2 USER B: Ambulatory surgery centers
- 6.8.4.1 User readiness
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY STANDARDS
- 7.1.3 REGULATORY FRAMEWORK
- 7.1.4 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS & BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 KEY BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS & END-USER ANALYSIS
- 8.5.1 UNMET NEEDS
- 8.5.2 END USER EXPECTATIONS
- 8.6 MARKET PROFITABILITY
9 TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP
- 9.1 INTRODUCTION
- 9.2 PEDIATRICS
- 9.2.1 EXPANDING ACCESS AND CARE THROUGH GROWTH OF PEDIATRIC TELEHEALTH ACROSS AGE GROUPS
- 9.3 ADULTS
- 9.3.1 SHIFT IN HEALTHCARE DELIVERY PREFERENCES DRIVES SEGMENT GROWTH
- 9.4 GERIATRICS
- 9.4.1 TRANSFORMING GERIATRIC CARE: RISE OF TELEHEALTH FOR ELDERLY PATIENTS
10 TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 PRIMARY CARE
- 10.2.1 ANALYZING THE TRANSFORMATION OF PRIMARY CARE THROUGH TELEHEALTH INNOVATIONS
- 10.3 SPECIALTY CARE
- 10.3.1 SPECIALTY TELEHEALTH EXPANDS ACCESS TO EXPERT MEDICAL CARE
- 10.3.2 TELERADIOLOGY
- 10.3.2.1 Teleradiology transforms healthcare with faster diagnoses and greater accessibility
- 10.3.3 TELECARDIOLOGY
- 10.3.3.1 Revolutionizing cardiac care with telecardiology to expand access and efficiency
- 10.3.4 TELENEUROLOGY
- 10.3.4.1 Use of AI and cloud-based monitoring drives market
- 10.3.5 DIABETES
- 10.3.5.1 Driving growth in diabetes specialty care through telemedicine
- 10.3.6 RESPIRATORY DISORDERS (COPD, ASTHMA, AND OTHERS)
- 10.3.6.1 Driving growth in respiratory disorder management through telemedicine
- 10.3.7 HYPERTENSION
- 10.3.7.1 Transforming hypertension management with telehealth technologies
- 10.3.8 TELEDERMATOLOGY
- 10.3.8.1 Rising prevalence of skin diseases and growing use of HD cameras for skin diagnosis to drive market
- 10.3.9 TELESTROKE
- 10.3.9.1 Rising incidence of stroke and increasing geriatric population to drive market
- 10.3.10 TELEPSYCHIATRY (MENTAL HEALTH)
- 10.3.10.1 Shortage of mental health practitioners and favorable reimbursement scenario to drive market
- 10.3.11 OTHERS
- 10.3.11.1 Expanding telehealth solutions across diverse specialties: from oncology to ophthalmology
- 10.4 TELEICU
- 10.4.1 INCREASING NUMBER OF PATIENTS IN EMERGENCY DEPARTMENTS AND STAFF SHORTAGE IN RURAL AREAS TO DRIVE MARKET
- 10.5 VIRTUAL SITTING & NURSING
- 10.5.1 DRIVING GROWTH IN VIRTUAL SITTING AND NURSING THROUGH TELEHEALTH & TELEMEDICINE
- 10.6 OTHER APPLICATIONS
- 10.6.1 EXPANDING TELEHEALTH GROWTH ACROSS DIVERSE APPLICATIONS: CLINICAL TRIALS, URGENT CARE, AND WELLNESS
11 TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT
- 11.1 INTRODUCTION
- 11.1.1 HARDWARE
- 11.1.1.1 Transforming telehealth and telemedicine with advanced hardware solutions
- 11.1.2 TELEHEALTH KITS, CARTS, AND STATIONS
- 11.1.2.1 Empowering remote care with telehealth kits, carts, and stations
- 11.1.3 PATIENT MONITORING DEVICES
- 11.1.3.1 Empowering telehealth with advanced patient monitoring solutions
- 11.1.3.2 Cardiac monitoring devices
- 11.1.3.2.1 Empowering remote cardiac care through advanced monitoring solutions
- 11.1.3.3 Neurological monitoring devices
- 11.1.3.3.1 Transforming neurocare with advanced telemedicine solutions
- 11.1.3.4 Respiratory monitoring devices
- 11.1.3.4.1 Transforming respiratory care with remote monitoring solutions
- 11.1.3.5 Blood glucose monitoring devices
- 11.1.3.5.1 Revolutionizing diabetes management through remote monitoring
- 11.1.3.6 Fetal & neonatal monitoring devices
- 11.1.3.6.1 Enhancing maternal and infant care with remote monitoring solutions
- 11.1.3.7 Weight monitoring devices
- 11.1.3.7.1 Supporting weight management through remote monitoring technologies
- 11.1.3.8 Multiparameter monitoring devices
- 11.1.3.8.1 Elevating remote care with multiparameter monitoring devices
- 11.1.3.9 Pulse oximeter devices
- 11.1.3.9.1 Improved patient outcomes and reduced costs drive market
- 11.1.3.10 Other monitoring devices
- 11.1.3.10.1 Expanding telehealth capabilities with diverse monitoring devices
- 11.1.1 HARDWARE
- 11.2 SOFTWARE
- 11.2.1 DRIVING TELEHEALTH INNOVATION THROUGH ADVANCED SOFTWARE SOLUTIONS
- 11.2.2 BY MODALITY
- 11.2.2.1 Leveraging EHR-centric and non-EHR-centric software modalities in telehealth
- 11.2.2.2 EHR Centric
- 11.2.2.2.1 Enhancing telehealth with EHR-centric software solutions
- 11.2.2.3 Non-HER Centric
- 11.2.2.3.1 Leveraging non-EHR centric software in telehealth and telemedicine
- 11.2.3 BY INTEGRATION TYPE
- 11.2.3.1 Maximizing telemedicine efficiency with integrated and standalone software solutions
- 11.2.3.2 Integrated Software
- 11.2.3.2.1 Advancements in technology to boost segment
- 11.2.3.3 Standalone software
- 11.2.3.3.1 Additional features that offer flexibility drive market
- 11.2.4 TYPE
- 11.2.4.1 Transforming telehealth with remote patient monitoring and virtual care platforms
- 11.2.4.2 Remote patient monitoring
- 11.2.4.2.1 Convenience of tracking patient vitals from different places to drive segment
- 11.2.4.3 Virtual care platform
- 11.2.4.3.1 Driving digital transformation in telemedicine through virtual care platforms
- 11.2.4.3.2 Real-time interaction
- 11.2.4.3.2.1 Synchronous nature and potential for better healthcare access to drive segment
- 11.2.4.3.3 Store and forward
- 11.2.4.3.3.1 Easy monitoring of vital signs for long-term chronic care without physical presence to drive segment
- 11.2.4.4 Video conferencing platforms
- 11.2.4.4.1 Revolutionizing Remote Care Delivery with Video Conferencing Platforms
- 11.2.4.5 Virtual sitting & nursing
- 11.2.4.5.1 Proactive patient monitoring to improve outcomes and reduce costs
- 11.2.5 BY DEPLOYMENT
- 11.2.5.1 Transforming telehealth with remote patient monitoring and virtual care platforms
- 11.2.5.2 On-premise model
- 11.2.5.2.1 Enhanced control of software and easy reuse of existing infrastructure to drive market
- 11.2.5.3 Cloud-based model
- 11.2.5.3.1 Cloud-based model segment to dominate market during forecast period
- 11.2.6 SERVICES
- 11.2.6.1 Key role in enhancing telehealth and telemedicine to boost segment
12 TELEHEALTH & TELEMEDICINE MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.2 HEALTHCARE PROVIDERS
- 12.2.1 HOSPITALS
- 12.2.1.1 Growing incidence of chronic diseases and rising demand for high-quality care to drive segment
- 12.2.2 AMBULATORY SURGICAL CENTERS, AMBULATORY CARE CENTERS, AND OTHER OUTPATIENT SETTINGS
- 12.2.2.1 Increasing preference for same-day surgeries and demand for cost-effective care to drive adoption of telehealth and telemedicine
- 12.2.3 LONG-TERM CARE AND ASSISTED LIVING FACILITIES
- 12.2.3.1 Increasing geriatric population and rising need for prolonged treatment for chronic diseases to drive segment
- 12.2.4 HOME HEALTHCARE
- 12.2.4.1 Rising aging population and growing focus on patient-centered care to propel home healthcare segment
- 12.2.5 OTHER HEALTHCARE PROVIDERS
- 12.2.5.1 Advancements in technology and increasing need for comprehensive care to drive adoption across specialized centers
- 12.2.1 HOSPITALS
- 12.3 HEALTHCARE PAYERS
- 12.3.1 PUBLIC PAYERS
- 12.3.1.1 Increasing investments by public payers to drive segment
- 12.3.2 PRIVATE PAYERS
- 12.3.2.1 Expansion of telehealth services to mental health and substance usage to drive segment
- 12.3.1 PUBLIC PAYERS
- 12.4 PATIENTS
- 12.4.1 RISING PREVALENCE OF CHRONIC DISEASES AND EMERGENCE OF ADVANCED WEARABLE MONITORS TO DRIVE MARKET
- 12.5 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 12.5.1 ADVANCEMENTS IN TELEMEDICINE PROVIDE PHARMACEUTICAL AND BIOTECH COMPANIES WITH NEW AVENUES FOR DRUG DEVELOPMENT AND MONITORING
- 12.6 MEDTECH COMPANIES
- 12.6.1 ADVANCING REMOTE CARE THROUGH INNOVATIVE TELEHEALTH SOLUTIONS DRIVES GROWTH FOR MEDTECH COMPANIES
- 12.7 OTHER END USERS
13 TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION
- 13.1 INTRODUCTION
- 13.2 CLINICAL CARE MANAGEMENT
- 13.2.1 OPTIMIZING TELEMEDICINE THROUGH EFFECTIVE CLINICAL CARE MANAGEMENT
- 13.3 PREVENTIVE CARE MANAGEMENT
- 13.3.1 OPTIMIZING TELEMEDICINE THROUGH EFFECTIVE CLINICAL CARE MANAGEMENT
- 13.4 DIAGNOSTICS & TREATMENT
- 13.4.1 OPTIMIZING TELEMEDICINE THROUGH EFFECTIVE CLINICAL CARE MANAGEMENT
- 13.5 REMOTE PATIENT MONITORING/PATIENT MONITORING
- 13.5.1 SEAMLESS PATIENT CARE THROUGH REMOTE MONITORING TECHNOLOGIES
- 13.6 REHABILITATION & RECOVERY
- 13.6.1 REDEFINING REMOTE RECOVERY WITH TELEREHABILITATION IN THE DIGITAL AGE
- 13.7 ADMINISTRATIVE
- 13.7.1 OPTIMIZING ADMINISTRATIVE SEGMENTS IN TELEHEALTH FOR ENHANCED WORKFLOW EFFICIENCY
- 13.8 ANALYTICS & REPORTING
- 13.8.1 SEAMLESS PATIENT CARE THROUGH REMOTE MONITORING TECHNOLOGIES
- 13.9 PATIENT ENGAGEMENT
- 13.9.1 EMPOWERING PATIENTS THROUGH ENGAGEMENT IN TELEHEALTH TRANSFORMATION
- 13.10 OTHER FUNCTIONS
- 13.10.1 EDUCATION & TRAINING PRACTICES TO LEAD TO TELEHEALTH GROWTH
14 TELEHEALTH & TELEMEDICINE MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Legislative extensions as a driving force in expanding telehealth and telemedicine access to drive market.
- 14.2.2 CANADA
- 14.2.2.1 Government investments and digital integration to fuel the market
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Key legislative reforms driving the digital transformation of healthcare in Germany
- 14.3.2 UK
- 14.3.2.1 Accelerating healthcare access and efficiency through digital transformation is driving the market
- 14.3.3 FRANCE
- 14.3.3.1 Strategic investments and policy reforms are driving the market
- 14.3.4 ITALY
- 14.3.4.1 Strategic government investments fuel growth in Italy's telehealth market.
- 14.3.5 SPAIN
- 14.3.5.1 Surging investment and increasing adoption of wearable technology is driving the market
- 14.3.6 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Advancing digital health infrastructure to drive market in China
- 14.4.2 JAPAN
- 14.4.2.1 Government reforms and technological advancements driving growth in Japan's telemedicine market.
- 14.4.3 INDIA
- 14.4.3.1 Government initiatives for digitalization is driving the market in India
- 14.4.4 AUSTRALIA
- 14.4.4.1 Government investment in rural aged care is driving the market in Australia
- 14.4.5 REST OF ASIA PACIFIC
- 14.4.1 CHINA
- 14.5 LATIN AMERICA
- 14.5.1 EXPANDING ACCESS THROUGH DIGITAL INNOVATION
- 14.5.2 BRAZIL
- 14.5.2.1 Bridging gaps with telemedicine
- 14.5.3 MEXICO
- 14.5.3.1 Mexico's digital healthcare expansion: telehealth & telemedicine advancements
- 14.5.4 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 GOVERNMENT INITIATIVES TO SUPPORT MARKET GROWTH FOR TELEHEALTH & TELEMEDICINE SOLUTION
- 14.6.2 GCC COUNTRIES
- 14.6.2.1 Shortage of healthcare workforce to support market growth
- 14.6.3 REST OF MIDDLE EAST & AFRICA
- 14.6.3.1 Improvement in healthcare infrastructure to support telemedicine and telehealth platforms
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN TELEHEALTH AND TELEMEDICINE MARKET
- 15.3 REVENUE ANALYSIS, 2021-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY VALUATION AND FINANCIAL METRICS
- 15.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.6.1 STARS
- 15.6.2 EMERGING LEADERS
- 15.6.3 PERVASIVE PLAYERS
- 15.6.4 PARTICIPANTS
- 15.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.6.5.1 Company footprint
- 15.6.5.2 Region footprint
- 15.6.5.3 Function footprint
- 15.6.5.4 Application footprint
- 15.6.5.5 Component footprint
- 15.6.5.6 End user footprint
- 15.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.7.1 PROGRESSIVE COMPANIES
- 15.7.2 RESPONSIVE COMPANIES
- 15.7.3 DYNAMIC COMPANIES
- 15.7.4 STARTING BLOCKS
- 15.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.7.5.1 Detailed list of key startups/SMEs
- 15.7.5.2 Competitive benchmarking of key startups/SMEs
- 15.8 BRAND/SOFTWARE COMPARATIVE ANALYSIS
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES & APPROVALS
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
- 15.9.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 MEDTRONIC
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Services/Solutions offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches and enhancements
- 16.1.1.3.2 Deals
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 TELADOC HEALTH, INC.
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Services/Solutions offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches and enhancements
- 16.1.2.3.2 Deals
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses & competitive threats
- 16.1.3 CISCO SYSTEMS, INC.
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Services/Solutions offered
- 16.1.4 DEALS
- 16.1.4.1 MnM view
- 16.1.4.1.1 Right to win
- 16.1.4.1.2 Strategic choices
- 16.1.4.1.3 Weaknesses & competitive threats
- 16.1.4.1 MnM view
- 16.1.5 KONINKLIJKE PHILIPS N.V.
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Services/Solutions offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Product launches & approvals
- 16.1.5.3.2 Deals
- 16.1.5.4 MnM view
- 16.1.5.4.1 Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses & competitive threats
- 16.1.6 ZOOM COMMUNICATIONS, INC.
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Services/Solutions offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.6.4 MnM view
- 16.1.6.4.1 Right to win
- 16.1.6.4.2 Strategic choices
- 16.1.6.4.3 Weaknesses & competitive threats
- 16.1.7 GE HEALTHCARE
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Services/Solutions offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Product launches
- 16.1.7.3.2 Deals
- 16.1.7.3.3 Other developments
- 16.1.8 EPIC SYSTEMS CORPORATION
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Services/Solutions offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Product launches and enhancements
- 16.1.8.3.2 Deals
- 16.1.9 ORACLE
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Services/Solutions offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Product launches
- 16.1.9.3.2 Deals
- 16.1.10 DOXIMITY, INC.
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Services/Solutions offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Product enhancements
- 16.1.10.3.2 Deals
- 16.1.10.3.3 Other developments
- 16.1.11 AMERICAN WELL
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Services/Solutions offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Product launches
- 16.1.11.3.2 Deals
- 16.1.11.3.3 Other developments
- 16.1.12 SIEMENS HEALTHINEERS AG
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Services/Solutions offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Product launches
- 16.1.12.3.2 Deals
- 16.1.13 INCLUDED HEALTH, INC. (DOCTOR ON DEMAND, INC.)
- 16.1.13.1 Business overview
- 16.1.13.2 Products/Services/Solutions offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 DEALS
- 16.1.13.3.2 Other developments
- 16.1.14 AMC HEALTH
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Services/Solutions offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Deals
- 16.1.15 TELESPECIALISTS
- 16.1.15.1 Business overview
- 16.1.15.2 Products/Services/Solutions offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Product launches
- 16.1.15.3.2 Other developments
- 16.1.16 WALGREENS BOOTS ALLIANCE, INC. (WALGREEN CO.)
- 16.1.16.1 Business overview
- 16.1.16.2 Products/Services/Solutions offered
- 16.1.16.3 Recent developments
- 16.1.16.3.1 Product launches
- 16.1.16.3.2 Deals
- 16.1.16.3.3 Expansions
- 16.1.16.3.4 Other developments
- 16.1.17 CAREGILITY
- 16.1.17.1 Business overview
- 16.1.17.2 Products/Services offered
- 16.1.17.3 Recent developments
- 16.1.17.3.1 Deals
- 16.1.18 CVS HEALTH
- 16.1.18.1 Business overview
- 16.1.18.2 Products/Services/Solutions offered
- 16.1.18.3 Recent developments
- 16.1.18.3.1 Product launches
- 16.1.18.3.2 Deals
- 16.1.19 EVERNORTH HEALTH, INC.
- 16.1.19.1 Products/Services/Solutions offered
- 16.1.19.2 Recent developments
- 16.1.19.2.1 Deals
- 16.1.20 ELATION
- 16.1.20.1 Business overview
- 16.1.20.2 Products/Services/Solutions offered
- 16.1.20.3 Recent developments
- 16.1.20.3.1 Deals
- 16.1.21 IRON BOW TECHNOLOGIES
- 16.1.21.1 Business overview
- 16.1.21.2 Products/Services/Solutions offered
- 16.1.1 MEDTRONIC
- 16.2 OTHER PLAYERS
- 16.2.1 TIMEDOC, INC.
- 16.2.2 CEREBRAL INC.
- 16.2.3 KINDBODY
- 16.2.4 TRANSCARENT
- 16.2.5 CARESIMPLE INC.
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Insights from primary experts
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.3 DATA TRIANGULATION
- 17.4 MARKET SHARE ESTIMATION
- 17.5 RESEARCH ASSUMPTIONS
- 17.6 LIMITATIONS
- 17.6.1 METHODOLOGY-RELATED LIMITATIONS
- 17.6.2 SCOPE-RELATED LIMITATIONS
- 17.7 RISK ASSESSMENT
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 CHRONIC DISEASES AND RELATED COST BURDEN IN US
- TABLE 2 RECENT DEVELOPMENTS FOR REMOTE PATIENT MONITORING SYSTEMS, JANUARY 2023-JANUARY 2026
- TABLE 3 US: STATE-WISE REGULATORY REQUIREMENTS FOR TELEHEALTH
- TABLE 4 TOP 30 HEALTHCARE DATA BREACHES IN US, 2011-2024
- TABLE 5 TELEHEALTH & TELEMEDICINE MARKET: PORTER'S FIVE FORCES
- TABLE 6 TELEHEALTH & TELEMEDICINE MARKET: ROLE IN ECOSYSTEM
- TABLE 7 COST RANGE INVOLVED IN TELEMEDICINE DEVICES (USD)
- TABLE 8 INDICATIVE PRICE FOR TELEHEALTH & TELEMEDICINE SOLUTIONS, BY COMPONENT, 2026
- TABLE 9 AVERAGE SELLING PRICE OF TELADOC CONSULTATIONS
- TABLE 10 INDICATIVE PRICING OF TELEHEALTH & TELEMEDICINE DEVICES, BY REGION, 2026
- TABLE 11 TELEHEALTH & TELEMEDICINE MARKET: KEY CONFERENCES & EVENTS, 2026-2027
- TABLE 12 CASE 1: TRANSFORMING PATIENT CARE AND OPERATIONAL EFFICIENCY WITH TEBRA'S INTEGRATED SOLUTIONS
- TABLE 13 CASE 2: USE OF TELEHEALTH TO REDUCE PREVENTABLE EMERGENCY ROOM TRANSFERS FROM SKILLED NURSING FACILITIES
- TABLE 14 CASE 3: CONE HEALTH TO REVOLUTIONIZE TELEICU AND TELEHEALTH FOR SEAMLESS TRANSITION TO CAREGILITY'S UNIVERSAL HEALTH ENGAGEMENT SOLUTIONS
- TABLE 15 AVERAGE TARIFF FOR HS CODE 9018, 2025
- TABLE 16 AVERAGE TARIFF FOR HS CODE 9021, 2025
- TABLE 17 AVERAGE TARIFF FOR HS CODE 9022, 2025
- TABLE 18 INDUSTRY TRENDS IN TELEHEALTH & TELEMEDICINE MARKET
- TABLE 19 OVERVIEW OF TELEHEALTH USE CASES
- TABLE 20 JURISDICTION ANALYSIS OF TOP APPLICANT COUNTRIES FOR TELEHEALTH & TELEHEALTH
- TABLE 21 TELEHEALTH AND TELEMEDICINE MARKET: LIST OF PATENTS/PATENT APPLICATIONS
- TABLE 22 AI TO REDEFINE TREATMENT EFFECTIVENESS AND SAFETY
- TABLE 23 AI-DRIVEN CHATBOTS AND TELEHEALTH TO ENHANCE MENTAL HEALTH AND CHRONIC DISEASE MANAGEMENT
- TABLE 24 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 26 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 27 TELEHEALTH & TELEMEDICINE MARKET: REGULATORY STANDARDS
- TABLE 28 REGULATORY REQUIREMENTS IN NORTH AMERICA
- TABLE 29 REGULATORY REQUIREMENTS IN EUROPE
- TABLE 30 REGULATORY REQUIREMENTS IN ASIA PACIFIC
- TABLE 31 REGULATORY REQUIREMENTS IN LATIN AMERICA
- TABLE 32 REGULATORY REQUIREMENTS IN MIDDLE EAST & AFRICA
- TABLE 33 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS, BY TYPE
- TABLE 34 KEY BUYING CRITERIA FOR TOP THREE COMPONENTS
- TABLE 35 UNMET NEEDS IN TELEHEALTH & TELEMEDICINE MARKET
- TABLE 36 END-USER EXPECTATIONS IN TELEHEALTH & TELEMEDICINE MARKET
- TABLE 37 TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 38 TELEHEALTH & TELEMEDICINE MARKET FOR PEDIATRICS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 39 TELEHEALTH & TELEMEDICINE MARKET FOR ADULTS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 40 TELEHEALTH & TELEMEDICINE MARKET FOR GERIATRICS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 41 TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 42 TELEHEALTH & TELEMEDICINE MARKET FOR PRIMARY CARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 43 TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 44 TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 45 TELEHEALTH & TELEMEDICINE MARKET FOR TELERADIOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 46 TELEHEALTH & TELEMEDICINE MARKET FOR TELECARDIOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 47 TELEHEALTH & TELEMEDICINE MARKET FOR TELENEUROLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 48 TELEHEALTH & TELEMEDICINE MARKET FOR DIABETES, BY REGION 2024-2031 (USD MILLION)
- TABLE 49 TELEHEALTH & TELEMEDICINE MARKET FOR RESPIRATORY DISORDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 50 TELEHEALTH & TELEMEDICINE MARKET FOR HYPERTENSION, BY REGION, 2024-2031 (USD MILLION)
- TABLE 51 TELEHEALTH & TELEMEDICINE MARKET FOR TELEDERMATOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 52 TELEHEALTH & TELEMEDICINE MARKET FOR TELESTROKE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 53 TELEHEALTH & TELEMEDICINE MARKET FOR TELEPSYCHIATRY (MENTAL HEALTH), BY REGION, 2024-2031 (USD MILLION)
- TABLE 54 TELEHEALTH & TELEMEDICINE MARKET FOR OTHERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 55 TELEHEALTH & TELEMEDICINE MARKET FOR TELEICU, BY REGION, 2024-2031 (USD MILLION)
- TABLE 56 TELEHEALTH & TELEMEDICINE MARKET FOR VIRTUAL SITTING & NURSING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 57 TELEHEALTH & TELEMEDICINE MARKET FOR OTHER APPLICATIONS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 58 TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 59 TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 60 TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 61 TELEHEALTH & TELEMEDICINE MARKET FOR TELEHEALTH KITS, CARTS, AND STATIONS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 62 TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 63 TELEHEALTH & TELEMEDICINE MARKET FOR CARDIAC MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 64 TELEHEALTH & TELEMEDICINE MARKET FOR NEUROLOGICAL MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 65 TELEHEALTH & TELEMEDICINE MARKET FOR RESPIRATORY MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 66 TELEHEALTH & TELEMEDICINE MARKET FOR BLOOD GLUCOSE MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 67 TELEHEALTH & TELEMEDICINE MARKET FOR FETAL & NEONATAL MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 68 TELEHEALTH & TELEMEDICINE MARKET FOR WEIGHT MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 69 TELEHEALTH & TELEMEDICINE MARKET FOR MULTIPARAMETER MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 70 TELEHEALTH & TELEMEDICINE MARKET FOR PULSE OXIMETER DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 71 TELEHEALTH & TELEMEDICINE MARKET FOR OTHER MONITORING DEVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 72 TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 73 TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 74 TELEHEALTH & TELEMEDICINE MARKET FOR EHR CENTRIC MODALITIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 75 TELEHEALTH & TELEMEDICINE MARKET FOR NON-EHR CENTRIC MODALITIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 76 TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 77 TELEHEALTH & TELEMEDICINE MARKET FOR INTEGRATED SOFTWARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 78 TELEHEALTH & TELEMEDICINE MARKET FOR STANDALONE SOFTWARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 79 TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 80 TELEHEALTH & TELEMEDICINE MARKET FOR REMOTE PATIENT MONITORING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 81 TELEHEALTH & TELEMEDICINE MARKET FOR VIRTUAL CARE PLATFORMS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 82 TELEHEALTH & TELEMEDICINE MARKET FOR VIDEO CONFERENCING PLATFORMS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 83 TELEHEALTH & TELEMEDICINE MARKET FOR VIRTUAL SITTING & NURSING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 84 TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 85 TELEHEALTH & TELEMEDICINE MARKET FOR ON-PREMISE MODEL, BY REGION, 2024-2031 (USD MILLION)
- TABLE 86 TELEHEALTH & TELEMEDICINE MARKET FOR CLOUD-BASED MODEL, BY REGION, 2024-2031 (USD MILLION)
- TABLE 87 TELEHEALTH & TELEMEDICINE MARKET FOR SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 88 TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 89 TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 90 TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 91 TELEHEALTH & TELEMEDICINE MARKET FOR HOSPITALS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 92 TELEHEALTH & TELEMEDICINE MARKET FOR AMBULATORY SURGICAL CENTERS, AMBULATORY CARE CENTERS, AND OTHER OUTPATIENT SETTINGS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 93 TELEHEALTH & TELEMEDICINE MARKET FOR LONG-TERM CARE AND ASSISTED LIVING FACILITIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 94 TELEHEALTH & TELEMEDICINE MARKET FOR HOME HEALTHCARE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 95 TELEHEALTH & TELEMEDICINE MARKET FOR OTHER HEALTHCARE PROVIDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 96 TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 97 TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 98 TELEHEALTH & TELEMEDICINE MARKET FOR PUBLIC PAYERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 99 TELEHEALTH & TELEMEDICINE MARKET FOR PRIVATE PAYERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 100 TELEHEALTH & TELEMEDICINE MARKET FOR PATIENTS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 101 TELEHEALTH & TELEMEDICINE MARKET FOR PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 102 TELEHEALTH & TELEMEDICINE MARKET FOR MEDTECH COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 103 TELEHEALTH & TELEMEDICINE MARKET FOR OTHER END USERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 104 TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 105 TELEHEALTH & TELEMEDICINE MARKET FOR CLINICAL CARE MANAGEMENT, BY REGION, 2024-2031 (USD MILLION)
- TABLE 106 TELEHEALTH & TELEMEDICINE MARKET FOR PREVENTIVE CARE MANAGEMENT, BY REGION, 2024-2031 (USD MILLION)
- TABLE 107 TELEHEALTH & TELEMEDICINE MARKET FOR DIAGNOSTICS & TREATMENT, BY REGION, 2024-2031 (USD MILLION)
- TABLE 108 TELEHEALTH & TELEMEDICINE MARKET FOR REMOTE PATIENT MONITORING/PATIENT MONITORING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 109 TELEHEALTH & TELEMEDICINE MARKET FOR REHABILITATION & RECOVERY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 110 TELEHEALTH & TELEMEDICINE MARKET FOR ADMINISTRATIVE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 111 TELEHEALTH & TELEMEDICINE MARKET FOR ANALYTICS & REPORTING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 112 TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT ENGAGEMENT, BY REGION, 2024-2031 (USD MILLION)
- TABLE 113 TELEHEALTH & TELEMEDICINE MARKET FOR OTHER FUNCTIONS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 114 TELEHEALTH & TELEMEDICINE MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 115 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 116 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 117 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 118 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 119 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 120 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 121 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 122 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 123 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 124 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 125 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 126 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 127 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 128 US: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 129 US: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 130 US: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 131 US: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 132 US: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 133 US: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 134 US: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 135 US: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 136 US: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 137 US: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 138 US: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 139 US: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 140 US: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 141 US: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 142 CANADA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 143 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 144 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 145 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 146 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 147 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 148 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 149 CANADA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 150 CANADA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 151 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 152 CANADA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 153 CANADA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 154 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 155 CANADA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 156 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 157 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 158 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 159 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 160 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 161 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 162 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 163 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 164 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 165 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 166 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 167 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 168 EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 169 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 170 EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 171 GERMANY: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 172 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 173 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 174 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 175 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 176 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 177 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 178 GERMANY: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 179 GERMANY: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 180 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 181 GERMANY: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 182 GERMANY: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 183 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 184 GERMANY: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 185 UK: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 186 UK: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 187 UK: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 188 UK: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 189 UK: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 190 UK: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 191 UK: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 192 UK: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 193 UK: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 194 UK: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 195 UK: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 196 UK: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 197 UK: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 198 UK: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 199 FRANCE: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 200 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 201 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 202 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 203 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 204 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 205 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 206 FRANCE: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 207 FRANCE: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 208 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 209 FRANCE: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 210 FRANCE: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 211 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 212 FRANCE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 213 ITALY: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 214 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 215 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 216 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 217 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 218 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 219 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 220 ITALY: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 221 ITALY: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 222 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 223 ITALY: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 224 ITALY: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 225 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 226 ITALY: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 227 SPAIN: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 228 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 229 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 230 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 231 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 232 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 233 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 234 SPAIN: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 235 SPAIN: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 236 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 237 SPAIN: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 238 SPAIN: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 239 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 240 SPAIN: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 241 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 242 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 243 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 244 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 245 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 246 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 247 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 248 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 249 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 250 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 251 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 252 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 253 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 254 REST OF EUROPE: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 255 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 256 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 257 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 258 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 259 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 260 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 261 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 262 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 263 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 264 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 265 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 266 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 267 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 268 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 269 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 270 CHINA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 271 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 272 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 273 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 274 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 275 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 276 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 277 CHINA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 278 CHINA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 279 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 280 CHINA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 281 CHINA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 282 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 283 CHINA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 284 JAPAN: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 285 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 286 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 287 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 288 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 289 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 290 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 291 JAPAN: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 292 JAPAN: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 293 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 294 JAPAN: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 295 JAPAN: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 296 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 297 JAPAN: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 298 INDIA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 299 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 300 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 301 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 302 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 303 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 304 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 305 INDIA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 306 INDIA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 307 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 308 INDIA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 309 INDIA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 310 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 311 INDIA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 312 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 313 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 314 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 315 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 316 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 317 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 318 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 319 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 320 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 321 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 322 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 323 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 324 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 325 AUSTRALIA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 326 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 327 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 328 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 329 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 330 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 331 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 332 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 333 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 334 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 335 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 336 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 337 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 338 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 339 REST OF ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 340 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 341 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 342 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 343 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 344 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 345 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 346 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 347 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 348 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 349 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 350 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 351 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 352 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 353 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 354 LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 355 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 356 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 357 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 358 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 359 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 360 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 361 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 362 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 363 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 364 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 365 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 366 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 367 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 368 BRAZIL: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 369 MEXICO: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 370 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 371 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 372 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 373 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 374 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 375 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 376 MEXICO: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 377 MEXICO: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 378 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 379 MEXICO: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 380 MEXICO: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 381 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 382 MEXICO: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 383 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 384 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 385 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 386 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 387 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 388 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 389 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 390 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 391 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 392 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 393 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 394 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 395 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 396 REST OF LATIN AMERICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 397 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 398 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 399 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 400 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 401 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 402 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 403 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 404 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 405 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 406 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 407 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 408 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 409 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 410 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 411 MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 412 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 413 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 414 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 415 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 416 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 417 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 418 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 419 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 420 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 421 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 422 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 423 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 424 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 425 GCC COUNTRIES: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 426 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY COMPONENT, 2024-2031 (USD MILLION)
- TABLE 427 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HARDWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 428 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR PATIENT MONITORING DEVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 429 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 430 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY INTEGRATION TYPE, 2024-2031 (USD MILLION)
- TABLE 431 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 432 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SOFTWARE, BY DEPLOYMENT MODEL, 2024-2031 (USD MILLION)
- TABLE 433 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY FUNCTION, 2024-2031 (USD MILLION)
- TABLE 434 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 435 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR SPECIALTY CARE, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 436 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY AGE GROUP, 2024-2031 (USD MILLION)
- TABLE 437 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 438 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PROVIDERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 439 REST OF MIDDLE EAST & AFRICA: TELEHEALTH & TELEMEDICINE MARKET FOR HEALTHCARE PAYERS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 440 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN TELEHEALTH AND TELEMEDICINE MARKET, JANUARY 2023-JULY 2026
- TABLE 441 TELEHEALTH & TELEMEDICINE MARKET: DEGREE OF COMPETITION
- TABLE 442 TELEHEALTH & TELEMEDICINE MARKET: REGION FOOTPRINT
- TABLE 443 TELEHEALTH & TELEMEDICINE MARKET: FUNCTION FOOTPRINT
- TABLE 444 TELEHEALTH & TELEMEDICINE MARKET: APPLICATION FOOTPRINT
- TABLE 445 TELEHEALTH & TELEMEDICINE MARKET: COMPONENT FOOTPRINT
- TABLE 446 TELEHEALTH & TELEMEDICINE MARKET: END USER FOOTPRINT
- TABLE 447 TELEHEALTH & TELEMEDICINE MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 448 TELEHEALTH & TELEMEDICINE MARKET: COMPETITIVE BENCHMARKING OF KEY EMERGING PLAYERS/STARTUPS
- TABLE 449 TELEHEALTH & TELEMEDICINE MARKET: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 450 TELEHEALTH & TELEMEDICINE MARKET: DEALS, JANUARY 2023-JULY 2026
- TABLE 451 TELEHEALTH & TELEMEDICINE MARKET: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 452 TELEHEALTH & TELEMEDICINE MARKET: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 453 MEDTRONIC: COMPANY OVERVIEW
- TABLE 454 MEDTRONIC: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 455 MEDTRONIC: PRODUCT LAUNCHES AND ENHANCEMENTS, JANUARY 2023-JULY 2026
- TABLE 456 MEDTRONIC: DEALS, JANUARY 2023-JULY 2026
- TABLE 457 TELADOC HEALTH, INC.: COMPANY OVERVIEW
- TABLE 458 TELADOC HEALTH, INC: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 459 TELADOC HEALTH, INC.: PRODUCT LAUNCHES AND ENHANCEMENTS, JANUARY 2023-JULY 2026
- TABLE 460 TELADOC HEALTH, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 461 CISCO SYSTEMS, INC.: COMPANY OVERVIEW
- TABLE 462 CISCO SYSTEMS, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 463 CISCO SYSTEMS, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 464 KONINKLIJKE PHILIPS N.V.: COMPANY OVERVIEW
- TABLE 465 KONINKLIJKE PHILIPS N.V.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 466 KONINKLIJKE PHILIPS N.V.: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 467 KONINKLIJKE PHILIPS N.V.: DEALS, JANUARY 2023-JULY 2026
- TABLE 468 ZOOM COMMUNICATIONS, INC.: COMPANY OVERVIEW
- TABLE 469 ZOOM COMMUNICATIONS, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 470 ZOOM COMMUNICATIONS, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 471 GE HEALTHCARE: COMPANY OVERVIEW
- TABLE 472 GE HEALTHCARE: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 473 GE HEALTHCARE: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 474 GE HEALTHCARE: DEALS, JANUARY 2023-JULY 2026
- TABLE 475 GE HEALTHCARE: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 476 EPIC SYSTEMS CORPORATION: COMPANY OVERVIEW
- TABLE 477 EPIC SYSTEMS CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 478 EPIC SYSTEMS CORPORATION: PRODUCT LAUNCHES AND ENHANCEMENTS, JANUARY 2023-JULY 2026
- TABLE 479 EPIC SYSTEMS CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 480 ORACLE: COMPANY OVERVIEW
- TABLE 481 ORACLE: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 482 ORACLE: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 483 ORACLE: DEALS, JANUARY 2023-JULY 2026
- TABLE 484 DOXIMITY, INC.: COMPANY OVERVIEW
- TABLE 485 DOXIMITY, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 486 DOXIMITY, INC.: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 487 DOXIMITY, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 488 DOXIMITY, INC.: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 489 AMERICAN WELL: COMPANY OVERVIEW
- TABLE 490 AMERICAN WELL: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 491 AMERICAN WELL: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 492 AMERICAN WELL: DEALS, JANUARY 2023-JULY 2026
- TABLE 493 AMERICAN WELL: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 494 SIEMENS HEALTHINEERS AG: COMPANY OVERVIEW
- TABLE 495 SIEMENS HEALTHINEERS AG: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 496 SIEMENS HEALTHINEERS AG: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 497 SIEMENS HEALTHINEERS AG: DEALS, JANUARY 2023-JULY 2026
- TABLE 498 INCLUDED HEALTH, INC.: COMPANY OVERVIEW
- TABLE 499 INCLUDED HEALTH, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 500 INCLUDED HEALTH, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 501 INCLUDED HEALTH, INC.: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 502 AMC HEALTH: COMPANY OVERVIEW
- TABLE 503 AMC HEALTH: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 504 AMC HEALTH.: DEALS, JANUARY 2023-JULY 2026
- TABLE 505 TELESPECIALISTS: COMPANY OVERVIEW
- TABLE 506 TELESPECIALISTS: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 507 TELESPECIALISTS: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 508 TELESPECIALISTS: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 509 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): COMPANY OVERVIEW
- TABLE 510 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): PRODUCTS/SERVICES/ SOLUTIONS OFFERED
- TABLE 511 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 512 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): DEALS, JANUARY 2023-JULY 2026
- TABLE 513 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 514 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 515 CAREGILITY: COMPANY OVERVIEW
- TABLE 516 CAREGILITY: PRODUCTS/SERVICES OFFERED
- TABLE 517 CAREGILITY: DEALS, JANUARY 2023-JULY 2026
- TABLE 518 CVS HEALTH: COMPANY OVERVIEW
- TABLE 519 CVS HEALTH: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 520 CVS HEALTH: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 521 CVS HEALTH: DEALS, JANUARY 2023-JULY 2026
- TABLE 522 EVERNORTH HEALTH, INC.: COMPANY OVERVIEW
- TABLE 523 EVERNORTH HEALTH, INC.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 524 EVERNORTH HEALTH, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 525 ELATION: COMPANY OVERVIEW
- TABLE 526 ELATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 527 ELATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 528 IRON BOW TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 529 IRON BOW TECHNOLOGIES: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 530 TIMEDOC, INC.: COMPANY OVERVIEW
- TABLE 531 CEREBRAL INC.: COMPANY OVERVIEW
- TABLE 532 KINDBODY: COMPANY OVERVIEW
- TABLE 533 TRANSACARENT: COMPANY OVERVIEW
- TABLE 534 CARESIMPLE INC.: COMPANY OVERVIEW
List of Figures
- FIGURE 1 TELEHEALTH & TELEMEDICINE MARKET SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 GLOBAL TELEHEALTH AND TELEMEDICINE MARKET, 2024-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN TELEHEALTH AND TELEMEDICINE MARKET, 2024-2026
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF TELEHEALTH AND TELEMEDICINE MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN TELEHEALTH AND TELEMEDICINE MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN TELEHEALTH AND TELEMEDICINE MARKET DURING FORECAST PERIOD
- FIGURE 8 NEED TO IMPROVE ACCESSIBILITY AND REDUCE HEALTHCARE EXPENSES TO DRIVE GROWTH IN TELEHEALTH & TELEMEDICINE MARKET
- FIGURE 9 HEALTHCARE PROVIDERS IN NORTH AMERICA ACCOUNTED FOR LARGEST MARKET SHARE IN 2025
- FIGURE 10 CHINA TO REGISTER HIGHEST GROWTH RATE DURING FORECAST PERIOD
- FIGURE 11 TELEHEALTH & TELEMEDICINE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 US: MEDICARE-CERTIFIED AMBULATORY SURGERY CENTERS, BY STATE (SEPTEMBER 2024)
- FIGURE 13 HEALTHCARE SECURITY BREACHES OF 500+ RECORDS IN US, 2009-2024
- FIGURE 14 US: MEDIAN HEALTHCARE DATA BREACH SIZE, 2009-2024
- FIGURE 15 INDIVIDUALS AFFECTED BY HEALTHCARE SECURITY BREACHES IN US, 2009-2023
- FIGURE 16 TELEHEALTH & TELEMEDICINE MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 17 TELEHEALTH & TELEMEDICINE MARKET: VALUE CHAIN ANALYSIS
- FIGURE 18 TELEHEALTH & TELEMEDICINE MARKET: ECOSYSTEM ANALYSIS
- FIGURE 19 TELEHEALTH & TELEMEDICINE MARKET: TRENDS/DISRUPTIONS IMPACTING CUSTOMER'S BUSINESS
- FIGURE 20 FUNDING AND DEALS IN TELEHEALTH & TELEMEDICINE MARKET
- FIGURE 21 GLOBAL PATENT PUBLICATION TRENDS IN TELEHEALTH & TELEMEDICINE, 2015-2026
- FIGURE 22 TOP APPLICANTS/OWNERS (COMPANIES/INSTITUTIONS) FOR TELEHEALTH & TELEMEDICINE (JANUARY 2015-SEPTEMBER 2026)
- FIGURE 23 POTENTIAL OF AI/GEN AI IN TELEHEALTH & TELEMEDICINE MARKET
- FIGURE 24 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS
- FIGURE 25 KEY BUYING CRITERIA FOR TOP THREE COMPONENTS
- FIGURE 26 NORTH AMERICA: TELEHEALTH & TELEMEDICINE MARKET SNAPSHOT
- FIGURE 27 ASIA PACIFIC: TELEHEALTH & TELEMEDICINE MARKET SNAPSHOT
- FIGURE 28 TELEHEALTH AND TELEMEDICINE MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021-2025 (USD MILLION)
- FIGURE 29 MARKET SHARE ANALYSIS OF KEY PLAYERS IN TELEHEALTH AND TELEMEDICINE MARKET, 2025
- FIGURE 30 EV/EBITDA OF KEY VENDORS
- FIGURE 31 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 32 TELEHEALTH & TELEMEDICINE MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 33 TELEHEALTH & TELEMEDICINE MARKET: COMPANY FOOTPRINT
- FIGURE 34 TELEHEALTH & TELEMEDICINE MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 35 TELEHEALTH & TELEMEDICINE MARKET: BRAND/SOFTWARE COMPARATIVE ANALYSIS
- FIGURE 36 MEDTRONIC: COMPANY SNAPSHOT
- FIGURE 37 TELADOC HEALTH, INC.: COMPANY SNAPSHOT
- FIGURE 38 CISCO SYSTEMS, INC.: COMPANY SNAPSHOT
- FIGURE 39 KONINKLIJKE PHILIPS N.V.: COMPANY SNAPSHOT
- FIGURE 40 ZOOM COMMUNICATIONS, INC.: COMPANY SNAPSHOT
- FIGURE 41 GE HEALTHCARE: COMPANY SNAPSHOT
- FIGURE 42 ORACLE: COMPANY SNAPSHOT
- FIGURE 43 DOXIMITY, INC.: COMPANY SNAPSHOT
- FIGURE 44 AMERICAN WELL: COMPANY SNAPSHOT
- FIGURE 45 SIEMENS HEALTHINEERS AG: COMPANY SNAPSHOT
- FIGURE 46 WALGREENS BOOTS ALLIANCE (WALGREEN CO.): COMPANY SNAPSHOT
- FIGURE 47 CVS HEALTH: COMPANY SNAPSHOT
- FIGURE 48 EVERNORTH HEALTH, INC.: COMPANY SNAPSHOT
- FIGURE 49 RESEARCH DESIGN
- FIGURE 50 PRIMARY SOURCES
- FIGURE 51 BREAKDOWN OF PRIMARY INTERVIEWS (DEMAND SIDE): BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 52 MARKET SIZE ESTIMATION: REVENUE SHARE ANALYSIS
- FIGURE 53 TOP-DOWN APPROACH
- FIGURE 54 CAGR PROJECTIONS, 2026-2031
- FIGURE 55 CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS
- FIGURE 56 DATA TRIANGULATION

 心理健康諮詢市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測。
 遠距精神病學和線上行為醫療保健服務市場預測至 2034 年——按服務交付模式、治療領域、技術整合、經營模式、最終用戶和地區進行全球分析。
 創新遠距遠端醫療服務市場分析與至2035年的預測:類型、產品類型、服務、技術、組件、應用、設備、部署模式、最終用戶、解決方案遠端醫療解決方案市場(專科醫生):市場分析及至 2035 年的預測-類型、產品類型、服務、技術、組件、應用、部署模式、最終用戶、解決方案
 遠端醫療市場— 2026-2032年全球市場預測遠端醫療市場:2026-2032年全球市場預測(按組件、存取方式、服務類型、應用程式和最終用戶分類)
 2026年全球寵物遠距分診服務市場報告
 遠端醫療市場:市場規模、佔有率和趨勢分析(按產品類型、交付方式、疾病領域、最終用途和地區分類),細分市場預測(2026-2033 年)
 遠端保健服務市場規模、佔有率和成長分析:按服務類型、交付方式、部署模式、通訊方式、應用、最終用戶、患者類型和地區分類-2026-2033年產業預測心理健康遠端醫療市場預測—按類型、服務、交付方式、最終用戶和地區分類的全球分析—2034年