


 |
市場調查報告書
商品編碼
2144545
醫用聚合物市場:按類型、應用、製造技術和地區分類-全球預測至2031年Medical Polymer Market by Type (Medical Plastics, Medical Elastomers), Application (Medical Disposables, Medical Instruments and Devices, Prosthetics, Diagnostics Instruments and Tools), Manufacturing Technology, and Region - Global Forecast to 2031 |
||||||

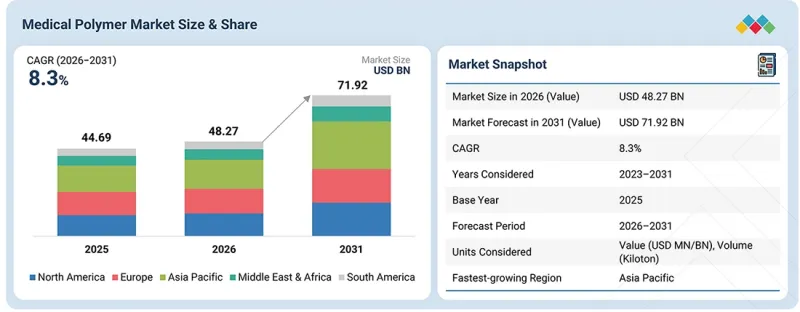
預計醫用聚合物市場將從 2026 年的 482.7 億美元成長到 2031 年的 719.2 億美元,預測期內複合年成長率為 8.3%。
受醫療領域進步、材料科學發展以及以患者為中心的創新理念的推動,醫用聚合物市場正經歷快速成長。慢性病日益普遍、人口老化以及對微創手術需求的不斷成長,促使人們更加青睞兼具柔軟性、安全性和精確性的先進聚合物。
| 調查範圍 | |
|---|---|
| 調查期 | 2023-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(百萬美元) 數量(千噸) |
| 部分 | 類型、應用、製造技術和地區 |
| 目標區域 | 北美洲、歐洲、亞太地區、南美洲、中東和非洲 |
一次性醫療產品在衛生管理和減少污染方面的廣泛應用,促進了聚合物組成的快速發展。聚合物科學正朝著開發具有卓越機械強度、耐久性、抗菌性能以及與主動滅菌技術相兼容的聚合物和材料的方向不斷邁進。知識和技術的進步在形狀保持性和生物可吸收性聚合物方面取得了突破性成果,為藥物傳輸裝置和組織工程領域開闢了新的可能性。醫療3D列印技術的普及徹底改變了這一領域,使得客製化植入和器械的快速開發成為可能。人們對永續發展的日益關注,也帶動了對可回收和可生物分解聚合物的興趣。
“在預測期內,醫用彈性體細分市場預計將佔據醫用聚合物市場第二大佔有率。”
醫用彈性體憑藉其柔軟性、耐用性和生物相容性,佔據醫用聚合物市場第二大佔有率,並廣泛應用於關鍵醫療領域的數百種精密應用。許多彈性體的特殊應用涉及需要持續運動、膨脹和收縮的產品,例如流體封裝、密封件、墊圈、導管、注射器、活塞和導管組件。醫用彈性體產品以其耐化學性、耐溫性和耐滅菌性而著稱,即使在高應力醫療應用中也能確保可靠的性能。矽橡膠、熱可塑性橡膠(TPE) 和橡膠材料因其優於傳統剛性聚合物的舒適性而經常被文獻提及,是穿戴式醫療設備和皮膚接觸應用的首選材料。此外,小型化趨勢以及影響藥物輸送系統、自動化閉迴路測試系統和生活方式診斷設備的先進設計概念,都在不斷推動彈性體材料的改進。此外,彈性體材料的彈性模量和拉伸強度較低,特別適合自動化製造和成型,從而能夠在大規模中實現經濟高效的產品生產。
“在預測期內,一次性醫療產品在醫用聚合物市場中佔據第二大應用領域。”
醫用一次性用品是醫用聚合物市場第二大應用領域。注射器、手套、輸液袋、導管和接頭、外科用覆蓋巾和口罩等產品均為一次性使用,旨在防止交叉感染並維持無菌環境。對感染預防的日益重視以及相關感染控制法規的訂定,推動了對醫用一次性用品的需求。由於其優異的加工性能、低成本以及與滅菌製程的兼容性,醫用一次性用品中使用的聚合物主要為聚丙烯、聚乙烯和聚氯乙烯(PVC)。住院時間的延長、外科技術的進步以及門診服務的擴展(尤其是在發展中地區),推動了對高品質一次性用品的需求。即用型無菌產品的便利性有助於提高繁忙醫療機構的效率。隨著醫療機構不斷關注安全性、成本效益和效率,基於聚合物的醫用一次性用品有望在未來成為一個重要的成長領域。
“在預測期內,射出成型將成為醫用聚合物市場第二大製造技術。”
射出成型是醫用聚合物領域第二大製造技術,因為它能夠在保持卓越可靠性和效率的同時,大規模生產高精度、複雜形狀的零件。射出成型廣泛應用於各種醫療產品的製造,包括診斷設備機殼、手術器械手柄、注射器、連接器和植入式醫療設備組件。射出成型相容於多種醫用級聚合物,例如聚碳酸酯、聚丙烯和ABS。它能夠成型具有嚴格公差的複雜形狀,這對於滿足醫療設備業的安全性和性能要求至關重要。此外,射出成型射出成型非常適合自動化,使其成為經濟高效地大量生產高品質產品的理想選擇。近年來,多色注塑和微注塑技術的進步進一步拓展了其應用範圍。
“在預測期內,北美市場預計將成為醫用聚合物市場第二快成長的地區。”
北美是醫用聚合物市場成長速度第二快的地區。在美國,隨著保險覆蓋範圍的擴大,以及加拿大對公共和私人醫療保健的大力投資,人均醫療保健支出正在成長。隨著醫學的進步,醫療設備、包裝和創傷護理領域預計在北美的成長速度將超過世界其他任何地區。美國擁有世界上最具創新性的醫療保健環境之一,其醫療保健基礎設施完善,研發生態系統強大,並與聚合物產業建立了牢固的夥伴關係。
我們進行了廣泛的初步訪談,以確定和檢驗幾個細分市場和子細分市場的市場規模,並透過二手研究收集資訊。
第一次面試的具體內容如下:
- 依公司類型分類:一級供應商:40%,二級供應商:30%,三級供應商:30%
- 按職位:董事:30%,經理:20%,其他:50%
- 按地區分類:亞太地區:40%,歐洲:10%,北美:20%,中東和非洲:20%,南美:10%
本研究對醫用聚合物市場的主要參與者進行了詳細的競爭分析,包括公司簡介、近期發展和關鍵市場策略。
調查範圍
本市場研究報告涵蓋醫用聚合物市場的各個細分領域。研究旨在根據產品類型、應用、製造技術和地區,估算各細分領域的市場規模和成長潛力。報告中還包括對市場主要參與者的詳細競爭分析、公司簡介、產品類型和業務範圍方面的關鍵觀察結果、各公司近期採取的發展舉措,以及為提升其在醫用聚合物市場地位而採取的關鍵成長戰略。
購買本報告的主要好處
本報告旨在幫助市場領導和新參與企業獲得關於醫用聚合物市場整體及其各細分市場和子細分市場銷售額的最準確估算。此外,本報告還將幫助相關人員了解市場狀況,取得提升自身業務地位的洞察,並制定合適的打入市場策略。同時,本報告旨在透過提供有關關鍵市場促進因素、限制、挑戰和機會的信息,幫助相關人員了解市場趨勢。
本報告深入分析了以下幾點:
- 關鍵促進因素(對生物相容性材料的需求不斷成長、全球人口老化、醫療技術的進步、對醫用級材料的監管支持)、阻礙因素(監管的複雜性和核准程序、來自替代材料的激烈競爭、環境永續性問題)、機遇(再生醫學的發展、對微創醫療設備的需求、可生物分解聚合物的進步永續性問題)、永續性問題(再生醫學的發展、對微創醫療器材的需求、可生物分解聚合物的進步)、永續性材料(久耐性和成本的限制)。
- 產品開發/創新:深入了解醫用聚合物市場的未來技術、研發活動以及新產品/服務的推出。
- 市場發展:盈利市場的全面資訊-本報告分析了各個地區的醫用聚合物市場。
- 市場多元化:有關醫用聚合物市場的新產品和服務、未開發的地區、近期趨勢和投資的全面資訊。
- 競爭分析:對主要公司的市場佔有率、成長策略和服務產品進行詳細評估。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 醫用聚合物市場企業面臨的極具吸引力的商機
- 亞太地區:醫用聚合物市場(按類型和國家分類)
- 醫用聚合物市場:依製造技術分類
- 醫用聚合物市場:依應用領域分類
- 醫用聚合物市場:依國家分類
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 醫用聚合物市場未滿足的需求
- 未開發市場中的機遇
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級主要公司的策略性舉措
- 主要發展和策略重點
第5章 產業趨勢
- 波特五力分析
- 新進入者的威脅
- 替代品的威脅
- 買方的議價能力
- 供應商的議價能力
- 競爭公司之間的競爭
- 總體經濟指標
- 全球GDP趨勢
- 醫療產業的趨勢
- 價值鏈分析
- 原物料供應商
- 製造商
- 分配
- 最終用戶
- 生態系統
- 價格分析
- 各地區平均售價趨勢
- 按應用程式分類的平均售價趨勢
- 貿易分析
- 導入場景
- 出口方案
- 重要會議和活動
- 影響客戶業務的趨勢和變化
- 醫用聚合物製造商的收入結構變化和新的收入來源
- 投資和資金籌措場景
- 案例研究分析
- 贏創工業集團向 JENACELL GMBH 供應醫用聚合物,用於傷口敷料、植入材料和藥物輸送系統。
- 恩欣格提供高性能醫用級聚合物,用於頻繁進行的外科手術。
- 2025年美國關稅對醫用聚合物市場的影響
- 主要關稅稅率
- 價格影響分析
- 主要國家和地區
- 對終端用戶產業的影響
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要技術
- 互補技術
- 技術和產品藍圖
- 短期(2025-2027)| 醫用級材料的創新與性能最佳化
- 中期規劃(2027-2030)| 先進材料、智慧製造與應用整合
- 長期(2030-2035年及以後)|永續高性能聚合物和智慧製造
- 專利分析
- 專利的法律地位
- 管轄權分析
- 未來應用
- 用於醫療器材和設備的高性能聚合物
- 永續、生物可吸收和生物衍生的醫用聚合物
- 積層製造和病患客製化醫用聚合物
- 先進聚合物加工、表面工程和智慧材料
- 人工智慧/生成式人工智慧對醫用聚合物市場的影響
- 醫用聚合物的主要應用案例和市場潛力
- 醫用聚合物加工的最佳實踐
- 人工智慧在醫用聚合物市場應用案例研究
- 相互關聯的鄰近生態系及其對市場參與者的影響
- 醫療聚合物市場中客戶對生成式人工智慧應用的準備情況
第7章永續性和監管情勢
- 區域法規和合規性
- 監管機構、政府機構和其他組織
- 業界標準
- 監理政策和永續發展舉措的影響
- 認證、標籤和環境標準
第8章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 採購過程中的關鍵相關人員
- 購買標準
- 實施障礙和內部挑戰
- 各終端用戶產業未滿足的需求
- 市場盈利
- 獲利潛力
- 成本趨勢
- 提高關鍵終端用戶產業利潤率的機會
第9章 醫用聚合物市場:依應用領域分類
- 醫用一次性用品
- 醫療器材及設備
- 義肢和矯正器具
- 診斷儀器和工具
- 其他用途
第10章 醫用聚合物市場:按類型分類
- 醫用塑膠
- 醫用彈性體
第11章 醫用聚合物市場:依製造技術分類
- 擠壓管
- 壓縮成型
- 射出成型
- 其他製造技術
第12章 醫用聚合物市場:依地區分類
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 亞太地區
- 中國
- 印度
- 韓國
- 日本
- 澳洲
- 亞太其他地區
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
- 中東和非洲
- 海灣合作理事會國家
- 南非
- 其他中東和非洲地區
第13章 競爭格局
- 概述
- 大公司的策略
- 收入分析(2022-2025)
- 市佔率分析(2025 年)
- 企業估值和財務指標
- 品牌與產品比較分析
- 企業估值矩陣:主要公司(2025 年)
- 明星公司
- 新興領導者
- 玩家種類繁多
- 參與企業
- 企業企業發展:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 先進公司
- 應對力的公司
- 充滿活力的公司
- 起始點
- 競爭標竿分析:領先的新創企業/中小企業,2025 年
- 競爭格局
- 產品發布
- 交易
- 業務拓展
第14章:公司簡介
- MAJOR PLAYERS
- BASF SE
- SABIC
- COVESTRO AG
- CELANESE CORPORATION
- EVONIK INDUSTRIES
- ARKEMA
- SOLVAY
- KURARAY CO., LTD.
- MOMENTIVE PERFORMANCE MATERIALS INC.
- DUPONT
- 其他主要公司
- TRINSEO
- KRATON CORPORATION
- TOTAL PLASTICS
- SIMONA AMERICA
- DSM
- INVIBIO
- AVIENT CORPORATION
- RTP COMPANY
- TEKNI-PLEX, INC.
- TEKNOR APEX
- MITSUBISHI CHEMICAL ADVANCED MATERIALS
- WACKER CHEMIE
- HARDIE POLYMERS
- ELIX POLYMERS
- INNOVATIVE POLYMER COMPOUNDS LTD.
第15章:調查方法
第16章附錄
The medical polymer market is projected to reach USD 71.92 billion by 2031 from USD 48.27 billion in 2026, at a CAGR of 8.3% during the forecast period. The medical polymer market is experiencing rapid growth due to progress in healthcare, materials engineering, and patient-focused innovation. The increased prevalence of chronic diseases, aging population, and the need for minimally invasive procedures is creating a preference for advanced polymers that provide flexibility, security, and accuracy.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) Volume (Kiloton) |
| Segments | Type, Application, Manufacturing Technology, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and Middle East & Africa |
The considerable shift in the use of disposable medical products for sanitation and fewer contaminants has contributed to the proliferation of components made from polymers. The science of polymers is advancing to create polymers and materials with superior mechanical strength, durability, antimicrobial properties, and compatibility with active sterilization techniques. Advances in knowledge and developments have resulted in breakthroughs in polymers that can hold shapes or be bioresorbable, offering opportunities in the areas of drug delivery devices and tissue engineering. The proliferation of medical-grade 3D printing has revolutionized this area because custom-designed implants and devices can now be developed rapidly. There is increased attention on sustainable practices, leading to interest in recyclable and biodegradable polymers.
"The medical elastomers segment is estimated to account for the second-largest share of the medical polymer market during the forecast period."
Medical elastomers account for the second-largest share of the medical polymer market due to their flexibility, durability, and biocompatibility, allowing them to be used for hundreds of precise applications in critical healthcare. Many of the devoted elastomer applications are products used to contain a fluid or products that need to be manipulated with constant movement, stretching or compression, like seals, gaskets, tubing, syringes, plungers, and catheter components. Medical elastomer products are best known because of their chemical resistance, resistance to temperature swings, and resistance to sterilization techniques, which enables reliable products in high-stress medical applications. Because silicone elastomers, thermoplastic elastomers (TPE), and rubber materials are often specifically mentioned in the literature due to increased comfort above conventional or hard polymers, they are favored for wearable medical devices and skin-contact applications. In addition, the influence of minimization continues to drive performance in elastomeric materials, as do the advanced design aspects influencing drug delivery systems, automated enclosed testing systems, and lifestyle diagnostic devices. Furthermore, elastomeric materials are especially amenable to automated manufacturing and/or molding with E-modulus and tensile strength decreases, enabling cost-effective product production at considerably large amounts.
"Medical disposables accounted for the second-largest application in the medical polymer market during the forecast period."
Medical disposables are the second-largest application in the medical polymer market. Items such as syringes, gloves, IV bags, tubing and connections, surgical drapes, and masks are designed for single-use to prevent cross-contamination and to maintain a sterile environment. The emphasis on infection prevention and the regulations supporting infection control have increased demand for disposable medical items. Due to their excellent processability, low cost, and compatibility with sterilizing processes, the polymers used in medical disposables are primarily polypropylene, polyethylene, and PVC. The increase in hospital stays, enhanced surgical procedures, and outpatient care, especially in developing areas, is driving demand for good quality disposables. The convenience of ready-to-use pre-sterilized items can add efficiency in busy medical settings. As health care continues to focus on safety, cost-effective practices and efficiencies, polymer medical disposables will be an important future growth area.
"Injection molding is the second-largest manufacturing technology in the medical polymer market during the forecast period."
Injection molding is the second-largest manufacturing technology in the medical polymer space because it can produce highly precise and complex components at scale with good reliability and efficiency. Injection molding is used to produce a wide variety of medical products, such as housing for diagnostic equipment, surgical instrument handles, syringes, connectors, and components of implantable devices. Injection molding is compatible with many medical-grade polymers, such as polycarbonate, polypropylene, and ABS. Injection molding can be made to tight tolerances with complex geometries, all of which are relevant in meeting the safety and performance requirements of the medical device industry. Injection molding is also compatible with automation and is conducive to produce item at large volumes while being cost-effective with high-quality output. Recent advancements in multi-shot and micro fabrications further enhance application range as well.
"North America market is projected to be the second-fastest growing region in the medical polymer market during the forecast period."
North America is the second-fastest growing region in the medical polymer market. Per capita healthcare expenses are rising, driven by expanding insurance coverage in the US and strong public and private healthcare investments in Canada. The medical devices, packaging, and wound care categories are projected to account for greater growth in North America than any other world region as healthcare advances. The US has one of the most innovative healthcare environments in the world. The country has a developed healthcare infrastructure, a strong research and development (R&D) ecosystem, and a strong partnership with the polymer industry.
Extensive primary interviews were conducted to determine and verify the market size for several segments and sub-segments, and information was gathered through secondary research.
The breakdown of primary interviews is given below:
- By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
- By Designation: Directors: 30%, Managers: 20%, and Others: 50%
- By Region: Asia Pacific: 40%, Europe: 10%, North America: 20%, Middle East & Africa: 20%, and South America: 10%
BASF SE (Germany), SABIC (Saudi Arabia), Covestro AG (Germany), Celanese Corporation (US), Evonik Industries (Germany), Arkema (France), Solvay (Belgium), Kuraray Co., Ltd. (Japan), Momentive Performance Materials Inc. (US), and DuPont (US) are some of the key players in the medical polymer market.
The study includes an in-depth competitive analysis of these key players in the medical polymer market, with their company profiles, recent developments, and key market strategies.
Research Coverage
The market study covers the medical polymer market across various segments. It aims to estimate the market size and the growth potential of this market across different segments based on type, application, manufacturing technology, and region. The study also includes an in-depth competitive analysis of key players in the market, their company profiles, key observations related to their products and business offerings, recent developments undertaken by them, and key growth strategies adopted by them to improve their position in the medical polymer market.
Key Benefits of Buying the Report
The report is expected to help the market leaders/new entrants in this market share the closest approximations of the revenue numbers of the overall medical polymer market and its segments and sub-segments. This report is projected to help stakeholders understand the competitive landscape of the market, gain insights to improve the position of their businesses, and plan suitable go-to-market strategies. The report also aims to help stakeholders understand the pulse of the market and provides them with information on the key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of key drivers (Increasing demand for biocompatible materials, Growing aging population globally, Advancements in medical technology, Regulatory support for medical-grade materials), restraints (Regulatory complexities and approvals, High competition from alternative materials, Environmental sustainability concerns), opportunities (Growth in regenerative medicine, Demand for minimally invasive devices, Advancements in biodegradable polymers), challenges (Cost constraints for novel materials, Long-term durability and degradation control).
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the medical polymer market
- Market Development: Comprehensive information about lucrative markets - the report analyses the medical polymer market across varied regions
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the medical polymer market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players like BASF SE (Germany), SABIC (Saudi Arabia), Covestro AG (Germany), Celanese Corporation (US), Evonik Industries (Germany), Arkema (France), Solvay (Belgium), Kuraray Co., Ltd. (Japan), Momentive Performance Materials Inc. (US), and DuPont (US), among others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 INCLUSIONS AND EXCLUSIONS
- 1.4 STUDY SCOPE
- 1.4.1 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 UNITS CONSIDERED
- 1.7 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN MEDICAL POLYMER MARKET
- 3.2 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE AND COUNTRY
- 3.3 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY
- 3.4 MEDICAL POLYMER MARKET, BY APPLICATION
- 3.5 MEDICAL POLYMER MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing demand for biocompatible and high-performance materials
- 4.2.1.2 Growing aging population and healthcare expenditure
- 4.2.1.3 Advancements in medical devices and minimally invasive procedures
- 4.2.1.4 Rise in chronic diseases
- 4.2.1.5 Increasing adoption of stringent medical-grade material and biocompatibility requirements
- 4.2.2 RESTRAINTS
- 4.2.2.1 Stringent regulatory and material qualification requirements
- 4.2.2.2 High competition from alternative polymers and materials
- 4.2.2.3 Environmental sustainability and chemical regulatory concerns
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growth in regenerative medicine and tissue engineering
- 4.2.3.2 Advancements in biodegradable and bioresorbable polymers
- 4.2.3.3 Growing adoption of 3D-printed and patient-specific medical devices
- 4.2.3.4 Increasing demand for minimally invasive and patient-specific devices
- 4.2.4 CHALLENGES
- 4.2.4.1 High cost and lengthy qualification of novel medical-grade materials
- 4.2.4.2 Balancing sustainability with durability, sterilization, and biocompatibility
- 4.2.4.3 Evolving restrictions on PFAS and other chemicals used in medical polymer applications
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS IN MEDICAL POLYMER MARKET
- 4.3.1 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT FROM NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 GLOBAL GDP TRENDS
- 5.2.2 HEALTHCARE INDUSTRY TRENDS
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 RAW MATERIAL SUPPLIERS
- 5.3.2 MANUFACTURERS
- 5.3.3 DISTRIBUTION
- 5.3.4 END USERS
- 5.4 ECOSYSTEM
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND, BY REGION
- 5.5.2 AVERAGE SELLING PRICE TREND, BY APPLICATION
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO
- 5.6.2 EXPORT SCENARIO
- 5.7 KEY CONFERENCES & EVENTS
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8.1 REVENUE SHIFT AND NEW REVENUE POCKETS FOR MEDICAL POLYMER MANUFACTURERS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 EVONIK INDUSTRIES PROVIDES MEDICAL POLYMERS TO JENACELL GMBH FOR WOUND DRESSINGS, IMPLANTABLE MATERIALS, AND DRUG DELIVERY SYSTEMS
- 5.10.2 ENSINGER OFFERS HIGH-PERFORMANCE, MEDICAL-GRADE POLYMERS FOR HIGH-FREQUENCY SURGERY
- 5.11 IMPACT OF 2025 US TARIFF ON MEDICAL POLYMER MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON KEY COUNTRIES/REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Biocompatible and medical-grade polymers
- 6.1.1.2 Medical-grade thermoplastic elastomers
- 6.1.1.3 High-performance medical polymer engineering
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Polymer-based additive manufacturing
- 6.1.2.2 Medical polymer surface modification techniques
- 6.1.2.3 Advanced polymer compounding and processing
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT TERM (2025-2027) | MEDICAL-GRADE MATERIAL INNOVATION & PERFORMANCE OPTIMIZATION
- 6.2.2 MID-TERM (2027-2030) | ADVANCED MATERIALS, SMART MANUFACTURING & APPLICATION INTEGRATION
- 6.2.3 LONG TERM (2030-2035+) | SUSTAINABLE HIGH-PERFORMANCE POLYMERS & INTELLIGENT MANUFACTURING
- 6.3 PATENT ANALYSIS
- 6.3.1 LEGAL STATUS OF PATENTS
- 6.3.2 JURISDICTION ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 HIGH-PERFORMANCE POLYMERS FOR MEDICAL INSTRUMENTS & DEVICES
- 6.4.2 SUSTAINABLE, BIORESORBABLE & BIO-BASED MEDICAL POLYMERS
- 6.4.3 ADDITIVE MANUFACTURING & PATIENT-SPECIFIC MEDICAL POLYMERS
- 6.4.4 ADVANCED POLYMER PROCESSING, SURFACE ENGINEERING & SMART MATERIALS
- 6.5 IMPACT OF AI/GEN AI ON MEDICAL POLYMER MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL OF MEDICAL POLYMERS
- 6.5.2 BEST PRACTICES IN MEDICAL POLYMER PROCESSING
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN MEDICAL POLYMER MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN MEDICAL POLYMER MARKET
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYING BEHAVIOUR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS & BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.6 MARKET PROFITABILITY
- 8.6.1 REVENUE POTENTIAL
- 8.6.2 COST DYNAMICS
- 8.6.3 MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES
9 MEDICAL POLYMER MARKET, BY APPLICATION
- 9.1 INTRODUCTION
- 9.2 MEDICAL DISPOSABLES
- 9.2.1 INCREASING DEMAND FOR CATHETERS AND SYRINGES TO DRIVE MARKET
- 9.2.2 GLOVES
- 9.2.3 SYRINGES
- 9.2.4 MEDICAL BAGS
- 9.2.5 OTHER MEDICAL DISPOSABLES
- 9.3 MEDICAL INSTRUMENTS & DEVICES
- 9.3.1 INCREASING USE OF ADVANCED AND MINIMALLY INVASIVE MEDICAL DEVICES TO DRIVE MARKET
- 9.3.2 MEDICAL TUBES
- 9.3.3 CATHETERS
- 9.3.4 DRUG DELIVERY INSTRUMENTS
- 9.3.5 OTHER MEDICAL INSTRUMENTS & DEVICES
- 9.4 PROSTHETICS
- 9.4.1 RISING DEMAND FOR ADVANCED LIMB PROSTHESES AND IMPLANTS TO DRIVE MARKET
- 9.4.2 IMPLANTS
- 9.4.3 LIMB PROSTHESIS
- 9.4.4 OTHER PROSTHETICS APPLICATIONS
- 9.5 DIAGNOSTIC INSTRUMENTS & TOOLS
- 9.5.1 INCREASING DEMAND IN SURGICAL AND PROCEDURAL APPLICATIONS TO DRIVE MARKET
- 9.5.2 DENTAL TOOLS
- 9.5.3 SURGICAL INSTRUMENTS
- 9.5.4 OTHER DIAGNOSTIC INSTRUMENTS & TOOLS
- 9.6 OTHER APPLICATIONS
10 MEDICAL POLYMER MARKET, BY TYPE
- 10.1 INTRODUCTION
- 10.2 MEDICAL PLASTICS
- 10.2.1 ADVANCEMENTS IN MATERIAL SCIENCE AND MANUFACTURING TECHNOLOGIES TO DRIVE MARKET
- 10.2.2 POLYPROPYLENE
- 10.2.3 POLYVINYL CHLORIDE
- 10.2.4 POLYETHYLENE
- 10.2.5 POLYSTYRENE
- 10.2.6 ENGINEERING & HIGH-PERFORMANCE PLASTICS
- 10.2.6.1 Polyether ether ketone
- 10.2.6.2 Nylon/polyamide
- 10.2.6.3 Polyphenylsulfone
- 10.2.6.4 Polysulfones
- 10.2.6.5 Polymethyl methacrylate
- 10.2.6.6 Polycarbonate
- 10.2.6.7 Acrylonitrile butadiene styrene
- 10.2.6.8 Other engineering & high-performance plastics
- 10.2.7 OTHER MEDICAL PLASTICS
- 10.3 MEDICAL ELASTOMERS
- 10.3.1 FLEXIBILITY, DURABILITY, AND BIOCOMPATIBILITY TO DRIVE MARKET
- 10.3.2 SILICONE
- 10.3.3 THERMOPLASTIC ELASTOMERS
- 10.3.3.1 Thermoplastic polyurethane
- 10.3.3.2 Thermoplastic vulcanizates
- 10.3.3.3 Thermoplastic styrenic elastomers
- 10.3.3.3.1 Poly (styrene-butadiene-styrene)
- 10.3.3.3.2 Styrene-ethylene-butylene-styrene
- 10.3.3.4 Thermoplastic copolyester elastomers
- 10.3.4 OTHER MEDICAL ELASTOMERS
11 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY
- 11.1 INTRODUCTION
- 11.2 EXTRUSION TUBING
- 11.2.1 INCREASING USE IN INTRAVENOUS DELIVERY SYSTEMS, CATHETERS, AND SURGICAL INSTRUMENTS TO DRIVE MARKET
- 11.3 COMPRESSION MOLDING
- 11.3.1 RISING USE IN PROSTHETIC AND ORTHOPEDIC COMPONENTS TO FUEL DEMAND
- 11.4 INJECTION MOLDING
- 11.4.1 INCREASING USE IN SYRINGES, SURGICAL INSTRUMENTS, AND MEDICAL DEVICE COMPONENTS TO SUPPORT MARKET GROWTH
- 11.5 OTHER MANUFACTURING TECHNOLOGIES
12 MEDICAL POLYMER MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 US
- 12.2.1.1 Strong medical R&D and device innovation to support demand
- 12.2.2 CANADA
- 12.2.2.1 Expanding medical device manufacturing and healthcare demand to support market
- 12.2.3 MEXICO
- 12.2.3.1 Expansion of medical-device manufacturing to support market growth
- 12.2.1 US
- 12.3 ASIA PACIFIC
- 12.3.1 CHINA
- 12.3.1.1 Establishment of medical device manufacturing units and investment in healthcare-related sectors to drive market
- 12.3.2 INDIA
- 12.3.2.1 Expansion of domestic medical device manufacturing to drive demand
- 12.3.3 SOUTH KOREA
- 12.3.3.1 Advanced medical device manufacturing and technology development to drive market
- 12.3.4 JAPAN
- 12.3.4.1 Aging population and advanced medical-device technologies to support market growth
- 12.3.5 AUSTRALIA
- 12.3.5.1 Strong medical device manufacturing and regulatory standards to support market growth
- 12.3.6 REST OF ASIA PACIFIC
- 12.3.1 CHINA
- 12.4 EUROPE
- 12.4.1 GERMANY
- 12.4.1.1 Advanced medical device manufacturing and aging population to support market growth
- 12.4.2 FRANCE
- 12.4.2.1 Aging population and advanced medical-device manufacturing to support market growth
- 12.4.3 UK
- 12.4.3.1 Growing medical device industry and government support for innovation to drive market
- 12.4.4 ITALY
- 12.4.4.1 Strong production facilities with presence of global players to propel market growth
- 12.4.5 SPAIN
- 12.4.5.1 Growing medical technology industry and government support to drive market
- 12.4.6 REST OF EUROPE
- 12.4.1 GERMANY
- 12.5 SOUTH AMERICA
- 12.5.1 BRAZIL
- 12.5.1.1 Aging population and expanding medical device industry to drive market
- 12.5.2 ARGENTINA
- 12.5.2.1 High import dependence and evolving medical device regulations to support market
- 12.5.3 REST OF SOUTH AMERICA
- 12.5.1 BRAZIL
- 12.6 MIDDLE EAST & AFRICA
- 12.6.1 GCC COUNTRIES
- 12.6.1.1 Saudi Arabia
- 12.6.1.1.1 Healthcare transformation and medical device localization to support market growth
- 12.6.1.2 UAE
- 12.6.1.2.1 Modernization of healthcare industry to drive market
- 12.6.1.3 Rest of GCC
- 12.6.1.1 Saudi Arabia
- 12.6.2 SOUTH AFRICA
- 12.6.2.1 Localization of medical device production to support market
- 12.6.3 REST OF MIDDLE EAST & AFRICA
- 12.6.1 GCC COUNTRIES
13 COMPETITIVE LANDSCAPE
- 13.1 OVERVIEW
- 13.2 KEY PLAYERS' STRATEGIES
- 13.3 REVENUE ANALYSIS, 2022-2025
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.5 COMPANY VALUATION AND FINANCIAL METRICS
- 13.6 BRAND/PRODUCT COMPARISON ANALYSIS
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.5.2 Region footprint
- 13.7.5.3 Type footprint
- 13.7.5.4 Manufacturing technology footprint
- 13.7.5.5 Application footprint
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING: KEY STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.5.2 Competitive benchmarking of key startups/SMEs
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
14 COMPANY PROFILES
- 14.1 MAJOR PLAYERS
- 14.1.1 BASF SE
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Services/Solutions offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product launches
- 14.1.1.3.2 Expansions
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 SABIC
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Services/Solutions offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.3.2 Deals
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 COVESTRO AG
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Services/Solutions offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Product launches
- 14.1.3.3.2 Expansions
- 14.1.3.4 MnM view
- 14.1.3.4.1 Key strengths
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 CELANESE CORPORATION
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Services/Solutions offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Deals
- 14.1.4.3.2 Expansions
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 EVONIK INDUSTRIES
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Services/Solutions offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Product launches
- 14.1.5.3.2 Deals
- 14.1.5.3.3 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 ARKEMA
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Services/Solutions offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Deals
- 14.1.6.3.2 Expansions
- 14.1.6.4 MnM view
- 14.1.7 SOLVAY
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Services/Solutions offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches
- 14.1.7.4 MnM view
- 14.1.8 KURARAY CO., LTD.
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Services/Solutions offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Expansions
- 14.1.8.4 MnM view
- 14.1.9 MOMENTIVE PERFORMANCE MATERIALS INC.
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Services/Solutions offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Expansions
- 14.1.9.4 MnM view
- 14.1.10 DUPONT
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Services/Solutions offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Product launches
- 14.1.10.3.2 Deals
- 14.1.10.3.3 Expansions
- 14.1.10.4 MnM view
- 14.1.1 BASF SE
- 14.2 OTHER PLAYERS
- 14.2.1 TRINSEO
- 14.2.2 KRATON CORPORATION
- 14.2.3 TOTAL PLASTICS
- 14.2.4 SIMONA AMERICA
- 14.2.5 DSM
- 14.2.6 INVIBIO
- 14.2.7 AVIENT CORPORATION
- 14.2.8 RTP COMPANY
- 14.2.9 TEKNI-PLEX, INC.
- 14.2.10 TEKNOR APEX
- 14.2.11 MITSUBISHI CHEMICAL ADVANCED MATERIALS
- 14.2.12 WACKER CHEMIE
- 14.2.13 HARDIE POLYMERS
- 14.2.14 ELIX POLYMERS
- 14.2.15 INNOVATIVE POLYMER COMPOUNDS LTD.
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 List of major secondary sources
- 15.1.1.2 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 List of primary interview participants-demand and supply side
- 15.1.2.3 Key industry insights
- 15.1.2.4 Breakdown of primary interviews
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 BASE NUMBER CALCULATION
- 15.3.1 DEMAND-SIDE APPROACH
- 15.3.2 SUPPLY-SIDE APPROACH
- 15.4 MARKET FORECAST APPROACH
- 15.4.1 SUPPLY SIDE
- 15.4.2 DEMAND SIDE
- 15.5 DATA TRIANGULATION
- 15.6 FACTOR ANALYSIS
- 15.7 ASSUMPTIONS
- 15.8 LIMITATIONS AND RISKS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS
List of Tables
- TABLE 1 MEDICAL POLYMER MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 MEDICAL POLYMER MARKET: IMPACT OF PORTER'S FIVE FORCES
- TABLE 3 PROJECTED REAL GDP GROWTH (ANNUAL PERCENTAGE CHANGE) OF KEY COUNTRIES, 2018-2025
- TABLE 4 GDP TRENDS AND FORECAST OF MAJOR ECONOMIES, 2023-2030 (USD BILLION, CURRENT PRICES)
- TABLE 5 U.S. NATIONAL HEALTH EXPENDITURE (NHE) TRENDS, 2022-2033
- TABLE 6 MEDICAL POLYMER MARKET: ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 7 MEDICAL POLYMER MARKET: CONFERENCES & EVENTS, 2026-2027
- TABLE 8 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 9 TOP USE CASES AND MARKET POTENTIAL
- TABLE 10 BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES
- TABLE 11 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 12 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 13 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 14 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 15 SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 16 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 17 GLOBAL STANDARDS IN MEDICAL POLYMER MARKET
- TABLE 18 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN MEDICAL POLYMER MARKET
- TABLE 19 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FOUR APPLICATIONS
- TABLE 20 KEY BUYING CRITERIA IN MAJOR APPLICATIONS
- TABLE 21 MEDICAL POLYMER MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES
- TABLE 22 MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 23 MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 24 MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 25 MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 26 MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 27 MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 28 MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 29 MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 30 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 31 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 32 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 33 MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 34 MEDICAL POLYMER MARKET, BY REGION, 2023-2025 (USD MILLION)
- TABLE 35 MEDICAL POLYMER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 36 MEDICAL POLYMER MARKET, BY REGION, 2023-2025 (KILOTON)
- TABLE 37 MEDICAL POLYMER MARKET, BY REGION, 2026-2031 (KILOTON)
- TABLE 38 NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 39 NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 40 NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 41 NORTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 42 NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 43 NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 44 NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 45 NORTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 46 NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 47 NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 48 NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 49 NORTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 50 NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 51 NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 52 NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 53 NORTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 54 US: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 55 US: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 56 US: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 57 US: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 58 US: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 59 US: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 60 US: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 61 US: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 62 CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 63 CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 64 CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 65 CANADA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 66 CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 67 CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 68 CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 69 CANADA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 70 MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 71 MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 72 MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 73 MEXICO: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 74 MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 75 MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 76 MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 77 MEXICO: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 78 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 79 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 80 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 81 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 82 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 83 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 84 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 85 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 86 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 87 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 88 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 89 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 90 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 91 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 92 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 93 ASIA PACIFIC: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 94 CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 95 CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 96 CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 97 CHINA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 98 CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 99 CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 100 CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 101 CHINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 102 INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 103 INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 104 INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 105 INDIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 106 INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 107 INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 108 INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 109 INDIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 110 SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 111 SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 112 SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 113 SOUTH KOREA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 114 SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 115 SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 116 SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 117 SOUTH KOREA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 118 JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 119 JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 120 JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 121 JAPAN: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 122 JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 123 JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 124 JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 125 JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 126 AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 127 AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 128 AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 129 AUSTRALIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 130 AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 131 AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 132 AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 133 AUSTRALIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 134 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 135 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 136 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 137 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 138 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 139 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 140 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 141 REST OF ASIA PACIFIC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 142 EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 143 EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 144 EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 145 EUROPE: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 146 EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 147 EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 148 EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 149 EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 150 EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 151 EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 152 EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 153 EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 154 EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 155 EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 156 EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 157 EUROPE: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 158 GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 159 GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 160 GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 161 GERMANY: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 162 GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 163 GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 164 GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 165 GERMANY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 166 FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 167 FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 168 FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 169 FRANCE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 170 FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 171 FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 172 FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 173 FRANCE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 174 UK: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 175 UK: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 176 UK: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 177 UK: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 178 UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 179 UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 180 UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 181 UK: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 182 ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 183 ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 184 ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 185 ITALY: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 186 ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 187 ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 188 ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 189 ITALY: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 190 SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 191 SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 192 SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 193 SPAIN: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 194 SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 195 SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 196 SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 197 SPAIN: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 198 REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 199 REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 200 REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 201 REST OF EUROPE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 202 REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 203 REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 204 REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 205 REST OF EUROPE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 206 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 207 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 208 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 209 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 210 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 211 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 212 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 213 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 214 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 215 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 216 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 217 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 218 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 219 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 220 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 221 SOUTH AMERICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 222 BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 223 BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 224 BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 225 BRAZIL: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 226 BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 227 BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 228 BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 229 BRAZIL: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 230 ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 231 ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 232 ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 233 ARGENTINA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 234 ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 235 ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 236 ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 237 ARGENTINA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 238 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 239 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 240 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 241 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 242 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 243 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 244 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 245 REST OF SOUTH AMERICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 246 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 247 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 248 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 249 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 250 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 251 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 252 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 253 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 254 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 255 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 256 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 257 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 258 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (USD MILLION)
- TABLE 259 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 260 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2023-2025 (KILOTON)
- TABLE 261 MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY MANUFACTURING TECHNOLOGY, 2026-2031 (KILOTON)
- TABLE 262 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 263 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 264 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 265 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 266 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 267 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 268 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 269 SAUDI ARABIA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 270 UAE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 271 UAE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 272 UAE: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 273 UAE: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 274 UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 275 UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 276 UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 277 UAE: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 278 REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 279 REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 280 REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 281 REST OF GCC: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 282 REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 283 REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 284 REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 285 REST OF GCC: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 286 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 287 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 288 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 289 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 290 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 291 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 292 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 293 SOUTH AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 294 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 295 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 296 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 297 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 298 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 299 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 300 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 301 REST OF MIDDLE EAST & AFRICA: MEDICAL POLYMER MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 302 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL POLYMER MARKET BETWEEN 2023 AND 2026
- TABLE 303 MEDICAL POLYMER MARKET: DEGREE OF COMPETITION
- TABLE 304 MEDICAL POLYMER MARKET: REGION FOOTPRINT
- TABLE 305 MEDICAL POLYMER MARKET: TYPE FOOTPRINT
- TABLE 306 MEDICAL POLYMER MARKET: MANUFACTURING TECHNOLOGY FOOTPRINT
- TABLE 307 MEDICAL POLYMER MARKET: APPLICATION FOOTPRINT
- TABLE 308 MEDICAL POLYMER MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 309 MEDICAL POLYMER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)
- TABLE 310 MEDICAL POLYMER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)
- TABLE 311 MEDICAL POLYMER MARKET: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 312 MEDICAL POLYMER MARKET: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 313 MEDICAL POLYMER MARKET: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 314 BASF SE: COMPANY OVERVIEW
- TABLE 315 BASF SE: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 316 BASF SE: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 317 BASF SE: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 318 SABIC: COMPANY OVERVIEW
- TABLE 319 SABIC: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 320 SABIC: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 321 SABIC: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 322 COVESTRO AG: COMPANY OVERVIEW
- TABLE 323 COVESTRO AG: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 324 COVESTRO AG: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 325 COVESTRO AG: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 326 CELANESE CORPORATION: COMPANY OVERVIEW
- TABLE 327 CELANESE CORPORATION: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 328 CELANESE CORPORATION: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 329 CELANESE CORPORATION: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 330 EVONIK INDUSTRIES: COMPANY OVERVIEW
- TABLE 331 EVONIK INDUSTRIES: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 332 EVONIK INDUSTRIES: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 333 EVONIK INDUSTRIES: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 334 EVONIK INDUSTRIES: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 335 ARKEMA: COMPANY OVERVIEW
- TABLE 336 ARKEMA: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 337 ARKEMA: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 338 ARKEMA: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 339 SOLVAY: COMPANY OVERVIEW
- TABLE 340 SOLVAY: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 341 SOLVAY: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 342 KURARAY CO., LTD.: COMPANY OVERVIEW
- TABLE 343 KURARAY CO., LTD.: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 344 KURARAY CO., LTD.: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 345 MOMENTIVE PERFORMANCE MATERIALS INC.: COMPANY OVERVIEW
- TABLE 346 MOMENTIVE PERFORMANCE MATERIALS INC.: PRODUCTS/SERVICES/ SOLUTIONS OFFERED
- TABLE 347 MOMENTIVE PERFORMANCE MATERIALS INC.: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 348 MOMENTIVE PERFORMANCE MATERIALS INC.: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 349 DUPONT: COMPANY OVERVIEW
- TABLE 350 DUPONT: PRODUCTS/SERVICES/SOLUTIONS OFFERED
- TABLE 351 DUPONT: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 352 DUPONT: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 353 DUPONT: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 354 TRINSEO: COMPANY OVERVIEW
- TABLE 355 KRATON CORPORATION: COMPANY OVERVIEW
- TABLE 356 TOTAL PLASTICS: COMPANY OVERVIEW
- TABLE 357 SIMONA AMERICA: COMPANY OVERVIEW
- TABLE 358 DSM: COMPANY OVERVIEW
- TABLE 359 INVIBIO: COMPANY OVERVIEW
- TABLE 360 AVIENT CORPORATION: COMPANY OVERVIEW
- TABLE 361 RTP COMPANY: COMPANY OVERVIEW
- TABLE 362 TEKNI-PLEX, INC.: COMPANY OVERVIEW
- TABLE 363 TEKNOR APEX: COMPANY OVERVIEW
- TABLE 364 MITSUBISHI CHEMICAL ADVANCED MATERIALS: COMPANY OVERVIEW
- TABLE 365 WACKER CHEMIE: COMPANY OVERVIEW
- TABLE 366 HARDIE POLYMERS: COMPANY OVERVIEW
- TABLE 367 ELIX POLYMERS: COMPANY OVERVIEW
- TABLE 368 INNOVATIVE POLYMER COMPOUNDS LTD.: COMPANY OVERVIEW
List of Figures
- FIGURE 1 MEDICAL POLYMER MARKET SEGMENTATION
- FIGURE 2 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 3 MEDICAL POLYMER MARKET, 2025-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL POLYMER MARKET (2020-2026)
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF MEDICAL POLYMER MARKET DURING FORECAST PERIOD
- FIGURE 6 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN MEDICAL POLYMER MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 8 HIGH DEMAND FOR MEDICAL POLYMER SECTOR TO CREATE LUCRATIVE OPPORTUNITIES FOR MARKET PLAYERS
- FIGURE 9 CHINA ACCOUNTED FOR LARGEST MARKET SHARE IN 2025
- FIGURE 10 EXTRUSION TUBING DOMINATED MEDICAL POLYMER MARKET IN 2025
- FIGURE 11 MEDICAL INSTRUMENTS & DEVICES SEGMENT ACCOUNTED FOR LARGEST SHARE OF MEDICAL POLYMER MARKET IN 2025
- FIGURE 12 INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 13 MEDICAL POLYMER MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 PORTER'S FIVE FORCES ANALYSIS: MEDICAL POLYMER MARKET
- FIGURE 15 MEDICAL POLYMER MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 MEDICAL POLYMER MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 AVERAGE SELLING PRICE TREND OF MEDICAL POLYMER, BY REGION, 2023-2025
- FIGURE 18 AVERAGE SELLING PRICE TREND OF APPLICATION, BY APPLICATION (2023-2025)
- FIGURE 19 IMPORT OF MEDICAL POLYMERS, BY COUNTRY, 2021-2025
- FIGURE 20 EXPORT OF MEDICAL POLYMERS, BY COUNTRY, 2021-2025
- FIGURE 21 REVENUE SHIFT AND NEW REVENUE POCKETS FOR MEDICAL POLYMER MANUFACTURERS
- FIGURE 22 INVESTMENT AND FUNDING SCENARIO, 2021-2025
- FIGURE 23 LIST OF MAJOR PATENTS FOR MEDICAL POLYMER, 2016-2025
- FIGURE 24 PATENT ANALYSIS, BY LEGAL STATUS
- FIGURE 25 TOP JURISDICTION, BY DOCUMENT
- FIGURE 26 MEDICAL POLYMER MARKET: DECISION-MAKING FACTORS
- FIGURE 27 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FOUR APPLICATIONS
- FIGURE 28 KEY BUYING CRITERIA IN MAJOR APPLICATIONS
- FIGURE 29 ADOPTION BARRIERS & INTERNAL CHALLENGES
- FIGURE 30 MEDICAL INSTRUMENTS & DEVICES TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD
- FIGURE 31 MEDICAL PLASTICS SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 32 EXTRUSION TUBING SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 33 MEDICAL POLYMER MARKET SNAPSHOT
- FIGURE 34 NORTH AMERICA: MEDICAL POLYMER MARKET SNAPSHOT
- FIGURE 35 ASIA PACIFIC: MEDICAL POLYMER MARKET SNAPSHOT
- FIGURE 36 EUROPE: MEDICAL POLYMER MARKET SNAPSHOT
- FIGURE 37 REVENUE ANALYSIS OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2022-2025
- FIGURE 38 SHARES OF TOP FIVE COMPANIES IN MEDICAL POLYMER MARKET, 2025
- FIGURE 39 VALUATION OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2025
- FIGURE 40 FINANCIAL METRICS OF KEY COMPANIES IN MEDICAL POLYMER MARKET, 2025
- FIGURE 41 MEDICAL POLYMER MARKET: BRAND/PRODUCT COMPARISON
- FIGURE 42 MEDICAL POLYMER MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 43 MEDICAL POLYMER MARKET: COMPANY FOOTPRINT
- FIGURE 44 MEDICAL POLYMER MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 45 BASF SE: COMPANY SNAPSHOT
- FIGURE 46 SABIC: COMPANY SNAPSHOT
- FIGURE 47 COVESTRO AG: COMPANY SNAPSHOT
- FIGURE 48 CELANESE CORPORATION: COMPANY SNAPSHOT
- FIGURE 49 EVONIK INDUSTRIES: COMPANY SNAPSHOT
- FIGURE 50 ARKEMA: COMPANY SNAPSHOT
- FIGURE 51 SOLVAY: COMPANY SNAPSHOT
- FIGURE 52 KURARAY CO., LTD.: COMPANY SNAPSHOT
- FIGURE 53 DUPONT: COMPANY SNAPSHOT
- FIGURE 54 MEDICAL POLYMER MARKET: RESEARCH DESIGN
- FIGURE 55 MEDICAL POLYMER MARKET: BOTTOM-UP APPROACH
- FIGURE 56 MEDICAL POLYMER MARKET: TOP-DOWN APPROACH
- FIGURE 57 MEDICAL POLYMER MARKET: APPROACH 1
- FIGURE 58 MEDICAL POLYMER MARKET: APPROACH 2
- FIGURE 59 MEDICAL POLYMER MARKET: DATA TRIANGULATION

 醫用合成聚合物材料市場:全球市場預測,2026-2032年醫用可生物分解纖維市場:全球市場預測,2026-2032年
 醫用聚合物市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測
 生物可分解合成纖維市場規模、佔有率和成長分析:按纖維類型、纖維形態、應用、終端用戶產業、生物分解環境和地區分類-產業預測,2026-2033年
 多材料3D列印聚合物市場規模、佔有率和趨勢分析報告:按材料類型、應用、地區和細分市場分類的市場預測(2026-2033年)
 醫用聚合物市場規模、佔有率、趨勢和預測:按產品類型、應用和地區分類,2026-2034年
 醫用聚合物市場:按類型、製造技術、應用、國家和地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 醫用聚合物市場:按產品、應用和地區分類
 熔融沈積成型(FFF)3D列印機市場規模、佔有率和成長分析:按印表機類型、列印床技術、耗材類型、應用、終端用戶產業和地區分類-2026-2033年產業預測
 醫用聚合物市場分析及預測(至2035年):依類型、產品類型、應用、材料類型、器材、製程、最終用戶、技術、功能分類