

 |
市場調查報告書
商品編碼
2136428
全球臨床試驗服務市場:按服務類型、階段、交付模式、研究設計、治療領域、治療方式、最終用戶和地區分類-預測至2031年Clinical Trial Services Market by Type (Lab, Monitoring, Contracts, Recruitment, PV, Biostatistics), Phase, Therapy (Oncology, Neurology, Dermatology, CVD), Modality (Biologics, Devices), Delivery Model (FSP, Hybrid) - Global forecast to 2031 |
||||||

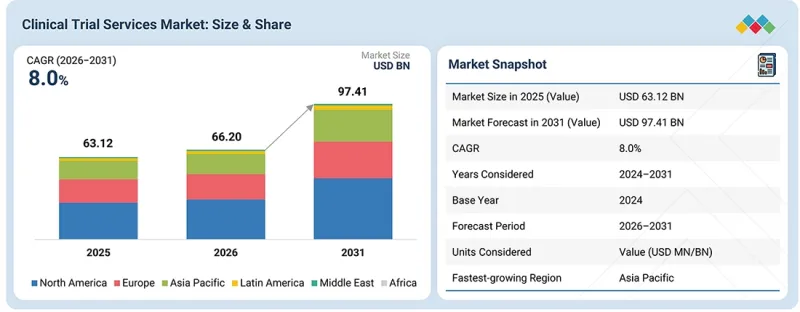
預計到 2031 年,臨床試驗服務市場規模將達到 974.1 億美元,而 2026 年為 662 億美元,2026 年至 2031 年預測期內的複合年成長率為 8.0%。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(10億美元) |
| 部分 | 按服務類型、階段、交付模式、試驗設計、治療領域、方式、最終用戶和地區分類。 |
| 目標區域 | 北美、歐洲、亞太地區、拉丁美洲、中東和非洲 |
隨著細胞和基因療法 (CGT) 以及精準醫療研發管線的不斷擴展,對 I 期至 IV 期臨床試驗專業外包服務的需求日益成長。這些項目通常需要複雜的方案、生物標記和基因組選擇、規模較小且地理分散的受試者群體、特殊的試驗中心要求、嚴格的檢體處理、客製化的藥物供應和物流,以及長期的安全性追蹤。這些需求促使申辦方將部分工作外包給合約臨床實驗)和在試驗中心選擇和管理、受試者招募、臨床監查、實驗室和生物標記檢測、數據管理、藥物安全性監查以及臨床試驗物流擁有豐富經驗的專業服務商。
從服務類型來看,實驗室服務領域在 2025 年將佔據臨床試驗服務市場第二大佔有率。
按服務類型分類,臨床試驗服務市場可細分為臨床實驗服務、現場管理和監查、與試驗中心簽訂合約和支付、臨床實驗招募和保留、醫學寫作、臨床試驗用藥供應和物流服務、安全性和藥物安全性監查、臨床試驗資料管理服務、諮詢等臨床試驗服務。至2025年,檢測服務將佔據第二大市場佔有率,僅次於臨床實驗管理和監查。檢測服務市佔率如此之大,是因為I期至IV期臨床試驗中廣泛需要分析和生物分析檢測,以產生可靠的檢測數據,用於藥物濃度測定、藥物動力學評估、生物標記和免疫抗原性評估以及療效和安全性評估。隨著生物製藥、癌症治療、細胞和基因療法以及其他複雜療法的研發進展,對專業檢測、生物標記檢測和高品質生物分析能力的需求進一步成長,申辦者也擴大將這些任務外包給合約研究組織(CRO)和專業檢測實驗室。
就最終用戶而言,到 2025 年,製藥和生物製藥公司將在臨床試驗服務市場中佔據最大佔有率。
從最終用戶/申辦方的角度來看,臨床試驗服務市場可細分為製藥和生物製藥公司、醫療設備公司以及學術機構。製藥和生物製藥公司可進一步細分為大型、中型和小型企業。到2025年,製藥和生物製藥公司將佔據最大的市場佔有率。這一龐大市場佔有率的促進因素包括:廣泛的I-IV期臨床開發平臺、巨額研發投入、日益複雜的試驗方案以及對CRO在全球範圍內開展試驗的日益依賴。外包服務使這些申辦方能夠利用專業的治療領域知識、全球試驗中心和受試者網路、可擴展的臨床營運資源以及在中心管理和監查、臨床試驗、資料管理、藥物安全監查、受試者招募和臨床試驗物流方面的能力,同時提高營運柔軟性和研發效率。
按地區分類,預計北美將在 2025 年佔據最大的市場佔有率。
到2025年,北美將佔據全球臨床試驗服務市場最大的佔有率,這得益於其成熟的製藥和生物製藥產業、高額的研發投入以及對I-IV期臨床試驗服務外包的巨大需求。該地區還擁有密集的臨床研究中心、醫院、大學附屬醫院和專業檢測實驗室網路,為大規模、複雜的臨床試驗提供了強大的基礎設施。此外,分散式和混合式臨床實驗模式、數位化病人參與工具、基於風險的監查以及先進的臨床數據技術(尤其是在美國)的快速普及,進一步推動了對諸如研究中心管理和監查、受試者招募和保留、數據管理、藥物安全監查、臨床試驗和臨床實驗物流等臨床實驗的需求。這些因素進一步鞏固了北美作為領先的臨床試驗服務外包區域市場的地位。
本報告涵蓋的公司簡介清單:
- IQVIA公司(美國)
- 賽默飛世爾科技公司(美國)
- Fortrea(美)
- ICON Plc(愛爾蘭)
- Syneos Health(美國)
- 美國實驗室控股公司(美國)
- Medpace(美國)
- 無錫康普(中國)
- Frontage Labs(美國)
- Pharmaron(美國)
- Tigermed(中國)
- SGS Societe Generale de Surveillance SA(瑞士)
- Eurofins Scientific(盧森堡)
- Linica(日本)
- Parexel International Corporation(美國)
- 全球臨床試驗(美國)
- 諾沃泰克(澳洲)
- PSI(瑞士)
- Allucent(美國)
- 德國研究(美國)
- 克拉里奧(美國)
- KCR SA(美國)
- Rho公司(美國)
- 高級臨床(美國)
調查範圍
本研究報告按服務類型、階段、治療領域、方式、交付模式、試驗設計、最終用戶/申辦方和地區對臨床試驗服務市場進行細分。
本報告詳細闡述了影響臨床試驗服務市場成長的關鍵促進因素、機會和挑戰。這些因素包括:在研藥物的擴展、臨床試驗複雜性的增加、研發投入的成長、合約研究組織(CRO)所提供服務的柔軟性、對更短藥物研發週期的需求、不斷演變的外包模式、監管現代化、人工智慧和數據分析、分散式和以患者/研究中心為中心的臨床試驗、受試者招募和保留方面的挑戰,以及專業臨床研究人員的短缺。報告還分析了行業趨勢、技術發展、監管和永續性考量、客戶格局、定價、生態系統趨勢和競爭格局。對主要市場參與企業的詳細評估涵蓋了他們的服務組合、策略、市場定位、合作夥伴關係、協議以及與臨床試驗服務市場相關的其他策略發展,例如服務推出、交易、合資企業、夥伴關係和收購。
購買本報告的主要好處
本報告提供臨床試驗服務市場及其細分市場最準確的收入估算,為市場領導者和新參與企業提供支援。此外,本報告也幫助相關人員深入了解競爭格局,獲取市場定位洞察,並制定合適的打入市場策略。本報告可協助相關人員了解市場趨勢,並獲取有關關鍵市場促進因素和挑戰的資訊。
本報告深入分析了以下幾點:
- 對關鍵促進因素(專業治療領域日益複雜的研發管線和臨床試驗活動、不斷擴大的研發投資和強大的臨床管線、CRO 提供的服務的柔軟性、對更短的藥物開發週期和更高生產力的需求,以及從全方位服務 CRO 向FSP/混合/策略外包模式的逐步轉變)、影響臨床試驗服務市場成長的機會(監管現代化和創新試驗設計、臨床開發中的人工智慧、自動化和數據分析,以及以患者/研究中心為中心和分散式臨床試驗)和挑戰(受試者的招募和留存,以及合格臨床研究人員和專業知識的短缺)的分析。
- 服務開發與創新:深入了解新推出或正在發展的臨床試驗服務和技術驅動解決方案。
- 市場發展:盈利市場的全面資訊-本報告分析了各個地區的市場。
- 市場多元化:臨床試驗服務市場的新服務、未開發的地區、近期趨勢和投資的全面資訊。
- 競爭格局分析:本報告詳細評估了領先的臨床試驗服務供應商的市場佔有率、成長策略、服務產品和競爭定位,這些公司包括賽默飛世爾科技(PPD公司)、IQVIA公司、ICON plc、美國實驗室控股公司、Syneos Health、藥明康德、Eurofins Scientific、Parexel International Corporation、Fortrea、Synec、SGS、SGS、SGS、SGS、Tile、SGSer、SGS」公司、SGS」公司、SGS、SGS、SGS、SGS、SGS」、SGS、SGSS、SGSS、SGSS、SGS」。報告分析了臨床試驗服務市場的關鍵策略、新服務推出、交易、收購、合作、協議、合資企業、業務擴張、投資和資金籌措活動、品牌/服務對比分析以及供應商估值和財務指標。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 市場趨勢
- 影響我們客戶公司業務的趨勢/變化
- 價格分析
- 價值鏈分析
- 生態系分析
- 投資及資金籌措活動
- 重要會議和活動
- 波特五力分析
- 川普關稅政策在2025年對臨床試驗服務市場的影響
- 宏觀經濟展望
第6章:科技進步、人工智慧的影響、創新與未來應用
- 技術分析
- 人工智慧/生成式人工智慧對臨床試驗服務市場的影響
- 技術/服務藍圖
- 未來應用
第7章永續性和監管情勢
- 當地法規和合規性
- 對永續性和監管政策舉措的影響
- 認證、標籤檢視和環境標準
第8章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 客戶狀況
- 各個終端用戶產業中尚未滿足的需求
- 市場盈利
第9章:臨床試驗服務市場(依服務類型分類)
- 臨床試驗管理和監測
- 檢查服務
- 臨床試驗資料管理服務
- 臨床試驗材料供應與物流服務
- 諮詢
- 病人招募和留存
- 醫用照明
- 安全和藥物安全監測
- 網站合約及付款
- 其他
第10章:臨床試驗服務市場(依階段分類)
- 第三階段
- 第二階段
- 第一階段
- 第四階段
第11章 臨床試驗服務市場(依交付模式分類)
- 全方位服務外包(FSO)模式
- 功能服務供應商(FSP)模型
- 混合模式
第12章 臨床試驗服務市場(依試驗設計分類)
- 干涉
- 觀察
第13章:臨床試驗服務市場(依治療領域分類)
- 腫瘤學
- 神經病學
- 呼吸系統疾病
- 代謝性疾病/內分泌學
- 心血管疾病
- 皮膚科
- 消化系統疾病
- 免疫疾病
- 感染疾病
- 精神病學
- 眼科
- 血液學
- 泌尿生殖系統與女性健康
- 其他
第14章 臨床試驗服務市場(依模式分類)
- 低分子
- 生物製劑
- 單株抗體
- 細胞和基因治療
- 其他生技藥品
- 生物相似藥
- 醫療設備和體外診斷醫療器械
第15章:臨床試驗服務市場(依最終使用者分類)
- 製藥和生物製藥公司
- 醫療設備公司
- 學術機構
第16章 臨床試驗服務市場(按地區分類)
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他
- 拉丁美洲
- 巴西
- 墨西哥
- 其他
- 中東
- 海灣合作理事會國家
- 其他
- 非洲
第17章 競爭格局
- 概述
- 主要參與企業的策略/優勢,2023-2025年
- 2023-2025年收入分析
- 2025年市佔率分析
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 企業估值和財務指標
- 品牌/服務比較
- 競爭格局
第18章:公司簡介
- 主要參與企業
- IQVIA INC.
- ICON PLC
- THERMO FISHER SCIENTIFIC INC.
- FORTREA
- SYNEOS HEALTH
- LABORATORY CORPORATION OF AMERICA HOLDINGS
- MEDPACE
- WUXI APPTEC
- FRONTAGE LABS
- PHARMARON
- TIGERMED
- SGS SA
- EUROFINS SCIENTIFIC
- LINICAL
- PAREXEL INTERNATIONAL CORPORATION
- PSI CRO AG
- NOVOTECH
- BIOAGILE
- ADVANCED CLINICAL
- FIRMA CLINICAL RESEARCH
- 其他公司
- WORLDWIDE CLINICAL TRIALS
- PROPHARMA
- ALLUCENT
- PREMIER RESEARCH
- CAIDYA
- ERGOMED GROUP
- CLARIO
- PRECISION MEDICINE GROUP, LLC.
- EPS HOLDINGS, INC.
- GUIRES INC.(PEPGRA)
- KCR SA
第19章:調查方法
第20章附錄
The clinical trial services market is projected to reach USD 97.41 billion by 2031 from USD 66.20 billion in 2026, at a CAGR of 8.0% during the forecast period of 2026 to 2031.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Service Type, Therapy Area, Phase, Study Design, Modality, Delivery Model, End User/Sponsor |
| Regions covered | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
The expanding pipeline of cell & gene therapies (CGTs) and precision medicines is increasing demand for specialized outsourced Phase I-IV clinical trial services. These programs often involve complex protocols, biomarker- or genomic-based patient selection, small and geographically dispersed patient populations, specialized site requirements, stringent sample handling, customized clinical supply and logistics, and extended safety follow-up. Such requirements are encouraging sponsors to engage CROs and specialized providers with capabilities in site identification and management, patient recruitment, clinical monitoring, laboratory and biomarker testing, data management, pharmacovigilance, and clinical trial logistics.
By service type, the laboratory services segment accounted for the second-largest share of the clinical trial services market in 2025.
By service type, the clinical trial services market is segmented into laboratory services, site management and monitoring, site contracts and payments, patient recruitment and retention, medical writing, clinical trial supply & logistics services, safety and pharmacovigilance, clinical trial data management services, consulting, and other clinical trial services. In 2025, laboratory services accounted for the second-largest share of the market, following site management and monitoring. The significant share of laboratory services stems from the extensive need for analytical and bioanalytical testing during Phase I-IV clinical trials to measure drug concentrations, evaluate pharmacokinetics, assess biomarkers and immunogenicity, and generate reliable laboratory data for efficacy and safety assessments. Increasing development of biologics, oncology therapies, cell & gene therapies, and other complex modalities is further increasing demand for specialized assays, biomarker testing, and high-quality bioanalytical capabilities, encouraging sponsors to outsource these activities to CROs and specialized laboratories.
By end user, the pharmaceutical & biopharmaceutical companies accounted for the largest share in the clinical trial services market in 2025.
Based on end user/sponsor, the clinical trial services market is segmented into pharmaceutical & biopharmaceutical companies, medical device companies, and academic institutes. Pharmaceutical & biopharmaceutical companies are further segmented into large and mid-size and small companies. In 2025, pharmaceutical & biopharmaceutical companies accounted for the largest market share. This segment's large share is driven by extensive Phase I-IV clinical development pipelines, substantial R&D expenditure, increasing protocol complexity, and growing reliance on CROs for global trial execution. Outsourcing enables these sponsors to access specialized therapeutic expertise, global site and patient networks, scalable clinical operations resources, and capabilities in site management and monitoring, laboratory testing, data management, pharmacovigilance, patient recruitment, and clinical trial logistics while improving operational flexibility and development efficiency.
By region, North America accounted for the largest share of the market in 2025.
In 2025, North America held the largest share of the global clinical trial services market, supported by a well-established pharmaceutical and biopharmaceutical industry, high R&D expenditure, and substantial demand for outsourced Phase I-IV clinical trial services. The region also benefits from a dense network of clinical research sites, hospitals, academic medical centers, and specialized laboratories, providing strong infrastructure for large-scale and complex clinical studies. In addition, the rapid adoption of decentralized and hybrid trial models, digital patient-engagement tools, risk-based monitoring, and advanced clinical data technologies, particularly in the US, is further supporting demand for services such as site management and monitoring, patient recruitment and retention, data management, pharmacovigilance, laboratory testing, and clinical trial logistics. These factors continue to strengthen North America's position as the leading regional market for outsourced clinical trial services.
List of Companies Profiled in the Report:
- IQVIA Inc. (US)
- Thermo Fisher Scientific Inc. (US)
- Fortrea (US)
- ICON Plc (Ireland)
- Syneos Health (US)
- Laboratory Corporation of America Holdings (US)
- Medpace (US)
- Wuxi AppTec (China)
- Frontage Labs (US)
- Pharmaron (US)
- Tigermed (China)
- SGS Societe Generale de Surveillance SA. (Switzerland)
- Eurofins Scientific (Luxembourg)
- Linical (Japan)
- Parexel International Corporation (US)
- Worldwide Clinical Trials (US)
- Novotech (Australia)
- PSI (Switzerland)
- Allucent (US)
- Premier Research (US)
- Clario (US)
- KCR S.A. (US)
- Rho, Inc. (US)
- Advanced Clinical (US)
Research Coverage
This research report categorizes the clinical trial services market by service type, phase, therapeutic area, modality, delivery model, study design, end user/sponsor, and region.
The report provides detailed information on the key drivers, opportunities, and challenges influencing the growth of the clinical trial services market, including increasing pipeline and trial complexity, growing R&D investment, service flexibility offered by CROs, demand for faster drug-development timelines, evolving outsourcing models, regulatory modernization, AI and data analytics, decentralized and patient/site-centric trials, patient recruitment and retention challenges, and shortages of specialized clinical research talent. It also analyzes industry trends, technology developments, regulatory and sustainability considerations, customer landscape, pricing, ecosystem dynamics, and the competitive landscape. A detailed assessment of key market participants covers their service portfolios, strategies, market positioning, partnerships, agreements, and other strategic developments, including service launches, deals, collaborations, partnerships, and acquisitions associated with the clinical trial services market.
Key Benefits of Buying the Report
The report will help market leaders/new entrants by providing the closest approximations of the revenue numbers for the overall clinical trial services market and its subsegments. It will also help stakeholders better understand the competitive landscape and gain insights to position their business and develop suitable go-to-market strategies. This report will help stakeholders understand the market's pulse and provide information on key market drivers, opportunities, and challenges.
The report provides insights into the following pointers:
- Analysis of key drivers (growing pipeline complexity and increasing clinical-trial activity in specialty therapies, growing R&D investments and presence of a robust clinical pipeline, service flexibility offered by CROs, demand for faster drug-development timelines and productivity improvement, and the gradual shift from full-service CRO toward FSP/hybrid/strategic outsourcing models), opportunities (regulatory modernization and innovative trial designs, AI, automation and data analytics in clinical development, and patient/site-centric and decentralized clinical trials), and challenges (patient recruitment and retention and shortage of qualified clinical research talent and specialized expertise) influencing the growth of the clinical trial services market
- Service Development/Innovation: Detailed insights into newly introduced and evolving clinical trial services and technology-enabled solutions
- Market Development: Comprehensive information about lucrative markets-the report analyzes the market across varied regions.
- Market Diversification: Exhaustive information about new services, untapped geographies, recent developments, and investments in the clinical trial services market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, service offerings, and competitive positioning of key clinical trial service providers, including Thermo Fisher Scientific Inc. (PPD, Inc.), IQVIA Inc., ICON plc, Laboratory Corporation of America Holdings, Syneos Health, WuXi AppTec, Eurofins Scientific, Parexel International Corporation, Fortrea Inc., Medpace, SGS, Frontage Labs, Pharmaron, Tigermed, and BioAgile, among others. The report analyzes key strategies, service launches, deals, acquisitions, partnerships, agreements, collaborations, expansions, investment and funding activities, brand/service comparative analysis, and vendor valuation and financial metrics in the clinical trial services market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS & EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKETS COVERED
- 1.3.2 REGIONAL SCOPE
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 GLOBAL CLINICAL TRIAL SERVICES MARKET SNAPSHOT
- 3.2 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY AND COUNTRY, 2025
- 3.3 CLINICAL TRIAL SERVICES MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing pipeline complexity and increasing clinical-trial activity in specialty and advanced therapies
- 4.2.1.2 Resilient biopharma R&D investment and broad clinical-development pipeline
- 4.2.1.3 Flexible and scalable service delivery offered by CROs
- 4.2.1.4 Pressure to shorten development timelines and improve clinical R&D productivity
- 4.2.1.5 Growing adoption of FSP, hybrid, and strategic portfolio-based outsourcing models
- 4.2.2 OPPORTUNITIES
- 4.2.2.1 Regulatory modernization and adoption of innovative trial designs
- 4.2.2.2 AI, automation, and advanced data analytics across clinical development
- 4.2.2.3 Patient- and site-centric, decentralized, and hybrid clinical-trial models
- 4.2.3 CHALLENGES
- 4.2.3.1 Patient recruitment, enrollment, and retention constraints
- 4.2.3.2 Shortage of qualified clinical-research talent and specialized domain expertise
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 MARKET TRENDS
- 5.1.1 INTEGRATION OF HEOR AND RWE INTO CLINICAL TRIAL DESIGN
- 5.1.2 INCREASING FOCUS ON IN SILICO TRIALS
- 5.1.3 FSP AND HYBRID OUTSOURCING ARE GAINING STRATEGIC IMPORTANCE VERSUS ONE-SIZE-FITS-ALL FULL-SERVICE OUTSOURCING
- 5.1.4 SUSTAINABILITY AND ESG PRESSURES ARE SHAPING CLINICAL TRIALS
- 5.1.5 SUPPLIER CONSOLIDATION AND STRATEGIC PARTNERSHIPS REDEFINE MARKET
- 5.2 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.3 PRICING ANALYSIS
- 5.3.1 INDICATIVE PRICING RANGE, BY SERVICE TYPE, 2025
- 5.3.2 INDICATIVE PRICING ANALYSIS, BY PHASE, 2025
- 5.3.3 INDICATIVE PRICING ANALYSIS, BY REGION, 2025
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 INVESTMENT/FUNDING ACTIVITY
- 5.7 KEY CONFERENCES & EVENTS
- 5.8 PORTER'S FIVE FORCES ANALYSIS
- 5.8.1 THREAT OF NEW ENTRANTS
- 5.8.2 THREAT OF SUBSTITUTES
- 5.8.3 BARGAINING POWER OF BUYERS
- 5.8.4 BARGAINING POWER OF SUPPLIERS
- 5.8.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.9 IMPACT OF 2025 TRUMP TARIFF ON CLINICAL TRIAL SERVICES MARKET
- 5.9.1 INTRODUCTION
- 5.9.2 KEY TARIFF RATES
- 5.9.3 PRICE IMPACT ANALYSIS
- 5.9.4 IMPACT ON COUNTRY/REGION
- 5.9.4.1 North America
- 5.9.4.1.1 US
- 5.9.4.2 Europe
- 5.9.4.3 Asia Pacific
- 5.9.4.1 North America
- 5.9.5 IMPACT ON END-USE INDUSTRIES
- 5.9.5.1 Pharmaceutical & biotech companies
- 5.9.5.2 Medical devices companies
- 5.9.5.3 Academic institutes
- 5.10 MACROECONOMIC OUTLOOK
- 5.10.1 INTRODUCTION
- 5.10.2 GDP TRENDS AND FORECAST
- 5.10.3 TRENDS IN GLOBAL CLINICAL TRIAL SERVICES MARKET
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVE N IMPACT, INNOVATIONS AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 AI-integrated Clinical Trial Management System (CTMS) & Electronic Trial Master File (eTMF) platforms
- 6.1.1.2 Randomization and Trial Supply Management (RTSM)
- 6.1.1.3 Electronic Data Capture (EDC) System
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Digital Biomarkers, Wearables & Electronic Patient-Reported Outcome (EPRO) Tools
- 6.1.2.2 Model-Informed Drug Development (MIDD)
- 6.1.2.3 Data Management and Informatics Technologies
- 6.1.2.4 Real-world evidence (RWE) & real-world data (RWD) platforms
- 6.1.3 ADJACENT TECHNOLOGY
- 6.1.3.1 Clinical trial simulation tools
- 6.1.1 KEY TECHNOLOGIES
- 6.2 IMPACT OF AI/GEN AI ON CLINICAL TRIAL SERVICES MARKET
- 6.2.1 INTRODUCTION
- 6.2.2 MARKET POTENTIAL ACROSS DRUG DEVELOPMENT STAGES
- 6.2.3 KEY COMPANIES IMPLEMENTING AI
- 6.2.4 FUTURE OF GENERATIVE AI IN DRUG DEVELOPMENT ECOSYSTEM
- 6.3 TECHNOLOGY/SERVICE ROADMAP
- 6.4 FUTURE APPLICATIONS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK & CLINICAL TRIAL AUTHORIZATION
- 7.1.3 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 CUSTOMER LANDSCAPE
- 8.3.1 BUDGET ALLOCATION TREND
- 8.3.2 ADOPTION BARRIER & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE
- 9.1 INTRODUCTION
- 9.2 CLINICAL TRIAL MANAGEMENT & MONITORING
- 9.2.1 ADOPTION OF ADVANCED TECHNOLOGIES SUCH AS ARTIFICIAL INTELLIGENCE AND RISE OF REMOTE CLINICAL MONITORING TO SUPPORT MARKET GROWTH
- 9.3 LABORATORY SERVICES
- 9.3.1 ANALYTICAL TESTING SERVICES
- 9.3.1.1 Increasing demand for analytical testing for drug development to drive market
- 9.3.2 BIOANALYTICAL TESTING SERVICES
- 9.3.2.1 Rising focus on biologics in advanced therapies to drive market
- 9.3.1 ANALYTICAL TESTING SERVICES
- 9.4 CLINICAL TRIAL DATA MANAGEMENT SERVICES
- 9.4.1 GROWING RELIANCE ON DATA FOR CLINICAL EVALUATIONS BY REGULATORY BODIES TO SUPPORT MARKET GROWTH
- 9.4.2 BIOSTATISTICS
- 9.4.2.1 Integration of real-world data (RWD) into statistical analysis to support market growth
- 9.4.3 OTHER DATA MANAGEMENT SERVICES
- 9.5 CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES
- 9.5.1 COMPLEXITIES ASSOCIATED WITH SUPPLY AND LOGISTICS TO DRIVE MARKET
- 9.6 CONSULTING
- 9.6.1 INCREASING COMPLEXITIES DURING TRIALS TO DRIVE MARKET
- 9.7 PATIENT RECRUITMENT & RETENTION
- 9.7.1 INCREASING REQUIREMENT FOR DECENTRALIZED CLINICAL TRIAL SERVICES TO BOOST MARKET GROWTH
- 9.8 MEDICAL WRITING
- 9.8.1 INCREASED OUTSOURCING OF MEDICAL WRITING SERVICES IN EMERGING ECONOMIES TO DRIVE MARKET
- 9.9 SAFETY & PHARMACOVIGILANCE
- 9.9.1 REGULATORY AND SAFETY MONITORING EXPERTISE OFFERED BY CROS TO SUPPORT MARKET GROWTH
- 9.10 SITE CONTRACTS & PAYMENTS
- 9.10.1 GROWING NEED FOR STREAMLINED SITE CONTRACTING AND PAYMENT MANAGEMENT TO SUPPORT MARKET GROWTH
- 9.11 OTHER SERVICE TYPES
10 CLINICAL TRIAL SERVICES MARKET, BY PHASE
- 10.1 INTRODUCTION
- 10.2 PHASE III
- 10.2.1 HIGH SIGNIFICANCE OF PHASE III TRIALS TO DRIVE DEMAND FOR OUTSOURCING
- 10.3 PHASE II
- 10.3.1 LONG DURATION OF PHASE II STUDIES TO CREATE GROWTH OPPORTUNITIES FOR CROS
- 10.4 PHASE I
- 10.4.1 DECLINING TRIALS TO POSE GROWTH CHALLENGE TO MARKET
- 10.5 PHASE IV
- 10.5.1 SIGNIFICANCE OF PHASE IV TO SUPPORT MARKET GROWTH
11 CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL
- 11.1 INTRODUCTION
- 11.2 FULL-SERVICE OUTSOURCING (FSO) MODEL
- 11.2.1 RISE IN NUMBER OF EMERGING BIOPHARMACEUTICAL COMPANIES TO DRIVE MARKET
- 11.3 FUNCTIONAL SERVICE PROVIDER (FSP) MODEL
- 11.3.1 GROWING ADOPTION OF FSP SERVICES BY LARGE PHARMACEUTICAL COMPANIES TO FUEL MARKET GROWTH
- 11.4 HYBRID MODEL
- 11.4.1 HIGH FLEXIBILITY OFFERED BY HYBRID MODEL TO SUPPORT MARKET GROWTH
12 CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN
- 12.1 INTRODUCTION
- 12.2 INTERVENTIONAL
- 12.2.1 MAJOR ROLE OF INTERVENTIONAL TRIALS IN EVALUATING SAFETY AND EFFICACY OF NEW DRUGS AND DEVICES TO DRIVE MARKET
- 12.3 OBSERVATIONAL
- 12.3.1 INCREASING RELIANCE ON OBSERVATIONAL STUDIES TO EVALUATE EFFICACY OF DRUGS IN REAL-WORLD SCENARIO TO SUPPORT MARKET GROWTH
13 CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA
- 13.1 INTRODUCTION
- 13.2 ONCOLOGY
- 13.2.1 GROWING DISEASE BURDEN AND FOCUS ON DEVELOPING NOVEL MEDICINES FOR CANCER TO DRIVE MARKET
- 13.2.2 BREAST CANCER
- 13.2.2.1 Increasing cases and high spending on treating breast cancer to support growth
- 13.2.3 LUNG CANCER
- 13.2.3.1 Increasing focus on developing drugs against lung cancer to foster growth
- 13.2.4 COLORECTAL CANCER
- 13.2.4.1 Increasing drug discovery and development efforts against colorectal cancer to aid growth
- 13.2.5 PROSTATE CANCER
- 13.2.5.1 Growing clinical pipeline to propel market
- 13.2.6 OTHER CANCER
- 13.3 NEUROLOGY
- 13.3.1 INCREASING R&D INVESTMENTS RELATED TO NEUROLOGICAL DISORDERS TO DRIVE MARKET
- 13.4 RESPIRATORY DISORDERS
- 13.4.1 RISING INCIDENCE OF RESPIRATORY DISORDERS TO SUPPORT MARKET GROWTH
- 13.5 METABOLIC DISORDERS/ENDOCRINOLOGY
- 13.5.1 INCREASING GLOBAL DIABETES POPULATION TO BOOST MARKET GROWTH
- 13.6 CARDIOVASCULAR SYSTEM DISORDERS
- 13.6.1 HIGH FOCUS ON PHARMACEUTICAL R&D ATTRIBUTED TO RISING MORTALITY RATES DUE TO CVD TO DRIVE MARKET
- 13.7 DERMATOLOGY
- 13.7.1 GROWING FOCUS ON DRUG DEVELOPMENT FOR DIFFERENT SKIN CONDITIONS TO SUPPORT MARKET GROWTH
- 13.8 GASTROINTESTINAL DISEASES
- 13.8.1 EXPANSION AND DEVELOPMENT OF GASTROINTESTINAL DRUG PRODUCT LINE TO PROPEL MARKET
- 13.9 IMMUNOLOGICAL DISORDERS
- 13.9.1 GROWING CLINICAL RESEARCH FOR IMMUNOLOGICAL DISORDERS TO FUEL MARKET GROWTH
- 13.10 INFECTIOUS DISEASES
- 13.10.1 RISING OUTBREAKS OF INFECTIOUS DISEASES TO INCREASE DRUG DISCOVERY ACTIVITIES AND DRIVE MARKET
- 13.11 PSYCHIATRY
- 13.11.1 GROWING INCIDENCE OF PSYCHIATRIC DISORDERS TO SUPPORT MARKET GROWTH
- 13.12 OPHTHALMOLOGY
- 13.12.1 RISING NUMBER OF OPHTHALMOLOGY PIPELINE DRUGS TO SUPPORT SEGMENT GROWTH
- 13.13 HEMATOLOGY
- 13.13.1 CONSISTENT DRUG DEVELOPMENT EFFORTS FOR HEMATOLOGICAL DISORDERS TO SUPPORT MARKET GROWTH
- 13.14 GENITOURINARY & WOMEN'S HEALTH
- 13.14.1 RISING PREVALENCE OF CHRONIC DISORDERS IN WOMEN TO PROPEL MARKET
- 13.15 OTHER THERAPEUTIC AREAS
14 CLINICAL TRIAL SERVICES MARKET, BY MODALITY
- 14.1 INTRODUCTION
- 14.2 SMALL MOLECULES
- 14.2.1 STRONG PIPELINE GROWTH AND GROWING INVESTMENTS TO SUPPORT GROWTH
- 14.3 BIOLOGICS
- 14.3.1 GROWING COLLABORATIONS TO DEVELOP NEW BIOLOGICS AND REGULATORY SUPPORT TO PROPEL DEMAND
- 14.4 MONOCLONAL ANTIBODY
- 14.4.1 SURGING DEMAND FOR TARGETED THERAPIES TO DRIVE MARKET
- 14.5 CELL & GENE THERAPY
- 14.5.1 DEVELOPMENT COMPLEXITY AND REGULATORY MOMENTUM TO DRIVE CRO DEMAND
- 14.6 OTHER BIOLOGICS
- 14.7 BIOSIMILARS
- 14.7.1 INCREASING DEMAND FOR COST-EFFECTIVE ALTERNATIVES TO SUPPORT BIOSIMILARS GROWTH, THUS AIDING OUTSOURCING
- 14.8 MEDICAL DEVICES & IVD
- 14.8.1 SPECIALIZED SERVICES OFFERED BY CROS TO DRIVE DEMAND
15 CLINICAL TRIAL SERVICES MARKET, BY END USER
- 15.1 INTRODUCTION
- 15.2 PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.1 INCREASE IN R&D EXPENDITURE OF PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES TO DRIVE MARKET
- 15.2.2 LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.2.1 Demand for therapeutic expertise and global reach to aid outsourcing to CROs
- 15.2.3 SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES
- 15.2.3.1 Demand driven by limited internal capabilities and rising trial complexity
- 15.3 MEDICAL DEVICE COMPANIES
- 15.3.1 RISING REGULATORY EVIDENCE REQUIREMENTS AND EXPANSION OF INTEGRATED SERVICE PORTFOLIOS BY MEDTECH CROS TO DRIVE MARKET GROWTH
- 15.4 ACADEMIC INSTITUTES
- 15.4.1 EXPANDING CRO-ACADEMIC PARTNERSHIPS AND SITE NETWORKS TO DRIVE MARKET
16 CLINICAL TRIAL SERVICES MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 Presence of well-established CROs to drive market
- 16.2.2 CANADA
- 16.2.2.1 Favorable government-led initiatives and rising R&D investments to drive market
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 GERMANY
- 16.3.1.1 Growing R&D spending and favorable government policies to propel market
- 16.3.2 UK
- 16.3.2.1 Rising collaborations and improved policies to support market
- 16.3.3 FRANCE
- 16.3.3.1 Government-led support for effective drug research to drive market
- 16.3.4 ITALY
- 16.3.4.1 Government-led focus on improving clinical trial regulations to drive market
- 16.3.5 SPAIN
- 16.3.5.1 Rising R&D expenditure to boost market growth
- 16.3.6 REST OF EUROPE
- 16.3.1 GERMANY
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Low manufacturing cost and increased establishment of R&D centers to drive market
- 16.4.2 INDIA
- 16.4.2.1 Cost-efficient and innovation-driven approach to propel market
- 16.4.3 JAPAN
- 16.4.3.1 Slight decline in number of clinical trials to limit market
- 16.4.4 AUSTRALIA
- 16.4.4.1 Favorable tax incentives and cash rebates to pharmaceutical companies to support market
- 16.4.5 SOUTH KOREA
- 16.4.5.1 Favorable government initiatives for drug development to drive market
- 16.4.6 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 LATIN AMERICA
- 16.5.1 BRAZIL
- 16.5.1.1 Government-led support through improved policies in pharmaceutical R&D to drive market
- 16.5.2 MEXICO
- 16.5.2.1 Increasing investments in pharma R&D to drive market
- 16.5.3 REST OF LATIN AMERICA
- 16.5.1 BRAZIL
- 16.6 MIDDLE EAST
- 16.6.1 GCC COUNTRIES
- 16.6.1.1 Saudi Arabia
- 16.6.1.1.1 Increase in collaborations to drive market
- 16.6.1.2 UAE
- 16.6.1.2.1 Growing clinical research activities to drive market
- 16.6.1.3 Rest of GCC Countries
- 16.6.1.1 Saudi Arabia
- 16.6.2 REST OF MIDDLE EAST
- 16.6.3 AFRICA
- 16.6.3.1 Expanding pharmaceutical industry to support market growth
- 16.6.1 GCC COUNTRIES
17 COMPETITIVE LANDSCAPE
- 17.1 OVERVIEW
- 17.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023-2025
- 17.3 REVENUE ANALYSIS, 2023-2025
- 17.3.1 CLINICAL TRIAL SERVICES MARKET
- 17.4 MARKET SHARE ANALYSIS, 2025
- 17.4.1 CLINICAL TRIAL SERVICES MARKET
- 17.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.5.1 CLINICAL TRIAL SERVICES MARKET
- 17.5.2 STARS
- 17.5.3 EMERGING LEADERS
- 17.5.4 PERVASIVE PLAYERS
- 17.5.5 PARTICIPANTS
- 17.5.5.1 Company footprint: Key players, 2025
- 17.5.5.1.1 Company footprint
- 17.5.5.2 Region footprint
- 17.5.5.3 Service type footprint
- 17.5.5.4 Phase footprint
- 17.5.5.1 Company footprint: Key players, 2025
- 17.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.6.1 CLINICAL TRIAL SERVICES MARKET: STARTUPS/SMES, 2025
- 17.6.2 PROGRESSIVE COMPANIES
- 17.6.3 RESPONSIVE COMPANIES
- 17.6.4 DYNAMIC COMPANIES
- 17.6.5 STARTING BLOCKS
- 17.6.5.1 Competitive benchmarking
- 17.6.5.1.1 Detailed list of key startups/SMES
- 17.6.5.1.2 Competitive benchmarking of startups/SMEs
- 17.6.5.1 Competitive benchmarking
- 17.7 COMPANY VALUATION AND FINANCIAL METRICS
- 17.7.1 CLINICAL TRIAL SERVICES MARKET
- 17.8 BRAND/SERVICE COMPARISON
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 SERVICE LAUNCHES
- 17.9.2 DEALS
- 17.9.3 EXPANSIONS
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 IQVIA INC.
- 18.1.1.1 Business overview
- 18.1.1.2 Solutions/Services offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Service/Solution launches
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses and competitive threats
- 18.1.2 ICON PLC
- 18.1.2.1 Business overview
- 18.1.2.2 Services/Solutions offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Service launches
- 18.1.2.3.2 Deals
- 18.1.2.3.3 Expansions
- 18.1.2.4 MnM view
- 18.1.2.4.1 Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses and competitive threats
- 18.1.3 THERMO FISHER SCIENTIFIC INC.
- 18.1.3.1 Business overview
- 18.1.3.2 Services/Solutions offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product/Service launches
- 18.1.3.3.2 Deals
- 18.1.3.3.3 Expansions
- 18.1.3.4 MnM view
- 18.1.3.4.1 Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses and competitive threats
- 18.1.4 FORTREA
- 18.1.4.1 Business overview
- 18.1.4.2 Services/Solutions offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Service launches
- 18.1.4.3.2 Deals
- 18.1.4.3.3 Expansions
- 18.1.4.3.4 Other developments
- 18.1.4.4 MnM view
- 18.1.4.4.1 Right to win
- 18.1.4.4.2 Strategic choices
- 18.1.4.4.3 Weaknesses and competitive threats
- 18.1.5 SYNEOS HEALTH
- 18.1.5.1 Business overview
- 18.1.5.2 Services/Solutions offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Service launches
- 18.1.5.3.2 Deals
- 18.1.6 LABORATORY CORPORATION OF AMERICA HOLDINGS
- 18.1.6.1 Business overview
- 18.1.6.2 Services/Solutions offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Service/ Solution launches
- 18.1.6.3.2 Deals
- 18.1.6.3.3 Expansions
- 18.1.6.4 MnM view
- 18.1.6.4.1 Right to win
- 18.1.6.4.2 Strategic choices
- 18.1.6.4.3 Weaknesses and competitive threats
- 18.1.7 MEDPACE
- 18.1.7.1 Business overview
- 18.1.7.2 Services/Solutions offered
- 18.1.8 WUXI APPTEC
- 18.1.8.1 Business overview
- 18.1.8.2 Services/Solutions offered
- 18.1.8.3 Recent developments
- 18.1.8.3.1 Deals
- 18.1.8.3.2 Expansions
- 18.1.8.4 Other developments
- 18.1.9 FRONTAGE LABS
- 18.1.9.1 Business overview
- 18.1.9.2 Services/Solutions offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Deals
- 18.1.10 PHARMARON
- 18.1.10.1 Business overview
- 18.1.10.2 Services/Solutions offered
- 18.1.11 TIGERMED
- 18.1.11.1 Business overview
- 18.1.11.2 Services offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Service approvals
- 18.1.11.3.2 Deals
- 18.1.12 SGS SA
- 18.1.12.1 Business overview
- 18.1.12.2 Services/Solutions offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Deals
- 18.1.12.3.2 Expansions
- 18.1.13 EUROFINS SCIENTIFIC
- 18.1.13.1 Business overview
- 18.1.13.2 Services/Solutions offered
- 18.1.14 LINICAL
- 18.1.14.1 Business overview
- 18.1.14.2 Services/Solutions offered
- 18.1.14.3 Recent developments
- 18.1.14.4 Expansions
- 18.1.15 PAREXEL INTERNATIONAL CORPORATION
- 18.1.15.1 Business overview
- 18.1.15.2 Services/Solutions offered
- 18.1.15.3 Recent developments
- 18.1.15.3.1 Product & service launches
- 18.1.15.3.2 Deals
- 18.1.15.3.3 Expansions
- 18.1.16 PSI CRO AG
- 18.1.16.1 Business overview
- 18.1.16.2 Services/Solutions offered
- 18.1.16.3 Recent developments
- 18.1.16.3.1 Service launches
- 18.1.16.3.2 Deals
- 18.1.16.3.3 Expansions
- 18.1.17 NOVOTECH
- 18.1.17.1 Business overview
- 18.1.17.2 Services/Solutions offered
- 18.1.17.3 Recent developments
- 18.1.17.3.1 Deals
- 18.1.18 BIOAGILE
- 18.1.18.1 Business overview
- 18.1.18.2 Services/Solutions offered
- 18.1.19 ADVANCED CLINICAL
- 18.1.19.1 Business overview
- 18.1.19.2 Services/Solutions offered
- 18.1.19.3 Recent developments
- 18.1.19.3.1 Deals
- 18.1.20 FIRMA CLINICAL RESEARCH
- 18.1.20.1 Business overview
- 18.1.20.2 Services/Solutions offered
- 18.1.1 IQVIA INC.
- 18.2 OTHER PLAYERS
- 18.2.1 WORLDWIDE CLINICAL TRIALS
- 18.2.2 PROPHARMA
- 18.2.3 ALLUCENT
- 18.2.4 PREMIER RESEARCH
- 18.2.5 CAIDYA
- 18.2.6 ERGOMED GROUP
- 18.2.7 CLARIO
- 18.2.8 PRECISION MEDICINE GROUP, LLC.
- 18.2.9 EPS HOLDINGS, INC.
- 18.2.10 GUIRES INC. (PEPGRA)
- 18.2.11 KCR S.A.
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH APPROACH
- 19.1.1 SECONDARY DATA
- 19.1.1.1 Key sources of secondary data
- 19.1.1.2 Key objectives of secondary research
- 19.1.2 PRIMARY DATA
- 19.1.2.1 Breakdown of primaries
- 19.1.2.2 Key objectives of primary research
- 19.1.1 SECONDARY DATA
- 19.2 MARKET ESTIMATION METHODOLOGY
- 19.2.1 COMPANY REVENUE ANALYSIS (BOTTOM-UP APPROACH)
- 19.2.2 MNM REPOSITORY ANALYSIS AND PRIMARY RESEARCH
- 19.2.3 SEGMENTAL MARKET ASSESSMENT (TOP-DOWN APPROACH)
- 19.3 GROWTH RATE PROJECTIONS
- 19.4 DATA TRIANGULATION
- 19.5 RESEARCH ASSUMPTIONS
- 19.6 RESEARCH LIMITATIONS
- 19.7 RISK ANALYSIS
20 APPENDIX
- 20.1 DISCUSSION GUIDE
- 20.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.3 CUSTOMIZATION OPTIONS
- 20.4 RELATED REPORTS
- 20.5 AUTHOR DETAILS
List of Tables
- TABLE 1 CLINICAL TRIAL SERVICES MARKET: IMPACT ANALYSIS
- TABLE 2 INDICATIVE PRICING RANGE, BY SERVICE TYPE, 2025
- TABLE 3 INDICATIVE PRICING ANALYSIS, BY PHASE, 2025
- TABLE 4 INDICATIVE PRICING ANALYSIS (PER STUDY), BY REGION, 2025 (USD MILLION)
- TABLE 5 CLINICAL TRIAL SERVICES MARKET: ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 6 DETAILED LIST OF KEY CONFERENCES & EVENTS, 2026-2027
- TABLE 7 PORTER'S FIVE FORCES ANALYSIS: CLINICAL TRIAL SERVICES MARKET
- TABLE 8 REGULATORY GUIDANCE, BY PHASE
- TABLE 9 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 10 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 11 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 12 REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 13 CLINICAL TRIAL AUTHORIZATION SCENARIO
- TABLE 14 COUNTRY-WISE REGULATORY SCENARIO FOR CLINICAL TRIAL SPONSORS AND CROS
- TABLE 15 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF CLINICAL TRIAL SERVICES, BY MODALITY
- TABLE 16 BUYING CRITERIA FOR CLINICAL TRIAL SERVICES ACROSS END USERS
- TABLE 17 CLINICAL TRIAL SERVICES: ADOPTION BARRIER & INTERNAL FRICTION
- TABLE 18 CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 19 CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 20 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 21 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 22 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 23 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 24 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 25 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL MANAGEMENT & MONITORING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 26 EXAMPLES OF LABORATORY SERVICES OFFERED BY PROMINENT PLAYERS
- TABLE 27 CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 28 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 29 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 30 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 31 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 32 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 33 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 34 CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 35 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 36 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 37 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 38 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 39 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 40 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR ANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 41 CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 42 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 43 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 44 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 45 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 46 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 47 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOANALYTICAL TESTING SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 48 EXAMPLES OF DATA MANAGEMENT SERVICES OFFERED BY PROMINENT PLAYERS
- TABLE 49 CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 50 CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 51 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 52 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 53 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 54 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 55 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 56 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 57 CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 58 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 59 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 60 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 61 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 62 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 63 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOSTATISTICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 64 CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 65 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 66 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 67 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 68 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 69 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 70 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OTHER DATA MANAGEMENT SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 71 CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 72 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 73 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 74 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 75 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 76 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 77 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CLINICAL TRIAL SUPPLY & LOGISTICS SERVICES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 78 CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 79 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 80 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 81 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 82 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 83 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 84 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CONSULTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 85 CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY REGION, 2024-2031 (USD MILLION)
- TABLE 86 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 87 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 88 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 89 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 90 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 91 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PATIENT RECRUITMENT & RETENTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 92 CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY REGION, 2024-2031 (USD MILLION)
- TABLE 93 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 94 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 95 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 96 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 97 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 98 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL WRITING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 99 CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY REGION, 2024-2031 (USD MILLION)
- TABLE 100 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 101 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 102 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 103 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 104 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 105 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR SAFETY & PHARMACOVIGILANCE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 106 CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 107 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 108 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 109 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 110 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 111 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 112 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR SITE CONTRACTS & PAYMENTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 113 CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 114 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 115 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 116 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 117 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 118 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 119 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OTHER SERVICE TYPES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 120 CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 121 CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY REGION, 2024-2031 (USD MILLION)
- TABLE 122 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 123 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 124 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 125 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 126 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 127 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHASE III, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 128 CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY REGION, 2024-2031 (USD MILLION)
- TABLE 129 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 130 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 131 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 132 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 133 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 134 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHASE II, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 135 CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY REGION, 2024-2031 (USD MILLION)
- TABLE 136 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 137 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 138 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 139 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 140 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 141 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHASE I, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 142 CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY REGION, 2024-2031 (USD MILLION)
- TABLE 143 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 144 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 145 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 146 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 147 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 148 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHASE IV, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 149 CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 150 CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY REGION, 2024-2031 (USD MILLION)
- TABLE 151 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 152 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 153 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 154 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 155 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 156 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR FULL-SERVICE OUTSOURCING (FSO) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 157 CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY REGION, 2024-2031 (USD MILLION)
- TABLE 158 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 159 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 160 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 161 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 162 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 163 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR FUNCTIONAL SERVICE PROVIDER (FSP) MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 164 CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY REGION, 2024-2031 (USD MILLION)
- TABLE 165 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 166 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 167 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 168 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 169 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 170 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR HYBRID MODEL, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 171 CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 172 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN, BY REGION, 2024-2031 (USD MILLION)
- TABLE 173 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR NORTH AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 174 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR EUROPE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 175 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR ASIA PACIFIC, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 176 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR LATIN AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 177 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR MIDDLE EAST, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 178 CLINICAL TRIAL SERVICES MARKET FOR INTERVENTIONAL STUDY DESIGN FOR GCC COUNTRIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 179 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN, BY REGION, 2024-2031 (USD MILLION)
- TABLE 180 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR NORTH AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 181 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR EUROPE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 182 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR ASIA PACIFIC, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 183 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR LATIN AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 184 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR MIDDLE EAST, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 185 CLINICAL TRIAL SERVICES MARKET FOR OBSERVATIONAL STUDY DESIGN FOR GCC COUNTRIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 186 CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 187 NUMBER OF NEW CANCER CASES, BY TYPE, 2022 VS. 2040
- TABLE 188 CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 189 CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 190 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 191 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 192 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 193 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 194 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 195 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 196 CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY REGION, 2024-2031 (USD MILLION)
- TABLE 197 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 198 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 199 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 200 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 201 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 202 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BREAST CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 203 CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY REGION, 2024-2031 (USD MILLION)
- TABLE 204 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 205 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 206 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 207 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 208 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 209 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR LUNG CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 210 CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY REGION, 2024-2031 (USD MILLION)
- TABLE 211 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 212 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 213 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 214 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 215 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 216 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR COLORECTAL CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 217 CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY REGION, 2024-2031 (USD MILLION)
- TABLE 218 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 219 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 220 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 221 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 222 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 223 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PROSTATE CANCER , BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 224 CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY REGION, 2024-2031 (USD MILLION)
- TABLE 225 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 226 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 227 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 228 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 229 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 230 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OTHER CANCER, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 231 CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 232 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 233 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 234 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 235 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 236 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 237 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR NEUROLOGY , BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 238 CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 239 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 240 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 241 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 242 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 243 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 244 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR RESPIRATORY DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 245 CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 246 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 247 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 248 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 249 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 250 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 251 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR METABOLIC DISORDERS/ENDOCRINOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 252 CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 253 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 254 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 255 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 256 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 257 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 258 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CARDIOVASCULAR SYSTEM DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 259 CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 260 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 261 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 262 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 263 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 264 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 265 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR DERMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 266 CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 267 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 268 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 269 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 270 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 271 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 272 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR GASTROINTESTINAL DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 273 CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 274 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 275 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 276 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 277 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 278 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 279 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR IMMUNOLOGICAL DISORDERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 280 CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 281 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 282 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 283 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 284 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 285 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 286 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR INFECTIOUS DISEASES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 287 CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 288 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 289 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 290 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 291 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 292 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 293 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PSYCHIATRY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 294 CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 295 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 296 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 297 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 298 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 299 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 300 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OPHTHALMOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 301 CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 302 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 303 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 304 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 305 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 306 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 307 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR HEMATOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 308 CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY REGION, 2024-2031 (USD MILLION)
- TABLE 309 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 310 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 311 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 312 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 313 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 314 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR GENITOURINARY & WOMEN'S HEALTH, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 315 CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 316 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 317 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 318 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 319 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 320 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 321 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC AREAS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 322 CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 323 CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 324 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 325 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 326 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 327 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 328 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 329 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR SMALL MOLECULES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 330 CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 331 CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 332 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 333 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 334 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 335 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 336 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 337 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 338 CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 339 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 340 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 341 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 342 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 343 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 344 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR MONOCLONAL ANTIBODY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 345 CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY REGION, 2024-2031 (USD MILLION)
- TABLE 346 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 347 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 348 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 349 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 350 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 351 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR CELL & GENE THERAPY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 352 CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 353 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 354 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 355 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 356 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 357 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 358 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR OTHER THERAPEUTIC PRODUCTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 359 CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY REGION, 2024-2031 (USD MILLION)
- TABLE 360 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 361 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 362 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 363 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 364 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 365 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOSIMILARS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 366 CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY REGION, 2024-2031 (USD MILLION)
- TABLE 367 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 368 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 369 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 370 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 371 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 372 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICES & IVD, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 373 CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 374 CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 375 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 376 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 377 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 378 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 379 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 380 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 381 CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 382 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 383 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 384 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 385 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 386 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 387 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR LARGE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 388 CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 389 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 390 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 391 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 392 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 393 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 394 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR SMALL & MID-SIZE PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 395 CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICE COMPANIES, BY REGION, 2024-2031 (USD MILLION)
- TABLE 396 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR MEDICAL DEVICE COMPANIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 397 MEDICAL DEVICE COMPANIES: CLINICAL TRIAL SERVICES MARKET FOR EUROPE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 398 MEDICAL DEVICE COMPANIES: CLINICAL TRIAL SERVICES MARKET FOR ASIA PACIFIC, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 399 MEDICAL DEVICE COMPANIES: CLINICAL TRIAL SERVICES MARKET FOR LATIN AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 400 MEDICAL DEVICE COMPANIES: CLINICAL TRIAL SERVICES MARKET FOR MIDDLE EAST, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 401 MEDICAL DEVICE COMPANIES: CLINICAL TRIAL SERVICES MARKET FOR GCC COUNTRIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 402 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 403 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR NORTH AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 404 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR EUROPE, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 405 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR ASIA PACIFIC, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 406 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR LATIN AMERICA, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 407 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR MIDDLE EAST, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 408 ACADEMIC INSTITUTES: CLINICAL TRIAL SERVICES MARKET FOR GCC COUNTRIES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 409 CLINICAL TRIAL SERVICES MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 410 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 411 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 412 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 413 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 414 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 415 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 416 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 417 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 418 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 419 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 420 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 421 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 422 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 423 US: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 424 US: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 425 US: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 426 US: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 427 US: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 428 US: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 429 US: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 430 US: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 431 US: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 432 US: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 433 US: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 434 US: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 435 CANADA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 436 CANADA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 437 CANADA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 438 CANADA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 439 CANADA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 440 CANADA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 441 CANADA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 442 CANADA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 443 CANADA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 444 CANADA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 445 CANADA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 446 CANADA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 447 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 448 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 449 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 450 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 451 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 452 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 453 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 454 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 455 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 456 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 457 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 458 EUROPE: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 459 EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 460 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 461 GERMANY: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 462 GERMANY: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 463 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 464 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 465 GERMANY: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 466 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 467 GERMANY: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 468 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 469 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 470 GERMANY: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 471 GERMANY: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 472 UK: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 473 UK: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 474 UK: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 475 UK: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 476 UK: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 477 UK: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 478 UK: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 479 UK: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 480 UK: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 481 UK: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 482 UK: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 483 UK: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 484 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 485 FRANCE: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 486 FRANCE: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 487 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 488 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 489 FRANCE: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 490 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 491 FRANCE: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 492 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 493 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 494 FRANCE: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 495 FRANCE: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 496 ITALY: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 497 ITALY: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 498 ITALY: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 499 ITALY: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 500 ITALY: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 501 ITALY: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 502 ITALY: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 503 ITALY: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 504 ITALY: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 505 ITALY: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 506 ITALY: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 507 ITALY: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 508 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 509 SPAIN: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 510 SPAIN: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 511 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 512 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 513 SPAIN: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 514 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 515 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 516 SPAIN: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 517 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 518 SPAIN: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 519 SPAIN: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 520 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 521 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 522 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 523 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 524 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 525 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 526 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 527 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 528 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 529 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 530 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 531 REST OF EUROPE: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 532 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 533 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 534 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 535 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 536 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 537 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 538 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 539 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 540 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 541 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 542 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 543 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 544 ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 545 CHINA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 546 CHINA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 547 CHINA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 548 CHINA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 549 CHINA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 550 CHINA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 551 CHINA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 552 CHINA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 553 CHINA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 554 CHINA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 555 CHINA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 556 CHINA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 557 INDIA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 558 INDIA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 559 INDIA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 560 INDIA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 561 INDIA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 562 INDIA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 563 INDIA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 564 INDIA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 565 INDIA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 566 INDIA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 567 INDIA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 568 INDIA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 569 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 570 JAPAN: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 571 JAPAN: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 572 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 573 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 574 JAPAN: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 575 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 576 JAPAN: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 577 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 578 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 579 JAPAN: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 580 JAPAN: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 581 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 582 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 583 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 584 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 585 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 586 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 587 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 588 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 589 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 590 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 591 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 592 AUSTRALIA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 593 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 594 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 595 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 596 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 597 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 598 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 599 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 600 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 601 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 602 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 603 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 604 SOUTH KOREA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 605 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 606 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 607 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 608 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 609 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 610 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 611 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 612 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 613 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 614 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 615 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 616 REST OF ASIA PACIFIC: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 617 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 618 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 619 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 620 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 621 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 622 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 623 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 624 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 625 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 626 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 627 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 628 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 629 LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 630 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 631 BRAZIL: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 632 BRAZIL: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 633 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 634 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 635 BRAZIL: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 636 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 637 BRAZIL: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 638 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 639 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 640 BRAZIL: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 641 BRAZIL: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 642 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 643 MEXICO: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 644 MEXICO: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 645 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 646 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 647 MEXICO: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 648 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 649 MEXICO: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 650 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 651 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 652 MEXICO: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 653 MEXICO: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 654 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 655 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 656 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 657 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 658 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 659 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 660 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 661 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 662 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 663 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 664 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 665 REST OF LATIN AMERICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 666 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 667 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 668 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 669 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 670 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 671 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 672 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 673 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 674 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 675 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 676 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 677 MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 678 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 679 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 680 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 681 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 682 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 683 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 684 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 685 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 686 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 687 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 688 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 689 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 690 GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 691 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 692 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 693 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 694 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 695 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 696 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 697 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 698 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 699 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 700 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 701 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 702 SAUDI ARABIA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 703 UAE: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 704 UAE: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 705 UAE: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 706 UAE: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 707 UAE: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 708 UAE: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 709 UAE: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 710 UAE: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 711 UAE: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 712 UAE: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 713 UAE: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 714 UAE: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 715 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 716 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 717 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 718 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 719 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 720 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 721 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 722 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 723 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 724 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 725 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 726 REST OF GCC COUNTRIES: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 727 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 728 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 729 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 730 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 731 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 732 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 733 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 734 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 735 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 736 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 737 REST OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 738 RETS OF MIDDLE EAST: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 739 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 740 AFRICA: CLINICAL TRIAL SERVICES MARKET FOR LABORATORY SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 741 AFRICA: CLINICAL TRIAL SERVICES MARKET FOR DATA MANAGEMENT SERVICES, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 742 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY PHASE, 2024-2031 (USD MILLION)
- TABLE 743 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY THERAPEUTIC AREA, 2024-2031 (USD MILLION)
- TABLE 744 AFRICA: CLINICAL TRIAL SERVICES MARKET FOR ONCOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 745 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 746 AFRICA: CLINICAL TRIAL SERVICES MARKET FOR BIOLOGICS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 747 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY DELIVERY MODEL, 2024-2031 (USD MILLION)
- TABLE 748 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY STUDY DESIGN, 2024-2031 (USD MILLION)
- TABLE 749 AFRICA: CLINICAL TRIAL SERVICES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 750 AFRICA: CLINICAL TRIAL SERVICES MARKET FOR PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 751 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN CLINICAL TRIAL SERVICES MARKET, JANUARY 2023-JULY 2026
- TABLE 752 CLINICAL TRIAL SERVICES MARKET: DEGREE OF COMPETITION
- TABLE 753 CLINICAL TRIAL SERVICES MARKET: REGION FOOTPRINT
- TABLE 754 CLINICAL TRIAL SERVICES MARKET: SERVICE TYPE FOOTPRINT
- TABLE 755 CLINICAL TRIAL SERVICES MARKET: PHASE FOOTPRINT
- TABLE 756 CLINICAL TRIAL SERVICES MARKET: DETAILED LIST OF KEY STARTUP/SMES
- TABLE 757 CLINICAL TRIAL SERVICES MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 758 CLINICAL TRIAL SERVICES MARKET: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 759 CLINICAL TRIAL SERVICES MARKET: DEALS, JANUARY 2023-JULY 2026
- TABLE 760 CLINICAL TRIAL SERVICES MARKET: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 761 IQVIA INC.: COMPANY OVERVIEW
- TABLE 762 IQVIA INC.: SOLUTIONS/SERVICES OFFERED
- TABLE 763 IQVIA INC.: SERVICE/ SOLUTION LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 764 IQVIA INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 765 ICON PLC: COMPANY OVERVIEW
- TABLE 766 ICON PLC.: SERVICES/SOLUTIONS OFFERED
- TABLE 767 ICON PLC.: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 768 ICON PLC: DEALS, JANUARY 2023-JULY 2026
- TABLE 769 ICON PLC.: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 770 THERMO FISHER SCIENTIFIC INC.: COMPANY OVERVIEW
- TABLE 771 THERMO FISHER SCIENTIFIC INC.: SERVICES/SOLUTIONS OFFERED
- TABLE 772 THERMO FISHER SCIENTIFIC, INC.: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 773 THERMO FISHER SCIENTIFIC, INC.: DEALS, JANUARY 2021-APRIL 2026
- TABLE 774 THERMO FISHER SCIENTIFIC, INC.: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 775 FORTREA: COMPANY OVERVIEW
- TABLE 776 FORTREA, INC.: SERVICES/SOLUTIONS OFFERED
- TABLE 777 FORTREA, INC.: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 778 FORTREA, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 779 FORTREA, INC.: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 780 FORTREA, INC.: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 781 SYNEOS HEALTH: COMPANY OVERVIEW
- TABLE 782 SYNEOS HEALTH: SERVICES/SOLUTIONS OFFERED
- TABLE 783 SYNEOS HEALTH: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 784 SYNEOS HEALTH: DEALS, JANUARY 2023-JULY 2026
- TABLE 785 LABORATORY CORPORATION OF AMERICA HOLDINGS: COMPANY OVERVIEW
- TABLE 786 LABORATORY CORPORATION OF AMERICA HOLDINGS: SERVICES/ SOLUTIONS OFFERED
- TABLE 787 LABORATORY CORPORATION OF AMERICA HOLDINGS: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 788 LABORATORY CORPORATION OF AMERICA HOLDINGS: DEALS, JANUARY 2023-JULY 2026
- TABLE 789 LABORATORY CORPORATION OF AMERICA HOLDINGS: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 790 MEDPACE: COMPANY OVERVIEW
- TABLE 791 MEDPACE: SERVICES/SOLUTIONS OFFERED
- TABLE 792 WUXI APPTEC: COMPANY OVERVIEW
- TABLE 793 WUXI APPTEC: SERVICES/SOLUTIONS OFFERED
- TABLE 794 WUXI APPTEC: DEALS, JANUARY 2023-JULY 2026
- TABLE 795 WUXI APPTEC: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 796 WUXI APPTEC: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 797 FRONTAGE LABS: COMPANY OVERVIEW
- TABLE 798 FRONTAGE LABS: SERVICES/SOLUTIONS OFFERED
- TABLE 799 FRONTAGE LABS: DEALS, JANUARY 2023-JULY 2026
- TABLE 800 PHARMARON: COMPANY OVERVIEW
- TABLE 801 PHARMARON: SERVICES/SOLUTIONS OFFERED
- TABLE 802 TIGERMED: COMPANY OVERVIEW
- TABLE 803 TIGERMED: SERVICES OFFERED
- TABLE 804 TIGERMED: SERVICE APPROVALS, JANUARY 2023-JULY 2026
- TABLE 805 TIGERMED: DEALS, JANUARY 2023-JULY 2026
- TABLE 806 SGS SA: COMPANY OVERVIEW
- TABLE 807 SGS SA: SERVICES/SOLUTIONS OFFERED
- TABLE 808 SGS SA: DEALS, JANUARY 2023-JULY 2026
- TABLE 809 SGS SA: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 810 EUROFINS SCIENTIFIC: COMPANY OVERVIEW
- TABLE 811 EUROFINS SCIENTIFIC: SERVICES/SOLUTIONS OFFERED
- TABLE 812 LINICAL: COMPANY OVERVIEW
- TABLE 813 LINICAL: SERVICES/SOLUTIONS OFFERED
- TABLE 814 LINICAL: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 815 PAREXEL INTERNATIONAL CORPORATION: COMPANY OVERVIEW
- TABLE 816 PAREXEL INTERNATIONAL CORPORATION: SERVICES/SOLUTIONS OFFERED
- TABLE 817 PAREXEL INTERNATIONAL CORPORATION: PRODUCT & SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 818 PAREXEL INTERNATIONAL CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 819 PAREXEL INTERNATIONAL CORPORATION: EXPANSIONS, JANUARY 2021-JANUARY 2025
- TABLE 820 PSI CRO AG: COMPANY OVERVIEW
- TABLE 821 PSI CRO AG: SERVICES/SOLUTIONS OFFERED
- TABLE 822 PSI CRO AG: SERVICE LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 823 PSI CRO AG: DEALS, JANUARY 2023-JULY 2026
- TABLE 824 PSI CRO AG: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 825 NOVOTECH: COMPANY OVERVIEW
- TABLE 826 NOVOTECH: SERVICES/SOLUTIONS OFFERED
- TABLE 827 NOVOTECH HEALTH HOLDINGS: DEALS, JANUARY 2023-JULY 2026
- TABLE 828 BIOAGILE: COMPANY OVERVIEW
- TABLE 829 BIOAGILE: SERVICES/SOLUTIONS OFFERED
- TABLE 830 ADVANCED CLINICAL: COMPANY OVERVIEW
- TABLE 831 ADVANCED CLINICAL: SERVICES/SOLUTIONS OFFERED
- TABLE 832 ADVANCED CLINICAL: DEALS, JANUARY 2023-JULY 2026
- TABLE 833 FIRMA CLINICAL RESEARCH: COMPANY OVERVIEW
- TABLE 834 FIRMA CLINICAL RESEARCH: SERVICES/SOLUTIONS OFFERED
- TABLE 835 WORLDWIDE CLINICAL TRIALS: COMPANY OVERVIEW
- TABLE 836 PROPHARMA: COMPANY OVERVIEW
- TABLE 837 ALLUCENT: COMPANY OVERVIEW
- TABLE 838 PREMIER RESEARCH: COMPANY OVERVIEW
- TABLE 839 CAIDYA: COMPANY OVERVIEW
- TABLE 840 ERGOMED GROUP: COMPANY OVERVIEW
- TABLE 841 CLARIO: COMPANY OVERVIEW
- TABLE 842 PRECISION MEDICINE GROUP, LLC: COMPANY OVERVIEW
- TABLE 843 EPS HOLDINGS, INC.: COMPANY OVERVIEW
- TABLE 844 GUIRES INC. (PEPGRA): COMPANY OVERVIEW
- TABLE 845 KCR S.A.: COMPANY OVERVIEW
- TABLE 846 IMPACT ANALYSIS OF SUPPLY- AND DEMAND-SIDE FACTORS
- TABLE 847 CLINICAL TRIAL SERVICES MARKET: RISK ANALYSIS
List of Figures
- FIGURE 1 CLINICAL TRIAL SERVICES MARKET SEGMENTATION
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 GLOBAL CLINICAL TRIAL SERVICES MARKET, 2024-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN CLINICAL TRIAL SERVICES MARKET, 2023-2025
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF CLINICAL TRIAL SERVICES MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN CLINICAL TRIAL SERVICES MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN CLINICAL TRIAL SERVICES MARKET, IN TERMS OF VALUE, DURING FORECAST PERIOD
- FIGURE 8 INCREASING SIZE OF CLINICAL DEVELOPMENT PIPELINE TO PROPEL MARKET GROWTH
- FIGURE 9 US AND SMALL MOLECULES SEGMENT COMMANDED LARGEST MARKET SHARES IN 2025
- FIGURE 10 CHINA TO REGISTER HIGHER CAGR DURING FORECAST PERIOD
- FIGURE 11 CLINICAL TRIAL SERVICES MARKET: DRIVERS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 ACTIVE PHARMACEUTICAL PIPELINE, 2015-2026
- FIGURE 13 REVENUE SHIFT AND NEW POCKETS FOR CLINICAL TRIAL SERVICE PROVIDERS
- FIGURE 14 INDICATIVE PRICING ANALYSIS, BY REGION, 2025
- FIGURE 15 CLINICAL TRIAL SERVICES MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 CLINICAL TRIAL SERVICES MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 PORTER'S FIVE FORCES ANALYSIS: CLINICAL TRIAL SERVICES MARKET
- FIGURE 18 AI USE CASES
- FIGURE 19 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF CLINICAL TRIAL SERVICES, BY MODALITY
- FIGURE 20 KEY BUYING CRITERIA FOR CLINICAL TRIAL SERVICES ACROSS END USERS
- FIGURE 21 DRUGS IN PIPELINE, BY DEVELOPMENT PHASE, 2023-2025
- FIGURE 22 ONCOLOGY TRIALS SHARE OF THE DEVELOPMENT PIPELINE, 2014-2025
- FIGURE 23 ESTIMATED NUMBER OF INDIVIDUALS WITH DIABETES, 2000-2045 (MILLION)
- FIGURE 24 NORTH AMERICA: CLINICAL TRIAL SERVICES MARKET SNAPSHOT
- FIGURE 25 ASIA PACIFIC: CLINICAL TRIALS MARKET SNAPSHOT
- FIGURE 26 CLINICAL TRIAL SERVICES MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2023-2025 (USD BILLION)
- FIGURE 27 CLINICAL TRIAL SERVICES MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025
- FIGURE 28 CLINICAL TRIAL SERVICES MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 29 CLINICAL TRIAL SERVICES MARKET: COMPANY FOOTPRINT
- FIGURE 30 CLINICAL TRIAL SERVICES MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2024
- FIGURE 31 CLINICAL TRIAL SERVICES MARKET: YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS, 2025
- FIGURE 32 CLINICAL TRIAL SERVICES MARKET: EV/EBITDA OF KEY VENDORS, 2025
- FIGURE 33 CLINICAL TRIAL SERVICES MARKET: BRAND/SERVICE COMPARISON
- FIGURE 34 IQVIA INC.: COMPANY SNAPSHOT (2025)
- FIGURE 35 ICON PLC: COMPANY SNAPSHOT (2025)
- FIGURE 36 THERMO FISHER SCIENTIFIC INC.: COMPANY SNAPSHOT (2023)
- FIGURE 37 FORTREA: COMPANY SNAPSHOT (2025)
- FIGURE 38 LABORATORY CORPORATION OF AMERICA HOLDINGS: COMPANY SNAPSHOT (2025)
- FIGURE 39 MEDPACE: COMPANY SNAPSHOT (2025)
- FIGURE 40 WUXI APPTEC: COMPANY SNAPSHOT (2025)
- FIGURE 41 FRONTAGE LABS: COMPANY SNAPSHOT (2024)
- FIGURE 42 PHARMARON: COMPANY SNAPSHOT (2025)
- FIGURE 43 TIGERMED: COMPANY SNAPSHOT (2025)
- FIGURE 44 SGS SA: COMPANY SNAPSHOT (2025)
- FIGURE 45 EUROFINS SCIENTIFIC: COMPANY SNAPSHOT (2025)
- FIGURE 46 LINICAL: COMPANY SNAPSHOT (2025)
- FIGURE 47 CLINICAL TRIAL SERVICES MARKET: RESEARCH DESIGN
- FIGURE 48 CLINICAL TRIAL SERVICES MARKET: BREAKDOWN OF PRIMARIES (DEMAND- AND SUPPLY-SIDE PARTICIPANTS)
- FIGURE 49 GLOBAL CLINICAL TRIAL SERVICES MARKET SIZE ESTIMATION (SUPPLY-SIDE ANALYSIS), 2025
- FIGURE 50 CLINICAL TRIAL SERVICES MARKET ESTIMATION: APPROACH 1 (COMPANY REVENUE ANALYSIS-BASED ESTIMATION), 2025
- FIGURE 51 ILLUSTRATIVE EXAMPLE OF IQVIA INC.: REVENUE SHARE ANALYSIS, 2025
- FIGURE 52 CLINICAL TRIAL SERVICES MARKET SIZE VALIDATION FROM PRIMARY SOURCES
- FIGURE 53 TOP-DOWN APPROACH
- FIGURE 54 GLOBAL CLINICAL TRIAL SERVICES MARKET: CAGR PROJECTIONS, 2026-2031
- FIGURE 55 CLINICAL TRIAL SERVICES MARKET: DATA TRIANGULATION METHODOLOGY

 臨床實驗市場分析及預測(至2035年):依類型、產品、服務、技術、組件、應用、部署、最終使用者、模式及階段分類
 臨床試驗機構管理機構市場:全球預測,2026-2032年
 全球卒中臨床試驗趨勢:發展現況與分析(2026 年)
 臨床試驗服務市場規模、佔有率和成長分析:按服務類型、階段、研究設計、應用、最終用戶、交付模式和地區分類-2026-2033年產業預測臨床研究服務市場:依服務類型、臨床試驗階段、治療領域及最終使用者分類-2026-2032年全球市場預測臨床試驗市場:2026-2032年全球市場預測(依服務、研究設計、臨床階段、服務模式、治療領域及申辦方分類)
 臨床階段生物技術市場規模、佔有率和成長分析:按臨床階段、治療領域、分子類型、公司類型、最終用戶、資金來源和地區分類-2026-2033年產業預測
 2026年全球臨床試驗市場報告
 人工智慧平台憂鬱症篩檢市場預測至2034年——全球篩檢方法、交付模式、經營模式、技術堆疊、最終用戶和區域分析
 臨床試驗機構管理組織市場 - 全球產業規模、佔有率、趨勢、機會、預測:臨床試驗服務、治療領域、階段、地區和競爭格局,2021-2031年