

 |
市場調查報告書
商品編碼
2134055
全球醫療設備市場(2008-2031年):按類型(體外診斷、心血管、診斷影像、眼科、內視鏡、整形外科、糖尿病護理、創傷護理、腎臟和透析、呼吸護理)和地區分類Medical Devices Market Size By Type (In Vitro Diagnostic Devices, Cardiovascular, Imaging, Ophthalmology, Endoscopy, Orthopedic, Diabetes Care, Wound Care Devices, Kidney/Dialysis Devices, Respiratory Care) and Region - Global Forecast to 2031 |
||||||

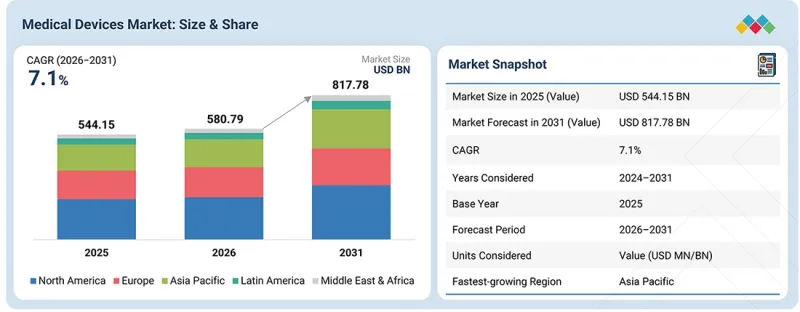
全球醫療設備市場預計將從 2026 年的 5,807.9 億美元成長到 2031 年的 8,177.8 億美元,複合年成長率為 7.1%。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 單元 | 金額(美元) |
| 部分 | 類型/區域 |
| 目標區域 | 北美、歐洲、亞太地區、拉丁美洲、中東和非洲(海灣合作理事會國家及其他中東和非洲國家) |
醫療設備市場的成長主要受慢性病盛行率上升和全球人口老化加速的驅動,這持續推動對診斷、心血管、整形外科、眼科及其他醫療設備的需求。然而,心血管系統、整形外科植入和診斷設備等先進醫療設備的高昂成本是其普及應用的主要障礙,尤其是在醫療預算有限的開發中國家。此外,市場還面臨著許多挑戰,例如嚴格的法規結構、冗長的產品核可流程以及能夠操作先進醫療技術的熟練醫護人員短缺,這些都可能延緩產品的上市和臨床實用化。儘管存在這些障礙,新興經濟體醫療基礎設施的快速發展仍帶來了巨大的成長機會。對醫院、門診手術中心、診斷實驗室和數位醫療系統的投資增加,以及醫療保險覆蓋範圍的擴大,正在改善人們獲得先進醫療技術的途徑,使主要製造商能夠拓展全球企業發展並增強市場的長期成長。
“按產品類型分類,預計到 2025 年,心血管器械領域將佔據第二大市場佔有率。”
這主要歸因於心血管疾病(CVD)在全球日益加重的負擔,以及對先進診斷和介入技術需求的不斷成長。根據世界衛生組織(WHO)估計,2022年全球將有1,980萬人死於心血管疾病,約佔全球死亡總數的32%。此外,根據美國疾病管制與預防中心(CDC)預測,2023年美國將有919,032人死於心血管疾病。如此沉重的疾病負擔促使心臟節律管理裝置、冠狀動脈支架、心臟瓣膜、導管和血管介入系統的應用顯著擴展。此外,老年人口的成長,以及高血壓、糖尿病和肥胖症的盛行率上升,也推動了對心血管器械的需求。人們對微創心血管治療的日益青睞以及技術的不斷進步也促進了需求的成長。因此,心血管器材領域在全球醫療設備市場中持續佔有重要地位。
“在預測期內,美國有望成為北美市場中複合年成長率最高的國家。”
醫療設備市場分為五大區域:北美、歐洲、亞太、拉丁美洲以及中東和非洲。其中,北美將在2025年之前主導全球醫療設備市場。北美市場又分為美國和加拿大。在這兩個區域內,美國將在2025年之前佔據北美市場最大的佔有率。這主要歸因於慢性病高發生率、先進的醫療基礎設施、高額的醫療費用支出以及大型醫療設備製造商的強大影響力。根據美國疾病管制與預防中心(CDC)的數據,2022年有371,506人死於冠狀動脈心臟病,這是最常見的心臟病。 CDC在2024年6月也報告稱,美國約有5,300萬成年人患有關節炎。同時,CDC在2026年發布的數據估計,超過十分之一的成年人(3,700萬人)患有慢性腎臟病(CKD)。沉重的疾病負擔推動了對心血管、整形外科、診斷和腎臟護理醫療設備的持續需求。此外,美國受益於先進醫療技術的快速普及、優惠的醫保報銷政策、強大的研發投入以及眾多大型醫療設備公司位置設於此,所有這些因素都支持了產品的持續創新,並鞏固了美國在區域醫療設備市場的領先地位。
本報告考察了全球醫療設備市場,提供了市場概述、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 體外診斷設備市場
- 心血管設備市場
- 影像設備市場
- 整形外科器材市場
- 眼科設備市場
- 內視鏡設備市場
- 糖尿病治療設備市場
- 傷口護理設備市場
- 腎臟/透析設備市場
- 呼吸護理設備市場
- 未滿足的需求和閒置頻段
- 與相關市場和不同產業相關的跨領域機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 宏觀經濟展望
- GDP趨勢與預測
- 微創手術(MIS)產業的發展趨勢
- 手術機器人產業的發展趨勢
- 供應鏈分析
- 價值鏈分析
- 生態系分析
- 價格分析
- 貿易分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 2025年美國關稅對醫療設備市場的影響
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 主要新興技術
- 機器人輔助與電腦輔助干預
- 照護現場(POC)和微型診斷技術
- 互補技術
- 數位醫療物聯網(IOMT)和雲端連接
- 技術/產品藍圖
- 短期(2025-2027 年)| 基礎設施建設和初步商業化
- 中期計劃(2027-2030 年)| 擴張與標準化
- 長期(2030-2035年及以後)|大規模商業化與顛覆性變革
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對醫療設備市場的影響
第7章永續性和監管情勢
- 當地法規和合規性
- 對永續性的承諾
- 對永續性和監管政策舉措的影響
- 認證、標籤檢視、環境標準
- 報銷分析
第8章:顧客趨勢與購買行為
- 決策流程
- 相關人員及購買評估標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第9章:醫療設備市場:按類型分類
- 體外診斷設備
- 心血管設備
- 傷口護理設備
- 呼吸照護設備
- 整形外科器械
- 腎臟/透析機
- 糖尿病護理設備
- 內視鏡設備
- 眼科醫療設備
- 影像設備
- 其他
第10章:醫療設備市場:依地區分類
- 北美洲
- 宏觀經濟展望
- 美國
- 加拿大
- 歐洲
- 宏觀經濟展望
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他
- 亞太地區
- 宏觀經濟展望
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他
- 拉丁美洲
- 宏觀經濟展望
- 巴西
- 墨西哥
- 其他
- 中東和非洲
- 宏觀經濟展望
- 海灣合作理事會國家
- 其他
第11章 競爭格局
- 主要參與企業的策略/優勢
- 收入分析
- 市佔率分析
- 企業估值矩陣:主要公司
- 公司估值矩陣:新創企業/中小企業
- 企業估值和財務指標
- 品牌/產品對比
- 競爭格局
第12章:公司簡介
- 大公司
- MEDTRONIC PLC
- JOHNSON & JOHNSON
- ABBOTT
- KONINKLIJKE PHILIPS NV
- SIEMENS HEALTHINEERS AG
- STRYKER CORPORATION
- B. BRAUN SE
- SMITH & NEPHEW
- BOSTON SCIENTIFIC CORPORATION
- F. HOFFMANN-LA ROCHE LTD.
- 其他公司
- BECTON, DICKINSON AND COMPANY
- BAXTER INTERNATIONAL, INC.
- ZIMMER BIOMET HOLDINGS, INC.
- OLYMPUS CORPORATION
- TERUMO CORPORATION
- FUJIFILM CORPORATION
- DANAHER CORPORATION
- FRESENIUS SE & CO. KGAA
- TELEFLEX INCORPORATED
- GE HEALTHCARE TECHNOLOGIES INC.
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
- DEXCOM, INC.
- THERMO FISHER SCIENTIFIC INC.
- ALCON INC.
- NIPRO CORPORATION
第13章:調查方法
第14章附錄
The global medical devices market is projected to reach USD 817.78 billion by 2031 from USD 580.79 billion in 2026, at a CAGR of 7.1%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Type and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa (GCC Countries and the Rest of Middle East & Africa) |
The growth of the medical devices market is driven by the increasing prevalence of chronic diseases and the rapidly aging global population, which continues to raise demand for diagnostic, cardiovascular, orthopedic, ophthalmic devices, and other medical devices. However, the high cost of advanced medical devices, including cardiovascular systems, orthopedic implants, and diagnostic equipment, restrains adoption, particularly in developing countries with limited healthcare budgets. The market also faces challenges from stringent regulatory frameworks and lengthy product approval processes, as well as shortages of skilled healthcare professionals capable of operating sophisticated medical technologies, which can delay product adoption and clinical implementation. Despite these barriers, the rapidly developing healthcare infrastructure in emerging economies presents significant growth opportunities. Increasing investments in hospitals, ambulatory surgery centers, diagnostic laboratories, and digital healthcare systems, along with expanding health insurance coverage, are improving access to advanced medical technologies, enabling leading manufacturers to expand their global footprint and strengthen long-term market growth.
"By type, the cardiovascular devices segment held the second-largest share of the medical devices market in 2025."
Based on type, the medical devices market comprises in vitro diagnostic devices, cardiovascular devices, imaging devices, orthopedic devices, ophthalmology devices, endoscopy devices, diabetes care devices, wound care devices, kidney/dialysis devices, respiratory care devices and other medical devices. Among these, cardiovascular devices held the second-largest share of the market in 2025. This is due to the increasing global burden of cardiovascular diseases (CVDs) and the growing demand for advanced diagnostic and interventional technologies. According to the World Health Organization (WHO), an estimated 19.8 million people died from cardiovascular diseases in 2022, accounting for approximately 32% of all global deaths. Additionally, the US Centers for Disease Control and Prevention (CDC) reported that 919,032 people died from cardiovascular disease in the US in 2023. This high disease burden has significantly increased the adoption of cardiac rhythm management devices, coronary stents, heart valves, catheters, and vascular intervention systems. The rising aging population, along with the increasing prevalence of hypertension, diabetes, and obesity, has led to a greater demand for cardiovascular devices. This demand is further bolstered by a growing preference for minimally invasive cardiovascular procedures and ongoing technological advancements. As a result, the cardiovascular devices segment continues to hold a prominent position in the global medical devices market.
"The US is expected to grow at the highest CAGR in the North American market during the forecast period."
The medical devices market is divided into five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Among these, North America dominated the global medical devices market in 2025. The North American market is further divided into the US and Canada. Among these, the US held the largest share of the North American market in 2025. This is due to its high prevalence of chronic diseases, advanced healthcare infrastructure, substantial healthcare spending, and strong presence of leading medical device manufacturers. According to the US Centers for Disease Control and Prevention (CDC), coronary heart disease, the most common type of heart disease, caused 371,506 deaths in 2022. The CDC also reported in June 2024 that approximately 53 million US adults have arthritis, while CDC data released in 2026 estimated that more than 1 in 10 adults (37 million people) have chronic kidney disease (CKD). This significant disease burden drives sustained demand for cardiovascular, orthopedic, diagnostic, and renal care devices. In addition, the US benefits from the rapid adoption of advanced medical technologies, favorable reimbursement systems, strong research and development investments, and the presence of major medical device company headquarters, which support continuous product innovation and reinforce the country's leadership in the regional medical devices market.
A breakdown of the primary participants (supply side) for the medical devices market referred to in this report is provided below:
- By Company Type: Tier 1 (35%), Tier 2 (40%), and Tier 3 (25%)
- By Designation: C-level Executives (45%), Directors (35%), and Others (20%)
- By Region: North America (27%), Europe (25%), Asia Pacific (30%), Latin America (8%), and the Middle East & Africa (10%)
Prominent players in the medical devices market include Medtronic (Ireland), Johnson & Johnson (US), B. Braun SE (Germany), Olympus Corporation (Japan), GE Healthcare (US), and Boston Scientific (US), among others.
Research Coverage
The report analyzes the medical devices market and estimates its size and future growth potential across segments (type and region). The report also includes a competitive analysis of the key players in this market along with their company profiles, product offerings, recent developments, and key market strategies.
Reasons to Buy the Report
The report will help market leaders/new entrants in this market by providing revenue estimates for the overall medical devices market. This report will help stakeholders understand the competitive landscape and gain deeper insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key drivers, restraints, challenges, and opportunities.
This report provides insights into the following pointers:
- Analysis of key drivers (rising aging population and increasing prevalence of chronic diseases), restraints (high cost of various medical devices), opportunities (rapidly developing healthcare sector in emerging economies), and challenges (shortage of skilled healthcare professionals and stringent regulatory framework).
- Market Penetration: It includes extensive information on the products offered by the major players in the global medical devices market. The report includes various segments: type and region.
- Product Enhancement/Innovation: Comprehensive details about new product launches and anticipated trends in the global medical devices market.
- Market Development: Thorough knowledge and analysis of the profitable rising markets by type and region.
- Market Diversification: Comprehensive information about newly launched products, expanding markets, current advancements, and investments in the global medical devices market.
- Competitive Assessment: Thorough evaluation of the market shares, growth plans, product offerings, and capacities of the major competitors in the global medical devices market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS & MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: INSIGHTS & DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET GROWTH
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 MEDICAL DEVICES MARKET OVERVIEW
- 3.2 MEDICAL DEVICES MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.3 MEDICAL DEVICES MARKET: DEVELOPED VS. EMERGING ECONOMIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 IN VITRO DIAGNOSTIC DEVICES MARKET
- 4.2.1.1 Drivers
- 4.2.1.1.1 Gradual shift from centralized testing to point-of-care testing
- 4.2.1.1.2 Growing awareness of early disease diagnosis across emerging countries
- 4.2.1.2 Restraints
- 4.2.1.2.1 Reimbursement pressure and test-price controls
- 4.2.1.3 Opportunities
- 4.2.1.3.1 Expansion of companion diagnostics (CDx) and oncology testing
- 4.2.1.4 Challenges
- 4.2.1.4.1 Operational barriers and data privacy and cybersecurity risks
- 4.2.1.1 Drivers
- 4.2.2 CARDIOVASCULAR DEVICES MARKET
- 4.2.2.1 Drivers
- 4.2.2.1.1 Rising prevalence of cardiovascular diseases
- 4.2.2.2 Restraints
- 4.2.2.2.1 Stringent regulatory guidelines for product approval
- 4.2.2.3 Opportunities
- 4.2.2.3.1 Growing healthcare needs and improving medical infrastructure in emerging countries
- 4.2.2.4 Challenges
- 4.2.2.4.1 Product recalls and device-related safety events
- 4.2.2.1 Drivers
- 4.2.3 IMAGING DEVICES MARKET
- 4.2.3.1 Drivers
- 4.2.3.1.1 Increasing funds, investments, and grants by public-private investors
- 4.2.3.2 Restraints
- 4.2.3.2.1 High cost of diagnostic imaging systems
- 4.2.3.3 Opportunities
- 4.2.3.3.1 Growing adoption of artificial intelligence (AI) and advanced analytics
- 4.2.3.4 Challenges
- 4.2.3.4.1 Increasing adoption of refurbished diagnostic imaging systems
- 4.2.3.1 Drivers
- 4.2.4 ORTHOPEDIC DEVICES MARKET
- 4.2.4.1 Drivers
- 4.2.4.1.1 Rising prevalence of orthopedic diseases
- 4.2.4.2 Restraints
- 4.2.4.2.1 Risks and complications associated with orthopedic surgical procedures
- 4.2.4.2.2 High cost of orthopedic devices and surgical procedures
- 4.2.4.3 Opportunities
- 4.2.4.3.1 Increasing adoption of robotics and 3D printing in orthopedics
- 4.2.4.4 Challenges
- 4.2.4.4.1 Shortage of orthopedic surgeons
- 4.2.4.1 Drivers
- 4.2.5 OPHTHALMOLOGY DEVICES MARKET
- 4.2.5.1 Drivers
- 4.2.5.1.1 Rising prevalence of eye disorders
- 4.2.5.2 Restraints
- 4.2.5.2.1 High cost & potential risks associated with eye surgery
- 4.2.5.3 Opportunities
- 4.2.5.3.1 Growing adoption of minimally invasive ophthalmic surgical procedures
- 4.2.5.4 Challenges
- 4.2.5.4.1 Low accessibility to eye care services in emerging and low-income countries
- 4.2.5.1 Drivers
- 4.2.6 ENDOSCOPY DEVICES MARKET
- 4.2.6.1 Drivers
- 4.2.6.1.1 Rising investments, funding, and grants for endoscopy procedures
- 4.2.6.1.2 Increasing incidence of inflammatory bowel disease (IBD) and colorectal cancer
- 4.2.6.2 Restraints
- 4.2.6.2.1 High overhead cost and procedural risks associated with endoscopy
- 4.2.6.3 Opportunities
- 4.2.6.3.1 Rapidly developing healthcare sector in emerging economies
- 4.2.6.4 Challenges
- 4.2.6.4.1 Increasing number of product recalls
- 4.2.6.5 Lack of proper sterilization and reprocessing
- 4.2.6.1 Drivers
- 4.2.7 DIABETES CARE DEVICES MARKET
- 4.2.7.1 Drivers
- 4.2.7.1.1 Increasing prevalence of diabetes
- 4.2.7.2 Restraints
- 4.2.7.2.1 High cost of advanced diabetes care devices
- 4.2.7.3 Opportunities
- 4.2.7.3.1 Increasing adoption of advanced implantable continuous glucose monitoring (CGM) devices
- 4.2.7.4 Challenges
- 4.2.7.4.1 High costs and socioeconomic disparities
- 4.2.7.1 Drivers
- 4.2.8 WOUND CARE DEVICES MARKET
- 4.2.8.1 Drivers
- 4.2.8.1.1 Rising incidents of traumatic injuries and burn cases
- 4.2.8.2 Restraints
- 4.2.8.2.1 Risks associated with advanced wound care
- 4.2.8.3 Opportunities
- 4.2.8.3.1 Growth potential in emerging economies
- 4.2.8.4 Challenges
- 4.2.8.4.1 Shortage of trained professionals and limited access to wound care devices
- 4.2.8.1 Drivers
- 4.2.9 KIDNEY/DIALYSIS DEVICES MARKET
- 4.2.9.1 Drivers
- 4.2.9.1.1 Rising prevalence of chronic kidney disease (CKD)
- 4.2.9.2 Restraints
- 4.2.9.2.1 Risks, complications, and high procedural costs associated with dialysis treatments
- 4.2.9.3 Opportunities
- 4.2.9.3.1 Increasing number of dialysis centers in emerging economies
- 4.2.9.4 Challenges
- 4.2.9.4.1 Increasing number of product recalls and growing preference for renal transplantation
- 4.2.9.1 Drivers
- 4.2.10 RESPIRATORY CARE DEVICES MARKET
- 4.2.10.1 Drivers
- 4.2.10.1.1 Rising prevalence of chronic respiratory disease
- 4.2.10.2 Restraints
- 4.2.10.2.1 Unfavorable reimbursement scenario
- 4.2.10.3 Opportunities
- 4.2.10.3.1 High growth in developing countries across Asia Pacific and Latin America
- 4.2.10.4 Challenges
- 4.2.10.4.1 Harmful effects of certain devices on neonates
- 4.2.10.1 Drivers
- 4.2.1 IN VITRO DIAGNOSTIC DEVICES MARKET
- 4.3 UNMET NEEDS & WHITE SPACES
- 4.3.1 UNMET NEEDS IN MEDICAL DEVICES MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECAST
- 5.2.3 TRENDS IN MINIMALLY INVASIVE SURGERY (MIS) INDUSTRY
- 5.2.4 TRENDS IN SURGICAL ROBOTS INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND OF MEDICAL DEVICES, BY KEY PLAYER (2023-2025)
- 5.6.2 AVERAGE SELLING PRICE TREND OF MEDICAL DEVICES, BY REGION (2023-2025)
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 9018)
- 5.7.2 EXPORT DATA (HS CODE 9018)
- 5.8 KEY CONFERENCES & EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.10 INVESTMENT & FUNDING SCENARIO
- 5.11 IMPACT OF 2025 US TARIFFS ON MEDICAL DEVICES MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 END-USE INDUSTRY IMPACT
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 ROBOTIC-ASSISTED & COMPUTER-ASSISTED INTERVENTIONS
- 6.1.2 POINT-OF-CARE (POC) & MINIATURIZED DIAGNOSTICS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 DIGITAL INTERNET OF MEDICAL THINGS (IOMT) & CLOUD CONNECTIVITY
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.3.1 SHORT TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.3.2 MID TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.3.3 LONG TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.4 PATENT ANALYSIS
- 6.4.1 INSIGHTS: JURISDICTION & TOP APPLICANT ANALYSIS
- 6.5 FUTURE APPLICATIONS
- 6.6 IMPACT OF AI/GEN AI ON MEDICAL DEVICES MARKET
- 6.6.1 TOP USE CASES & MARKET POTENTIAL
- 6.6.2 CASE STUDIES OF AI IMPLEMENTATION IN MEDICAL DEVICES MARKET
- 6.6.3 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- 6.6.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN MEDICAL DEVICES MARKET
7 SUSTAINABILITY & REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS & COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT & ECO-APPLICATIONS OF MEDICAL DEVICES MARKET
- 7.2.1.1 Carbon impact reduction
- 7.2.1.2 Eco-applications
- 7.2.1 CARBON IMPACT & ECO-APPLICATIONS OF MEDICAL DEVICES MARKET
- 7.3 SUSTAINABILITY IMPACT & REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
- 7.5 REIMBURSEMENT ANALYSIS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 MEDICAL DEVICES MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 IN VITRO DIAGNOSTIC DEVICES
- 9.2.1 WIDESPREAD DIAGNOSTIC TESTING TO DRIVE DEMAND FOR IN VITRO DIAGNOSTIC DEVICES
- 9.3 CARDIOVASCULAR DEVICES
- 9.3.1 RISING CARDIOVASCULAR DISEASE BURDEN TO DRIVE DEMAND FOR CARDIOVASCULAR DEVICES
- 9.4 WOUND CARE DEVICES
- 9.4.1 RISING PREVALENCE OF CHRONIC WOUNDS AND ADVANCED WOUND MANAGEMENT TO DRIVE WOUND CARE DEVICE ADOPTION
- 9.5 RESPIRATORY CARE DEVICES
- 9.5.1 SHIFT TOWARD HOME-BASED RESPIRATORY MANAGEMENT AND NONINVASIVE THERAPIES TO DRIVE DEVICE ADOPTION
- 9.6 ORTHOPEDIC DEVICES
- 9.6.1 GROWING MUSCULOSKELETAL DISEASE BURDEN AND ADVANCES IN RECONSTRUCTIVE SURGERY TO SUPPORT MARKET GROWTH
- 9.7 KIDNEY/DIALYSIS DEVICES
- 9.7.1 RISING BURDEN OF CHRONIC KIDNEY DISEASE AND EXPANDING RENAL REPLACEMENT THERAPIES TO BOOST GROWTH
- 9.8 DIABETES CARE DEVICES
- 9.8.1 RISING DIABETES PREVALENCE AND ADVANCES IN CONTINUOUS GLUCOSE MONITORING TO FUEL GROWTH
- 9.9 ENDOSCOPY DEVICES
- 9.9.1 GROWING DEMAND FOR MINIMALLY INVASIVE DIAGNOSIS AND THERAPY TO CONTRIBUTE TO MARKET GROWTH
- 9.10 OPHTHALMOLOGY DEVICES
- 9.10.1 RISING GLOBAL BURDEN OF VISION IMPAIRMENT TO BOOST MARKET GROWTH
- 9.11 IMAGING DEVICES
- 9.11.1 GROWING DEMAND FOR ADVANCED DIAGNOSTIC IMAGING O FUEL GROWTH
- 9.12 OTHER MEDICAL DEVICES
10 MEDICAL DEVICES MARKET, BY REGION
- 10.1 INTRODUCTION
- 10.2 NORTH AMERICA
- 10.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 10.2.2 US
- 10.2.2.1 US to hold major share in North American medical devices market
- 10.2.3 CANADA
- 10.2.3.1 Growing chronic disease burden and aging population to support Canada's market
- 10.3 EUROPE
- 10.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 10.3.2 GERMANY
- 10.3.2.1 Germany's leadership in medtech manufacturing, hospital modernization, and aging population to support market expansion
- 10.3.3 UK
- 10.3.3.1 NHS diagnostic modernization and medtech innovation to accelerate market growth
- 10.3.4 FRANCE
- 10.3.4.1 France's emphasis on early diagnosis and specialized care to drive medical device demand
- 10.3.5 ITALY
- 10.3.5.1 Hospital technology modernization and expanding surgical care to drive medical device demand
- 10.3.6 SPAIN
- 10.3.6.1 Digital transformation of national health system to accelerate medical device adoption
- 10.3.7 REST OF EUROPE
- 10.4 ASIA PACIFIC
- 10.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 10.4.2 CHINA
- 10.4.2.1 Healthcare capacity expansion to drive medical device demand in China
- 10.4.3 JAPAN
- 10.4.3.1 Healthy aging policies and advanced healthcare delivery to drive market growth
- 10.4.4 INDIA
- 10.4.4.1 Expanding specialty healthcare access to drive medical device demand
- 10.4.5 AUSTRALIA
- 10.4.5.1 Expanding access to specialist healthcare services to support market growth
- 10.4.6 SOUTH KOREA
- 10.4.6.1 Biohealth innovation and AI-enabled healthcare to drive adoption
- 10.4.7 REST OF ASIA PACIFIC
- 10.5 LATIN AMERICA
- 10.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 10.5.2 BRAZIL
- 10.5.2.1 Strengthening domestic healthcare innovation and medical device production to boost market
- 10.5.3 MEXICO
- 10.5.3.1 Medical technology manufacturing expansion to support growth
- 10.5.4 REST OF LATIN AMERICA
- 10.6 MIDDLE EAST & AFRICA
- 10.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 10.6.2 GCC COUNTRIES
- 10.6.2.1 Healthcare transformation programs and smart hospital initiatives to drive medical device demand
- 10.6.3 REST OF MIDDLE EAST & AFRICA
11 COMPETITIVE LANDSCAPE
- 11.1 INTRODUCTION
- 11.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 11.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL DEVICES MARKET
- 11.3 REVENUE ANALYSIS, 2021-2025
- 11.4 MARKET SHARE ANALYSIS, 2025
- 11.4.1 GLOBAL IN VITRO DIAGNOSTIC DEVICES MARKET SHARE ANALYSIS, 2025
- 11.4.2 GLOBAL CARDIOVASCULAR DEVICES MARKET SHARE ANALYSIS, 2025
- 11.4.3 GLOBAL ORTHOPEDIC DEVICES MARKET SHARE ANALYSIS, 2025
- 11.4.4 GLOBAL DIABETES CARE DEVICES MARKET SHARE ANALYSIS, 2025
- 11.4.5 GLOBAL ENDOSCOPY DEVICES MARKET SHARE ANALYSIS, 2025
- 11.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 11.5.1 STARS
- 11.5.2 EMERGING LEADERS
- 11.5.3 PERVASIVE PLAYERS
- 11.5.4 PARTICIPANTS
- 11.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 11.5.5.1 Company footprint
- 11.5.5.2 Region footprint
- 11.5.5.3 Type footprint
- 11.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 11.6.1 PROGRESSIVE COMPANIES
- 11.6.2 RESPONSIVE COMPANIES
- 11.6.3 DYNAMIC COMPANIES
- 11.6.4 STARTING BLOCKS
- 11.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 11.6.5.1 Detailed list of key startups/SMEs
- 11.6.5.2 Competitive benchmarking of key startups/SMEs
- 11.7 COMPANY VALUATION & FINANCIAL METRICS
- 11.7.1 FINANCIAL METRICS
- 11.7.2 COMPANY VALUATION
- 11.8 BRAND/PRODUCT COMPARISON
- 11.9 COMPETITIVE SCENARIO
- 11.9.1 PRODUCT LAUNCHES & APPROVALS
- 11.9.2 DEALS
- 11.9.3 EXPANSION
12 COMPANY PROFILES
- 12.1 KEY PLAYERS
- 12.1.1 MEDTRONIC PLC
- 12.1.1.1 Business overview
- 12.1.1.2 Products offered
- 12.1.1.3 Recent developments
- 12.1.1.3.1 Product launches & approvals
- 12.1.1.4 MnM view
- 12.1.1.4.1 Right to win
- 12.1.1.4.2 Strategic choices
- 12.1.1.4.3 Weaknesses & competitive threats
- 12.1.2 JOHNSON & JOHNSON
- 12.1.2.1 Business overview
- 12.1.2.2 Products offered
- 12.1.2.3 Recent developments
- 12.1.2.3.1 Product launches & approvals
- 12.1.2.3.2 Deals
- 12.1.2.3.3 Expansions
- 12.1.2.4 MnM view
- 12.1.2.4.1 Right to win
- 12.1.2.4.2 Strategic choices
- 12.1.2.4.3 Weaknesses & competitive threats
- 12.1.3 ABBOTT
- 12.1.3.1 Business overview
- 12.1.3.2 Products offered
- 12.1.3.3 Recent developments
- 12.1.3.3.1 Product launches & approvals
- 12.1.3.3.2 Deals
- 12.1.3.3.3 Expansions
- 12.1.4 KONINKLIJKE PHILIPS N.V.
- 12.1.4.1 Business overview
- 12.1.4.2 Products offered
- 12.1.4.3 Recent developments
- 12.1.4.3.1 Product launches
- 12.1.4.3.2 Deals
- 12.1.4.3.3 Expansions
- 12.1.5 SIEMENS HEALTHINEERS AG
- 12.1.5.1 Business overview
- 12.1.5.2 Products offered
- 12.1.5.3 Recent developments
- 12.1.5.3.1 Product launches & approvals
- 12.1.5.3.2 Deals
- 12.1.5.3.3 Expansions
- 12.1.6 STRYKER CORPORATION
- 12.1.6.1 Business overview
- 12.1.6.2 Products offered
- 12.1.6.3 Recent developments
- 12.1.6.3.1 Deals
- 12.1.7 B. BRAUN SE
- 12.1.7.1 Business overview
- 12.1.7.2 Products offered
- 12.1.7.3 Recent developments
- 12.1.7.3.1 Deals
- 12.1.7.3.2 Expansions
- 12.1.7.4 MnM view
- 12.1.7.4.1 Right to win
- 12.1.7.4.2 Strategic choices
- 12.1.7.4.3 Weaknesses & competitive threats
- 12.1.8 SMITH & NEPHEW
- 12.1.8.1 Business overview
- 12.1.8.2 Products offered
- 12.1.8.3 Recent developments
- 12.1.8.3.1 Product launches
- 12.1.9 BOSTON SCIENTIFIC CORPORATION
- 12.1.9.1 Business overview
- 12.1.9.2 Products offered
- 12.1.9.3 Recent developments
- 12.1.9.3.1 Product approvals
- 12.1.9.3.2 Deals
- 12.1.10 F. HOFFMANN-LA ROCHE LTD.
- 12.1.10.1 Business overview
- 12.1.10.2 Products offered
- 12.1.10.3 Recent developments
- 12.1.10.3.1 Product launches & approvals
- 12.1.10.3.2 Deals
- 12.1.1 MEDTRONIC PLC
- 12.2 OTHER PLAYERS
- 12.2.1 BECTON, DICKINSON AND COMPANY
- 12.2.2 BAXTER INTERNATIONAL, INC.
- 12.2.3 ZIMMER BIOMET HOLDINGS, INC.
- 12.2.4 OLYMPUS CORPORATION
- 12.2.5 TERUMO CORPORATION
- 12.2.6 FUJIFILM CORPORATION
- 12.2.7 DANAHER CORPORATION
- 12.2.8 FRESENIUS SE & CO. KGAA
- 12.2.9 TELEFLEX INCORPORATED
- 12.2.10 GE HEALTHCARE TECHNOLOGIES INC.
- 12.2.11 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
- 12.2.12 DEXCOM, INC.
- 12.2.13 THERMO FISHER SCIENTIFIC INC.
- 12.2.14 ALCON INC.
- 12.2.15 NIPRO CORPORATION
13 RESEARCH METHODOLOGY
- 13.1 RESEARCH DATA
- 13.1.1 SECONDARY DATA
- 13.1.1.1 Key data from secondary sources
- 13.1.2 PRIMARY DATA
- 13.1.2.1 Key data from primary sources
- 13.1.2.2 Key industry insights
- 13.1.1 SECONDARY DATA
- 13.2 MARKET SIZE ESTIMATION
- 13.3 MARKET BREAKDOWN & DATA TRIANGULATION
- 13.4 MARKET RANKING ANALYSIS
- 13.5 STUDY ASSUMPTIONS
- 13.6 RESEARCH LIMITATIONS
- 13.6.1 METHODOLOGY-RELATED LIMITATIONS
- 13.6.2 SCOPE-RELATED LIMITATIONS
- 13.7 RISK ASSESSMENT
14 APPENDIX
- 14.1 DISCUSSION GUIDE
- 14.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 14.3 CUSTOMIZATION OPTIONS
- 14.4 RELATED REPORTS
- 14.5 AUTHOR DETAILS
List of Tables
- TABLE 1 MEDICAL DEVICES MARKET: INCLUSIONS & EXCLUSIONS
- TABLE 2 STANDARD CURRENCY CONVERSION RATES
- TABLE 3 LIST OF INVESTMENT FOR IMAGING DEVICES
- TABLE 4 LIST OF RECALLS BY KEY PLAYERS
- TABLE 5 MEDICAL DEVICES MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 6 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2030
- TABLE 7 AVERAGE SELLING PRICE TREND OF MEDICAL DEVICES, BY KEY PLAYER, 2023-2025 (USD)
- TABLE 8 AVERAGE PRICING TREND OF MEDICAL DEVICES, BY REGION, 2023-2025 (USD)
- TABLE 9 IMPORT DATA FOR MEDICAL DEVICES UNDER HS CODE 9018, BY COUNTRY, 2019-2024 (USD THOUSAND)
- TABLE 10 EXPORT DATA FOR MEDICAL DEVICES UNDER HS CODE 9018, BY COUNTRY, 2019-2024 (USD THOUSAND)
- TABLE 11 MEDICAL DEVICES MARKET: DETAILED LIST OF KEY CONFERENCES & EVENTS (2026-2027)
- TABLE 12 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 13 KEY PRODUCT-RELATED TARIFFS EFFECTIVE FOR MEDICAL DEVICES
- TABLE 14 AI-ENABLED DIAGNOSTICS, DIGITAL HEALTH, AND PRECISION MEDICINE
- TABLE 15 CONNECTED MEDICAL DEVICES, REMOTE MONITORING, AND SMART HEALTHCARE ECOSYSTEMS
- TABLE 16 TOP USE CASES & MARKET POTENTIAL
- TABLE 17 MEDICAL DEVICES MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION
- TABLE 18 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- TABLE 19 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 MIDDLE EAST & AFRICA AND GCC COUNTRIES: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 GLOBAL STANDARDS IN MEDICAL DEVICES MARKET
- TABLE 25 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN MEDICAL DEVICES MARKET
- TABLE 26 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR MEDICAL DEVICES
- TABLE 27 KEY BUYING CRITERIA FOR TOP THREE MEDICAL DEVICES
- TABLE 28 MEDICAL DEVICES MARKET: UNMET NEEDS/END-USER EXPECTATIONS
- TABLE 29 MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 30 IN VITRO DIAGNOSTIC DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 31 CARDIOVASCULAR DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 32 WOUND CARE DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 33 RESPIRATORY CARE DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 34 ORTHOPEDIC DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 35 KIDNEY/DIALYSIS DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 36 DIABETES CARE DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 37 ENDOSCOPY DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 38 OPHTHALMOLOGY DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 39 IMAGING DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 40 OTHER MEDICAL DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 41 MEDICAL DEVICES MARKET, BY REGION, 2024-2031 (USD BILLION)
- TABLE 42 NORTH AMERICA: MEDICAL DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 43 NORTH AMERICA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 44 US: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 45 CANADA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 46 EUROPE: MEDICAL DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 47 EUROPE: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 48 GERMANY: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 49 UK: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 50 FRANCE: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 51 ITALY: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 52 SPAIN: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 53 REST OF EUROPE: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 54 ASIA PACIFIC: MEDICAL DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 55 ASIA PACIFIC: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 56 CHINA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 57 JAPAN: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 58 INDIA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 59 AUSTRALIA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 60 SOUTH KOREA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 61 REST OF ASIA PACIFIC: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 62 LATIN AMERICA: MEDICAL DEVICES MARKET, BY COUNTRY, 2024-2031 (USD BILLION)
- TABLE 63 LATIN AMERICA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 64 BRAZIL: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 65 MEXICO: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 66 REST OF LATIN AMERICA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 67 MIDDLE EAST & AFRICA: MEDICAL DEVICES MARKET, BY REGION, 2024-2031 (USD BILLION)
- TABLE 68 MIDDLE EAST & AFRICA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 69 GCC COUNTRIES: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 70 REST OF MIDDLE EAST & AFRICA: MEDICAL DEVICES MARKET, BY TYPE, 2024-2031 (USD BILLION)
- TABLE 71 OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN MEDICAL DEVICES MARKET
- TABLE 72 MEDICAL DEVICES MARKET: REGION FOOTPRINT
- TABLE 73 MEDICAL DEVICES MARKET: TYPE FOOTPRINT
- TABLE 74 MEDICAL DEVICES MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 75 MEDICAL DEVICES MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 76 MEDICAL DEVICES MARKET: PRODUCT LAUNCHES & APPROVALS, J ANUARY 2022-JUNE 2026
- TABLE 77 MEDICAL DEVICES MARKET: DEALS, JANUARY 2022-JUNE 2026
- TABLE 78 MEDICAL DEVICES MARKET: EXPANSION, JANUARY 2022-JUNE 2026
- TABLE 79 MEDTRONIC PLC: COMPANY OVERVIEW
- TABLE 80 MEDTRONIC PLC: PRODUCTS OFFERED
- TABLE 81 MEDTRONIC PLC: PRODUCT LAUNCHES & APPROVALS, JANUARY 2021-JUNE 2026
- TABLE 82 JOHNSON & JOHNSON: COMPANY OVERVIEW
- TABLE 83 JOHNSON & JOHNSON: PRODUCTS OFFERED
- TABLE 84 JOHNSON & JOHNSON: PRODUCT LAUNCHES & APPROVALS, JANUARY 2021-JUNE 2026
- TABLE 85 JOHNSON & JOHNSON: DEALS, JANUARY 2021-JUNE 2026
- TABLE 86 JOHNSON & JOHNSON: EXPANSIONS, JANUARY 2021-JUNE 2026
- TABLE 87 ABBOTT: COMPANY OVERVIEW
- TABLE 88 ABBOTT: PRODUCTS OFFERED
- TABLE 89 ABBOTT: PRODUCT LAUNCHES & APPROVALS, JANUARY 2022-JUNE 2026
- TABLE 90 ABBOTT: DEALS, JANUARY 2022-JUNE 2026
- TABLE 91 ABBOTT: EXPANSIONS, JANUARY 2022-JUNE 2026
- TABLE 92 KONINKLIJKE PHILIPS N.V.: COMPANY OVERVIEW
- TABLE 93 KONINKLIJKE PHILIPS N.V.: PRODUCTS OFFERED
- TABLE 94 KONINKLIJKE PHILIPS N.V.: PRODUCT LAUNCHES, JANUARY 2022-JUNE 2026
- TABLE 95 KONINKLIJKE PHILIPS N.V.: DEALS, JANUARY 2022-JUNE 2026
- TABLE 96 KONINKLIJKE PHILIPS N.V.: EXPANSIONS, JANUARY 2022-JUNE 2026
- TABLE 97 SIEMENS HEALTHINEERS AG: COMPANY OVERVIEW
- TABLE 98 SIEMENS HEALTHINEERS AG: PRODUCTS OFFERED
- TABLE 99 SIEMENS HEALTHINEERS AG: PRODUCT LAUNCHES & APPROVALS, JANUARY 2022-JUNE 2026
- TABLE 100 SIEMENS HEALTHINEERS AG: DEALS, JANUARY 2021-JUNE 2026
- TABLE 101 SIEMENS HEALTHINEERS AG: EXPANSIONS, JANUARY 2021-JUNE 2026
- TABLE 102 STRYKER CORPORATION: COMPANY OVERVIEW
- TABLE 103 STRYKER CORPORATION: PRODUCTS OFFERED
- TABLE 104 STRYKER CORPORATION: DEALS, JANUARY 2021-JUNE 2026
- TABLE 105 B. BRAUN SE: COMPANY OVERVIEW
- TABLE 106 B. BRAUN SE: PRODUCTS OFFERED
- TABLE 107 B. BRAUN SE: DEALS, JANUARY 2021-JUNE 2026
- TABLE 108 B. BRAUN SE: EXPANSIONS, JANUARY 2021-JUNE 2026
- TABLE 109 SMITH & NEPHEW: COMPANY OVERVIEW
- TABLE 110 SMITH & NEPHEW: PRODUCTS OFFERED
- TABLE 111 SMITH & NEPHEW: PRODUCT LAUNCHES, JANUARY 2021-JUNE 2026
- TABLE 112 BOSTON SCIENTIFIC CORPORATION: COMPANY OVERVIEW
- TABLE 113 BOSTON SCIENTIFIC CORPORATION: PRODUCTS OFFERED
- TABLE 114 BOSTON SCIENTIFIC CORPORATION: PRODUCT APPROVALS, J ANUARY 2021-JUNE 2026
- TABLE 115 BOSTON SCIENTIFIC CORPORATION: DEALS, JANUARY 2022-JUNE 2026
- TABLE 116 F. HOFFMANN-LA ROCHE LTD.: COMPANY OVERVIEW
- TABLE 117 F. HOFFMANN-LA ROCHE LTD.: PRODUCTS OFFERED
- TABLE 118 F. HOFFMANN-LA ROCHE LTD.: PRODUCT LAUNCHES & APPROVALS, JANUARY 2022-JUNE 2026
- TABLE 119 F. HOFFMANN-LA ROCHE LTD.: DEALS, JANUARY 2022-JUNE 2026
- TABLE 120 BECTON, DICKINSON AND COMPANY: BUSINESS OVERVIEW
- TABLE 121 BAXTER INTERNATIONAL, INC.: BUSINESS OVERVIEW
- TABLE 122 ZIMMER BIOMET HOLDINGS, INC.: BUSINESS OVERVIEW
- TABLE 123 OLYMPUS CORPORATION: BUSINESS OVERVIEW
- TABLE 124 TERUMO CORPORATION: BUSINESS OVERVIEW
- TABLE 125 FUJIFILM CORPORATION: BUSINESS OVERVIEW
- TABLE 126 DANAHER CORPORATION: BUSINESS OVERVIEW
- TABLE 127 FRESENIUS SE & CO. KGAA: BUSINESS OVERVIEW
- TABLE 128 TELEFLEX INCORPORATED: BUSINESS OVERVIEW
- TABLE 129 GE HEALTHCARE TECHNOLOGIES INC.: BUSINESS OVERVIEW
- TABLE 130 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: BUSINESS OVERVIEW
- TABLE 131 DEXCOM, INC.: BUSINESS OVERVIEW
- TABLE 132 THERMO FISHER SCIENTIFIC INC.: BUSINESS OVERVIEW
- TABLE 133 ALCON INC.: BUSINESS OVERVIEW
- TABLE 134 NIPRO CORPORATION: BUSINESS OVERVIEW
- TABLE 135 MEDICAL DEVICES MARKET: STUDY ASSUMPTIONS
- TABLE 136 MEDICAL DEVICES MARKET: RISK ASSESSMENT ANALYSIS
List of Figures
- FIGURE 1 MEDICAL DEVICES MARKET SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 KEY INSIGHTS & MARKET HIGHLIGHTS
- FIGURE 3 MEDICAL DEVICES MARKET, 2026 - 2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN MEDICAL DEVICES MARKET
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF MEDICAL DEVICES MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS IN MEDICAL DEVICES MARKET, 2025
- FIGURE 7 NORTH AMERICA TO HOLD LARGEST MARKET SHARE IN 2025
- FIGURE 8 RISING PREVALENCE OF CHRONIC DISEASES TO DRIVE MARKET GROWTH
- FIGURE 9 INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 10 EMERGING ECONOMIES TO REGISTER HIGHER GROWTH RATES DURING FORECAST PERIOD
- FIGURE 11 IN VITRO DIAGNOSTIC DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 CARDIOVASCULAR DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 13 IMAGING DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 ORTHOPEDIC DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 15 OPHTHALMOLOGY DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 16 ENDOSCOPY DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 17 DIABETES CARE DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 18 WOUND CARE DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 19 KIDNEY/DIALYSIS DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 20 RESPIRATORY DEVICES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 21 MEDICAL DEVICES MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 22 MEDICAL DEVICES MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 23 MEDICAL DEVICES MARKET: VALUE CHAIN ANALYSIS
- FIGURE 24 MEDICAL DEVICES MARKET: ECOSYSTEM ANALYSIS
- FIGURE 25 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- FIGURE 26 MEDICAL DEVICES MARKET: INVESTMENT & FUNDING SCENARIO
- FIGURE 27 NUMBER OF PATENTS PUBLISHED (JANUARY 2015-JUNE 2026)
- FIGURE 28 TOP APPLICANT COUNTRIES/REGIONS FOR MEDICAL DEVICES (JANUARY 2015-JUNE 2026)
- FIGURE 29 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR MEDICAL DEVICES
- FIGURE 30 KEY BUYING CRITERIA FOR MEDICAL DEVICES
- FIGURE 31 MEDICAL DEVICES MARKET: GEOGRAPHIC SNAPSHOT
- FIGURE 32 NORTH AMERICA: MEDICAL DEVICES MARKET SNAPSHOT
- FIGURE 33 ASIA PACIFIC: MEDICAL DEVICES MARKET SNAPSHOT
- FIGURE 34 REVENUE ANALYSIS OF KEY PLAYERS IN MEDICAL DEVICES MARKET (2021-2025)
- FIGURE 35 MARKET SHARE ANALYSIS OF KEY PLAYERS IN IN VITRO DIAGNOSTIC DEVICES MARKET (2025)
- FIGURE 36 MARKET SHARE ANALYSIS OF KEY PLAYERS IN CARDIOVASCULAR DEVICES MARKET (2025)
- FIGURE 37 MARKET SHARE ANALYSIS OF KEY PLAYERS IN ORTHOPEDIC DEVICES MARKET (2025)
- FIGURE 38 MARKET SHARE ANALYSIS OF KEY PLAYERS IN DIABETES CARE DEVICES MARKET (2025)
- FIGURE 39 MARKET SHARE ANALYSIS OF KEY PLAYERS IN ENDOSCOPY DEVICES MARKET (2025)
- FIGURE 40 MEDICAL DEVICES MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 41 MEDICAL DEVICES MARKET: COMPANY FOOTPRINT
- FIGURE 42 MEDICAL DEVICES MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 43 EV/EBITDA OF KEY VENDORS
- FIGURE 44 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 45 MEDICAL DEVICES MARKET: BRAND/PRODUCT COMPARATIVE ANALYSIS
- FIGURE 46 MEDTRONIC PLC: COMPANY SNAPSHOT (2025)
- FIGURE 47 JOHNSON & JOHNSON: COMPANY SNAPSHOT (2025)
- FIGURE 48 ABBOTT: COMPANY SNAPSHOT (2025)
- FIGURE 49 KONINKLIJKE PHILIPS N.V.: COMPANY SNAPSHOT (2025)
- FIGURE 50 SIEMENS HEALTHINEERS AG: COMPANY SNAPSHOT (2025)
- FIGURE 51 STRYKER CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 52 B. BRAUN SE: COMPANY SNAPSHOT (2025)
- FIGURE 53 SMITH & NEPHEW: COMPANY SNAPSHOT (2025)
- FIGURE 54 BOSTON SCIENTIFIC CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 55 F. HOFFMANN-LA ROCHE LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 56 RESEARCH DESIGN
- FIGURE 57 PRIMARY SOURCES
- FIGURE 58 PRIMARY BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 59 MARKET SIZE APPROACH: REVENUE SHARE ANALYSIS
- FIGURE 60 TOP-DOWN APPROACH
- FIGURE 61 BOTTOM-UP APPROACH
- FIGURE 62 IMPACT ANALYSIS OF DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES (2026-2031)
- FIGURE 63 MEDICAL DEVICES MARKET: CAGR PROJECTIONS
- FIGURE 64 DATA TRIANGULATION METHODOLOGY

 醫療設備銷售協議(2016年至2026年)
 量子成像檢測器市場—全球及區域分析:按應用、產品和國家分類—分析與預測(2026-2035年)醫療設備市場報告:趨勢、預測與競爭分析(至2035年)
 全球醫療設備人工智慧市場:2035 年的機會與策略
 醫療設備市場:2026-2032年全球市場預測(依產品、技術、用途、應用、最終用戶及通路分類)
 神經多樣性兒童的保育記錄和管理應用程式市場預測至2034年:全球解決方案類型、交付方式、經營模式、整合與生態系統、支援功能、最終用戶和區域分析
 2026-2030年全球醫療設備市場醫療設備市場預測至2034年-按產品類型、器材分類、應用、最終用戶、通路和地區分類的全球分析醫療設備合作與授權協議(2016-2026 年)
 按診醫療市場:按產品類型、應用、分銷管道和地區分類。