


 |
市場調查報告書
商品編碼
2131874
全球高清地圖市場:依自動化程度、服務類型、解決方案類型、用途、車輛類型和地區分類-預測至2033年HD maps market by LOA (L2, L3, L4 & L5), Service Type (Mapping & Localization, Update & Maintenance), Vehicle Type (Passenger Cars, Commercial Vehicle), Solution Type (Embedded, Cloud), Usage (Personal, Commercial), and Region - Global Forecast to 2033 |
||||||


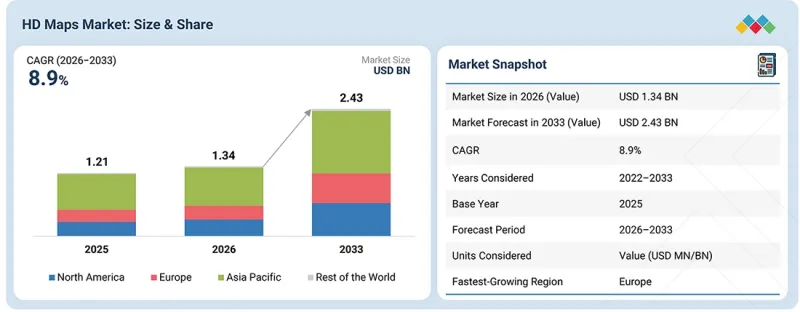
高清地圖市場預計將從 2026 年的 13.4 億美元成長到 2033 年的 24.3 億美元,複合年成長率為 8.9%。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2033 |
| 基準年 | 2025 |
| 預測期 | 2026-2033 |
| 目標單元 | 10億美元 |
| 部分 | 按自動化程度、服務類型、解決方案類型、使用方法、車輛類型和地區分類。 |
| 目標區域 | 亞太地區、北美地區、歐洲地區和世界其他地區 |
隨著語意地圖技術的興起,高清地圖市場也不斷發展。語意地圖技術不僅能顯示道路,還能解讀交通號誌燈、行人穿越道和車道線等物體,進而達到情境辨識。高解析度定位層正被整合到地圖中,以支援在複雜的都市區實現公分級定位。另一個新興趨勢是利用區塊鏈和安全資料共用框架,確保整個車隊地圖更新的可靠性和可信度。此外,節能地圖技術也日益受到關注,旨在降低自動駕駛車輛的計算負荷,同時保持地圖精度。高清地圖資料通常由配備LiDAR、攝影機、GPS 和雷達的車隊採集,並持續獲取和更新詳細的道路和環境資訊。這種群眾外包和感測器融合方法確保了自動駕駛所需的地圖的準確性和及時性。更高的地圖精度、更短的更新周期、更精確的定位以及更低的處理需求,將增強高清地圖在更高級的自動駕駛技術中的作用,並促進其在複雜的城市道路、高速公路和商業車輛路線上的更廣泛應用。
在預測期內,嵌入式解決方案預計將在高清地圖市場佔據顯著的市場佔有率。
市場對高清地圖的需求正轉向嵌入式地圖架構,這種架構能夠在車輛內部持續提供關鍵的道路信息,同時減少對持續雲連接的依賴。這對於需要持續定位和車道級道路資訊的功能尤其重要,因為網路延遲和覆蓋盲區會影響地圖的可用性。高清地圖供應商也正在開發包含更詳細道路資訊的嵌入式地圖內容,以支援自動駕駛功能。例如,Dynamic Map Platform 的「汽車高清地圖」提供高度精確和詳細的道路信息,包括車道形狀、道路邊界和交通相關屬性。此外,TMAP Mobility 於 2026 年 6 月宣布計劃於 2027 年將基於高清地圖的 3D 車道感知導航系統商業化。該系統將高清地圖與車載高精度定位和 ADAS 感測器識別技術相結合,可在高速公路和快速道路上提供車道級導航。市場也朝著可在車輛軟體生命週期內持續更新的嵌入式地圖發展。例如,現代汽車的AutoEver透過OTA(空中下載)方式提供地圖和導航更新,無需人工干預即可更新儲存在車輛內部的地圖內容。隨著嵌入式地圖與車輛運算、感測器融合和OTA基礎設施的整合日益緊密,競爭的焦點正轉向能夠高效管理車載地圖儲存、更新頻率和連接需求,同時提供低延遲地圖存取的解決方案。這種轉變推動了對嵌入式高清地圖架構的需求,該架構結合了本地可用性和選擇性OTA更新,使OEM廠商能夠在自動駕駛功能擴展的同時,保持可靠的車道級上下文信息,並管理車載存儲、連接依賴性和更新開銷。
在預測期內,自動駕駛汽車預計將在高清地圖市場中實現最高的成長率。
自動駕駛汽車領域的成長主要得益於高清地圖作為乘用車和商用車L4級自動駕駛核心資料圖層的日益普及。隨著L2+/L3級系統的廣泛應用和L4級部署的不斷擴大,對精確的車道級道路資訊的需求也日益成長,尤其是在定位、車道拓撲和預測性駕駛方面。隨著自動駕駛汽車的運行範圍不斷擴大,大規模創建、更新和檢驗高清地圖的能力變得與地圖本身的精度同等重要。例如,梅賽德斯-奔馳於2026年5月宣布計劃在2026年底前在德國部分城市都市區點對點自動導航服務,併計劃於2027年初在全國範圍內推廣。這將使自動駕駛技術應用於更複雜的城市環境。這些系統旨在應對複雜的城市環境,包括交通號誌、車道變換和擁塞路況,因此對詳細的道路資訊和精確的定位提出了更高的要求。
原始設備製造商 (OEM) 正在將高清地圖直接整合到其自動駕駛功能中。例如,梅賽德斯-奔馳在其「駕駛輔助系統 (DRIVE PILOT)」中使用了「HERE HD Live Map」來支援自動駕駛。同樣,BMW也在其高速公路自動駕駛系統「Personal Pilot L3」中利用了高清地圖資訊。一級供應商正在將高清地圖與位置數據和感測器數據整合。例如,博世將車輛產生的雷達和影像觀測資料與地圖資料結合,而採埃孚則將高精度定位和連接功能整合到其自動駕駛架構中,以支援更高水準的車輛自動化。在商用車領域,高畫質地圖正在支援在特定貨運路線上擴展自動駕駛功能。例如,達夫卡車在其 MODI 專案中使用 HERE HD Live Map 來實現 L4 級自動駕駛貨運營運。隨著 OEM 和一級供應商將高清地圖更深入地整合到其定位、感知和自動駕駛架構中,市場需求正在轉向高精度地圖內容、基於感測器的更新、雲端連接和可擴展的地理覆蓋範圍,這為高清地圖提供者創造了機會,使其成為更先進的自動駕駛汽車平臺的技術合作夥伴。
在預測期內,歐洲高清地圖市場預計將呈現最高的成長率。
在歐洲,對高清地圖解決方案的需求日益成長,這些方案能夠提供車道級道路幾何資訊、高精度定位、道路屬性以及用於高級乘用車功能的頻繁更新資訊。技術要求包括在大規模路網中維護車道級數據,並將這些資訊直接整合到車輛軟體平台中。歐洲乘用車製造商正擴大使用高清地圖作為自動駕駛功能的資料圖層。例如,大眾集團的軟體公司CARIAD在其自動駕駛系統中使用TomTom Orbis地圖,而路特斯則將高精度地圖資料整合到其「高速公路導航助理」(Highway Navigation Pilot)中,用於歐洲的L2+級自動駕駛功能。
此外,歐洲高清地圖正朝著更豐富的3D表示發展,以更精細地捕捉道路基礎設施及其周邊物理條件。例如,「動態地圖平台」提供高速公路和主要幹道的高精度3D點雲資料。 「MINDY Support」也為ADAS和自動駕駛提供企業級3D高清地圖標註和檢驗服務,涵蓋超過15,000個道路基礎設施對象,並可執行厘米級位置精度檢查(截至2026年2月)。在整個歐洲,這些市場變化為高清地圖提供者創造了機遇,使其能夠建立可擴展的平台,將高精度車道級數據、頻繁更新的道路資訊和3D道路表示相結合,從而支援乘用車自動化、ADAS開發、模擬、檢驗和數位道路應用。
高畫質地圖市場由百度(中國)、Mobileye(以色列)、TomTom International BV(荷蘭)、NVIDIA Corporation(美國)和HERE(荷蘭)等主要廠商主導。這些公司提供高度精細、即時更新的車道級高清地圖,旨在支援自動駕駛和高級駕駛輔助系統(ADAS)。它們還提供增值服務,例如動態地圖圖層(交通、路況、天氣)、雲端地圖交付平台、群眾外包資料整合、感測器融合解決方案以及用於路線規劃、位置估計和附加價值服務的軟體工具。
調查範圍:
本報告從服務類型(地圖繪製與定位、更新與維護、廣告)、車輛類型(PC 和 CV)、解決方案類型(嵌入式和雲端)、使用模式、自動化程度和地區等方面分析了高清地圖市場。報告中還涵蓋了高清地圖市場生態系統中的競爭格局和主要參與者的公司概況。
除了對主要市場參與者進行詳細的競爭分析外,本研究還涵蓋公司簡介、有關產品和營業內容的關鍵觀察、近期趨勢和主要市場策略。
購買本報告的主要好處:
- 本報告透過提供高清地圖市場及其細分市場的整體收入估計數據,幫助市場領導者和新參與企業。
- 本報告將幫助相關人員了解競爭格局,更好地定位其業務,並獲得進一步的見解,以製定合適的打入市場策略。
- 此外,本報告可協助相關人員了解市場趨勢,並提供關鍵市場促進因素、限制因素、挑戰和機會的資訊。
本報告深入分析了以下幾點:
- 本報告深入分析了關鍵促進因素(OEM 對持續更新的高清地圖而非靜態地圖的需求、將高清地圖整合到自動駕駛和定位堆疊中,以及配備 L2 和 L3 ADAS 的車輛的日益普及)、阻礙因素(創建和維護車道級地圖覆蓋範圍的高成本成本地圖以及提高車載感知能力以減少對預構建高清4D 地圖的日益普及以即時反映不斷變化的道路狀況)和挑戰(在快速變化的道路網路中保持地圖精度以及多感測器資料的複雜即時整合)。
- 產品開發/創新:深入分析高清地圖市場的未來技術和研發活動。
- 市場發展:盈利市場的全面資訊-本報告分析了各個地區的高清地圖市場。
- 市場多元化:提供高清地圖市場中未開發的市場、近期趨勢和投資機會的全面資訊。
- 競爭分析:對高清地圖市場主要參與者的市場佔有率、成長策略和產品陣容進行詳細評估,包括 HERE(荷蘭)、百度(中國)、TomTom International BV(荷蘭)、NVIDIA 公司(美國)和 Mobileye(以色列)。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 原始設備製造商和一級/二級/三級供應商的策略性舉措
第5章 產業趨勢
- 宏觀經濟展望
- 生態系分析
- 供應鏈分析
- 案例研究分析
- 投資和資金籌措場景
- 貿易分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 主要新興技術
- 互補技術
- 鄰近技術
- 技術/產品藍圖
- 專利分析
- 人工智慧/生成式人工智慧對高畫質地圖市場的影響
- 自動駕駛生態系統中高清地圖的分階段部署策略
- 高清地圖資料格式和標準化現狀
- MNM分享了對在地化關鍵產業解決方案的見解。
- 自動駕駛出行領域高解析度地圖繪製的經營模式演變
- 混合地圖策略以加強高級駕駛輔助系統(ADAS)的開發
- 無地圖自動駕駛概念對高清地圖的影響
- 原始設備製造商的高清地圖解決方案分析
- 高畫質地圖服務供應商:競爭格局
- 成功案例和實際應用
- 高清地圖的未來發展領域
- 高清地圖的貨幣化和收入模式
- OEM高清地圖的依賴性和戰略分析
- OEM區域地圖本地化策略
- 高清地圖實施的區域OEM策略
- 高清地圖提供者戰略能力基準
- 高解析度地圖在自動駕駛中的演變
- 高清地圖:總體擁有成本分析
第7章:監理情勢與永續性舉措
- 監理情勢
- 對永續性的承諾
- 監理政策對永續性舉措的影響
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 實施障礙和內部挑戰
第9章:高清地圖市場(依自動化程度分類)
- 半自動駕駛汽車
- 自動駕駛汽車
- 關鍵見解
第10章:高清地圖市場(依服務類型分類)
- 地圖繪製與定位
- 更新和維護
- 廣告
- 關鍵見解
第11章:高清地圖市場(按解決方案類型分類)
- 內建
- 基於雲端的
- 關鍵見解
第12章:高清地圖市場(依使用方法分類)
- 個人出行
- 商業流動性
- 關鍵見解
第13章:高清地圖市場(依車輛類型分類)
- 搭乘用車
- 商用車輛
- 關鍵見解
第14章:高清地圖市場(依地區分類)
- 亞太地區
- 對自動駕駛和先進地圖技術的投資增加正在推動市場發展。
- 中國
- 印度
- 日本
- 韓國
- 歐洲
- 車輛安全和自動駕駛方面的法規日益嚴格,正在推動市場成長。
- 德國
- 法國
- 義大利
- 西班牙
- 英國
- 北美洲
- 聯網汽車智慧汽車技術的日益普及將推動市場成長。
- 美國
- 加拿大
- 墨西哥
- 線
- 加大對智慧運輸和技術合作的投資將推動市場成長。
- 巴西
- 南非
- 俄羅斯
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第15章 競爭格局
- 概述
- 主要參與企業的競爭策略/優勢,2024-2026 年
- 2025年市佔率分析
- 2021-2025年收入分析
- 企業估值和財務指標
- 品牌/產品對比
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 競爭格局
第16章:公司簡介
- 主要參與企業
- HERE
- BAIDU
- TOMTOM INTERNATIONAL BV
- NVIDIA CORPORATION
- MOBILEYE
- WAYMO LLC
- DYNAMIC MAP PLATFORM CO., LTD.
- NAVINFO CO., LTD.
- THE SANBORN MAP COMPANY, INC.
- MOMENTA
- MAPBOX
- CE INFO SYSTEMS LTD.
- 其他公司
- NAVMII
- RMSI
- ZENRIN CO., LTD.
- WOVEN BY TOYOTA, INC.
- SWIFT NAVIGATION, INC.
- EXLSERVICE HOLDINGS, INC.
- ROBOTIC DATA
- HYUNDAI AUTOEVER CORP.
- GENESYS INTERNATIONAL CORPORATION LTD
- GEOMATE
- INTELLIAS
- MORAI INC.
- TRIMBLE INC.
第17章調查方法
第18章附錄
The HD maps market is projected to grow from USD 1.34 billion in 2026 to USD 2.43 billion by 2033, at a CAGR of 8.9%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | USD billion |
| Segments | LOA, Service Type, Vehicle Type, Solution Type, Usage, and Region |
| Regions covered | Asia Pacific, North America, Europe, and the Rest of the World |
The HD maps market is advancing with the rise of semantic mapping, where maps show roads and interpret objects such as traffic lights, crosswalks, and lane markings for contextual awareness. High-definition localization layers are being integrated to support centimeter-level positioning in complex urban areas. Another emerging trend is the use of blockchain and secure data-sharing frameworks to ensure reliability and trust in map updates across fleets. In addition, energy-efficient mapping techniques are gaining attention to reduce the computational load on autonomous vehicles while maintaining accuracy. Data for HD maps is typically collected through fleets of sensor-equipped vehicles using LiDAR, cameras, GPS, and radar, which continuously capture and update detailed road and environment information. This crowdsourced and sensor-fusion approach ensures maps remain precise and up to date for autonomous driving. Improved map accuracy, faster update cycles, precise localization, and lower processing requirements will strengthen the role of HD maps in higher levels of autonomous driving, supporting wider deployment across complex urban roads, highways, and commercial vehicle routes.
Embedded solution to hold a significant market share of the HD maps market during the forecast period.
Market demand for HD Maps is moving toward embedded map architectures that can keep critical road information available inside the vehicle while reducing dependence on continuous cloud connectivity. This is particularly relevant for functions requiring consistent localization and lane-level road context, where network latency or coverage gaps can affect map availability. HD map providers are also developing embedded map content with higher levels of road detail for automated driving functions. For instance, Dynamic Map Platform's Automotive HD Map provides high-precision, detailed road features, including lane geometry, road boundaries, and traffic-related attributes. Additionally, in June 2026, TMAP Mobility announced plans to commercialize its HD map-based 3D lane recognition navigation system in 2027, integrating HD maps with in-vehicle precise positioning and ADAS sensor recognition to provide lane-level guidance across highways and expressways. The market is also moving toward embedded maps that can be refreshed through the vehicle software lifecycle. For instance, Hyundai AutoEver distributes map and navigation updates through OTA, allowing map content stored in the vehicle to be updated without physical service intervention. As embedded mapping becomes more closely connected with vehicle computing, sensor fusion, and OTA infrastructure, competition is shifting toward solutions that can provide low-latency map access while efficiently managing map storage, update frequency, and connectivity requirements within the vehicle. This shift is strengthening demand for embedded HD map architectures that combine local availability with selective OTA updates, enabling OEMs to maintain reliable lane-level context while controlling onboard storage, connectivity dependence, and updating overhead as automated driving functions scale.
Autonomous vehicles are projected to grow at the fastest rate in the HD maps market during the forecast period.
The growth of the autonomous vehicles segment is being driven by the increasing use of HD maps as a core data layer for Level 4 autonomous driving in passenger cars and commercial vehicles. The expansion of L2+/L3 systems and emerging L4 deployment is increasing the need for precise, lane-level road intelligence, particularly for localization, lane topology, and predictive maneuvering. As autonomous vehicles expand into larger operating areas, the ability to create, update, and validate HD maps at scale is becoming as important as map accuracy itself. For instance, in May 2026, Mercedes-Benz announced that its urban point-to-point automated navigation would be available in selected German cities by the end of 2026, with nationwide rollout planned by early 2027, which is also moving automated driving into more complex urban environments. The system is designed for complex urban conditions including traffic lights, lane changes, and dense traffic, increasing the need for detailed road intelligence and precise localization.
OEMs are integrating HD maps directly into automated driving functions. For instance, Mercedes-Benz uses HERE HD Live Map within DRIVE PILOT to support autonomous driving. Similarly, BMW uses HD map information within its Personal Pilot L3 system for highway automated driving. Tier 1 suppliers are integrating HD maps with localization and sensor data. For instance, Bosch is combining vehicle-generated radar and video observations with map data, and ZF is integrating high-precision positioning and connectivity into its automated driving architecture to support higher levels of vehicle automation. For commercial vehicles, HD maps are supporting the expansion of automated driving across defined freight routes, such as DAF Trucks using HERE HD Live Map in the MODI project for Level 4 automated freight operations. As OEMs and Tier 1 suppliers integrate HD maps more deeply into localization, perception, and automated driving architectures, demand is shifting toward high-precision map content, sensor-based updates, cloud connectivity, and scalable geographic coverage, creating opportunities for HD map providers to become technology partners within higher automation vehicle platforms.
Europe is expected to grow at the fastest rate in the HD maps market during the forecast period.
In Europe, the demand is increasingly shifting toward HD map solutions that provide lane-level road geometry, high-precision positioning, road attributes, and frequently refreshed information for advanced passenger vehicle functions. The technical requirement is moving toward maintaining lane-level data across large road networks and integrating this information directly into vehicle software platforms. European passenger car OEMs are increasingly using HD maps as a data layer for automated driving functions. For instance, Volkswagen Group's software company CARIAD is using TomTom Orbis Maps for automated driving systems, while Lotus is integrating high-precision map data with its Highway Navigation Pilot for L2+ driving functions in Europe.
Additionally, HD maps in Europe are also moving toward richer 3D representations that capture road infrastructure and surrounding physical conditions in greater detail. For instance, Dynamic Map Platform provides high-precision 3D point cloud data of motorways and major arterial roads; MINDY Support has also provided enterprise-scale 3D HD map annotation and validation for ADAS and autonomous driving, covering more than 15,000 road infrastructure objects with centimeter-level positional accuracy checks as of February 2026. Across Europe, these market shifts are creating opportunities for HD map providers to combine high-precision lane-level data, frequently updated road information, and 3D road representations into scalable platforms that can support passenger vehicle automation, ADAS development, simulation, validation, and digital road applications.
In-depth interviews were conducted with CEOs, marketing directors, other innovation and technology directors, and executives from various key organizations operating in this market.
- By Company Type: OEM - 18%, Tier I - 74%, and Tier II/III - 8%
- By Designation: CXOs - 36%, Managers - 51%, and Executives - 13%
- By Region: North America - 24%, Europe - 30%, Asia Pacific - 38%, and RoW - 8%
The HD maps market is dominated by major players, including Baidu, Inc. (China), Mobileye (Israel), TomTom International BV (Netherlands), NVIDIA Corporation (US), and HERE (Netherlands). These companies offer highly detailed, lane-level HD maps with real-time updates, designed to support autonomous driving and ADAS. They also provide value-added services such as dynamic map layers (traffic, road conditions, and weather), cloud-based map delivery platforms, crowdsourced data integration, sensor fusion solutions, and software tools for path planning, localization, and navigation.
Research Coverage:
The report covers the HD maps market by Service Type (mapping & localization, update & maintenance, and advertisement), Vehicle Type (PC & CV), Solution Type (embedded & cloud-based), Usage Type, Level of Automation, and Region. It covers the competitive landscape and company profiles of the major HD maps market ecosystem players.
The study also includes an in-depth competitive analysis of key market players, along with company profiles, key observations on product and business offerings, recent developments, and key market strategies.
Key Benefits of Buying the Report:
- The report will help market leaders/new entrants with information on the closest approximations of revenue numbers for the overall HD maps market and its subsegments.
- This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies.
- The report also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insight on the following pointers:
- Analysis of key drivers (Demand from OEMs for Continuously Refreshed rather than Static HD Maps, Integration of HD Maps into Autonomous Driving and Localization Stacks, and Increasing Adoption of L2 and L3 ADAS-Equipped Vehicles), restraints (High Cost of Creating and Maintaining Lane Level Map Coverage, and Increasing Capability of Onboard Perception to Reduce Dependence on Prebuilt HD Maps), opportunities (Vehicle Generated Data and Maps as a Service Enabling Scalable HD Map Creation and Continuous Updates, Growing Adoption of Dynamic HD Maps and 4D Mapping for Real Time Representation of Changing Road Conditions), and challenges (Maintaining Map Accuracy During Rapid Road Network Changes and Complex Real-time Merging of Multi-Sensor Data).
- Product Development/Innovation: Detailed insights on upcoming technologies and research & development activities in the HD maps market.
- Market Development: Comprehensive information about lucrative markets - the report analyzes the HD maps market across varied regions.
- Market Diversification: Exhaustive information about untapped geographies, recent developments, and investments in the HD maps market.
- Competitive Assessment: In-depth assessment of market share, growth strategies, and product offerings of leading players such as HERE (Netherlands), Baidu, Inc. (China), TomTom International BV (Netherlands), NVIDIA Corporation (US), and Mobileye (Israel) in the HD maps market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN HD MAPS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN HD MAPS MARKET
- 3.2 HD MAPS MARKET, BY SERVICE TYPE
- 3.3 HD MAPS MARKET, BY VEHICLE TYPE
- 3.4 HD MAPS MARKET, BY SOLUTION TYPE
- 3.5 HD MAPS MARKET, BY LEVEL OF AUTOMATION
- 3.6 HD MAPS MARKET, BY USAGE TYPE
- 3.7 HD MAPS MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Shifting preference from static HD maps to updated map data
- 4.2.1.2 Rising integration of mapping, localization, and ADAS processing into shared software interfaces
- 4.2.1.3 Increasing adoption of L2 and L3 vehicles
- 4.2.2 RESTRAINTS
- 4.2.2.1 High costs of HD map creation and maintenance
- 4.2.2.2 Increasing capability of onboard perception
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing data generation from connected vehicles
- 4.2.3.2 Increasing reliance on dynamic HD maps and 4D mapping
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues in maintaining map accuracy amid rapid road network changes
- 4.2.4.2 Complexities in achieving seamless multi-sensor fusion
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 LACK OF STANDARDIZED HD MAP FORMATS AND INTERFACES ACROSS AUTONOMOUS DRIVING PLATFORMS
- 4.3.2 LIMITED COMMERCIAL MODELS FOR CONTINUOUS HD MAP UPDATES AND VEHICLE GENERATED MAP DATA
- 4.3.3 LACK OF SCALABLE MAP FRESHNESS AND AUTOMATED CHANGE VALIDATION
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY OEMS AND TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 MACROECONOMIC OUTLOOK
- 5.1.1 INTRODUCTION
- 5.1.2 GDP TRENDS AND FORECAST
- 5.1.3 TRENDS IN GLOBAL MAPPING INDUSTRY
- 5.1.4 TRENDS IN GLOBAL AUTONOMOUS VEHICLE INDUSTRY
- 5.2 ECOSYSTEM ANALYSIS
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 CASE STUDY ANALYSIS
- 5.4.1 MINDY SUPPORT DELIVERS ENTERPRISE-SCALE 3D HD MAP ANNOTATION AND VALIDATION FOR ADAS
- 5.4.2 HERE ENABLES HD MAP-BASED AUTOMATED DRIVING APPLICATIONS FOR GLOBAL OEMS
- 5.4.3 BAIDU AND TONGJI UNIVERSITY DEVELOP HISTORICAL MAP TRACKING FOR HD MAP CONSTRUCTION
- 5.4.4 MERCEDES-BENZ INTEGRATES HERE'S HD LIVE MAP INTO DRIVE PILOT SYSTEMS
- 5.4.5 INTELLIAS CONCEPTUALIZES, DEVELOPS, AND SCALES CLOUD-BASED HD MAPPING AND LOCATION DATA PLATFORM FOR AUTONOMOUS DRIVING
- 5.4.6 MAGNASOFT DEPLOYS AI-DRIVEN CONTINUOUS IMPROVEMENT PROCESSES THAT ENABLED REAL-TIME DETECTION OF CHANGES IN TRAFFIC PATTERNS AND ROAD CONDITIONS
- 5.4.7 INFOSYS ADOPTS MULTI-SOURCE HD MAPPING SOLUTION DESIGNED FOR ADAS IN URBAN ENVIRONMENTS
- 5.5 INVESTMENT AND FUNDING SCENARIO
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 852691)
- 5.6.2 EXPORT SCENARIO (HS CODE 852691)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 AI-BASED HD MAP GENERATION AND AUTOMATED FEATURE EXTRACTION
- 6.1.2 CROWD-SOURCED AND VEHICLE GENERATED HD MAPPING
- 6.1.3 DYNAMIC HD MAPS AND CONTINUOUS MAP UPDATING
- 6.1.4 CLOUD-BASED HD MAP PROCESSING AND DELIVERY
- 6.1.5 HIGH-PRECISION LOCALIZATION AND MAP MATCHING
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SENSOR FUSION
- 6.2.2 MACHINE LEARNING-POWERED MAP ANALYTICS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 DIGITAL TWIN AND SIMULATION
- 6.3.2 VEHICLE EDGE COMPUTING
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 2D VS. 3D VS. 4D MAPPING
- 6.4.2 SEMANTIC HD MAPS
- 6.4.3 VECTORIZED HD MAPS
- 6.4.4 RASTER VS. VECTOR MAP ARCHITECTURE
- 6.4.5 CLOUD-BASED VS. EMBEDDED HD MAPS
- 6.4.6 EDGE/ONBOARD MAP PROCESSING
- 6.4.7 MAP HORIZON
- 6.4.8 HD MAP APIS AND DATA INTERFACES
- 6.4.9 ADASIS AND MAP DATA EXCHANGE
- 6.5 PATENT ANALYSIS
- 6.6 IMPACT OF AI/GEN AI ON HD MAPS MARKET
- 6.6.1 ACCELERATED MAP CREATION AND UPDATES
- 6.6.2 ENHANCED LOCALIZATION ACCURACY
- 6.6.3 COST REDUCTION THROUGH SYNTHETIC DATA
- 6.6.4 DYNAMIC MAP PERSONALIZATION
- 6.6.5 TOP USE CASES AND MARKET POTENTIAL
- 6.6.6 BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN HD MAPS MARKET
- 6.6.7 CASE STUDIES RELATED TO AI/GEN IMPLEMENTATION IN HD MAPS MARKET
- 6.6.8 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.9 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED HD MAPS
- 6.7 PHASED ADOPTION STRATEGY OF HD MAPS IN AV ECOSYSTEM
- 6.7.1 ASSISTED DRIVING AND PILOT DEPLOYMENTS
- 6.7.2 LIMITED AUTONOMY IN CONTROLLED ENVIRONMENTS
- 6.7.3 EXPANDED COVERAGE AND REAL-TIME UPDATES
- 6.7.4 FULL AUTONOMY AND ECOSYSTEM INTEGRATION
- 6.8 HD MAP DATA FORMATS AND STANDARDIZATION LANDSCAPE
- 6.8.1 CORE COMPONENTS OF HD MAP DATA
- 6.8.1.1 Geometric layer
- 6.8.1.2 Semantic layer
- 6.8.1.3 Localization layer
- 6.8.1.4 Dynamic/Update layer
- 6.8.2 HD MAP: KEY STANDARDS AND FORMATS
- 6.8.1 CORE COMPONENTS OF HD MAP DATA
- 6.9 MNM INSIGHTS ON KEY INDUSTRY SOLUTIONS FOR LOCALIZATION
- 6.9.1 GNSS AND AUGMENTED POSITIONING
- 6.9.2 HD MAP-BASED LOCALIZATION
- 6.9.3 LIDAR AND CAMERA-BASED LOCALIZATION
- 6.9.4 SENSOR FUSION
- 6.9.5 V2X-ENABLED COOPERATIVE LOCALIZATION
- 6.10 EVOLVING BUSINESS MODELS FOR HD MAPPING IN AUTONOMOUS MOBILITY
- 6.10.1 LICENSING AND SUBSCRIPTION-BASED MODEL
- 6.10.2 CROWDSOURCED MAPPING AND DATA-AS-A-SERVICE (DAAS)
- 6.10.3 PAY-PER-USE MODEL
- 6.11 HYBRID MAPPING STRATEGIES FOR ENHANCING ADAS DEVELOPMENT
- 6.12 IMPACT OF MAPLESS AUTONOMY CONCEPT ON HD MAPS
- 6.13 ANALYSIS OF OEM HD MAPPING SOLUTIONS
- 6.14 HD MAPPING SERVICE PROVIDERS: COMPETITIVE LANDSCAPE
- 6.15 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.15.1 WAYMO: COMMERCIAL ROBOTAXI OPERATIONS IN US
- 6.15.2 MOBILEYE REM: CROWDSOURCED HD MAPPING ACROSS EUROPE
- 6.15.3 BAIDU APOLLO GO: CHINA'S ROBOTAXI EXPANSION
- 6.15.4 DYNAMIC MAP PLATFORM: GLOBAL HD MAP DEPLOYMENT
- 6.16 FUTURE DEPLOYMENT AREAS FOR HD MAPS
- 6.16.1 AUTONOMOUS DELIVERY VEHICLES
- 6.16.2 PLATOONING SUPPORT
- 6.16.3 V2X INTEGRATION
- 6.16.4 DYNAMIC TRAFFIC ROUTING
- 6.16.5 FREIGHT CORRIDOR OPTIMIZATION
- 6.16.6 SMART CITY INTEGRATION
- 6.16.7 AUTONOMOUS RIDE HAILING AND SHUTTLES
- 6.17 HD MAP MONETIZATION AND REVENUE MODELS
- 6.17.1 MAP LICENSE
- 6.17.2 PER-VEHICLE LICENSING
- 6.17.3 ANNUAL SUBSCRIPTION
- 6.17.4 PER-KILOMETER PRICING
- 6.17.5 API-BASED PRICING
- 6.17.6 CLOUD MAP SUBSCRIPTION
- 6.17.7 UPDATE/MAINTENANCE FEES
- 6.17.8 DATA-AS-A-SERVICE
- 6.17.9 MAP-AS-A-SERVICE
- 6.17.10 REVENUE SHARING WITH OEMS
- 6.17.11 BUNDLED HD MAP + LOCALIZATION
- 6.17.12 BUNDLED MAP + ADAS SOFTWARE
- 6.18 OEM HD MAP DEPENDENCY AND STRATEGY ANALYSIS
- 6.18.1 OEM FLEET DATA STRATEGY
- 6.18.2 OEM-OWNED MAPPING ASSETS
- 6.18.3 OEM-MAP PROVIDER PARTNERSHIPS
- 6.18.4 OEM-CLOUD PROVIDER PARTNERSHIPS
- 6.18.5 OEM-AV SOFTWARE INTEGRATION
- 6.19 OEM MAP LOCALIZATION STRATEGY, BY REGION
- 6.19.1 ASIA PACIFIC
- 6.19.2 EUROPE
- 6.19.3 NORTH AMERICA
- 6.20 REGIONAL OEM STRATEGIES FOR HD MAP ADOPTION
- 6.21 HD MAP PROVIDER STRATEGIC CAPABILITY BENCHMARK
- 6.21.1 GLOBAL ROAD COVERAGE
- 6.21.2 MAP ACCURACY
- 6.21.3 MAP UPDATE CAPABILITY
- 6.21.4 CROWDSOURCED DATA SCALE
- 6.21.5 OEM INTEGRATION
- 6.21.6 AUTONOMOUS DRIVING CAPABILITY
- 6.21.7 COMMERCIAL MODEL
- 6.22 EVOLUTION OF HD MAPS FOR AUTONOMOUS DRIVING
- 6.22.1 EVOLUTION FROM SD MAPS TO DYNAMIC HD MAPS
- 6.22.2 EVOLUTION FROM STATIC MAP TO CONTINUOUSLY UPDATED MAP
- 6.23 HD MAPS: TOTAL COST OF OWNERSHIP ANALYSIS
- 6.23.1 OEM TOTAL COST OF OWNERSHIP PER VEHICLE
- 6.23.2 HD MAP SUPPLIER TOTAL COST OF OWNERSHIP PER KILOMETER
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.4 RoW
- 7.1.2 KEY REGULATIONS
- 7.1.2.1 US
- 7.1.2.2 Germany
- 7.1.2.3 China
- 7.1.2.4 Japan
- 7.1.2.5 South Korea
- 7.1.2.6 UK
- 7.1.3 REGULATIONS AND INITIATIVES FOR ADAS
- 7.1.3.1 US
- 7.1.3.2 China
- 7.1.3.3 Japan
- 7.1.3.4 European Union
- 7.1.3.5 UK
- 7.1.3.6 Germany
- 7.1.3.7 France
- 7.1.3.8 India
- 7.1.4 NCAP REGULATIONS
- 7.1.4.1 US
- 7.1.4.2 Europe
- 7.1.4.3 Australia & New Zealand
- 7.1.4.4 South Korea
- 7.1.4.5 China
- 7.1.4.6 Latin America
- 7.1.4.7 Southeast Asia
- 7.1.4.8 India
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CHINA: INTELLIGENT CONNECTED VEHICLE AND DIGITAL ROAD INFRASTRUCTURE INITIATIVES
- 7.2.2 EUROPE: DIGITAL AND SUSTAINABLE TRANSPORT INFRASTRUCTURE INITIATIVES
- 7.2.3 US: SMART TRANSPORTATION AND CONNECTED VEHICLE INITIATIVES
- 7.2.4 JAPAN: SMART ROAD AND CONNECTED MOBILITY INITIATIVES
- 7.2.5 SOUTH KOREA: INTELLIGENT TRANSPORTATION AND AUTONOMOUS MOBILITY INITIATIVES
- 7.2.6 UAE: SMART MOBILITY AND DIGITAL ROAD INFRASTRUCTURE INITIATIVES
- 7.2.7 INDIA: INTELLIGENT TRANSPORTATION AND DIGITAL ROAD INFRASTRUCTURE INITIATIVES
- 7.2.8 GERMANY: SMART ROAD AND AUTOMATED DRIVING INFRASTRUCTURE INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.3.1 MARKET PROFITABILITY
- 8.3.2 REVENUE POTENTIAL
- 8.3.3 COST DYNAMICS
- 8.3.4 MARGIN OPPORTUNITIES, BY APPLICATION
9 HD MAPS MARKET, BY LEVEL OF AUTOMATION
- 9.1 INTRODUCTION
- 9.2 SEMI-AUTONOMOUS VEHICLE
- 9.2.1 LEVEL 2/2+
- 9.2.1.1 Strong focus on safety, convenience, and ADAS regulation compliance to foster segmental growth
- 9.2.2 LEVEL 3
- 9.2.2.1 High emphasis on precise localization and safe driving during traffic congestion to boost segmental growth
- 9.2.1 LEVEL 2/2+
- 9.3 AUTONOMOUS VEHICLE
- 9.3.1 LEVEL 4
- 9.3.1.1 Ability to tackle complex driving situations and operate under pretrained or predefined conditions to fuel segmental growth
- 9.3.2 LEVEL 5
- 9.3.2.1 Focus on enabling fully driverless operation to contribute to segmental growth
- 9.3.1 LEVEL 4
- 9.4 KEY PRIMARY INSIGHTS
10 HD MAPS MARKET, BY SERVICE TYPE
- 10.1 INTRODUCTION
- 10.2 MAPPING & LOCALIZATION
- 10.2.1 RAPID ADVANCES IN AI, MACHINE LEARNING, AND SENSOR TECHNOLOGIES TO EXPEDITE SEGMENTAL GROWTH
- 10.3 UPDATE & MAINTENANCE
- 10.3.1 GROWING EMPHASIS ON MAINTAINING PRECISION IN AUTONOMOUS DRIVING AND ADJUSTING TO CHANGING ENVIRONMENTS TO DRIVE MARKET
- 10.4 ADVERTISEMENT
- 10.5 KEY PRIMARY INSIGHTS
11 HD MAPS MARKET, BY SOLUTION TYPE
- 11.1 INTRODUCTION
- 11.2 EMBEDDED
- 11.2.1 USE TO OFFER REAL-TIME, HIGH-PRECISION LOCALIZATION AND NAVIGATION TO AUGMENT SEGMENTAL GROWTH
- 11.3 CLOUD-BASED
- 11.3.1 ABILITY TO MAKE CONTINUOUS UPDATES AND PROCESS VAST AMOUNTS OF DATA FROM SENSORS AND CAMERAS TO SPUR DEMAND
- 11.4 KEY PRIMARY INSIGHTS
12 HD MAPS MARKET, BY USAGE TYPE
- 12.1 INTRODUCTION
- 12.2 PERSONAL MOBILITY
- 12.2.1 GROWING DEMAND FOR ADAS-EQUIPPED PASSENGER CARS TO ACCELERATE SEGMENTAL GROWTH
- 12.3 COMMERCIAL MOBILITY
- 12.3.1 RISING POPULARITY OF E-COMMERCE AND DEMAND FOR EFFICIENT DELIVERY AND TRANSPORT TO FUEL SEGMENTAL GROWTH
- 12.4 KEY PRIMARY INSIGHTS
13 HD MAPS MARKET, BY VEHICLE TYPE
- 13.1 INTRODUCTION
- 13.2 PASSENGER CAR
- 13.2.1 GROWING INTEGRATION OF ADAS AND SEMI-AUTONOMOUS FEATURES INTO MID- TO HIGH-END VEHICLES TO FACILITATE SEGMENTAL GROWTH
- 13.3 COMMERCIAL VEHICLE
- 13.3.1 HIGH EMPHASIS ON SUPPORTING ROUTE OPTIMIZATION, PREDICTIVE MAINTENANCE, AND LIVE TRAFFIC MONITORING TO DRIVE MARKET
- 13.4 KEY PRIMARY INSIGHTS
14 HD MAPS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 ASIA PACIFIC
- 14.2.1 INCREASING INVESTMENT IN AUTONOMOUS DRIVING AND ADVANCED MAPPING TECHNOLOGIES TO DRIVE MARKET
- 14.2.2 CHINA
- 14.2.3 INDIA
- 14.2.4 JAPAN
- 14.2.5 SOUTH KOREA
- 14.3 EUROPE
- 14.3.1 RISING REGULATORY FOCUS ON VEHICLE SAFETY AND AUTONOMOUS DRIVING TO FOSTER MARKET GROWTH
- 14.3.2 GERMANY
- 14.3.3 FRANCE
- 14.3.4 ITALY
- 14.3.5 SPAIN
- 14.3.6 UK
- 14.4 NORTH AMERICA
- 14.4.1 MOUNTING ADOPTION OF CONNECTED AND INTELLIGENT VEHICLE TECHNOLOGIES TO BOOST MARKET GROWTH
- 14.4.2 US
- 14.4.3 CANADA
- 14.4.4 MEXICO
- 14.5 ROW
- 14.5.1 INCREASING SMART MOBILITY INVESTMENT AND TECHNOLOGY PARTNERSHIPS TO AUGMENT MARKET GROWTH
- 14.5.2 BRAZIL
- 14.5.3 SOUTH AFRICA
- 14.5.4 RUSSIA
- 14.5.5 SAUDI ARABIA
- 14.5.6 UAE
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2024-2026
- 15.3 MARKET SHARE ANALYSIS, 2025
- 15.4 REVENUE ANALYSIS, 2021-2025
- 15.5 COMPANY VALUATION AND FINANCIAL METRICS
- 15.6 BRAND/PRODUCT COMPARISON
- 15.6.1 HERE (NETHERLANDS)
- 15.6.2 BAIDU (CHINA)
- 15.6.3 TOMTOM INTERNATIONAL BV (NETHERLANDS)
- 15.6.4 NVIDIA CORPORATION (US)
- 15.6.5 MOBILEYE (ISRAEL)
- 15.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.7.1 STARS
- 15.7.2 EMERGING LEADERS
- 15.7.3 PERVASIVE PLAYERS
- 15.7.4 PARTICIPANTS
- 15.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.7.5.1 Company footprint
- 15.7.5.2 Region footprint
- 15.7.5.3 Usage type footprint
- 15.7.5.4 Vehicle type footprint
- 15.7.5.5 Level of automation footprint
- 15.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.8.1 PROGRESSIVE COMPANIES
- 15.8.2 RESPONSIVE COMPANIES
- 15.8.3 DYNAMIC COMPANIES
- 15.8.4 STARTING BLOCKS
- 15.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.8.5.1 Detailed list of key startups/SMEs
- 15.8.5.2 Competitive benchmarking of key startups/SMEs
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT/SERVICE LAUNCHES/DEVELOPMENTS
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
- 15.9.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 HERE
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Deals
- 16.1.1.3.2 Other developments
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths/Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses/Competitive threats
- 16.1.2 BAIDU
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Deals
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key strengths/Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses/Competitive threats
- 16.1.3 TOMTOM INTERNATIONAL BV
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Product/Service launches/enhancements
- 16.1.3.3.2 Deals
- 16.1.3.3.3 Other developments
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key strengths/Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses/Competitive threats
- 16.1.4 NVIDIA CORPORATION
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Deals
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key strengths/Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses/Competitive threats
- 16.1.5 MOBILEYE
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Deals
- 16.1.5.3.2 Other developments
- 16.1.5.4 MnM view
- 16.1.5.4.1 Key strengths/Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses/Competitive threats
- 16.1.6 WAYMO LLC
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.6.3.2 Expansions
- 16.1.6.3.3 Other developments
- 16.1.7 DYNAMIC MAP PLATFORM CO., LTD.
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Product/Service launches/enhancements
- 16.1.7.3.2 Deals
- 16.1.7.3.3 Expansions
- 16.1.7.3.4 Other developments
- 16.1.8 NAVINFO CO., LTD.
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.8.3.2 Other developments
- 16.1.9 THE SANBORN MAP COMPANY, INC.
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Developments
- 16.1.10 MOMENTA
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.11 MAPBOX
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Product/Service launches/enhancements
- 16.1.11.3.2 Deals
- 16.1.12 CE INFO SYSTEMS LTD.
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Deals
- 16.1.1 HERE
- 16.2 OTHER PLAYERS
- 16.2.1 NAVMII
- 16.2.2 RMSI
- 16.2.3 ZENRIN CO., LTD.
- 16.2.4 WOVEN BY TOYOTA, INC.
- 16.2.5 SWIFT NAVIGATION, INC.
- 16.2.6 EXLSERVICE HOLDINGS, INC.
- 16.2.7 ROBOTIC DATA
- 16.2.8 HYUNDAI AUTOEVER CORP.
- 16.2.9 GENESYS INTERNATIONAL CORPORATION LTD
- 16.2.10 GEOMATE
- 16.2.11 INTELLIAS
- 16.2.12 MORAI INC.
- 16.2.13 TRIMBLE INC.
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 List of key secondary sources
- 17.1.1.2 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.2.3 List of primary interview participants
- 17.1.2.4 Breakdown of primary interviews
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 TOP-DOWN APPROACH
- 17.2.2 MARKET FORECAST APPROACH
- 17.2.2.1 Supply side
- 17.2.2.2 Demand side
- 17.3 DATA TRIANGULATION
- 17.4 FACTOR ANALYSIS
- 17.5 RESEARCH ASSUMPTIONS
- 17.6 RESEARCH LIMITATIONS
- 17.7 RISK ANALYSIS
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.3.1 HD MAPS MARKET, BY SEMI AUTONOMOUS VEHICLES, AT REGIONAL LEVEL
- 18.3.2 HD MAPS MARKET, BY AUTONOMOUS VEHICLES, AT REGIONAL LEVEL
- 18.3.3 HD MAPS MARKET, BY VEHICLE TYPE, BY LEVEL OF AUTOMATION
- 18.3.4 COMPANY INFORMATION
- 18.3.4.1 Profiling of additional market players (up to five)
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 HD MAPS MARKET DEFINITION, BY SERVICE TYPE
- TABLE 2 HD MAPS MARKET DEFINITION, BY LEVEL OF AUTOMATION
- TABLE 3 HD MAPS MARKET DEFINITION, BY SOLUTION TYPE
- TABLE 4 HD MAPS MARKET DEFINITION, BY VEHICLE TYPE
- TABLE 5 HD MAPS MARKET DEFINITION, BY USAGE TYPE
- TABLE 6 HD MAPS MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 7 USD EXCHANGE RATES, 2021-2025
- TABLE 8 OEMS OFFERING HD MAPS IN L2/L3 VEHICLES
- TABLE 9 PREBUILT HD MAPS VS. ONBOARD PERCEPTION
- TABLE 10 HD MAP MONETIZATION OPPORTUNITIES FROM VEHICLE GENERATED DATA
- TABLE 11 IMPACT OF MARKET DYNAMICS
- TABLE 12 STRATEGIC FOCUS OF OEMS AND TIER-1/2/3 PLAYERS
- TABLE 13 GDP PERCENTAGE CHANGE, BY COUNTRY, 2021-2030
- TABLE 14 ROLE OF COMPANIES IN HD MAPS ECOSYSTEM
- TABLE 15 GERMAN AUTOMOTIVE TECHNOLOGY SUPPLIER ADOPTS MINDY SUPPORT'S 3D HD MAP ANNOTATION FOR ADAS AND AUTOMATED DRIVING PROGRAMS
- TABLE 16 AUTOMAKERS LEVERAGE HERE'S HD LIVE MAP TO SUPPORT AUTOMATED DRIVING FUNCTIONS
- TABLE 17 RESEARCHERS FROM BAIDU AND TONGJI UNIVERSITY DEVELOP HISTORICAL MAP TRACKING FOR HD MAP CONSTRUCTION FRAMEWORK TO IMPROVE CONSISTENCY OF MAP ELEMENTS
- TABLE 18 MERCEDES-BENZ INTEGRATES HERE'S HD LIVE MAP INTO DRIVE PILOT SYSTEM TO IMPROVE ENVIRONMENTAL AWARENESS
- TABLE 19 LOCATION-BASED SERVICES PROVIDER PARTNERS WITH INTELLIAS TO DEVELOP AND SCALE CLOUD-BASED HD MAPPING AND LOCATION DATA PLATFORM FOR AUTONOMOUS DRIVING
- TABLE 20 MAGNASOFT HELPS AUTONOMOUS MIDDLE-MILE DELIVERY SERVICE PROVIDER ACHIEVE COMPREHENSIVE HD MAPPING OF ROAD CONDITIONS
- TABLE 21 INFOSYS DEPLOYS MULTI-SOURCE HD MAPPING SOLUTION FOR ADAS IN URBAN ENVIRONMENTS TO IMPROVE NAVIGATION ACCURACY
- TABLE 22 FUNDING DETAILS, 2024-2026
- TABLE 23 IMPORT DATA FOR HS CODE 852691-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 24 EXPORT DATA FOR HS CODE 852691-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 25 LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 26 AI-BASED HD MAP GENERATION AND AUTOMATED FEATURE EXTRACTION: KEY INDUSTRY APPLICATIONS
- TABLE 27 DYNAMIC HD MAPS AND CONTINUOUS MAP UPDATING: KEY INDUSTRY APPLICATIONS
- TABLE 28 CLOUD-BASED HD MAP PROCESSING AND DELIVERY: KEY INDUSTRY APPLICATIONS
- TABLE 29 LIDAR VS. CAMERA VS. RADAR SENSORS
- TABLE 30 TECHNOLOGY/PRODUCT ROADMAP IN HD MAPS MARKET
- TABLE 31 LIST OF KEY PATENTS, 2024-2026
- TABLE 32 BEST PRACTICES FOLLOWED BY MANUFACTURERS
- TABLE 33 AI-BASED LANE DETECTION AND HD MAP AUTOMATION FOR AUTONOMOUS DRIVING
- TABLE 34 AI-BASED HD MAP AUTOMATION AND CHANGE DETECTION
- TABLE 35 AI-BASED HD MAP LABELING AND MULTI SENSOR DATA ANNOTATION
- TABLE 36 IMPACT OF ECOSYSTEM PARTICIPANTS ON HD MAPS MARKET
- TABLE 37 STANDARDS AND FORMATS OF HD MAPS
- TABLE 38 LICENSING AND SUBSCRIPTION-BASED MODEL
- TABLE 39 CROWDSOURCED MAPPING AND DATA-AS-A-SERVICE MODEL
- TABLE 40 PAY-PER-USE MODEL
- TABLE 41 MAPLESS AUTONOMY, KEY COMPANY APPROACHES, AND IMPACT ON HD MAP DEMAND
- TABLE 42 HD MAPPING SOLUTIONS, BY KEY OEM (1/2)
- TABLE 43 HD MAPPING SOLUTIONS, BY KEY OEM (2/2)
- TABLE 44 HD MAPPING SERVICE PROVIDERS: COMPETITIVE LANDSCAPE (1/2)
- TABLE 45 HD MAPPING SERVICE PROVIDERS: COMPETITIVE LANDSCAPE (2/2)
- TABLE 46 HD MAP MONETIZATION AND REVENUE MODELS
- TABLE 47 KEY OEM FLEET DATA STRATEGY
- TABLE 48 OEM-OWNED MAPPING ASSETS
- TABLE 49 OEM-MAP PROVIDER PARTNERSHIPS
- TABLE 50 OEM-CLOUD PROVIDER PARTNERSHIPS
- TABLE 51 OEM-AV SOFTWARE INTEGRATION
- TABLE 52 ASIA PACIFIC: OEM MAP LOCALIZATION STRATEGY
- TABLE 53 EUROPE: OEM MAP LOCALIZATION STRATEGY
- TABLE 54 NORTH AMERICA: OEM MAP LOCALIZATION STRATEGY
- TABLE 55 REGIONAL OEM STRATEGIES FOR HD MAP ADOPTION
- TABLE 56 HD MAP PROVIDERS STRATEGIC BENCHMARK
- TABLE 57 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 58 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 59 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 60 ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 61 US: KEY REGULATIONS
- TABLE 62 GERMANY: KEY REGULATIONS
- TABLE 63 CHINA: KEY REGULATIONS
- TABLE 64 JAPAN: KEY REGULATIONS
- TABLE 65 SOUTH KOREA: KEY REGULATIONS
- TABLE 66 UK: KEY REGULATIONS
- TABLE 67 US: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 68 CHINA: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 69 JAPAN: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 70 EUROPEAN UNION: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 71 UK: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 72 GERMANY: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 73 FRANCE: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 74 INDIA: REGULATIONS AND INITIATIVES FOR ADAS
- TABLE 75 US: NCAP REGULATIONS
- TABLE 76 EUROPE: NCAP REGULATIONS
- TABLE 77 AUSTRALIA & NEW ZEALAND: NCAP REGULATIONS
- TABLE 78 SOUTH KOREA: NCAP REGULATIONS
- TABLE 79 CHINA: NCAP REGULATIONS
- TABLE 80 LATIN AMERICA: NCAP REGULATIONS
- TABLE 81 SOUTHEAST ASIA: NCAP REGULATIONS
- TABLE 82 INDIA: NCAP REGULATIONS
- TABLE 83 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY VEHICLE TYPE (%)
- TABLE 84 BUYING CRITERIA, BY VEHICLE TYPE
- TABLE 85 HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2022-2025 (USD MILLION)
- TABLE 86 HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2026-2033 (USD MILLION)
- TABLE 87 SEMI-AUTONOMOUS VEHICLE: HD MAPS MARKET, BY AUTOMATION LEVEL, 2022-2025 (USD MILLION)
- TABLE 88 SEMI-AUTONOMOUS VEHICLE: HD MAPS MARKET, BY AUTOMATION LEVEL, 2026-2033 (USD MILLION)
- TABLE 89 SEMI-AUTONOMOUS VEHICLE: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 90 SEMI-AUTONOMOUS VEHICLE: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 91 AUTONOMOUS VEHICLE: HD MAPS MARKET, BY AUTOMATION LEVEL, 2022-2025 (USD MILLION)
- TABLE 92 AUTONOMOUS VEHICLE: HD MAPS MARKET, BY AUTOMATION LEVEL, 2026-2033 (USD MILLION)
- TABLE 93 AUTONOMOUS VEHICLE: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 94 AUTONOMOUS VEHICLE: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 95 HD MAPS MARKET, BY SERVICE TYPE, 2022-2025 (USD MILLION)
- TABLE 96 HD MAPS MARKET, BY SERVICE TYPE, 2026-2033 (USD MILLION)
- TABLE 97 MAPPING & LOCALIZATION: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 98 MAPPING & LOCALIZATION: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 99 UPDATE & MAINTENANCE: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 100 UPDATE & MAINTENANCE: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 101 HD MAPS MARKET, BY SOLUTION TYPE, 2022-2025 (USD MILLION)
- TABLE 102 HD MAPS MARKET, BY SOLUTION TYPE, 2026-2033 (USD MILLION)
- TABLE 103 EMBEDDED: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 104 EMBEDDED: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 105 CLOUD-BASED: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 106 CLOUD-BASED: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 107 HD MAPS MARKET, BY USAGE TYPE, 2022-2025 (USD MILLION)
- TABLE 108 HD MAPS MARKET, BY USAGE TYPE, 2026-2033 (USD MILLION)
- TABLE 109 PERSONAL MOBILITY: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 110 PERSONAL MOBILITY: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 111 COMMERCIAL MOBILITY: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 112 COMMERCIAL MOBILITY: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 113 HD MAPS MARKET, BY VEHICLE TYPE, 2022-2025 (USD MILLION)
- TABLE 114 HD MAPS MARKET, BY VEHICLE TYPE, 2026-2033 (USD MILLION)
- TABLE 115 OEMS PROVIDING HD MAPS IN PASSENGER CARS
- TABLE 116 PASSENGER CAR: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 117 PASSENGER CAR: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 118 COMMERCIAL VEHICLE: HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 119 COMMERCIAL VEHICLE: HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 120 HD MAPS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 121 HD MAPS MARKET, BY REGION, 2026-2033 (USD MILLION)
- TABLE 122 ASIA PACIFIC: HD MAPS MARKET, BY VEHICLE TYPE, 2022-2025 (USD MILLION)
- TABLE 123 ASIA PACIFIC: HD MAPS MARKET, BY VEHICLE TYPE, 2026-2033 (USD MILLION)
- TABLE 124 ASIA PACIFIC: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2022-2025 (USD MILLION)
- TABLE 125 ASIA PACIFIC: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2026-2033 (USD MILLION)
- TABLE 126 ASIA PACIFIC: HD MAPS MARKET, BY USAGE TYPE, 2022-2025 (USD MILLION)
- TABLE 127 ASIA PACIFIC: HD MAPS MARKET, BY USAGE TYPE, 2026-2033 (USD MILLION)
- TABLE 128 ASIA PACIFIC: HD MAPS MARKET, BY SOLUTION TYPE, 2022-2025 (USD MILLION)
- TABLE 129 ASIA PACIFIC: HD MAPS MARKET, BY SOLUTION TYPE, 2026-2033 (USD MILLION)
- TABLE 130 ASIA PACIFIC: HD MAPS MARKET, BY SERVICE TYPE, 2022-2025 (USD MILLION)
- TABLE 131 ASIA PACIFIC: HD MAPS MARKET, BY SERVICE TYPE, 2026-2033 (USD MILLION)
- TABLE 132 KEY COMPANIES OFFERING AUTONOMOUS VEHICLE TECHNOLOGIES AND THEIR PARTNERS IN CHINA
- TABLE 133 EUROPE: HD MAPS MARKET, BY VEHICLE TYPE, 2022-2025 (USD MILLION)
- TABLE 134 EUROPE: HD MAPS MARKET, BY VEHICLE TYPE, 2026-2033 (USD MILLION)
- TABLE 135 EUROPE: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2022-2025 (USD MILLION)
- TABLE 136 EUROPE: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2026-2033 (USD MILLION)
- TABLE 137 EUROPE: HD MAPS MARKET, BY USAGE TYPE, 2022-2025 (USD MILLION)
- TABLE 138 EUROPE: HD MAPS MARKET, BY USAGE TYPE, 2026-2033 (USD MILLION)
- TABLE 139 EUROPE: HD MAPS MARKET, BY SOLUTION TYPE, 2022-2025 (USD MILLION)
- TABLE 140 EUROPE: HD MAPS MARKET, BY SOLUTION TYPE, 2026-2033 (USD MILLION)
- TABLE 141 EUROPE: HD MAPS MARKET, BY SERVICE TYPE, 2022-2025 (USD MILLION)
- TABLE 142 EUROPE: HD MAPS MARKET, BY SERVICE TYPE, 2026-2033 (USD MILLION)
- TABLE 143 NORTH AMERICA: HD MAPS MARKET, BY VEHICLE TYPE, 2022-2025 (USD MILLION)
- TABLE 144 NORTH AMERICA: HD MAPS MARKET, BY VEHICLE TYPE, 2026-2033 (USD MILLION)
- TABLE 145 NORTH AMERICA: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2022-2025 (USD MILLION)
- TABLE 146 NORTH AMERICA: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2026-2033 (USD MILLION)
- TABLE 147 NORTH AMERICA: HD MAPS MARKET, BY USAGE TYPE, 2022-2025 (USD MILLION)
- TABLE 148 NORTH AMERICA: HD MAPS MARKET, BY USAGE TYPE, 2026-2033 (USD MILLION)
- TABLE 149 NORTH AMERICA: HD MAPS MARKET, BY SOLUTION TYPE, 2022-2025 (USD MILLION)
- TABLE 150 NORTH AMERICA: HD MAPS MARKET, BY SOLUTION TYPE, 2026-2033 (USD MILLION)
- TABLE 151 NORTH AMERICA: HD MAPS MARKET, BY SERVICE TYPE, 2022-2025 (USD MILLION)
- TABLE 152 NORTH AMERICA: HD MAPS MARKET, BY SERVICE TYPE, 2026-2033 (USD MILLION)
- TABLE 153 ROW: HD MAPS MARKET, BY VEHICLE TYPE, 2022-2025 (USD MILLION)
- TABLE 154 ROW: HD MAPS MARKET, BY VEHICLE TYPE, 2026-2033 (USD MILLION)
- TABLE 155 ROW: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2022-2025 (USD MILLION)
- TABLE 156 ROW: HD MAPS MARKET, BY LEVEL OF AUTOMATION, 2026-2033 (USD MILLION)
- TABLE 157 ROW: HD MAPS MARKET, BY USAGE TYPE, 2022-2025 (USD MILLION)
- TABLE 158 ROW: HD MAPS MARKET, BY USAGE TYPE, 2026-2033 (USD MILLION)
- TABLE 159 ROW: HD MAPS MARKET, BY SOLUTION TYPE, 2022-2025 (USD MILLION)
- TABLE 160 ROW: HD MAPS MARKET, BY SOLUTION TYPE, 2026-2033 (USD MILLION)
- TABLE 161 ROW: HD MAPS MARKET, BY SERVICE TYPE, 2022-2025 (USD MILLION)
- TABLE 162 ROW: HD MAPS MARKET, BY SERVICE TYPE, 2026-2033 (USD MILLION)
- TABLE 163 HD MAPS MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2025-AUGUST 2026
- TABLE 164 HD MAPS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 165 HD MAPS MARKET: REGION FOOTPRINT
- TABLE 166 HD MAPS MARKET: USAGE TYPE FOOTPRINT
- TABLE 167 HD MAPS MARKET: VEHICLE TYPE FOOTPRINT
- TABLE 168 HD MAPS MARKET: LEVEL OF AUTOMATION FOOTPRINT
- TABLE 169 HD MAPS MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 170 HD MAPS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 171 HD MAPS MARKET: PRODUCT/SERVICE LAUNCHES/DEVELOPMENTS, SEPTEMBER 2024-AUGUST 2026
- TABLE 172 HD MAPS MARKET: DEALS, JANUARY 2026-AUGUST 2026
- TABLE 173 HD MAPS MARKET: EXPANSIONS, FEBRUARY 2026-AUGUST 2026
- TABLE 174 HD MAPS MARKET: OTHER DEVELOPMENTS, JANUARY 2026-AUGUST 2026
- TABLE 175 HERE: COMPANY OVERVIEW
- TABLE 176 HERE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 177 HERE: DEALS
- TABLE 178 HERE: OTHER DEVELOPMENTS
- TABLE 179 BAIDU: COMPANY OVERVIEW
- TABLE 180 BAIDU: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 181 BAIDU: DEALS
- TABLE 182 TOMTOM INTERNATIONAL BV: COMPANY OVERVIEW
- TABLE 183 TOMTOM INTERNATIONAL BV: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 184 TOMTOM INTERNATIONAL BV: PRODUCT/SERVICE LAUNCHES/ENHANCEMENTS
- TABLE 185 TOMTOM INTERNATIONAL BV: DEALS
- TABLE 186 TOMTOM INTERNATIONAL BV: OTHER DEVELOPMENTS
- TABLE 187 NVIDIA CORPORATION: COMPANY OVERVIEW
- TABLE 188 NVIDIA CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 189 NVIDIA CORPORATION: DEALS
- TABLE 190 MOBILEYE: COMPANY OVERVIEW
- TABLE 191 MOBILEYE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 192 MOBILEYE: DEALS
- TABLE 193 MOBILEYE: OTHER DEVELOPMENTS
- TABLE 194 WAYMO LLC: COMPANY OVERVIEW
- TABLE 195 WAYMO LLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 196 WAYMO LLC: DEALS
- TABLE 197 WAYMO LLC: EXPANSIONS
- TABLE 198 WAYMO LLC: OTHER DEVELOPMENTS
- TABLE 199 DYNAMIC MAP PLATFORM CO., LTD.: COMPANY OVERVIEW
- TABLE 200 DYNAMIC MAP PLATFORM CO., LTD.: GROUP COMPANIES
- TABLE 201 DYNAMIC MAP PLATFORM CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 202 DYNAMIC MAP PLATFORM CO., LTD.: PRODUCT/SERVICE LAUNCHES/ENHANCEMENTS
- TABLE 203 DYNAMIC MAP PLATFORM CO., LTD.: DEALS
- TABLE 204 DYNAMIC MAP PLATFORM CO., LTD.: EXPANSIONS
- TABLE 205 DYNAMIC MAP PLATFORM CO., LTD.: OTHER DEVELOPMENTS
- TABLE 206 NAVINFO CO., LTD.: COMPANY OVERVIEW
- TABLE 207 NAVINFO CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 208 NAVINFO CO., LTD.: DEALS
- TABLE 209 NAVINFO CO., LTD.: OTHER DEVELOPMENTS
- TABLE 210 THE SANBORN MAP COMPANY, INC.: COMPANY OVERVIEW
- TABLE 211 THE SANBORN MAP COMPANY, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 212 THE SANBORN MAP COMPANY, INC.: DEVELOPMENTS
- TABLE 213 MOMENTA: COMPANY OVERVIEW
- TABLE 214 MOMENTA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 215 MAPBOX: COMPANY OVERVIEW
- TABLE 216 MAPBOX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 217 MAPBOX: PRODUCT/SERVICE LAUNCHES/ENHANCEMENTS
- TABLE 218 MAPBOX: DEALS
- TABLE 219 CE INFO SYSTEMS LTD.: COMPANY OVERVIEW
- TABLE 220 CE INFO SYSTEMS LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 221 CE INFO SYSTEMS LTD.: DEALS
- TABLE 222 NAVMII: COMPANY OVERVIEW
- TABLE 223 RMSI: COMPANY OVERVIEW
- TABLE 224 ZENRIN CO., LTD.: COMPANY OVERVIEW
- TABLE 225 WOVEN BY TOYOTA, INC.: COMPANY OVERVIEW
- TABLE 226 SWIFT NAVIGATION, INC.: COMPANY OVERVIEW
- TABLE 227 EXLSERVICE HOLDINGS, INC.: COMPANY OVERVIEW
- TABLE 228 ROBOTIC DATA: COMPANY OVERVIEW
- TABLE 229 HYUNDAI AUTOEVER CORP.: COMPANY OVERVIEW
- TABLE 230 GENESYS INTERNATIONAL CORPORATION LTD: COMPANY OVERVIEW
- TABLE 231 GEOMATE: COMPANY OVERVIEW
- TABLE 232 INTELLIAS: COMPANY OVERVIEW
- TABLE 233 MORAI INC.: COMPANY OVERVIEW
- TABLE 234 TRIMBLE INC.: COMPANY OVERVIEW
- TABLE 235 PRIMARY INTERVIEW PARTICIPANTS
- TABLE 236 HD MAPS MARKET: RESEARCH ASSUMPTIONS
- TABLE 237 HD MAPS MARKET: RISK ANALYSIS
List of Figures
- FIGURE 1 HD MAPS MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 HD MAPS MARKET: DURATION CONSIDERED
- FIGURE 3 HD MAPS MARKET SIZE, 2022-2033
- FIGURE 4 HD MAPS MARKET SCENARIO
- FIGURE 5 KEY MARKET PARCTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- FIGURE 6 DISRUPTIVE TRENDS IMPACTING GROWTH OF HD MAPS MARKET DURING FORECAST PERIOD
- FIGURE 7 HIGH-GROWTH SEGMENTS IN HD MAPS MARKET
- FIGURE 8 ASIA PACIFIC TO DOMINATE HD MAPS MARKET DURING FORECAST PERIOD
- FIGURE 9 ADVANCEMENTS IN AUTONOMOUS DRIVING TECHNOLOGY AND SUPPORTIVE GOVERNMENT INITIATIVES TO DRIVE HD MAPS MARKET
- FIGURE 10 UPDATE & MAINTENANCE SEGMENT TO EXHIBIT HIGHER CAGR FROM 2026 TO 2033 DUE TO CONTINUOUS MAP CHANGE DETECTION
- FIGURE 11 COMMERCIAL VEHICLE SEGMENT TO BE THE FASTER GROWING MARKET DURING FORECAST PERIOD DUE TO LANE LEVEL ADAS AND AUTOMATED DRIVING DEPLOYMENT
- FIGURE 12 CLOUD-BASED SEGMENT TO GROW AT FASTER RATE BETWEEN 2026 AND 2033 DUE TO VEHICLE DATA PROCESSING AND OTA MAP UPDATES
- FIGURE 13 SEMI-AUTONOMOUS VEHICLE SEGMENT TO DOMINATE MARKET FROM 2026 TO 2033 DUE TO L2 AND L3 HD MAP LOCALIZATION
- FIGURE 14 COMMERCIAL MOBILITY SEGMENT TO GROW AT SIGNIFICANT RATE DURING FORECAST PERIOD DUE TO HIGH VOLUME VEHICLE BASED MAP DATA DEMAND
- FIGURE 15 ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026 DUE INTELLIGENT VEHICLE AND AUTONOMOUS DRIVING DEPLOYMENT
- FIGURE 16 FUNCTIONS OF HD MAPS IN AUTONOMOUS DRIVING VEHICLES
- FIGURE 17 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 18 HD MAPS ECOSYSTEM ANALYSIS
- FIGURE 19 HD MAPS SUPPLY CHAIN ANALYSIS
- FIGURE 20 INVESTMENT AND FUNDING SCENARIO, 2024-2026
- FIGURE 21 IMPORT DATA FOR HS CODE 852691-COMPLIANT PRODUCTS FOR KEY COUNTRIES, 2021-2025
- FIGURE 22 EXPORT DATA FOR HS CODE 852691-COMPLIANT PRODUCTS FOR KEY COUNTRIES, 2021-2025
- FIGURE 23 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 24 PATENTS APPLIED AND GRANTED, 2017-2026
- FIGURE 25 PHASED ADOPTION STRATEGY OF HD MAPS IN AV ECOSYSTEM
- FIGURE 26 VEHICLE LOCALIZATION
- FIGURE 27 FUTURE DEPLOYMENT AREAS OF HD MAPS
- FIGURE 28 EVOLUTION FROM SD MAPS TO DYNAMIC HD MAPS
- FIGURE 29 EVOLUTION FROM STATIC MAP TO CONTINUOUSLY UPDATED MAP
- FIGURE 30 OEM TCO PER VEHICLE
- FIGURE 31 HD MAP SUPPLIER TCO PER KILOMETRE
- FIGURE 32 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY VEHICLE TYPE
- FIGURE 33 KEY BUYING CRITERIA, BY VEHICLE TYPE
- FIGURE 34 SEMI-AUTONOMOUS VEHICLE SEGMENT TO DOMINATE HD MAPS MARKET FROM 2026 TO 2033
- FIGURE 35 KEY PRIMARY INSIGHTS, BY LEVEL OF AUTOMATION
- FIGURE 36 MAPPING & LOCALIZATION SEGMENT TO CAPTURE LARGER MARKET SHARE IN 2026 AND 2033
- FIGURE 37 KEY PRIMARY INSIGHTS, BY SERVICE TYPE
- FIGURE 38 CLOUD-BASED SEGMENT TO HOLD LARGER SHARE OF HD MAPS MARKET IN 2026 AND 2033
- FIGURE 39 KEY PRIMARY INSIGHTS, BY SOLUTION TYPE
- FIGURE 40 PERSONAL MOBILITY SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE IN 2026 AND 2033
- FIGURE 41 KEY PRIMARY INSIGHTS, BY USAGE TYPE
- FIGURE 42 PASSENGER CAR SEGMENT TO DOMINATE HD MAPS MARKET FROM 2026 TO 2033
- FIGURE 43 KEY PRIMARY INSIGHTS, BY VEHICLE TYPE
- FIGURE 44 ASIA PACIFIC TO CAPTURE LARGEST SHARE OF HD MAPS MARKET IN 2026 AND 2033
- FIGURE 45 ASIA PACIFIC: HD MAPS MARKET SNAPSHOT
- FIGURE 46 NORTH AMERICA: HD MAPS MARKET SNAPSHOT
- FIGURE 47 MARKET SHARE ANALYSIS OF COMPANIES OFFERING HD MAPS, 2025
- FIGURE 48 HD MAPS MARKET: REVENUE ANALYSIS OF TOP FIVE PLAYERS, 2021-2025
- FIGURE 49 COMPANY VALUATION OF KEY PLAYERS
- FIGURE 50 FINANCIAL METRICS OF KEY PLAYERS
- FIGURE 51 BRAND/PRODUCT COMPARISON OF KEY PLAYERS
- FIGURE 52 HD MAPS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 53 HD MAPS MARKET: COMPANY FOOTPRINT
- FIGURE 54 HD MAPS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 55 HERE: PRODUCT SPECIFICATIONS
- FIGURE 56 BAIDU: COMPANY SNAPSHOT
- FIGURE 57 TOMTOM INTERNATIONAL BV: COMPANY SNAPSHOT
- FIGURE 58 NVIDIA CORPORATION: COMPANY SNAPSHOT
- FIGURE 59 MOBILEYE: COMPANY SNAPSHOT
- FIGURE 60 MOBILEYE: COMMON INDUSTRY APPROACH VS. MOBILEYE APPROACH
- FIGURE 61 MOBILEYE: REM SOLUTIONS FOR AUTONOMOUS VEHICLE MAPPING
- FIGURE 62 WAYMO LLC: COMPANY SNAPSHOT
- FIGURE 63 DYNAMIC MAP PLATFORM CO., LTD.: COMPANY SNAPSHOT
- FIGURE 64 NAVINFO CO., LTD.: COMPANY SNAPSHOT
- FIGURE 65 THE SANBORN MAP COMPANY, INC.: COMPANY SNAPSHOT
- FIGURE 66 MAPBOX: COMPANY SNAPSHOT
- FIGURE 67 CE INFO SYSTEMS LTD.: COMPANY SNAPSHOT
- FIGURE 68 HD MAPS MARKET: RESEARCH DESIGN
- FIGURE 69 DATA CAPTURED FROM SECONDARY SOURCES
- FIGURE 70 DATA CAPTURED FROM PRIMARY SOURCES
- FIGURE 71 CORE FINDINGS FROM INDUSTRY INSIGHTS
- FIGURE 72 BREAKDOWN OF PRIMARY INTERVIEWS, BY RESPONDENT TYPE, DESIGNATION, AND REGION
- FIGURE 73 HD MAPS MARKET: TOP-DOWN APPROACH
- FIGURE 74 HD MAPS MARKET: DATA TRIANGULATION
- FIGURE 75 HD MAPS MARKET: FACTOR ANALYSIS

 面向自動駕駛汽車的高清地圖市場:按組件、車輛類型、定價模式、應用和最終用戶分類-2026-2032年全球市場預測
 面向自動駕駛汽車的高解析度(HD)地圖市場:預測至2034年-按組件、地圖類型、技術、自動駕駛等級、應用、最終用戶和地區分類的全球分析汽車3D測繪系統市場:按組件、車輛類型、部署模式、應用和最終用戶分類-2026-2032年全球市場預測
 2035 年前自動駕駛汽車高精地圖市場分析與預測:類型、產品、服務、技術、組件、應用、部署、最終用戶、功能以自動駕駛汽車為導向的高清地圖市場預測(至2034年)-按組件、地圖類型、技術、自動化程度、應用、最終使用者和地區分類的全球分析
 2026年全球自動駕駛汽車高清地圖市場報告2026年全球自動駕駛汽車高精度地圖市場報告2026年全球高清地圖通訊市場報告
 以自動駕駛汽車為導向的高清地圖(HD Maps)市場規模、佔有率和成長分析(按技術類型、應用程式、用例、最終用戶、部署模式和地區分類)—2026-2033年產業預測
 2026-2034年全球汽車3D測繪系統市場規模、佔有率、趨勢和成長分析報告