


 |
市場調查報告書
商品編碼
2129355
全球人體組成分析儀市場(至2031年):依產品、用途類別、模式及最終用戶分類Body Composition Analyzers Market by Product, Usage, Modality, End User - Global Forecast to 2031 |
||||||


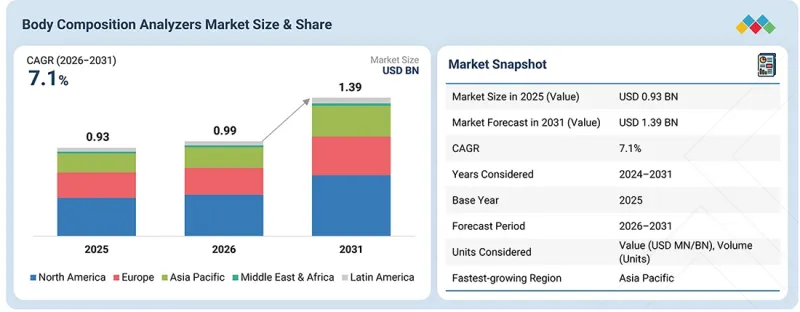
全球人體組成分析儀市場預計將從 2026 年的 9.9 億美元成長到 2031 年的 13.9 億美元,預測期內複合年成長率為 7.1%。
人體組成分析儀廣泛應用於醫院、診所、健身健康中心、學術研究機構和私人住宅。它們也用於根據個人的人體組成數據監測和調整健身計劃。亞太地區等新興市場蘊藏著巨大的成長潛力。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 單元 | 金額(美元) |
| 部分 | 產品、用途類別、模式、應用領域、最終用戶、地區 |
| 目標區域 | 北美、歐洲、亞太地區、拉丁美洲、中東和非洲 |
肥胖和代謝性疾病盛行率的上升、預防醫學的擴展以及對個人化營養和健身計劃需求的不斷成長,正在推動市場成長。此外,生物電電阻分析 (BIA) 技術的進步及其與數位健康平台和穿戴式設備的整合,使得更準確、互聯和便捷的身體組成監測成為可能,從而促進了整體市場成長。
“預計從 2026 年到 2031 年,生物電電阻分析 (BPI) 領域將呈現最高的成長率。”
從產品細分市場來看,電阻分析儀細分市場預計在預測期內將保持最高的成長率。其主要驅動力是電阻技術的不斷改進,從而提升了準確性、可靠性和易用性。此外,對無創體成分評估的需求不斷成長、多頻和部位特異性分析的日益普及以及健身和健康項目的蓬勃發展,也推動了該細分市場的成長。同時,家庭健康監測的增加以及與連網型設備和數位健康平台的整合也促進了該細分市場的發展。這些趨勢正在提升臨床和消費應用中的測量準確性、易用性、個人化和即時健康追蹤能力。
“到2025年,按身體部位進行身體組成分析這一細分市場將佔據最大的市場佔有率。”
與全身測量相比,節段性體組成分析能夠提供更精確的分析結果,深入了解身體特定部位的情況。這一領域的發展主要源自於人們對精準節段性體成分評估日益成長的需求,尤其是在監測脂肪分佈、肌肉量和體液平衡方面。隨著肥胖管理、運動表現、營養管理和臨床護理等領域的廣泛應用,節段性體成分分析的應用範圍也不斷擴大。多頻生物電阻抗分析(BIA)、8電極配置和數位分析技術的進步正在提升節段性測量的能力,而人們對個人化健身和健康管理方案日益成長的需求也推動了其更廣泛的應用。
“預計亞太地區在2026年至2031年間將經歷最快的成長。”
從區域來看,亞太地區預計將在預測期內成為人體組成分析儀市場成長最快的地區,這主要歸功於快速的都市化以及久坐少動、飲食不健康等生活方式的改變。人體成分分析儀透過提供詳細的人體成分信息,幫助人們應對日益成長的健康問題,滿足人們對有效健康管理解決方案的需求。該地區的市場成長主要受以下因素驅動:肥胖和代謝性疾病的增加、健康和健身意識的提高、醫療基礎設施的完善以及可支配收入的成長。健身俱樂部、健康計劃和預防性醫療保健措施的普及也進一步推動了這些產品的使用。尤其是在印度、中國、日本和東南亞地區,對價格適中、便攜且可連網的人體組成分析儀的需求不斷成長,加速了市場滲透。生物電電阻分析 (BIA) 技術的進步以及與數位健康的融合,正在拓展其在臨床、健身和家庭環境中的應用。
本報告考察了全球人體組成分析儀市場,提供了市場概述、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和閒置頻段
- 與相關市場和不同產業相關的跨領域機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 總體經濟指標
- GDP趨勢與預測
- 全球醫療保健產業趨勢
- 全球醫療設備業趨勢
- 供應鏈分析
- 價值鏈分析
- 生態系分析
- 價格分析
- 貿易分析
- 救贖方案
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢和顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 2025年美國關稅對人體成分秤市場的影響。
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要新興技術
- 互補技術
- 鄰近技術
- 技術/產品藍圖
- 短期(2025-2027)
- 中期計劃(2028-2030年)
- 長期(2030 年後)
- 專利分析
- 未來應用
- 人工智慧輔助的個人化身體組成管理
- 遠端/居家身體組成監測
- 應用於肥胖和體重管理
- 肌肉少症和肌肉健康評估
- 人工智慧/生成式人工智慧對身體組成量表的影響
第7章:監理情勢與永續性舉措
- 監理情勢
- 對永續性的承諾
第8章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第9章 人體組成分析儀市場:依產品分類
- 生物電電阻分析儀
- 多頻電阻分析儀
- 單頻電阻分析儀
- 雙頻電阻分析儀
- 雙能量X光吸收分析儀(DXA)
- 皮下脂肪厚度計
- 空氣置換式體積測量裝置
- 水下稱重裝置
第10章 人體組成監測儀市場:依用途分類
- 專業體成分秤
- 面向一般消費者的體成分秤
第11章 人體組成分析儀市場:依測量方法分類
- 可攜式體成分秤
- 固定式/桌上型人體組成分析儀
第12章 人體組成分析儀市場:依應用領域分類
- 依身體部位測量身體成分
- 全身成分測量
第13章 人體組成分析儀市場:依最終用戶分類
- 健身俱樂部及健康中心
- 醫院和診所
- 學術和研究中心
- 家庭用戶
第14章 人體組成分析儀市場:依地區分類
- 北美洲
- 宏觀經濟展望
- 定量分析
- 美國
- 加拿大
- 歐洲
- 宏觀經濟展望
- 定量分析
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 其他
- 亞太地區
- 宏觀經濟展望
- 定量分析
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他
- 拉丁美洲
- 宏觀經濟展望
- 定量分析
- 巴西
- 墨西哥
- 其他
- 中東和非洲
- 宏觀經濟展望
- 定量分析
- 海灣合作理事會國家
- 其他:海灣合作理事會國家
- 其他:中東和非洲
第15章 競爭格局
- 概述
- 主要參與企業的策略/優勢
- 收入分析
- 市佔率分析
- 企業估值矩陣:主要公司
- 企業企業發展
- 公司估值矩陣:新創企業/中小企業
- 企業估值和財務指標
- 品牌/產品對比
- 競爭格局
第16章:公司簡介
- 大公司
- GE HEALTHCARE
- OMRON CORPORATION
- HOLOGIC, INC.
- INBODY CO., LTD.
- SELVAS HEALTHCARE, INC.
- IMPEDIMED LIMITED
- DMS IMAGING
- A&D COMPANY, LIMITED
- XIAOMI CORPORATION
- TANITA CORPORATION
- SECA
- WITHINGS
- COSMED SRL
- RJL SYSTEMS
- CHARDER ELECTRONIC CO., LTD.
- BODYSTAT LIMITED
- 其他公司
- MALTRON INTERNATIONAL LTD.
- AKERN SRL
- BIOTEKNA
- BIODYNAMICS CORPORATION
- MICROLIFE CORPORATION
- NUMED SARL
- TONGYONG TIZHI HEALTH TECHNOLOGY CO., LTD.
- FOOK TIN TECHNOLOGIES LTD.
- OSTEOSYS CORP.
- EXERTECH
- SHANGHAI GOLDENWELL MEDICAL TECHNOLOGY CO., LTD.
第17章調查方法
第18章附錄
The global body composition analyzers market is anticipated to grow from USD 0.99 billion in 2026 to USD 1.39 billion by 2031, at a CAGR of 7.1% during the forecast period. Body composition analyzers are widely used by hospitals & clinics, fitness & wellness centers, academic & research centers, and home users. They are also used in monitoring and tailoring fitness programs based on individual body composition data. Emerging markets such as Asia Pacific offer lucrative market growth opportunities.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Product, Usage type, Modality, Application, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa |
Rising prevalence of obesity and metabolic disorders, growing adoption of preventive healthcare, and increasing demand for personalized nutrition and fitness programs drive the market. Furthermore, technological advancements in bioelectrical impedance analysis (BIA) and integration with digital health platforms and wearable devices enable more accurate, connected, and convenient body composition monitoring, driving the overall market.
"Bioimpedance analyzers segment to exhibit the highest growth rate from 2026 to 2031"
Based on product, the bioimpedance analyzers segment is likely to register the highest growth rate in the body composition analyzers market during the forecast period. Major driving factors include continuous improvements in bioimpedance technology to enhance accuracy, reliability, and user-friendliness. The rising demand for non-invasive body composition assessment, growing adoption of multifrequency and segmental analysis, and expansion of fitness and wellness programs also contribute to the segmental growth. Additionally, increasing home-based health monitoring and integration with connected devices and digital health platforms drive the segment. These trends are enhancing measurement accuracy, accessibility, personalization, and real-time health tracking across clinical and consumer applications.
"Segmental body measurement segment captured the largest market share in 2025"
Based on application, the segmental body measurement segment accounted for the largest share of the body composition analyzers market in 2025. Segmental body measurement offers more precise and accurate analysis compared with whole-body measurements, providing detailed insights into specific areas of the body. The segment is driven by growing demand for precise regional body composition assessment, particularly for monitoring fat distribution, muscle mass, and fluid balance. Increasing adoption in obesity management, sports performance, nutrition, and clinical care is expanding applications. Technological advances in multifrequency BIA, octopolar configurations, and digital analytics are improving regional measurement capabilities, while demand for personalized fitness and healthcare programs is encouraging broader adoption.
"Asia Pacific to be the fastest-growing regional market between 2026 and 2031"
Based on region, Asia Pacific is expected to register the highest growth rate in the body composition analyzers market during the forecast period, mainly due to rapid urbanization and lifestyle changes, such as sedentary habits and poor diets. These devices help address emerging health concerns by providing detailed insights into body composition, which reflects the growing need for effective health management solutions. The regional market is driven by rising obesity and metabolic disorders, increasing health and fitness awareness, expanding healthcare infrastructure, and growing disposable incomes. Adoption is further supported by the expansion of fitness clubs, wellness programs, and preventive healthcare initiatives. Demand for affordable, portable, and connected analyzers, particularly across India, China, Japan, and Southeast Asia, is also accelerating market penetration. Technological advancements in BIA and digital health integration are broadening clinical, fitness, and home-use applications.
A breakdown of the primary participants referred to for this report is provided below:
- By Company Type: Tier 1-35%, Tier 2-40%, and Tier 3-25%
- By Designation: Directors-25%, Managers-50%, and Others-25%
- By Region: North America-43%, Europe-14%, Asia Pacific-26%, Latin America- 12%, and the Middle East & Africa- 5%
Prominent players in the body composition analyzers market include GE HealthCare (US), OMRON Corporation (Japan), Hologic, Inc. (US), InBody Co., Ltd. (South Korea), Tanita Corporation (Japan), seca (Germany), Withings (France), SELVAS Healthcare, Inc. (South Korea), COSMED srl (Italy), and RJL Systems (US).
Research Coverage
This report studies the body composition analyzers market based on product, usage type, modality, application, end user, and region. It also covers the factors affecting market growth, analyzes the various opportunities and challenges in the market, and provides details of the competitive landscape for market leaders. Furthermore, the report analyzes micro markets with respect to their individual growth trends. It forecasts the revenue of the market segments with respect to five main regions (and the respective countries in these regions).
Reasons to Buy the Report
The report will enable established firms as well as entrants/smaller firms to gauge the pulse of the market, which, in turn, would help them to garner a larger market share. Firms purchasing the report could use one or a combination of the below-mentioned strategies to strengthen their market presence.
This report provides insights into the following pointers:
- Analysis of key drivers (Rising prevalence of obesity and focus on body fat and muscle mass assessment, Growing adoption of body composition analysis in weight management and preventive healthcare), restraints (Limited reimbursement for routine body composition assessment, High sensitivity of bioimpedance measurements to hydration status and measurement conditions), opportunities (Increasing establishment of fitness, wellness and sports performance centers, Mounting demand for connected and data-driven monitoring), and challenges (Lack of standardization, Competition from established clinical imaging technologies) influencing the growth of the body composition analyzers market
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product launches in the market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the market across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings of leading players such as Omron Corporation (Japan), Hologic Inc. (US), and GE Healthcare (US)
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN BODY COMPOSITION ANALYZERS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 BODY COMPOSITION ANALYZERS MARKET OVERVIEW
- 3.2 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY END USER AND COUNTRY (2025)
- 3.3 BODY COMPOSITION ANALYZERS MARKET: REGION (2026-2031)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising prevalence of obesity and increasing focus on body fat and muscle mass assessment
- 4.2.1.2 Growing adoption of body composition analysis in weight management and preventive healthcare
- 4.2.1.3 Growing geriatric population and rising demand for sarcopenia & muscle mass monitoring
- 4.2.2 RESTRAINTS
- 4.2.2.1 Limited reimbursement for routine body composition assessment
- 4.2.2.2 High sensitivity of bioimpedance measurements to hydration status and measurement conditions
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing establishment of fitness, wellness, and sports performance centers
- 4.2.3.2 Growing demand for connected and data-driven monitoring
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of standardization across BIA devices, algorithms, and measurement protocols
- 4.2.4.2 Competition from established clinical imaging technologies such as CT and MRI
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN BODY COMPOSITION ANALYZERS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES IN BODY COMPOSITION ANALYZERS MARKET
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT FROM NEW ENTRANTS
- 5.1.2 THREAT FROM SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL HEALTHCARE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL MEDICAL DEVICE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 MANUFACTURERS
- 5.5.2 END USERS
- 5.5.3 REGULATORY BODIES
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND, BY KEY PLAYER, 2023-2025
- 5.6.2 AVERAGE SELLING PRICE TREND, BY MODALITY, 2023-2025
- 5.6.3 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT DATA (HS CODE 901819)
- 5.7.2 EXPORT DATA (HS CODE 901819)
- 5.7.3 IMPORT DATA (HS CODE 903180)
- 5.7.4 EXPORT DATA FOR (HS CODE 903180)
- 5.8 REIMBURSEMENT SCENARIO
- 5.9 KEY CONFERENCES & EVENTS, 2026-2027
- 5.10 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.11 INVESTMENT & FUNDING SCENARIO
- 5.12 CASE STUDY ANALYSIS
- 5.13 IMPACT OF 2025 US TARIFFS-BODY COMPOSITION ANALYZERS MARKET
- 5.13.1 INTRODUCTION
- 5.13.2 KEY TARIFF RATES
- 5.13.3 PRICE IMPACT ANALYSIS
- 5.13.4 IMPACT ON COUNTRIES/REGIONS
- 5.13.5 IMPACT ON END-USE SEGMENTS
- 5.13.5.1 Hospitals & clinics
- 5.13.5.2 Fitness clubs & wellness centers
- 5.13.5.3 Academic & research centers
- 5.13.5.4 Home Users
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.1.1.1 Wearable body composition monitoring
- 6.1.1.2 AI-enabled body composition analysis and smartphone-based assessment
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Cloud-based body composition data platforms
- 6.1.2.2 Digital nutrition and weight-management technologies
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 MRI and CT-based body composition analysis
- 6.1.3.2 Ultrasound body composition assessment
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 NEAR-TERM (2025-2027)
- 6.2.2 MID-TERM (2028-2030)
- 6.2.3 LONG-TERM (2030+)
- 6.3 PATENT ANALYSIS
- 6.3.1 JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 AI-ASSISTED PERSONALIZED BODY COMPOSITION MANAGEMENT
- 6.4.2 REMOTE AND HOME-BASED BODY COMPOSITION MONITORING
- 6.4.3 OBESITY AND WEIGHT-MANAGEMENT APPLICATIONS
- 6.4.4 SARCOPENIA AND MUSCLE-HEALTH ASSESSMENT
- 6.5 IMPACT OF AI/GEN AI ON BODY COMPOSITION ANALYZERS
- 6.5.1 INTRODUCTION
- 6.5.2 MARKET POTENTIAL OF AI IN BODY COMPOSITION ANALYZERS
- 6.5.3 AI USE CASES
- 6.5.4 KEY COMPANIES IMPLEMENTING AI
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY FRAMEWORK
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.4 Latin America
- 7.1.1.5 Middle East & Africa
- 7.1.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.3 INDUSTRY STANDARDS
- 7.1.1 REGULATORY FRAMEWORK
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 REDUCING MEDICAL WASTE & USE OF LOWER-IMPACT MATERIALS AND PACKAGING
- 7.2.2 WATER, ENERGY, AND RESOURCE EFFICIENCY
- 7.2.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS & BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN THE BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT
- 9.1 INTRODUCTION
- 9.2 BIOIMPEDANCE ANALYZERS
- 9.2.1 MULTI-FREQUENCY BIOIMPEDANCE ANALYZERS
- 9.2.1.1 Detailed body water and segmental assessment supporting demand
- 9.2.1.2 Global volume analysis of multi-frequency bioimpedance analyzers, 2024-2031 (units)
- 9.2.2 SINGLE-FREQUENCY BIOIMPEDANCE ANALYZERS
- 9.2.2.1 Cost-effective assessment expanding accessibility
- 9.2.2.2 Global volume analysis of single-frequency bioimpedance analyzers, 2024-2031 (units)
- 9.2.3 DUAL-FREQUENCY BIOIMPEDANCE ANALYZERS
- 9.2.3.1 Enhanced fluid assessment and practical measurement supporting adoption
- 9.2.3.2 Global volume analysis of dual-frequency bioimpedance analyzers, 2024-2031 (units)
- 9.2.1 MULTI-FREQUENCY BIOIMPEDANCE ANALYZERS
- 9.3 DUAL-ENERGY X-RAY ABSORPTIOMETRY EQUIPMENT
- 9.3.1 COMPREHENSIVE BONE AND BODY COMPOSITION ASSESSMENT SUPPORTING ADOPTION
- 9.4 SKINFOLD CALIPERS
- 9.4.1 SIMPLE MEASUREMENT OF SUBCUTANEOUS FAT SUPPORTING CONTINUED USE
- 9.5 AIR DISPLACEMENT PLETHYSMOGRAPHY EQUIPMENT
- 9.5.1 RAPID ASSESSMENT AND COST-EFFECTIVE TESTING SUPPORTING ADOPTION
- 9.6 HYDROSTATIC WEIGHING EQUIPMENT
- 9.6.1 ESTABLISHED BODY DENSITY METHOD SUPPORTING NICHE APPLICATIONS
10 BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE
- 10.1 INTRODUCTION
- 10.2 PROFESSIONAL-GRADE BODY COMPOSITION ANALYZERS
- 10.2.1 EXPANDING FITNESS AND SPECIALIZED ASSESSMENT FACILITIES SUPPORTING DEMAND
- 10.3 CONSUMER-GRADE BODY COMPOSITION ANALYZERS
- 10.3.1 ADVANCEMENTS IN CONNECTED AND HOME-BASED MONITORING SUPPORTING GROWTH
11 BODY COMPOSITION ANALYZERS MARKET, BY MODALITY
- 11.1 INTRODUCTION
- 11.2 PORTABLE BODY COMPOSITION ANALYZERS
- 11.2.1 MOBILITY AND WIRELESS DATA CONNECTIVITY SUPPORTING BROADER ADOPTION
- 11.3 STATIONARY/BENCHTOP BODY COMPOSITION ANALYZERS
- 11.3.1 STANDARDIZED MEASUREMENT AND PROFESSIONAL-GRADE FEATURES SUPPORTING ADOPTION
12 BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 SEGMENTAL BODY MEASUREMENT
- 12.2.1 DETAILED REGIONAL ANALYSIS SUPPORTING PERSONALIZED ASSESSMENT
- 12.3 WHOLE-BODY MEASUREMENT
- 12.3.1 COMPREHENSIVE BODY COMPOSITION ASSESSMENT SUPPORTING WIDER APPLICATION
13 BODY COMPOSITION ANALYZERS MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 FITNESS CLUBS & WELLNESS CENTERS
- 13.2.1 EXPANDING FITNESS INFRASTRUCTURE SUPPORTING DEMAND
- 13.3 HOSPITALS & CLINICS
- 13.3.1 OSTEOPOROSIS ASSESSMENT AND CLINICAL BODY COMPOSITION MONITORING SUPPORTING DEMAND
- 13.4 ACADEMIC & RESEARCH CENTERS
- 13.4.1 INCREASING RESEARCH FUNDING AND TECHNOLOGY VALIDATION ACTIVITIES SUPPORTING DEMAND
- 13.5 HOME USERS
- 13.5.1 CONNECTED AND USER-FRIENDLY DEVICES SUPPORTING HOME-BASED MONITORING
14 BODY COMPOSITION ANALYZERS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 14.2.2 NORTH AMERICA: VOLUME ANALYSIS, 2024-2031 (UNITS)
- 14.2.3 US
- 14.2.3.1 High Obesity Prevalence and Growing Need for Direct Body Composition Assessment Driving Market Growth
- 14.2.4 CANADA
- 14.2.4.1 Increasing Adiposity and Growing Attention to Abdominal Fat Assessment Supporting Market Growth
- 14.3 EUROPE
- 14.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 14.3.2 EUROPE: VOLUME ANALYSIS, 2024-2031 (UNITS)
- 14.3.3 GERMANY
- 14.3.3.1 Widespread Excess Weight and Rising Demand for More Detailed Body Assessment Supporting Market Growth
- 14.3.4 FRANCE
- 14.3.4.1 Growing Clinical Use of Body Composition Assessment in Obesity Care Supporting Market Growth
- 14.3.5 UK
- 14.3.5.1 Expansion of Large-Scale Body Composition Research Supporting Demand for Advanced Assessment Technologies
- 14.3.6 ITALY
- 14.3.6.1 Growing Adoption of Body Composition Assessment in Obesity Management Supporting Market Expansion
- 14.3.7 SPAIN
- 14.3.7.1 Increasing Use of Body Composition Monitoring in Obesity and Metabolic Health Supporting Market Growth
- 14.3.8 REST OF EUROPE
- 14.4 ASIA PACIFIC
- 14.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 14.4.2 ASIA PACIFIC: VOLUME ANALYSIS, 2024-2031 (UNITS)
- 14.4.3 CHINA
- 14.4.3.1 Rising cases of obesity in children to propel the market
- 14.4.4 JAPAN
- 14.4.4.1 Growing Emphasis on Healthy Aging and Muscle Mass Assessment Creating Demand for Body Composition Technologies
- 14.4.5 INDIA
- 14.4.5.1 Expanding Obesity Management Initiatives and Greater Focus on Body Fat Assessment Driving Market Growth
- 14.4.6 AUSTRALIA
- 14.4.6.1 Use of body composition assessment in high-performance sports to sustain demand
- 14.4.7 SOUTH KOREA
- 14.4.7.1 Evolving Obesity Assessment Practices Driving Demand for Body Composition Technologies
- 14.4.8 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 14.5.2 LATIN AMERICA: VOLUME ANALYSIS, 2024-2031 (UNITS)
- 14.5.3 BRAZIL
- 14.5.3.1 Strengthening Obesity Management Practices Creating Opportunities for Body Composition Assessment
- 14.5.4 MEXICO
- 14.5.4.1 Increasing Emphasis on Comprehensive Obesity Assessment Creating Opportunities for Body Composition Technologies
- 14.5.5 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MIDDLE EAST & AFRICA: MACROECONOMIC OUTLOOK
- 14.6.2 MIDDLE EAST & AFRICA: VOLUME ANALYSIS, 2024-2031 (UNITS)
- 14.6.3 GCC COUNTRIES
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.3.1.1 Expanding weight management programs creating opportunities for body composition assessment
- 14.6.3.2 UAE
- 14.6.3.2.1 Rising emphasis on obesity prevention and weight management to propel market
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.4 REST OF GCC COUNTRIES
- 14.6.5 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN THE BODY COMPOSITION ANALYZERS MARKET
- 15.3 REVENUE ANALYSIS
- 15.4 MARKET SHARE ANALYSIS
- 15.4.1 GLOBAL BODY COMPOSITION ANALYZERS MARKET SHARE ANALYSIS, 2025
- 15.4.2 US BODY COMPOSITION ANALYZERS MARKET SHARE ANALYSIS, 2025
- 15.4.3 EUROPE BODY COMPOSITION ANALYZERS MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.6 COMPANY FOOTPRINT
- 15.6.1 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.6.1.1 Company footprint
- 15.6.1.2 Region footprint
- 15.6.1.3 Product footprint
- 15.6.1.4 Modality footprint
- 15.6.1.5 Usage type footprint
- 15.6.1.6 Application footprint
- 15.6.1 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.7.1 PROGRESSIVE COMPANIES
- 15.7.2 RESPONSIVE COMPANIES
- 15.7.3 DYNAMIC COMPANIES
- 15.7.4 STARTING BLOCKS
- 15.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.7.5.1 Detailed list of key startups/SMEs
- 15.7.5.2 Competitive benchmarking of key startups/SMEs
- 15.8 COMPANY VALUATION & FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 BRAND/PRODUCT COMPARISON
- 15.10 COMPETITIVE SCENARIO
- 15.10.1 PRODUCT LAUNCHES & APPROVALS
- 15.10.2 DEALS
- 15.10.3 EXPANSIONS
- 15.10.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 GE HEALTHCARE
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Deals
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths/Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 OMRON CORPORATION
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Deals
- 16.1.2.3.2 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key strengths/Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses & competitive threats
- 16.1.3 HOLOGIC, INC.
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key strengths/Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses & competitive threats
- 16.1.4 INBODY CO., LTD.
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches & approvals
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key strengths/Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses & competitive threats
- 16.1.5 SELVAS HEALTHCARE, INC.
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Other developments
- 16.1.6 IMPEDIMED LIMITED
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.7 DMS IMAGING
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Product launches & approvals
- 16.1.7.3.2 Deals
- 16.1.8 A&D COMPANY, LIMITED
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.9 XIAOMI CORPORATION
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Product launches & approvals
- 16.1.10 TANITA CORPORATION
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Product launches & approvals
- 16.1.10.3.2 Deals
- 16.1.11 SECA
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Product launches
- 16.1.11.3.2 Deals
- 16.1.12 WITHINGS
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Product & services launches
- 16.1.12.3.2 Deals
- 16.1.13 COSMED S.R.L.
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Deals
- 16.1.14 RJL SYSTEMS
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.15 CHARDER ELECTRONIC CO., LTD.
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Other developments
- 16.1.16 BODYSTAT LIMITED
- 16.1.16.1 Business overview
- 16.1.16.2 Products offered
- 16.1.1 GE HEALTHCARE
- 16.2 OTHER PLAYERS
- 16.2.1 MALTRON INTERNATIONAL LTD.
- 16.2.2 AKERN S.R.L.
- 16.2.3 BIOTEKNA
- 16.2.4 BIODYNAMICS CORPORATION
- 16.2.5 MICROLIFE CORPORATION
- 16.2.6 NUMED S.A.R.L.
- 16.2.7 TONGYONG TIZHI HEALTH TECHNOLOGY CO., LTD.
- 16.2.8 FOOK TIN TECHNOLOGIES LTD.
- 16.2.9 OSTEOSYS CORP.
- 16.2.10 EXERTECH
- 16.2.11 SHANGHAI GOLDENWELL MEDICAL TECHNOLOGY CO., LTD.
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Primary sources
- 17.1.2.2 Key data from primary sources
- 17.1.2.3 Key industry insights
- 17.1.2.4 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 APPROACH 1: COMPANY REVENUE ANALYSIS APPROACH
- 17.2.2 APPROACH 2: CUSTOMER-BASED MARKET ESTIMATION
- 17.2.3 APPROACH 3: TOP-DOWN APPROACH
- 17.2.4 APPROACH 4: BOTTOM-UP APPROACH
- 17.2.5 APPROACH 5: PRIMARY INTERVIEWS
- 17.2.6 APPROACH 6: DEMAND-SIDE APPROACH
- 17.2.7 APPROACH 7: VOLUME DATA ANALYSIS
- 17.3 DATA TRIANGULATION AND MARKET BREAKDOWN
- 17.4 MARKET SHARE ASSESSMENT
- 17.5 RESEARCH ASSUMPTIONS
- 17.5.1 STUDY ASSUMPTIONS
- 17.5.2 GROWTH RATE ASSUMPTIONS
- 17.6 RISK ASSESSMENT
- 17.6.1 RESEARCH LIMITATIONS
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.3.1 PRODUCT ANALYSIS
- 18.3.2 COMPANY INFORMATION
- 18.3.3 GEOGRAPHIC ANALYSIS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 STANDARD CURRENCY CONVERSION RATES
- TABLE 2 BODY COMPOSITION ANALYZERS MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 3 GDP CHANGE, BY KEY COUNTRY, 2021-2030 (USD BILLION)
- TABLE 4 LIST OF KEY BODY COMPOSITION ANALYZERS MANUFACTURERS
- TABLE 5 LIST OF KEY END USERS
- TABLE 6 LIST OF KEY REGULATORY BODIES
- TABLE 7 AVERAGE SELLING PRICE TREND OF PRODUCTS, BY KEY PLAYER, 2023-2025 (USD)
- TABLE 8 AVERAGE SELLING PRICE TREND, BY MODALITY, 2023-2025 (USD)
- TABLE 9 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025 (USD)
- TABLE 10 IMPORT DATA FOR HS CODE 901819-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 EXPORT DATA FOR HS CODE 901819-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 12 IMPORT DATA FOR HS CODE 903180-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 13 EXPORT DATA FOR HS CODE 903180-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 14 BODY COMPOSITION ANALYZERS MARKET: MAJOR CONFERENCES & EVENTS, 2026-2027
- TABLE 15 SECA MBCA - BODY COMPOSITION MONITORING DURING INJURY REHABILITATION
- TABLE 16 EVOLT 360 - GNC TULSA HILLS NUTRITION RETAIL APPLICATION
- TABLE 17 CHARDER ELECTRONIC - TAIWAN TECH FITNESS ASSESSMENT PROGRAM
- TABLE 18 RECIPROCAL TARIFF RATES ADJUSTED BY US, 2025
- TABLE 19 KEY PRODUCT-RELATED TARIFFS
- TABLE 20 NORTH AMERICA: IMPACT OF US TARIFF ON CANADA
- TABLE 21 ASIA PACIFIC: IMPACT OF US TARIFF ON CHINA, JAPAN, AND INDIA
- TABLE 22 EUROPE: IMPACT OF US TARIFF ON GERMANY AND UK
- TABLE 23 LATIN AMERICA: IMPACT OF US TARIFF ON MEXICO
- TABLE 24 BODY COMPOSITION ANALYZERS MARKET: KEY PATENTS, 2015-2026
- TABLE 25 COMPANIES IMPLEMENTING AI
- TABLE 26 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 27 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 28 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 29 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 30 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 31 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF BODY COMPOSITION ANALYZERS
- TABLE 32 KEY BUYING CRITERIA FOR BODY COMPOSITION ANALYZERS, BY END USER
- TABLE 33 BODY COMPOSITION ANALYZERS MARKET: ADOPTION BARRIERS & INTERNAL CHALLENGES
- TABLE 34 BODY COMPOSITION ANALYZERS MARKET: UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- TABLE 35 BODY COMPOSITION ANALYZERS MARKET: KEY PROFITABILITY DRIVERS
- TABLE 36 BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 37 PRODUCT: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 38 BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 39 BIOIMPEDANCE ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 40 KEY PLAYERS PROVIDING MULTI-FREQUENCY BIOIMPEDANCE ANALYZERS
- TABLE 41 MULTI-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 42 MULTI-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY REGION, 2024-2031 (UNITS)
- TABLE 43 KEY PLAYERS PROVIDING SINGLE-FREQUENCY BIOIMPEDANCE ANALYZERS
- TABLE 44 SINGLE-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 45 SINGLE-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY REGION, 2024-2031 (UNITS)
- TABLE 46 KEY PLAYERS PROVIDING DUAL-FREQUENCY BIOIMPEDANCE ANALYZERS
- TABLE 47 DUAL-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 48 DUAL-FREQUENCY BIOIMPEDANCE ANALYZERS MARKET, BY REGION, 2024-2031 (UNITS)
- TABLE 49 KEY PLAYERS PROVIDING DUAL-ENERGY X-RAY ABSORPTIOMETRY
- TABLE 50 DUAL-ENERGY X-RAY ABSORPTIOMETRY EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 51 KEY PLAYERS PROVIDING SKINFOLD CALIPERS
- TABLE 52 SKINFOLD CALIPERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 53 KEY PLAYERS PROVIDING AIR DISPLACEMENT PLETHYSMOGRAPHY
- TABLE 54 AIR DISPLACEMENT PLETHYSMOGRAPHY EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 55 KEY PLAYERS PROVIDING HYDROSTATIC WEIGHING EQUIPMENT
- TABLE 56 HYDROSTATIC WEIGHING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 57 BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 58 USAGE TYPE: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 59 PROFESSIONAL-GRADE BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 60 CONSUMER-GRADE BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 61 BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 62 MODALITY: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 63 PORTABLE BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 64 STATIONARY/BENCHTOP BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 65 BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 66 APPLICATION: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 67 BODY COMPOSITION ANALYZERS MARKET FOR SEGMENTAL BODY MEASUREMENT, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 68 BODY COMPOSITION ANALYZERS MARKET FOR WHOLE-BODY MEASUREMENT, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 69 BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 70 END USER: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 71 BODY COMPOSITION ANALYZERS MARKET FOR FITNESS CLUBS & WELLNESS CENTERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 72 BODY COMPOSITION ANALYZERS MARKET FOR HOSPITALS & CLINICS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 73 BODY COMPOSITION ANALYZERS MARKET FOR ACADEMIC & RESEARCH CENTERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 74 BODY COMPOSITION ANALYZERS MARKET FOR HOME USERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 75 BODY COMPOSITION ANALYZERS MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 76 NORTH AMERICA: BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (UNITS)
- TABLE 77 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 78 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 79 NORTH AMERICA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 80 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 81 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 82 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 83 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 84 US: MACROECONOMIC INDICATORS
- TABLE 85 US: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 86 US: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 87 US: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 88 US: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 89 US: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 90 US: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 91 CANADA: MACROECONOMIC INDICATORS
- TABLE 92 CANADA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 93 CANADA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 94 CANADA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 95 CANADA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 96 CANADA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 97 CANADA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 98 EUROPE: BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (UNITS)
- TABLE 99 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 100 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 101 EUROPE: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 102 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 103 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 104 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 105 EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 106 GERMANY: MACROECONOMIC INDICATORS
- TABLE 107 GERMANY: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 108 GERMANY: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 109 GERMANY: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 110 GERMANY: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 111 GERMANY: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 112 GERMANY: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 113 FRANCE: MACROECONOMIC INDICATORS
- TABLE 114 FRANCE: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 115 FRANCE: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 116 FRANCE: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 117 FRANCE: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 118 FRANCE: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 119 FRANCE: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 120 UK: MACROECONOMIC INDICATORS
- TABLE 121 UK: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 122 UK: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 123 UK: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 124 UK: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 125 UK: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 126 UK: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 127 ITALY: MACROECONOMIC INDICATORS
- TABLE 128 ITALY: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 129 ITALY: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 130 ITALY: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 131 ITALY: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 132 ITALY: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 133 ITALY: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 134 SPAIN: MACROECONOMIC INDICATORS
- TABLE 135 SPAIN: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 136 SPAIN: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 137 SPAIN: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 138 SPAIN: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 139 SPAIN: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 140 SPAIN: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 141 REST OF EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 142 REST OF EUROPE: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 143 REST OF EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 144 REST OF EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 145 REST OF EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 146 REST OF EUROPE: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 147 ASIA PACIFIC: BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (UNITS)
- TABLE 148 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 149 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 150 ASIA PACIFIC: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 151 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 152 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 153 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 154 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 155 CHINA: MACROECONOMIC INDICATORS
- TABLE 156 CHINA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 157 CHINA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 158 CHINA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 159 CHINA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 160 CHINA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 161 CHINA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 162 JAPAN: MACROECONOMIC INDICATORS
- TABLE 163 JAPAN: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 164 JAPAN: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 165 JAPAN: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 166 JAPAN: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 167 JAPAN: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 168 JAPAN: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 169 INDIA: MACROECONOMIC INDICATORS
- TABLE 170 INDIA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 171 INDIA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 172 INDIA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 173 INDIA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 174 INDIA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 175 INDIA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 176 AUSTRALIA: MACROECONOMIC INDICATORS
- TABLE 177 AUSTRALIA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 178 AUSTRALIA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 179 AUSTRALIA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 180 AUSTRALIA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 181 AUSTRALIA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 182 AUSTRALIA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 183 SOUTH KOREA: MACROECONOMIC INDICATORS
- TABLE 184 SOUTH KOREA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 185 SOUTH KOREA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 186 SOUTH KOREA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 187 SOUTH KOREA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 188 SOUTH KOREA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 189 SOUTH KOREA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 190 REST OF ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 191 REST OF ASIA PACIFIC: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 192 REST OF ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 193 REST OF ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 194 REST OF ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 195 REST OF ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 196 LATIN AMERICA: BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (UNITS)
- TABLE 197 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 198 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 199 LATIN AMERICA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 200 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 201 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 202 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 203 LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 204 BRAZIL: MACROECONOMIC INDICATORS
- TABLE 205 BRAZIL: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 206 BRAZIL: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 207 BRAZIL: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 208 BRAZIL: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 209 BRAZIL: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 210 BRAZIL: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 211 MEXICO: MACROECONOMIC INDICATORS
- TABLE 212 MEXICO: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 213 MEXICO: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 214 MEXICO: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 215 MEXICO: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 216 MEXICO: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 217 MEXICO: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 218 REST OF LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 219 REST OF LATIN AMERICA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 220 REST OF LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 221 REST OF LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 222 REST OF LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 223 REST OF LATIN AMERICA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 224 MIDDLE EAST & AFRICA: BIOIMPEDANCE ANALYZERS MARKET, BY TYPE, 2024-2031 (UNITS)
- TABLE 225 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 226 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 227 MIDDLE EAST & AFRICA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 228 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 229 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 230 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 231 MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 232 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 233 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 234 GCC COUNTRIES: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 235 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 236 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 237 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 238 GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 239 KINGDOM OF SAUDI ARABIA: MACROECONOMIC INDICATORS
- TABLE 240 KINGDOM OF SAUDI ARABIA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 241 KINGDOM OF SAUDI ARABIA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 242 KINGDOM OF SAUDI ARABIA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 243 KINGDOM OF SAUDI ARABIA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 244 KINGDOM OF SAUDI ARABIA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 245 KINGDOM OF SAUDI ARABIA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 246 UAE: MACROECONOMIC INDICATORS
- TABLE 247 UAE: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 248 UAE: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 249 UAE: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 250 UAE: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 251 UAE: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 252 UAE: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 253 REST OF GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 254 REST OF GCC COUNTRIES: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 255 REST OF GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 256 REST OF GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 257 REST OF GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 258 REST OF GCC COUNTRIES: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 259 REST OF MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY PRODUCT, 2024-2031 (USD MILLION)
- TABLE 260 REST OF MIDDLE EAST & AFRICA: BIOIMPEDANCE ANALYZERS MARKET, 2024-2031 (USD MILLION)
- TABLE 261 REST OF MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY MODALITY, 2024-2031 (USD MILLION)
- TABLE 262 REST OF MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY USAGE TYPE, 2024-2031 (USD MILLION)
- TABLE 263 REST OF MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 264 REST OF MIDDLE EAST & AFRICA: BODY COMPOSITION ANALYZERS MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 265 OVERVIEW OF STRATEGIES DEPLOYED BY KEY MANUFACTURING COMPANIES, JANUARY 2023-JULY 2026
- TABLE 266 BODY COMPOSITION ANALYZERS MARKET: DEGREE OF COMPETITION
- TABLE 267 US BODY COMPOSITION ANALYZERS MARKET: DEGREE OF COMPETITION
- TABLE 268 EUROPE BODY COMPOSITION ANALYZERS MARKET: DEGREE OF COMPETITION
- TABLE 269 BODY COMPOSITION ANALYZERS MARKET: REGION FOOTPRINT
- TABLE 270 BODY COMPOSITION ANALYZERS MARKET: PRODUCT FOOTPRINT
- TABLE 271 BODY COMPOSITION ANALYZERS MARKET: MODALITY FOOTPRINT
- TABLE 272 BODY COMPOSITION ANALYZERS MARKET: USAGE TYPE FOOTPRINT
- TABLE 273 BODY COMPOSITION ANALYZERS MARKET: APPLICATION FOOTPRINT
- TABLE 274 BODY COMPOSITION ANALYZERS MARKET: DETAILED LIST OF KEY START-UPS/SMES
- TABLE 275 BODY COMPOSITION ANALYZERS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 276 BODY COMPOSITION ANALYZERS MARKET: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 277 BODY COMPOSITION ANALYZERS MARKET: DEALS, JANUARY 2023- JULY 2026
- TABLE 278 BODY COMPOSITION ANALYZERS MARKET: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 279 BODY COMPOSITION ANALYZERS MARKET: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 280 GE HEALTHCARE: COMPANY OVERVIEW
- TABLE 281 GE HEALTHCARE: PRODUCTS OFFERED
- TABLE 282 GE HEALTHCARE: DEALS, JANUARY 2023-JULY 2026
- TABLE 283 OMRON CORPORATION: COMPANY OVERVIEW
- TABLE 284 OMRON CORPORATION: PRODUCTS OFFERED
- TABLE 285 OMRON CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 286 OMRON CORPORATION: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 287 HOLOGIC, INC.: COMPANY OVERVIEW
- TABLE 288 HOLOGIC, INC.: PRODUCTS OFFERED
- TABLE 289 HOLOGIC, INC.: DEALS, JANUARY 2023-JULY 2026
- TABLE 290 INBODY CO., LTD.: COMPANY OVERVIEW
- TABLE 291 INBODY CO., LTD.: PRODUCTS OFFERED
- TABLE 292 INBODY CO., LTD.: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 293 INBODY CO., LTD.: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 294 SELVAS HEALTHCARE, INC.: COMPANY OVERVIEW
- TABLE 295 SELVAS HEALTHCARE, INC.: PRODUCTS OFFERED
- TABLE 296 SELVAS HEALTHCARE, INC: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 297 IMPEDIMED LIMITED: COMPANY OVERVIEW
- TABLE 298 IMPEDIMED LIMITED: PRODUCTS OFFERED
- TABLE 299 DMS IMAGING: COMPANY OVERVIEW
- TABLE 300 DMS IMAGING: PRODUCTS OFFERED
- TABLE 301 DMS IMAGING: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 302 DMS IMAGING: DEALS, JANUARY 2023-JULY 2026
- TABLE 303 A&D COMPANY, LIMITED: COMPANY OVERVIEW
- TABLE 304 A&D COMPANY, LIMITED: PRODUCTS OFFERED
- TABLE 305 A&D COMPANY, LIMITED: DEALS, JANUARY 2023-JULY 2026
- TABLE 306 XIAOMI CORPORATION: COMPANY OVERVIEW
- TABLE 307 XIAOMI CORPORATION: PRODUCTS OFFERED
- TABLE 308 XIAOMI CORPORATION: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 309 TANITA CORPORATION: COMPANY OVERVIEW
- TABLE 310 TANITA CORPORATION: PRODUCTS
- TABLE 311 TANITA CORPORATION: PRODUCT LAUNCHES & APPROVALS, JANUARY 2023-JULY 2026
- TABLE 312 TANITA CORPORATION: DEALS, JANUARY 2023-JULY 2026
- TABLE 313 SECA: COMPANY OVERVIEW
- TABLE 314 SECA: PRODUCTS OFFERED
- TABLE 315 SECA: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 316 SECA: DEALS, JANUARY 2023-JULY 2026
- TABLE 317 WITHINGS: COMPANY OVERVIEW
- TABLE 318 WITHINGS: PRODUCTS OFFERED
- TABLE 319 WITHINGS: PRODUCT AND SERVICES LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 320 WITHINGS: DEALS, JANUARY 2023-JULY 2026
- TABLE 321 COSMED S.R.L.: COMPANY OVERVIEW
- TABLE 322 COSMED S.R.L.: PRODUCTS OFFERED
- TABLE 323 COSMED S.R.L.: DEALS, JANUARY 2023-JULY 2026
- TABLE 324 RJL SYSTEMS: COMPANY OVERVIEW
- TABLE 325 RJL SYSTEMS: PRODUCTS OFFERED
- TABLE 326 CHARDER ELECTRONIC CO., LTD.: COMPANY OVERVIEW
- TABLE 327 CHARDER ELECTRONIC CO., LTD.: PRODUCTS OFFERED
- TABLE 328 CHARDER ELECTRONIC CO., LTD.: OTHER DEVELOPMENTS, JANUARY 2023-JULY 2026
- TABLE 329 BODYSTAT LIMITED: COMPANY OVERVIEW
- TABLE 330 BODYSTAT LIMITED: PRODUCTS OFFERED
- TABLE 331 MALTRON INTERNATIONAL LTD.: COMPANY OVERVIEW
- TABLE 332 AKERN S.R.L.: COMPANY OVERVIEW
- TABLE 333 BIOTEKNA: COMPANY OVERVIEW
- TABLE 334 BIODYNAMICS CORPORATION: COMPANY OVERVIEW
- TABLE 335 MICROLIFE CORPORATION: COMPANY OVERVIEW
- TABLE 336 NUMED S.A.R.L.: COMPANY OVERVIEW
- TABLE 337 TONGYONG TIZHI HEALTH TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 338 FOOK TIN TECHNOLOGIES LTD.: COMPANY OVERVIEW
- TABLE 339 OSTEOSYS CORP.: COMPANY OVERVIEW
- TABLE 340 EXERTECH: COMPANY OVERVIEW
- TABLE 341 SHANGHAI GOLDENWELL MEDICAL TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
List of Figures
- FIGURE 1 MARKET SCENARIO
- FIGURE 2 GLOBAL BODY COMPOSITION ANALYZERS MARKET, 2024-2031
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN BODY COMPOSITION ANALYZERS MARKET, 2023-2025
- FIGURE 4 DISRUPTIONS INFLUENCING GROWTH OF BODY COMPOSITION ANALYZERS MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS IN BODY COMPOSITION ANALYZERS MARKET, 2026-2031
- FIGURE 6 ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 7 MARKET TRENDS SIGNAL STRONG FUTURE FOR PORTABLE, CONSUMER-GRADE, AND ADVANCED BODY COMPOSITION ASSESSMENT
- FIGURE 8 HOSPITALS & CLINICS DOMINATED MARKET IN 2025
- FIGURE 9 CHINA TO REGISTER HIGHEST GROWTH RATE TILL 2031
- FIGURE 10 BODY COMPOSITION ANALYZERS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 11 2030 PROJECTIONS: MEN VS. WOMEN, BY BMI CATEGORY
- FIGURE 12 BODY COMPOSITION ANALYZERS MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 13 BODY COMPOSITION ANALYZERS MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 14 BODY COMPOSITION ANALYZERS MARKET: VALUE CHAIN ANALYSIS
- FIGURE 15 BODY COMPOSITION ANALYZERS MARKET ECOSYSTEM
- FIGURE 16 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY PRODUCT, 2025 (USD)
- FIGURE 17 AVERAGE SELLING PRICE TREND, BY MODALITY, 2025 (USD)
- FIGURE 18 AVERAGE SELLING PRICE TREND, BY REGION, 2025 (USD)
- FIGURE 19 REVENUE SHIFT AND NEW REVENUE POCKETS FOR BODY COMPOSITION ANALYZERS DEVICES MARKET
- FIGURE 20 INVESTMENT & FUNDING SCENARIO
- FIGURE 21 TOP APPLICANTS/OWNERS (COMPANIES/INSTITUTIONS) FOR BODY COMPOSITION ANALYZERS PATENTS, JANUARY 2015-JUNE 2026
- FIGURE 22 BODY COMPOSITION ANALYZERS MARKET: AI USE CASES
- FIGURE 23 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF BODY COMPOSITION ANALYZERS
- FIGURE 24 KEY BUYING CRITERIA FOR BODY COMPOSITION ANALYZERS, BY END USER
- FIGURE 25 NORTH AMERICA: BODY COMPOSITION ANALYZERS MARKET SNAPSHOT
- FIGURE 26 ASIA PACIFIC: BODY COMPOSITION ANALYZERS MARKET SNAPSHOT
- FIGURE 27 REVENUE ANALYSIS OF KEY PLAYERS IN BODY COMPOSITION ANALYZERS MARKET (2023-2025)
- FIGURE 28 GLOBAL BODY COMPOSITION ANALYZERS MARKET SHARE, 2025
- FIGURE 29 US BODY COMPOSITION ANALYZERS MARKET SHARE, 2025
- FIGURE 30 EUROPE BODY COMPOSITION ANALYZERS MARKET SHARE, 2025
- FIGURE 31 BODY COMPOSITION ANALYZERS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 32 BODY COMPOSITION ANALYZERS MARKET: COMPANY FOOTPRINT
- FIGURE 33 BODY COMPOSITION ANALYZERS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 34 EV/EBITDA OF KEY VENDORS
- FIGURE 35 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 36 BODY COMPOSITION ANALYZERS MARKET: BRAND/PRODUCT COMPARATIVE ANALYSIS
- FIGURE 37 GE HEALTHCARE: COMPANY SNAPSHOT (2025)
- FIGURE 38 OMRON CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 39 HOLOGIC, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 40 INBODY CO., LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 41 SELVAS HEALTHCARE, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 42 IMPEDIMED LIMITED: COMPANY SNAPSHOT (2025)
- FIGURE 43 DMS IMAGING: COMPANY SNAPSHOT (2025)
- FIGURE 44 A&D COMPANY, LIMITED: COMPANY SNAPSHOT (2025)
- FIGURE 45 XIAOMI CORPORATION: COMPANY SNAPSHOT (2025)
- FIGURE 46 BODY COMPOSITION ANALYZERS MARKET: RESEARCH DESIGN
- FIGURE 47 BREAKDOWN OF PRIMARY INTERVIEWS: SUPPLY-SIDE AND DEMAND-SIDE PARTICIPANTS
- FIGURE 48 BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 49 BREAKDOWN OF PRIMARY INTERVIEWS (DEMAND SIDE): BY END USER, DESIGNATION, AND REGION
- FIGURE 50 RESEARCH METHODOLOGY: HYPOTHESIS BUILDING
- FIGURE 51 MARKET SIZE APPROACH - REVENUE SHARE ANALYSIS
- FIGURE 52 REVENUE SHARE ANALYSIS ILLUSTRATION: GE HEALTHCARE (2025)
- FIGURE 53 TOP-DOWN APPROACH
- FIGURE 54 BOTTOM-UP APPROACH
- FIGURE 55 DEMAND-SIDE APPROACH
- FIGURE 56 CAGR PROJECTIONS FROM ANALYSIS OF DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES OF BODY COMPOSITION ANALYZERS MARKET (2026-2031)
- FIGURE 57 CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS
- FIGURE 58 DATA TRIANGULATION METHODOLOGY

 人體組成分析儀市場:全球市場預測(2026-2032)
 人體組成分析儀市場-全球產業規模、佔有率、趨勢、機會、預測:按產品、最終用戶、地區和競爭對手分類,2021-2031年
 人體組成分析儀市場報告:按產品、最終用戶和地區分類(2026-2034 年)
 全球人體組成分析儀市場:市場規模、佔有率、趨勢和成長分析(2026-2034)
 2026年全球人體組成監測儀市場報告超靈敏多元素電化學分析儀市場:依產品類型、技術、應用、最終用戶和銷售管道-2026年至2032年全球預測日本人體成分分析儀市場報告(按產品、最終用戶和地區分類,2026-2034)
 人體組成分析儀市場規模、佔有率和成長分析(按產品類型、模式、用途、應用和地區分類)—產業預測(2026-2033 年)
 人體組成監測儀市場規模、佔有率和趨勢分析報告:按產品、最終用途、地區和細分市場預測(2025-2033 年)
 印度的體脂秤市場:各產品,各種模式,各終端用戶,各地區,機會,預測,2019年~2033年