


 |
市場調查報告書
商品編碼
2119932
全球醫療保健產業室內定位資訊市場(至 2032 年):按服務細分(硬體、軟體、服務)、設施類型(醫院和醫療機構、老年護理機構)、技術(BLE、UWB、Wi-Fi、RFID、超音波、紅外線)和應用分類。Healthcare Indoor Location Market by Offering (Hardware, Software, Services), Facility Type (Hospitals & Healthcare, Senior Living), Technology (BLE, UWB, Wi-Fi, RFID, Ultrasound, Infrared), Application - Global Forecast to 2032 |
||||||


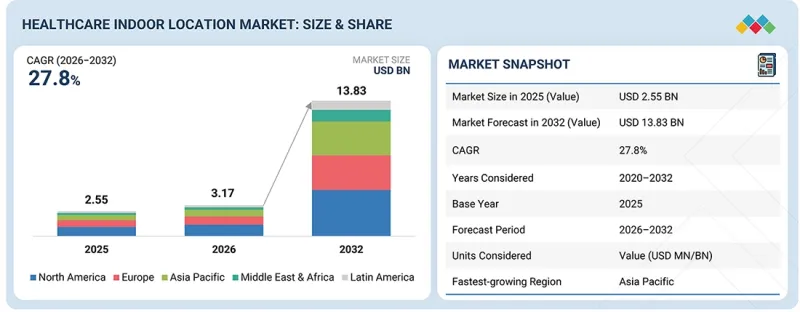
預計醫療領域室內定位解決方案的市場規模將從 2026 年的 31.7 億美元成長到 2032 年的 138.3 億美元,複合年成長率為 27.8%。
醫療機構正擴大採用基於位置的技術來提高臨床和非臨床環境的可見性。
| 調查範圍 | |
|---|---|
| 調查期 | 2020-2032 |
| 基準年 | 2025 |
| 預測期 | 2026-2032 |
| 單元 | 金額(美元) |
| 部分 | 按服務類別、技術、應用、設施類型和地區分類。 |
| 目標區域 | 北美洲、歐洲、亞太地區、中東和非洲、拉丁美洲 |
室內定位解決方案能夠實現醫療設備的定位、病患和醫護人員的行動監控、庫存管理以及安全相關工作流程的支援。 Wi-Fi、藍牙低功耗 (BLE)、無線射頻識別 (RFID)、超寬頻 (UWB)、超音波和紅外線等技術使醫療機構能夠根據其精度、覆蓋範圍和應用需求選擇合適的定位解決方案。
將位置資訊的應用範圍擴展到基本的資產追蹤之外,也創造了新的機會。醫療機構正在將室內定位功能與電子健康記錄 (EHR)、電腦化維護管理系統和其他營運平台整合,以支援患者流動、設備使用和工作流程管理。這種整合使醫療機構能夠從人工資源位置追蹤轉向更自動化、數據驅動的醫療運作。
“在預測期內,養老設施領域預計將錄得最高的複合年成長率。”
從設施類型來看,預計在預測期內,養老設施細分市場將實現最高的複合年成長率。由於老年人口不斷成長,以及人們對住戶安全的日益關注,養老設施正擴大採用能夠更清晰地提供住戶和員工位置資訊的技術。室內定位解決方案可以幫助輔助住宅和養老機構進行住戶監控、員工回應、資產管理以及基於位置的警報通知。
對更有效率護理服務日益成長的需求進一步推動了定位技術的應用。定位技術能夠幫助看護者找到住戶和所需設備,從而減少尋找資源的時間,並提高對安全事件的反應速度。隨著養老住家周邊設施營運商擴大採用互聯護理和數位化監控技術,室內定位解決方案有望在保障住戶福祉和提升營運效率方面發揮更關鍵的作用。此外,與醫院相比,這些技術的普及率相對較低,這意味著未來仍有巨大的應用空間。
“在預測期內,Wi-Fi 細分市場預計將佔據最大佔有率。”
從技術細分來看,Wi-Fi 部分預計將佔據最大佔有率。這是因為 Wi-Fi 基礎設施已在醫院和醫療機構廣泛部署。醫療機構可以利用現有的無線網路來支援基於位置的應用,而無需部署大規模的專用基礎設施。對於希望在大型複雜環境中實施室內定位的機構而言,這是一種實用且擴充性的方法。
基於 Wi-Fi 的定位功能支援多種應用,例如追蹤醫療設備、監控醫護人員、監控病患移動、室內導航和營運視覺化。醫療機構無線連線的持續擴展也提高了對應位置情報服務的覆蓋範圍和可靠性。此外,與醫院 IT 系統和其他連接技術的整合使得基於 Wi-Fi 的定位資訊能夠融入更廣泛的營運工作流程。這些優勢表明,Wi-Fi 將繼續保持其主導地位,尤其是在尋求可擴展定位部署的醫療服務提供者中。
“預計亞太地區在預測期內將錄得最高的成長率。”
預計亞太地區在預測期內將保持最高的成長率。醫療基礎設施投資的增加、數位轉型以及連網技術的應用,為醫院和其他醫療機構的定位解決方案創造了機會。亞太地區整體即時定位系統(RTLS)市場也正在快速擴張,醫療保健產業是其主要應用領域之一。
隨著醫療機構設施的現代化,預計該地區將擴大採用室內定位系統 (RTLS) 來管理醫療設備、病患流動、保障員工安全並提升庫存可視性。印度預計將成為該地區成長最快的醫療 RTLS 市場之一,而中國、日本和其他亞太國家則憑藉其成熟且不斷擴展的醫療基礎設施,也提供了發展機會。多種定位技術的應用將進一步推動區域成長。醫療機構可以根據所需的精度和應用場景,將現有的 Wi-Fi 基礎設施與 BLE、RFID、UWB 等技術相結合,從而在設施的各個區域擴展部署規模。
本報告檢視了全球醫療保健產業的室內定位資訊市場,提供了市場概述、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 與相關市場和不同產業相關的跨領域機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 宏觀經濟展望
- GDP趨勢與預測
- 醫療保健產業室內定位資訊市場的發展趨勢
- 供應鏈分析
- 生態系分析
- 定價模型分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 2025年美國關稅的影響-醫療保健室內定位市場
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 主要技術
- Bluetooth Low Energy (BLE)
- 超寬頻(UWB)
- RFID
- WI-FI
- 鄰近技術
- IoT
- 人工智慧和機器學習
- 邊緣運算
- 5G 和專用無線網路
- 互補技術
- 室內地圖和數位路線導航
- 感測器融合
- 穿戴式定位追蹤設備
- 地理空間分析
- 技術藍圖
- 短期(2026-2027)
- 中期計劃(2027-2028)
- 長期(2029-2030 年及以後)
- 專利分析
- 人工智慧/生成式人工智慧對醫療保健室內定位市場的影響
第7章 監理情勢
- 當地法規和合規性
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
第9章:醫療產業的室內定位資訊市場:依服務類別分類
- 硬體
- 標籤/徽章
- 閱讀器/追蹤器/網路基地台
- 其他
- 軟體
- 服務
- 實施與整合
- 支援與維護
- 諮詢
第10章:醫療產業的室內定位資訊市場:依技術分類
- RFID
- WI-FI
- UWB
- BLE
- 超音波
- 紅外線的
- 其他
第11章:醫療領域的室內定位資訊市場:按應用分類
- 庫存和資產追蹤與管理
- 人員位置核實和監控
- 存取控制和安全
- 環境監測
- 供應鏈管理與自動化
- 其他
第12章:醫療保健產業的室內定位資訊市場:依設施類型分類
- 醫院和醫療設施
- 老年人住宅設施
第13章:醫療保健產業的室內定位資訊市場:按地區分類
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 其他
- 亞太地區
- 中國
- 印度
- 日本
- 其他
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 其他
- 拉丁美洲
- 巴西
- 墨西哥
- 其他
第14章 競爭格局
- 主要參與企業的策略/優勢
- 市佔率分析
- 品牌/產品對比
- 企業估值和財務指標
- 企業估值象限
- 新創企業/中小企業評估矩陣
- 競爭格局
第15章:公司簡介
- 大公司
- SECURITAS HEALTHCARE
- ZEBRA TECHNOLOGIES
- CENTRAK
- TELETRACKING TECHNOLOGIES
- HID GLOBAL
- HPE ARUBA
- SONITOR TECHNOLOGIES
- GE HEALTHCARE
- AIRISTA
- ADVANTECH
- UBISENSE
- INFOR
- MIDMARK
- ASCOM
- 中小企業/新創企業
- BLUEIOT
- KONTAKT.IO
- NAVIGINE
- POZYX
- COGNOSOS
- REDPOINT POSITIONING
- SECURE CARE PRODUCTS
- BORDA TECHNOLOGY
- LITUM
第16章調查方法
第17章附錄
The market for healthcare indoor location solutions is projected to increase from USD 3.17 billion in 2026 to USD 13.83 billion by 2032 at a CAGR of 27.8%. Healthcare organizations are increasingly adopting location technologies to improve visibility across clinical and nonclinical environments.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2020-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million/Billion) |
| Segments | By Offering, Technology, Application, Facility Type, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
Indoor location solutions help providers locate medical equipment, monitor patient and staff movement, manage inventory, and support safety-related workflows. Technologies including Wi-Fi, BLE, RFID, UWB, ultrasound, and infrared allow healthcare facilities to select positioning solutions based on accuracy, coverage, and application requirements.
The growing use of location data beyond basic asset tracking is also creating new opportunities. Healthcare providers are integrating indoor location capabilities with electronic health records, computerized maintenance management systems, and other operational platforms to support patient flow, equipment utilization, and workflow management. Such integration enables organizations to move from manually locating resources toward more automated and data-driven healthcare operations.
"The senior living facilities segment is projected to register the highest CAGR during the forecast period."
By facility type, the senior living facilities segment is expected to register the highest CAGR in the healthcare indoor location market during the forecast period. The growing elderly population and increasing focus on resident safety are encouraging senior living facilities to adopt technologies that provide greater visibility into resident and staff locations. Indoor location solutions can support resident monitoring, staff response, asset management, and location-based alerts across assisted living and senior care environments.
The increasing need to improve the efficiency of care delivery is further supporting adoption. Location technologies can help caregivers identify the location of residents and required equipment, reduce time spent searching for resources, and improve response to safety-related events. As senior living operators increasingly adopt connected care and digital monitoring technologies, indoor location solutions are expected to gain greater importance in supporting resident well-being and operational efficiency. The relatively lower existing penetration of these technologies compared with hospitals also provides significant room for future adoption.
"The Wi-Fi segment is expected to contribute the largest share to the healthcare indoor location market during the forecast period."
By technology, the Wi-Fi segment is estimated to hold the largest share of the healthcare indoor location market because Wi-Fi infrastructure is already widely deployed across hospitals and healthcare facilities. Healthcare organizations can leverage existing wireless networks to support location-based applications without requiring extensive deployment of dedicated infrastructure. This provides a practical and scalable approach for facilities seeking to introduce indoor positioning across large and complex environments.
Wi-Fi-based location capabilities support applications such as medical equipment tracking, personnel monitoring, patient movement, indoor navigation, and operational visibility. The continued expansion of wireless connectivity within healthcare facilities is also improving the coverage and reliability of location-enabled services. In addition, integration with hospital IT systems and other connected technologies allows Wi-Fi-based location data to be incorporated into broader operational workflows. These advantages are expected to help Wi-Fi maintain its leading position, particularly among healthcare providers seeking scalable location deployments.
"Asia Pacific will register the highest growth rate during the forecast period."
Asia Pacific is expected to register the highest growth rate in the healthcare indoor location market during the forecast period. Increasing healthcare infrastructure investment, digital transformation, and adoption of connected technologies are creating opportunities for location-enabled solutions across hospitals and other healthcare facilities. The broader Asia Pacific RTLS market is also expanding rapidly, with healthcare identified as one of the important application areas.
The region is likely to see increasing deployment of indoor location for medical equipment management, patient movement, staff safety, and inventory visibility as healthcare providers modernize their facilities. India is expected to be among the faster-growing healthcare RTLS markets in the region, while China, Japan, and other Asia Pacific countries provide opportunities through their established and expanding healthcare infrastructure. The adoption of multiple positioning technologies will further support regional growth. Healthcare providers can combine existing Wi-Fi infrastructure with BLE, RFID, UWB, or other technologies depending on the required level of accuracy and the application, allowing deployments to scale across different areas of a facility.
Breakdown of primaries
The study contains insights from various industry experts, from solution vendors to Tier 1 companies. The breakdown of the primaries is as follows:
- By Company Type: Tier 1 - 30%, Tier 2 - 45%, and Tier 3 - 25%
- By Designation: C-level -35%, D-level - 30%, and Managers - 35%
- By Region: North America - 40%, Europe - 20%, Asia Pacific - 30%, Middle East & Africa- 5%, and Latin America- 5%.
The major players in the healthcare indoor location market are Securitas Healthcare (US), Zebra Technologies (US), HPE Aruba (US), TeleTracking Technologies (US), Advantech (Taiwan), AiRISTA (US), CenTrak (US), GE HealthCare (US), HID Global (US), Sonitor (Norway), Ubisense (UK), Infor (US), Midmark (US), Ascom (Switzerland), SME/Startun (US), Litum (US), BlueIOT (China), Kontakt.io (US), Cognosos (US), Pozyx (Belgium), Navigine (US), Redpoint Positioning (US), Secure Care Products (US), and Borda Technology (Turkey).
Research Coverage
The market study covers the healthcare indoor location market size across different segments. It aims to estimate the market size and the growth potential across various segments, including offering, technology, application, facility type, and regions. The study includes an in-depth competitive analysis of the leading market players, their company profiles, key observations related to product and business offerings, recent developments, and market strategies.
Key Benefits of Buying the Report
The report will help market leaders/new entrants with information on the closest approximations of the global healthcare indoor location market's revenue numbers and subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. Moreover, the report will provide insights for stakeholders to understand the market's pulse and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
Analysis of key drivers (Growing adoption of smart hospitals and digital healthcare transformation, Increasing demand for operational efficiency through real-time asset and workflow visibility, Rising emphasis on patient safety, staff security, and quality of care, Advancements in indoor positioning technologies improving deployment accuracy), restraints (Complex integration with heterogeneous healthcare IT environments, High infrastructure investment and long ROI realization), opportunities (Expansion across long-term care and senior living facilities, AI-enabled hospital command centers and predictive healthcare operations, Increasing adoption of cloud-native RTLS and Location-as-a-Service, Integration with autonomous healthcare logistics and robotics) and challenges (Maintaining positioning accuracy across complex healthcare environments, Shortage of skilled RTLS implementation expertise and organizational change management)
Product Development/Innovation: Detailed insights on upcoming technologies, research and development activities, and new product and service launches in the healthcare indoor location market.
Market Development: Comprehensive information about lucrative markets - the report analyses various regions' healthcare indoor location markets.
Market Diversification: Exhaustive information about new products and services, untapped geographies, recent developments, and investments in the healthcare indoor location market.
Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players like Securitas Healthcare (US), Zebra Technologies (US), HPE Aruba (US), TeleTracking Technologies (US), Advantech (Taiwan), AiRISTA (US), CenTrak (US), GE HealthCare (US), HID Global (US), Sonitor (Norway), Ubisense (UK), Infor (US), Midmark (US), Ascom (Switzerland), SME/Startun (US), Litum (US), BlueIOT (China), Kontakt.io (US), Cognosos (US), Pozyx (Belgium), Navigine (US), Redpoint Positioning (US), Secure Care Products (US), and Borda Technology (Turkey).
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN HEALTHCARE INDOOR LOCATION MARKET
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN HEALTHCARE INDOOR LOCATION MARKET
- 3.2 HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING
- 3.3 HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE
- 3.4 HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY
- 3.5 HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION
- 3.6 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING AND FACILITY TYPE
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing adoption of smart hospitals and digital healthcare transformation
- 4.2.1.2 Increasing demand for operational efficiency through real-time asset and workflow visibility
- 4.2.1.3 Rising emphasis on patient safety, staff security, and quality of care
- 4.2.1.4 Advancements in indoor positioning technologies improving deployment accuracy
- 4.2.2 RESTRAINTS
- 4.2.2.1 High infrastructure investment and long ROI realization
- 4.2.2.2 Complex integration with heterogeneous healthcare IT environments
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion across long-term care and senior living facilities
- 4.2.3.2 AI-enabled hospital command centers and predictive healthcare operations
- 4.2.3.3 Increasing adoption of cloud-native RTLS and Location-as-a-Service
- 4.2.3.4 Integration with autonomous healthcare logistics and robotics
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining positioning accuracy across complex healthcare environments
- 4.2.4.2 Shortage of skilled RTLS implementation expertise and organizational change management
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.3.1 INTERCONNECTED MARKETS
- 4.3.2 CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN HEALTHCARE INDOOR LOCATION MARKET
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.3.1 COMPONENT & DEVICE MANUFACTURERS
- 5.3.2 CONNECTIVITY & INFRASTRUCTURE PROVIDERS
- 5.3.3 HEALTHCARE INDOOR LOCATION SOLUTION PROVIDERS
- 5.3.4 SYSTEM INTEGRATORS, IMPLEMENTATION PARTNERS & CHANNEL PARTNERS
- 5.3.5 HEALTHCARE PROVIDERS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING MODEL ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF HEALTHCARE INDOOR LOCATION HARDWARE, BY REGION, 2025
- 5.5.2 INDICATIVE PRICING ANALYSIS OF HEALTHCARE INDOOR LOCATION SOLUTIONS, 2025
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 RWJBARNABAS HEALTH LEVERAGED SECURITAS HEALTHCARE'S RTLS PLATFORM TO MODERNIZE ENTERPRISE ASSET MANAGEMENT
- 5.9.2 WASHINGTON HOSPITAL CENTER IMPROVING ASSET VISIBILITY AND CLINICAL WORKFLOWS THROUGH REAL-TIME LOCATION TECHNOLOGY
- 5.9.3 ENLOE MEDICAL CENTER MODERNIZED MEDICAL DEVICE TRACKING WITH ARUBA LOCATION SERVICES
- 5.9.4 HOLYOKE MEDICAL CENTER IMPROVED CARE COORDINATION AND CLINICAL WORKFLOWS USING AI-ENABLED RTLS
- 5.9.5 OMMELANDER HOSPITAL IMPROVED MEDICAL ASSET VISIBILITY WITH REAL-TIME LOCATION SYSTEM
- 5.10 IMPACT OF 2025 US TARIFF - HEALTHCARE INDOOR LOCATION MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.3.1 Strategic shifts and emerging trends
- 5.10.4 IMPACT ON COUNTRIES/REGIONS
- 5.10.4.1 US
- 5.10.4.2 China
- 5.10.4.3 Europe
- 5.10.4.4 Asia Pacific (excluding China)
- 5.10.5 IMPACT ON END-USER INDUSTRIES
- 5.10.5.1 Hospitals
- 5.10.5.2 Long-term Care & Senior Living Facilities
- 5.10.5.3 Specialty Clinics & Rehabilitation Centers
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 BLUETOOTH LOW ENERGY (BLE)
- 6.1.2 ULTRA-WIDEBAND (UWB)
- 6.1.3 RADIO FREQUENCY IDENTIFICATION (RFID)
- 6.1.4 WI-FI
- 6.2 ADJACENT TECHNOLOGIES
- 6.2.1 INTERNET OF THINGS (IOT)
- 6.2.2 ARTIFICIAL INTELLIGENCE (AI) & MACHINE LEARNING
- 6.2.3 EDGE COMPUTING
- 6.2.4 5G & PRIVATE WIRELESS NETWORKS
- 6.3 COMPLEMENTARY TECHNOLOGIES
- 6.3.1 INDOOR MAPPING & DIGITAL WAYFINDING
- 6.3.2 SENSOR FUSION
- 6.3.3 WEARABLE LOCATION DEVICES
- 6.3.4 GEOSPATIAL ANALYTICS
- 6.4 TECHNOLOGY ROADMAP
- 6.4.1 SHORT-TERM (2026-2027)
- 6.4.2 MID-TERM ROADMAP (2027-2028)
- 6.4.3 LONG-TERM ROADMAP (2029-2030+)
- 6.5 PATENT ANALYSIS
- 6.6 IMPACT OF AI/GEN AI ON HEALTHCARE INDOOR LOCATION MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 CASE STUDIES OF AI IMPLEMENTATION IN HEALTHCARE INDOOR LOCATION MARKET
- 6.6.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN HEALTHCARE INDOOR LOCATION MARKET
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
9 HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.1.1 OFFERING: MARKET DRIVERS
- 9.2 HARDWARE
- 9.2.1 INCREASING DEMAND FOR REAL-TIME VISIBILITY DRIVING ADOPTION OF SCALABLE HEALTHCARE LOCATION INFRASTRUCTURE
- 9.2.2 TAGS/BADGES
- 9.2.3 READERS/TRACKERS/ACCESS POINT
- 9.2.4 OTHER HARDWARE
- 9.3 SOFTWARE
- 9.3.1 GROWING NEED TO CONVERT LOCATION DATA INTO ACTIONABLE WORKFLOWS DRIVING DEMAND FOR HEALTHCARE RTLS SOFTWARE
- 9.4 SERVICES
- 9.4.1 INCREASING COMPLEXITY OF HEALTHCARE RTLS DEPLOYMENTS DRIVING DEMAND FOR IMPLEMENTATION AND LIFECYCLE SERVICES
- 9.4.2 DEPLOYMENT & INTEGRATION
- 9.4.3 SUPPORT & MAINTENANCE
- 9.4.4 CONSULTING
10 HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.1.1 TECHNOLOGY: MARKET DRIVERS
- 10.2 RFID
- 10.2.1 GROWING DEMAND FOR AUTOMATED ASSET VISIBILITY SUSTAINING RFID ADOPTION ACROSS HEALTHCARE FACILITIES
- 10.3 WI-FI
- 10.3.1 GROWING USE OF EXISTING WIRELESS INFRASTRUCTURE SUPPORTING WI-FI-BASED HEALTHCARE LOCATION DEPLOYMENTS
- 10.4 UWB
- 10.4.1 INCREASING NEED FOR HIGH-PRECISION POSITIONING ACCELERATING UWB ADOPTION IN HEALTHCARE RTLS
- 10.5 BLE
- 10.5.1 EXPANDING LOW-POWER CONNECTIVITY STRENGTHENING BLE ADOPTION ACROSS HEALTHCARE LOCATION APPLICATIONS
- 10.6 ULTRASOUND
- 10.6.1 DEMAND FOR RELIABLE ROOM-LEVEL POSITIONING SUPPORTING ULTRASOUND-BASED HEALTHCARE RTLS
- 10.7 INFRARED
- 10.7.1 GROWING DEMAND FOR ROOM-CERTAIN WORKFLOW AUTOMATION SUSTAINING INFRARED APPLICATIONS IN HEALTHCARE
- 10.8 OTHER TECHNOLOGIES
11 HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.1.1 APPLICATION: MARKET DRIVERS
- 11.2 INVENTORY/ASSET TRACKING & MANAGEMENT
- 11.2.1 GROWING NEED FOR REAL-TIME VISIBILITY OF MEDICAL EQUIPMENT ACCELERATING HEALTHCARE ASSET-TRACKING ADOPTION
- 11.3 PERSONNEL LOCATING & MONITORING
- 11.3.1 INCREASING FOCUS ON WORKFORCE SAFETY AND OPERATIONAL COORDINATION DRIVING ADOPTION OF PERSONNEL LOCATION SOLUTIONS
- 11.4 ACCESS CONTROL & SECURITY
- 11.4.1 CONVERGENCE OF LOCATION INTELLIGENCE AND PHYSICAL SECURITY EXPANDING HEALTHCARE ACCESS-CONTROL APPLICATIONS
- 11.5 ENVIRONMENTAL MONITORING
- 11.5.1 INCREASING NEED TO PROTECT SENSITIVE HEALTHCARE ENVIRONMENTS SUPPORTING LOCATION-ENABLED ENVIRONMENTAL MONITORING
- 11.6 SUPPLY CHAIN MANAGEMENT & AUTOMATION
- 11.6.1 GROWING PRESSURE TO IMPROVE MATERIAL VISIBILITY DRIVING LOCATION-ENABLED HEALTHCARE SUPPLY CHAIN AUTOMATION
- 11.7 OTHER APPLICATIONS
12 HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE
- 12.1 INTRODUCTION
- 12.1.1 FACILITY TYPE: MARKET DRIVERS
- 12.2 HOSPITALS & HEALTHCARE FACILITIES
- 12.2.1 INCREASING OPERATIONAL COMPLEXITY AND DEMAND FOR REAL-TIME VISIBILITY ACCELERATING INDOOR-LOCATION ADOPTION ACROSS HOSPITALS
- 12.3 SENIOR LIVING FACILITIES
- 12.3.1 RISING FOCUS ON RESIDENT SAFETY AND CAREGIVER RESPONSIVENESS EXPANDING RTLS ADOPTION ACROSS SENIOR LIVING ENVIRONMENTS
13 HEALTHCARE INDOOR LOCATION MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Connected hospital operations and workforce safety to accelerate indoor location adoption
- 13.2.2 CANADA
- 13.2.2.1 Connected healthcare infrastructure and hospital asset visibility to support market development
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Patient flow and capacity management strengthen demand for healthcare indoor location
- 13.3.2 GERMANY
- 13.3.2.1 Medical equipment visibility and hospital resource management create opportunities for healthcare indoor location
- 13.3.3 FRANCE
- 13.3.3.1 Growing focus on indoor positioning for hospital workflow and resource optimization
- 13.3.4 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Smart hospital development and demand for efficient patient and resource management to support market growth
- 13.4.2 INDIA
- 13.4.2.1 RTLS improves patient transport efficiency and porter utilization in Indian hospitals
- 13.4.3 JAPAN
- 13.4.3.1 Aging population and workforce constraints increase focus on healthcare efficiency
- 13.4.4 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 UAE
- 13.5.1.1 Smart hospital development and patient experience create opportunities for indoor location
- 13.5.2 KSA
- 13.5.2.1 Vision 2030 projects and smart infrastructure investments to strengthen demand
- 13.5.3 SOUTH AFRICA
- 13.5.3.1 Selective adoption in large healthcare facilities creates opportunities
- 13.5.4 REST OF MIDDLE EAST & AFRICA
- 13.5.1 UAE
- 13.6 LATIN AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Reference deployments and asset management support market development
- 13.6.2 MEXICO
- 13.6.2.1 Digital health development creates enabling environment for indoor location
- 13.6.3 REST OF LATIN AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023-2026
- 14.3 MARKET SHARE ANALYSIS, 2025
- 14.4 BRAND/PRODUCT COMPARISON
- 14.5 COMPANY VALUATION AND FINANCIAL METRICS
- 14.6 COMPANY EVALUATION QUADRANT, 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2024
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Offering footprint
- 14.6.5.4 Application footprint
- 14.6.5.5 Facility Type footprint
- 14.7 STARTUP/SME EVALUATION MATRIX
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPETITIVE SCENARIO
- 14.8.1 PRODUCT LAUNCHES
- 14.8.2 DEALS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 SECURITAS HEALTHCARE
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches & enhancements
- 15.1.1.3.2 Deals
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 ZEBRA TECHNOLOGIES
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches/enhancements
- 15.1.2.3.2 Deals
- 15.1.2.3.3 Expansions
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 CENTRAK
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches & enhancements
- 15.1.3.3.2 Deals
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 TELETRACKING TECHNOLOGIES
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches & enhancements
- 15.1.4.3.2 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 HID GLOBAL
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Deals
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 HPE ARUBA
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Deals
- 15.1.7 SONITOR TECHNOLOGIES
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches
- 15.1.7.3.2 Deals
- 15.1.8 GE HEALTHCARE
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.9 AIRISTA
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Product launches
- 15.1.9.3.2 Deals
- 15.1.10 ADVANTECH
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.11 UBISENSE
- 15.1.12 INFOR
- 15.1.13 MIDMARK
- 15.1.14 ASCOM
- 15.1.1 SECURITAS HEALTHCARE
- 15.2 SMES/STARTUPS
- 15.2.1 BLUEIOT
- 15.2.2 KONTAKT.IO
- 15.2.3 NAVIGINE
- 15.2.4 POZYX
- 15.2.5 COGNOSOS
- 15.2.6 REDPOINT POSITIONING
- 15.2.7 SECURE CARE PRODUCTS
- 15.2.8 BORDA TECHNOLOGY
- 15.2.9 LITUM
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.3 MARKET BREAKUP AND DATA TRIANGULATION
- 16.4 MARKET FORECAST
- 16.5 RESEARCH ASSUMPTIONS
- 16.6 RESEARCH LIMITATIONS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 USD EXCHANGE RATES, 2021-2025
- TABLE 2 INTERCONNECTED MARKETS
- TABLE 3 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- TABLE 4 IMPACT OF PORTER'S FIVE FORCES ON HEALTHCARE INDOOR LOCATION MARKET
- TABLE 5 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2029
- TABLE 6 ROLE OF COMPANIES IN HEALTHCARE INDOOR LOCATION MARKET ECOSYSTEM
- TABLE 7 INDICATIVE PRICING ANALYSIS OF HEALTHCARE INDOOR LOCATION SOLUTIONS, BY KEY PLAYER, 2025
- TABLE 8 HEALTHCARE INDOOR LOCATION MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 9 US ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 10 LIST OF MAJOR PATENTS (2022-2026)
- TABLE 11 TOP USE CASES AND MARKET POTENTIAL
- TABLE 12 HEALTHCARE INDOOR LOCATION MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 13 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 14 LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 15 KEY REGULATIONS IN HEALTHCARE INDOOR LOCATION MARKET
- TABLE 16 KEY INDUSTRY STANDARDS IN HEALTHCARE INDOOR LOCATION
- TABLE 17 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FACILITY TYPES (%)
- TABLE 18 KEY BUYING CRITERIA FOR TOP FACILITY TYPES
- TABLE 19 UNMET NEEDS IN HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE
- TABLE 20 HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 21 HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 22 HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 23 HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 24 HARDWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 25 HARDWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 26 TAGS/BADGES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 27 TAGS/BADGES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 28 READERS/TRACKERS/ACCESS POINT: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 29 READERS/TRACKERS/ACCESS POINT: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 30 OTHER HARDWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 31 OTHER HARDWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 32 SOFTWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 33 SOFTWARE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 34 SERVICES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 35 SERVICES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 36 SERVICES: HEALTHCARE INDOOR LOCATION MARKET, BY TYPE, 2020-2025 (USD MILLION)
- TABLE 37 SERVICES: HEALTHCARE INDOOR LOCATION MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 38 DEPLOYMENT & INTEGRATION: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 39 DEPLOYMENT & INTEGRATION: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 40 SUPPORT & MAINTENANCE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 41 SUPPORT & MAINTENANCE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 42 CONSULTING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 43 CONSULTING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 44 HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 45 HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 46 RFID: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 47 RFID: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 48 WI-FI: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 49 WI-FI: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 50 UWB: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 51 UWB: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 52 BLE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 53 BLE: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 54 ULTRASOUND: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 55 ULTRASOUND: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 56 INFRARED: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 57 INFRARED: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 58 OTHER TECHNOLOGIES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 59 OTHER TECHNOLOGIES: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 60 HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 61 HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 62 INVENTORY/ASSET TRACKING & MANAGEMENT: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 63 INVENTORY/ASSET TRACKING & MANAGEMENT: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 64 PERSONNEL LOCATING & MONITORING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 65 PERSONNEL LOCATING & MONITORING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 66 ACCESS CONTROL & SECURITY: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 67 ACCESS CONTROL & SECURITY: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 68 ENVIRONMENTAL MONITORING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 69 ENVIRONMENTAL MONITORING: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 70 SUPPLY CHAIN MANAGEMENT & AUTOMATION: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 71 SUPPLY CHAIN MANAGEMENT & AUTOMATION: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 72 OTHER APPLICATIONS: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 73 OTHER APPLICATIONS: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 74 HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 75 HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 76 HOSPITALS & HEALTHCARE FACILITIES: HEALTHCARE INDOOR LOCATIONS MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 77 HOSPITALS & HEALTHCARE FACILITIES: HEALTHCARE INDOOR LOCATIONS MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 78 TRAVEL & HOSPITALITY: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 79 TRAVEL & HOSPITALITY: HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 80 HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2020-2025 (USD MILLION)
- TABLE 81 HEALTHCARE INDOOR LOCATION MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 82 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 83 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 84 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 85 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 86 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 87 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 88 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 89 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 90 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 91 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 92 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 93 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 94 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 95 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 96 US: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 97 US: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 98 US: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 99 US: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 100 US: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 101 US: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 102 US: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 103 US: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 104 US: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 105 US: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 106 US: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 107 US: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 108 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 109 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 110 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 111 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 112 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 113 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 114 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 115 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 116 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 117 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 118 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 119 CANADA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 120 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 121 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 122 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 123 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 124 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 125 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 126 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 127 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 128 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 129 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 130 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 131 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 132 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 133 EUROPE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 134 UK: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 135 UK: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 136 UK: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 137 UK: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 138 UK: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 139 UK: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 140 UK: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 141 UK: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 142 UK: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 143 UK: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 144 UK: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 145 UK: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 146 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 147 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 148 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 149 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 150 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 151 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 152 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 153 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 154 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 155 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 156 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 157 GERMANY: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 158 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 159 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 160 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 161 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 162 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 163 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 164 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 165 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 166 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 167 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 168 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 169 FRANCE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 170 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 171 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 172 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 173 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 174 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 175 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 176 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 177 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 178 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 179 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 180 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 181 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 182 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 183 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 184 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 185 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 186 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 187 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 188 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 189 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 190 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 191 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 192 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 193 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 194 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 195 CHINA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 196 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 197 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 198 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 199 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 200 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 201 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 202 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 203 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 204 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 205 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 206 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 207 INDIA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 208 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 209 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 210 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 211 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 212 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 213 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 214 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 215 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 216 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 217 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 218 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 219 JAPAN: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 220 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 221 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 222 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 223 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 224 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 225 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 226 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 227 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 228 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 229 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 230 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 231 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 232 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 233 MIDDLE EAST & AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 234 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 235 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 236 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 237 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 238 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 239 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 240 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 241 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 242 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 243 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 244 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 245 UAE: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 246 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 247 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 248 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 249 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 250 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 251 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 252 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 253 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 254 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 255 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 256 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 257 KSA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 258 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 259 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 260 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 261 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 262 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 263 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 264 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 265 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 266 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 267 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 268 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 269 SOUTH AFRICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 270 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2020-2025 (USD MILLION)
- TABLE 271 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 272 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 273 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 274 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 275 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 276 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 277 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 278 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 279 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 280 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 281 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 282 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 283 LATIN AMERICA: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 284 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 285 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 286 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 287 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 288 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 289 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 290 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 291 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 292 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 293 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 294 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 295 BRAZIL: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 296 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2020-2025 (USD MILLION)
- TABLE 297 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 298 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2020-2025 (USD MILLION)
- TABLE 299 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY HARDWARE, 2026-2032 (USD MILLION)
- TABLE 300 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2020-2025 (USD MILLION)
- TABLE 301 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY SERVICE, 2026-2032 (USD MILLION)
- TABLE 302 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2020-2025 (USD MILLION)
- TABLE 303 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY FACILITY TYPE, 2026-2032 (USD MILLION)
- TABLE 304 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2020-2025 (USD MILLION)
- TABLE 305 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY TECHNOLOGY, 2026-2032 (USD MILLION)
- TABLE 306 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2020-2025 (USD MILLION)
- TABLE 307 MEXICO: HEALTHCARE INDOOR LOCATION MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 308 OVERVIEW OF STRATEGIES DEPLOYED BY KEY MARKET PLAYERS, 2023-2026
- TABLE 309 HEALTHCARE INDOOR LOCATION MARKET: DEGREE OF COMPETITION
- TABLE 310 HEALTHCARE INDOOR LOCATION MARKET: REGION FOOTPRINT
- TABLE 311 HEALTHCARE INDOOR LOCATION MARKET: OFFERING FOOTPRINT
- TABLE 312 HEALTHCARE INDOOR LOCATION MARKET: APPLICATION FOOTPRINT
- TABLE 313 HEALTHCARE INDOOR LOCATION MARKET: TECHNOLOGY FOOTPRINT
- TABLE 314 HEALTHCARE INDOOR LOCATION MARKET: LIST OF KEY STARTUPS/SMES
- TABLE 315 HEALTHCARE INDOOR LOCATION MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 316 PRODUCT LAUNCHES, MARCH 2023-JULY 2026
- TABLE 317 DEALS, JANUARY 2023-MAY 2026
- TABLE 318 SECURITAS HEALTHCARE: COMPANY OVERVIEW
- TABLE 319 SECURITAS HEALTHCARE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 320 SECURITAS HEALTHCARE: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 321 SECURITAS HEALTHCARE: DEALS
- TABLE 322 ZEBRA TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 323 ZEBRA TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 324 ZEBRA TECHNOLOGIES, INC.: PRODUCT LAUNCHES/ENHANCEMENTS
- TABLE 325 ZEBRA TECHNOLOGIES: DEALS
- TABLE 326 ZEBRA TECHNOLOGIES: EXPANSIONS
- TABLE 327 CENTRAK: COMPANY OVERVIEW
- TABLE 328 CENTRAK: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 329 CENTRAK: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 330 CENTRAK: DEALS
- TABLE 331 TELETRACKING TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 332 TELETRACKING TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 333 TELETRACKING TECHNOLOGIES: PRODUCT LAUNCHES & ENHANCEMENTS
- TABLE 334 TELETRACKING TECHNOLOGIES: DEALS
- TABLE 335 HID GLOBAL: COMPANY OVERVIEW
- TABLE 336 HID GLOBAL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 337 HID GLOBAL: DEALS
- TABLE 338 HPE ARUBA: COMPANY OVERVIEW
- TABLE 339 HPE ARUBA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 340 HPE ARUBA: DEALS
- TABLE 341 SONITOR TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 342 SONITOR TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 343 SONITOR TECHNOLOGIES: PRODUCT LAUNCHES
- TABLE 344 SONITOR TECHNOLOGIES: DEALS
- TABLE 345 GE HEALTHCARE: COMPANY OVERVIEW
- TABLE 346 GE HEALTHCARE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 347 AIRISTA: COMPANY OVERVIEW
- TABLE 348 AIRISTA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 349 AIRISTA: PRODUCT LAUNCHES
- TABLE 350 AIRISTA: DEALS
- TABLE 351 ADVANTECH: COMPANY OVERVIEW
- TABLE 352 ADVANTECH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 353 FACTOR ANALYSIS
List of Figures
- FIGURE 1 MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 GLOBAL HEALTHCARE INDOOR LOCATION MARKET, 2020-2032
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN HEALTHCARE INDOOR LOCATION MARKET, 2020-2025
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF HEALTHCARE INDOOR LOCATION MARKET
- FIGURE 6 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN HEALTHCARE INDOOR LOCATION MARKET DURING FORECAST PERIOD
- FIGURE 7 RISING DEMAND FOR REAL-TIME LOCATION VISIBILITY AND CONNECTED HEALTHCARE OPERATIONS TO DRIVE MARKET GROWTH
- FIGURE 8 HARDWARE SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2026
- FIGURE 9 HOSPITAL & HEALTHCARE FACILITIES SEGMENT TO DOMINATE IN 2026
- FIGURE 10 INVENTORY/ASSET TRACKING & MANAGEMENT SEGMENT TO DOMINATE IN 2026
- FIGURE 11 INVENTORY/ASSET TRACKING & MANAGEMENT SEGMENT TO DOMINATE IN 2026
- FIGURE 12 HARDWARE ACCOUNTED FOR LARGEST MARKET SHARE IN 2026
- FIGURE 13 HEALTHCARE INDOOR LOCATION MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 HEALTHCARE INDOOR LOCATION MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 HEALTHCARE INDOOR LOCATION MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 16 HEALTHCARE INDOOR LOCATION MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 18 INVESTMENT AND FUNDING SCENARIO OF MAJOR HEALTHCARE INDOOR LOCATION VENDORS (2025)
- FIGURE 19 LIST OF MAJOR PATENTS APPLIED FOR AND GRANTED (2017-2026)
- FIGURE 20 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP FACILITY TYPES
- FIGURE 21 KEY BUYING CRITERIA FOR TOP FACILITY TYPES
- FIGURE 22 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 23 SOFTWARE SEGMENT TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 24 OTHER HARDWARE TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 25 CONSULTING SEGMENT TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 26 UWB TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 27 ACCESS CONTROL & SECURITY TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 28 HOSPITAL & HEALTHCARE FACILITIES TO BE FASTEST-GROWING FACILITY TYPE
- FIGURE 29 NORTH AMERICA: HEALTHCARE INDOOR LOCATION MARKET SNAPSHOT
- FIGURE 30 ASIA PACIFIC: HEALTHCARE INDOOR LOCATION MARKET SNAPSHOT
- FIGURE 31 SHARES OF LEADING COMPANIES IN HEALTHCARE INDOOR LOCATION MARKET, 2025
- FIGURE 32 HEALTHCARE INDOOR LOCATION MARKET: BRAND/PRODUCT COMPARISON
- FIGURE 33 COMPANY VALUATION, 2026
- FIGURE 34 FINANCIAL METRICS OF KEY VENDORS: 2026
- FIGURE 35 KEY HEALTHCARE INDOOR LOCATION MARKET PLAYER EVALUATION MATRIX, 2025
- FIGURE 36 HEALTHCARE INDOOR LOCATION MARKET: COMPANY FOOTPRINT
- FIGURE 37 HEALTHCARE INDOOR LOCATION MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 38 ZEBRA TECHNOLOGIES: COMPANY SNAPSHOT
- FIGURE 39 HPE ARUBA: COMPANY SNAPSHOT
- FIGURE 40 GE HEALTHCARE: COMPANY SNAPSHOT
- FIGURE 41 HEALTHCARE INDOOR LOCATION MARKET: RESEARCH DESIGN
- FIGURE 42 KEY DATA FROM SECONDARY SOURCES
- FIGURE 43 BREAKUP OF PRIMARY PROFILES
- FIGURE 44 KEY INSIGHTS FROM INDUSTRY EXPERTS
- FIGURE 45 KEY DATA FROM PRIMARY SOURCES
- FIGURE 46 HEALTHCARE INDOOR LOCATION MARKET: BOTTOM-UP APPROACH
- FIGURE 47 MARKET SIZE ESTIMATION METHODOLOGY, BOTTOM-UP (DEMAND-SIDE): COLLECTIVE REVENUE FROM ALL SOLUTIONS/SERVICES OF HEALTHCARE INDOOR LOCATION MARKET
- FIGURE 48 MARKET SIZE ESTIMATION METHODOLOGY, BOTTOM-UP (SUPPLY-SIDE): COLLECTIVE REVENUE FROM ALL SOLUTIONS/SERVICES OF HEALTHCARE INDOOR LOCATION MARKET
- FIGURE 49 HEALTHCARE INDOOR LOCATION MARKET: TOP-DOWN APPROACH
- FIGURE 50 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 1 (SUPPLY-SIDE): REVENUE OF OFFERINGS IN HEALTHCARE INDOOR LOCATION MARKET
- FIGURE 51 MARKET SIZE ESTIMATION METHODOLOGY - APPROACH 2 (DEMAND-SIDE): HEALTHCARE INDOOR LOCATION MARKET
- FIGURE 52 HEALTHCARE INDOOR LOCATION MARKET: DATA TRIANGULATION

 全球即時位置資訊系統市場規模、佔有率、趨勢和成長分析報告(2026-2034)醫療保健領域即時定位系統 (RTLS) 的成長機會:至 2031 年的預測
 即時位置資訊系統市場:按組件、技術、位置資訊類型、應用和最終用戶產業分類-2026-2032年全球市場預測全球即時定位系統(RTLS)市場規模、佔有率、趨勢和成長分析報告(2026-2034年體育產業篇)
 醫療保健即時位置資訊系統市場預測至2034年-按產品、技術、應用、最終用戶和地區分類的全球分析
 醫療保健領域即時定位系統 (RTLS) 市場:按產品、應用、最終用途和地區分類 (2026–2034)
 2026年全球交通運輸與物流即時位置資訊系統市場報告
 即時位置資訊系統市場:按交付方式、技術、應用和地區分類。2026年全球醫療保健即時定位系統市場報告2026年全球即時定位系統(RTLS)市場報告