


 |
市場調查報告書
商品編碼
2121198
心血管器材市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Cardiovascular Devices Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

預計到 2025 年,全球心血管器材市場價值將達到 740 億美元,年複合成長率為 7.5%,到 2035 年將達到 1,520 億美元。
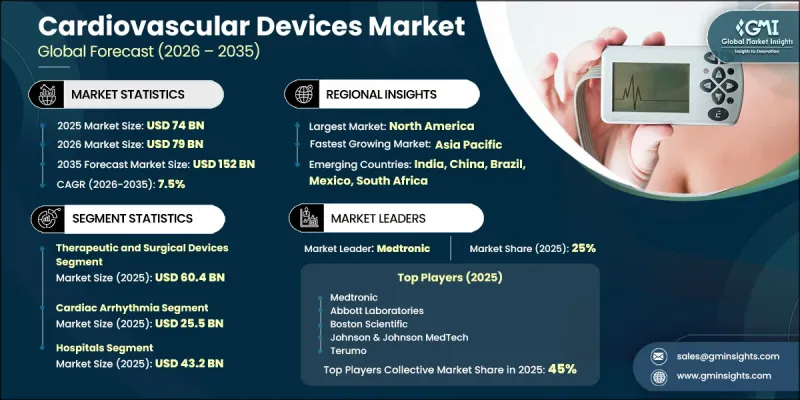
心血管疾病盛行率不斷上升、人口快速老化、醫療保健投資增加、技術持續進步以及人們對微創治療的日益青睞,是推動全球心血管器材市場成長的主要因素。全球心血管疾病發生率的持續攀升是市場擴張的關鍵驅動力,因為醫療專業人員需要更先進的疾病檢測、監測和治療解決方案。對高效心臟護理日益成長的需求,推動了包括先進介入系統、植入式設備、穿戴式監測解決方案和智慧診斷平台在內的創新心血管技術的應用。預防性心臟健康管理意識的提高以及發展中地區醫療保健服務的改善,也促進了心血管器械使用量的增加。醫療保健系統越來越重視疾病的早期管理、精準診斷和有效的治療性介入,以應對日益沉重的心血管疾病負擔。患者需求的成長、技術的進步以及醫療基礎設施的改善,共同為全球心血管器材市場創造了強勁的成長機會。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 740億美元 |
| 預測金額 | 1520億美元 |
| 複合年成長率 | 7.5% |
預計到2025年,治療和外科醫療設備市場規模將達到604億美元。該市場涵蓋一系列重要的心血管解決方案,旨在支持心臟治療手術並改善患者預後。這些醫療設備在介入性心臟病學和心血管外科手術中發揮核心作用,為治療複雜的心臟相關疾病提供了有效的解決方案。治療和外科醫療設備憑藉其關鍵的治療功能,以及在需要快速可靠的介入心臟病學手術中的廣泛應用,主導地位。
到2025年,醫院細分市場規模將達到432億美元,佔總市場的58.3%。醫院是最大的終端使用者群體,這得益於其先進的醫療基礎設施、專業的醫護人員以及提供全面心血管服務的能力。這些機構支持各種心血管手術,包括診斷、介入治療、外科手術和長期病患監測。提供綜合心臟護理服務、急救治療能力以及獲得先進醫療技術的能力將繼續推動醫院對心血管器械的需求。
到2025年,北美心血管器材市場將佔據全球41.8%的佔有率。由於心血管疾病盛行率不斷上升、醫療基礎設施完善以及先進醫療技術的快速普及,該地區市場持續擴張。生活方式相關風險因素導致的心臟病病例不斷增加,推動了創新診斷和治療解決方案的持續成長。微創心血管系統、人工智慧(AI)驅動的診斷技術、先進的植入式醫療設備以及遠端患者監護解決方案的開發,進一步促進了該地區市場的成長。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 成長促進因素
- 患有心血管疾病的患者人數正在增加。
- 遠端患者監護和聯網心血管設備整合方面的進展
- 心血管器械的技術進步
- 對微創手術的需求日益成長
- 產業潛在風險與挑戰
- 心臟治療相關的高風險
- 心血管器材複雜的法規核准流程
- 市場機遇
- 人工智慧在心血管疾病領域的應用日益廣泛
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 技術展望
- 最新科技趨勢
- 用於即時心血管診斷的先進成像和感測系統
- 用於自動檢測和風險分層的AI整合式心血管設備
- 新興技術
- 用於下一代心血管植入和支架的生物工程和自適應材料
- 用於動態心血管評估的超高速 3D 視覺化和數位孿生技術
- 最新科技趨勢
- 未來市場趨勢
- 贖回方案
- 專利分析
- 價格趨勢分析
- 人工智慧和生成式人工智慧對市場的影響
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業市場占有率
- 世界
- 北美洲
- 歐洲
- 亞太地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依設備類型分類,2022-2035年
- 診斷和監測設備
- 心電圖系統
- 心電圖監測與心臟事件記錄器
- 遠端心電圖監測設備
- 心臟診斷超音波設備
- 其他診斷和監測設備
- 治療及外科醫療設備
- 導管
- 電生理消融導管
- 電生理診斷及標測導管
- 介入導管
- 用於冠狀動脈介入治療的醫療設備
- 藥物釋放型支架
- 裸金屬支架
- 生物可吸收支架
- PTCA球囊
- 動脈粥狀硬化斑塊切除術裝置
- 導管導引線
- 栓塞預防裝置
- 其他冠狀動脈介入醫療設備
- 心臟節律管理(CRM)設備
- 心律調節器
- 植入式心臟整流去顫器(ICD)
- 心臟再同步治療裝置
- 植物型循環記錄器
- 其他心臟節律管理設備
- 結構性心臟醫療設備
- 左心耳封堵裝置
- 心臟瓣膜
- 心臟外科醫療設備
- 冠狀動脈繞道手術手術(CABG)手術器械
- 其他心臟外科醫療設備
- 心室輔助裝置
- 導管
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 缺血性心臟病
- 心律不整
- 心臟衰竭
- 其他用途
第7章 市場估計與預測:依最終用途分類,2022-2035年
- 醫院
- 門診手術中心
- 心臟中心
- 其他最終用戶
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- Abbott Laboratories
- AngioDynamics
- Biotronik
- Boston Scientific
- Edwards
- Johnson & Johnson MedTech
- Koninklijke Philips
- Medtronic
- Meril Life Sciences
- MicroPort Scientific
- Olympus
- Pneumbra
- Relisys Medical Devices
- Sahajanand Medical Technologies
- Terumo
- Translumina Therapeutics
The Global Cardiovascular Devices Market was valued at USD 74 billion in 2025 and is estimated to grow at a CAGR of 7.5% to reach USD 152 billion by 2035.
The market is witnessing growth due to the increasing prevalence of cardiovascular diseases, a rapidly expanding aging population, rising healthcare investments, continuous technological advancements, and growing preference for minimally invasive treatment approaches. The rising worldwide incidence of cardiovascular conditions remains one of the primary factors supporting market expansion, as healthcare providers require more advanced solutions for disease detection, monitoring, and treatment. Increasing demand for efficient cardiac care is encouraging the adoption of innovative cardiovascular technologies, including advanced intervention systems, implantable devices, wearable monitoring solutions, and intelligent diagnostic platforms. Growing awareness regarding preventive cardiac health and improved healthcare accessibility across developing regions is also contributing to higher utilization of cardiovascular devices. Healthcare systems are increasingly focusing on early disease management, accurate diagnosis, and effective therapeutic interventions to address the growing cardiovascular disease burden. The combination of rising patient demand, technological progress, and increasing healthcare infrastructure development continues to create strong growth opportunities for the global Cardiovascular Devices Market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $74 Billion |
| Forecast Value | $152 Billion |
| CAGR | 7.5% |
The therapeutic and surgical devices segment generated USD 60.4 billion in 2025. This segment includes a wide range of essential cardiovascular solutions designed to support cardiac treatment procedures and improve patient outcomes. These devices play a central role in interventional cardiology and cardiovascular surgeries by providing effective solutions for managing complex heart-related conditions. The segment maintains its leading position because therapeutic and surgical devices deliver critical treatment capabilities and are widely used in procedures requiring immediate and reliable cardiovascular intervention.
The hospitals segment generated USD 43.2 billion and accounted for a 58.3% share in 2025. Hospitals represent the largest end-user segment due to their advanced medical infrastructure, specialized healthcare professionals, and capability to provide comprehensive cardiovascular services. These facilities support a wide range of cardiovascular procedures, including diagnosis, intervention, surgery, and long-term patient monitoring. The availability of integrated cardiac care services, emergency treatment capabilities, and advanced medical technologies continues to strengthen hospital demand for cardiovascular devices.
North America Cardiovascular Devices Market accounted for a 41.8% share in 2025. The regional market continues to expand due to the increasing prevalence of cardiovascular diseases, strong healthcare infrastructure, and rapid adoption of advanced medical technologies. Rising cases of heart-related conditions associated with lifestyle-related risk factors continue to increase demand for innovative diagnostic and treatment solutions. Technological advancements are further supporting regional growth through the development of minimally invasive cardiovascular systems, artificial intelligence-enabled diagnostic technologies, advanced implantable devices, and remote patient monitoring solutions.
Major companies operating in the global cardiovascular devices market include Abbott Laboratories, AngioDynamics, Biotronik, Boston Scientific, Edwards, Johnson & Johnson MedTech, Koninklijke Philips, Medtronic, Meril Life Sciences, MicroPort Scientific, Olympus, Pneumbra, Relisys Medical Devices, Sahajanand Medical Technologies, Terumo, and Translumina Therapeutics. Companies operating in the cardiovascular devices market are strengthening their market positions through continuous innovation, strategic partnerships, and investments in advanced medical technologies. Leading manufacturers are focusing on developing next-generation cardiovascular devices with improved safety, accuracy, efficiency, and patient outcomes. Companies are expanding their product portfolios through research and development initiatives aimed at creating minimally invasive solutions, intelligent monitoring systems, and advanced treatment technologies. Strategic collaborations, mergers, acquisitions, and geographic expansion efforts are helping organizations enhance their market presence and strengthen their technological capabilities. Businesses are also investing in digital healthcare solutions, artificial intelligence integration, and remote monitoring technologies to improve clinical outcomes and healthcare delivery.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Device type trends
- 2.2.2 Application trends
- 2.2.3 End use trends
- 2.2.4 Regional trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing number of patients suffering from cardiovascular diseases
- 3.2.1.2 Growing integration of remote patient monitoring and connected cardiovascular devices
- 3.2.1.3 Technological advancements in cardiovascular devices
- 3.2.1.4 Rising demand for minimally invasive procedures
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High risk associated with cardiac procedures
- 3.2.2.2 Complex regulatory approval processes for cardiovascular devices
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing applications of AI in cardiovascular diseases
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by primary research)
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.5 Technology landscape (Driven by primary research)
- 3.5.1 Current technological trends
- 3.5.1.1 Advanced imaging and sensing systems for real-time cardiovascular diagnostics
- 3.5.1.2 AI-integrated cardiovascular devices for automated detection and risk stratification
- 3.5.2 Emerging technologies
- 3.5.2.1 Bioengineered and adaptive materials for next-generation cardiovascular implants and stents
- 3.5.2.2 Ultra-high-speed 3D visualization and digital twin technologies for dynamic cardiovascular assessment
- 3.5.1 Current technological trends
- 3.6 Future market trends (Driven by primary research)
- 3.7 Reimbursement scenario
- 3.8 Patent analysis
- 3.9 Pricing trend analysis
- 3.10 Impact of AI and Generative AI on the market (Driven by primary research)
- 3.11 Porter's analysis
- 3.12 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis by region
- 4.2.1 Global
- 4.2.2 North America
- 4.2.3 Europe
- 4.2.4 Asia Pacific
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers and acquisitions
- 4.6.2 Partnerships and collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Device Type, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Diagnostic and monitoring devices
- 5.2.1 Electrocardiogram systems
- 5.2.2 Holter and event monitors
- 5.2.3 Remote cardiac monitoring devices
- 5.2.4 Cardiac diagnostic ultrasound
- 5.2.5 Other diagnostic and monitoring devices
- 5.3 Therapeutic and surgical devices
- 5.3.1 Catheters
- 5.3.1.1 Electrophysiology ablation catheters
- 5.3.1.2 Electrophysiology diagnostic and mapping catheters
- 5.3.1.3 Interventional catheters
- 5.3.2 Coronary intervention devices
- 5.3.2.1 Drug eluting stents
- 5.3.2.2 Bare metal stents
- 5.3.2.3 Bioresorbable scaffolds
- 5.3.2.4 PTCA balloons
- 5.3.2.5 Atherectomy devices
- 5.3.2.6 Guidewires
- 5.3.2.7 Embolic protection devices
- 5.3.2.8 Other coronary intervention devices
- 5.3.3 Cardiac rhythm management (CRM) devices
- 5.3.3.1 Pacemakers
- 5.3.3.2 Implantable cardioverter defibrillators
- 5.3.3.3 Cardiac resynchronization therapy devices
- 5.3.3.4 Implantable loop recorders
- 5.3.3.5 Other cardiac rhythm management devices
- 5.3.4 Structural heart devices
- 5.3.4.1 LAA closure devices
- 5.3.4.2 Heart valves
- 5.3.5 Cardiac surgery devices
- 5.3.5.1 Coronary artery bypass graft (CABG) surgical tools
- 5.3.5.2 Other cardiac surgical devices
- 5.3.6 Ventricular assist devices
- 5.3.1 Catheters
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Coronary artery disease
- 6.3 Cardiac arrhythmia
- 6.4 Heart failure
- 6.5 Other applications
Chapter 7 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Hospitals
- 7.3 Ambulatory surgical centers
- 7.4 Cardiac centers
- 7.5 Other end users
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Abbott Laboratories
- 9.2 AngioDynamics
- 9.3 Biotronik
- 9.4 Boston Scientific
- 9.5 Edwards
- 9.6 Johnson & Johnson MedTech
- 9.7 Koninklijke Philips
- 9.8 Medtronic
- 9.9 Meril Life Sciences
- 9.10 MicroPort Scientific
- 9.11 Olympus
- 9.12 Pneumbra
- 9.13 Relisys Medical Devices
- 9.14 Sahajanand Medical Technologies
- 9.15 Terumo
- 9.16 Translumina Therapeutics

 有氧運動器材市場規模、佔有率、成長率、全球產業分析、區域趨勢及2026-2034年預測。
 心血管醫療設備市場報告:趨勢、預測與競爭分析(至2035年)全球心血管疾病流行病學分析與預測:2026-2035年
 心血管醫療設備市場:2026-2032年全球市場預測(按器材類型、入路方式、治療類型、材料類型、應用和最終用戶分類)
 心血管器材:2030 年全球市場展望
 心血管臨床試驗市場規模、佔有率和趨勢分析報告:按階段、研究設計、適應症、研究設計與適應症、申辦者、地區和細分市場預測(2026-2033 年)
 心血管醫療設備市場規模、佔有率和成長分析:按產品、應用、最終用戶和地區分類-2026-2033年產業預測
 2026-2030年全球心血管醫療設備市場
 心血管醫療設備市場預測至2034年-按器材類型、應用、最終用戶和地區分類的全球分析
 心血管器材市場報告:按器材類型、應用、最終用戶和地區分類,2026-2034年