


 |
市場調查報告書
商品編碼
2121188
2026 年至 2035 年軍用和國防半導體市場機會、成長要素、產業趨勢和預測。Military and Defense Semiconductor Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球軍用和國防半導體市場預計到 2025 年將達到 62 億美元,年複合成長率為 7.4%,到 2035 年將達到 129 億美元。
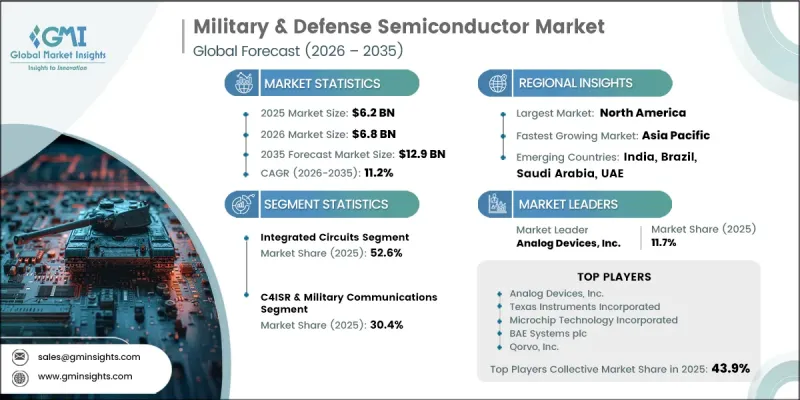
隨著國防機構加強對先進電子系統、智慧運算技術和關鍵任務半導體解決方案的投資,市場正在不斷擴張。多個地區國防費用的持續成長,加速了高性能半導體組件的採購,這些組件專為安全、可靠和嚴苛的運作環境而設計。對電子戰能力的日益重視、國防平台的現代化以及先進數位技術的應用,都增強了對具有更高處理能力和耐用性的專用半導體裝置的需求。人工智慧 (AI) 和機器學習在現代國防裝備中的整合,進一步增加了對高性能處理器、先進儲存技術和節能半導體架構的需求,這些組件能夠支援在複雜作戰場景中進行即時決策。此外,現有軍事系統的持續升級和下一代國防技術的研發,也推動了創新半導體解決方案的應用。這些因素,加上對安全可靠的國內半導體生產和穩健供應鏈的日益重視,將繼續支撐全球軍事工業和國防半導體市場的整體長期成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 62億美元 |
| 預計金額 | 129億美元 |
| 複合年成長率 | 7.4% |
國防預算的持續成長仍然是軍工和國防半導體市場的主要成長要素之一。人工智慧、機器學習和自主技術在國防領域的應用日益廣泛,持續推動對先進處理器、高密度儲存裝置和專用半導體組件的需求,這些元件不僅要具備卓越的運算性能,還要滿足嚴格的尺寸、重量和功耗要求。此外,對數位國防能力和先進電子系統投資的增加,也進一步強化了對創新半導體技術的需求,這些技術能夠提升作戰效能和任務準備水準。
到2025年,積體電路市佔率將達到52.6%,成為最大的產品類型。積體電路將繼續在各種國防電子系統中發揮至關重要的作用,為先進軍事應用提供所需的處理、控制、通訊和訊號管理功能。對高可靠性、環境適應性和專用積體電路技術的需求不斷成長,推動市場的持續擴張;而更嚴格的認證要求和專用製造流程的引入,進一步鞏固了該領域的長期重要性。
按應用領域分類,C4ISR 和軍事通訊領域仍將保持其最大佔有率,到 2025 年將佔市場佔有率的 30.4%。對先進指揮、通訊、情報、監視和偵察 (C4ISR) 能力的投資不斷增加,持續推動對先進半導體技術的需求,這些技術能夠實現安全通訊、快速資料處理和可靠的系統互通性。數位化互聯的國防平台和先進通訊網路的不斷擴展部署,進一步增加了對支撐現代軍事行動的高效能半導體解決方案的需求。
到2025年,北美軍工半導體市場將佔據全球39%的佔有率。政府對國防現代化的大力投入、對先進電子系統的持續採購以及對提升國內半導體製造能力的日益重視,將繼續支撐該地區的市場成長。對半導體創新、先進封裝技術和安全生產能力的持續投資,將鞏固北美在該領域的領先地位,並支持該地區國防半導體產業的長期發展。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 增加國防預算,用於建立具備先進電子戰和運算能力的系統。
- 對耐輻射、關鍵任務半導體的需求不斷成長
- 加速傳統國防平台的現代化進程
- 下一代國防系統對高性能半導體架構的需求日益成長
- 人工智慧/機器學習在國防行動和自主系統中的整合
- 產業潛在風險與挑戰
- 國防半導體領域研發強度高、產品認證週期長
- 出口管制架構和半導體供應鏈中日益加深的地緣政治碎片化
- 市場機遇
- 擴展天基防禦和衛星通訊基礎設施
- 下一代高超音速飛彈和先進飛彈防禦系統的研發
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的趨勢
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 法令半導體
- 功率二極體
- 整流器
- 電晶體
- 閘流體和可控矽整流器
- 電源模組
- 其他
- 光電子學
- LED 和紅外線 LED
- 雷射二極體
- 光電二極體
- 光耦合器/光隔離器
- 紅外線檢測器
- 其他
- 感應器
- MEMS感測器
- 壓力感測器
- 溫度感測器
- 磁感測器
- 化學和環境感測器
- 影像感測器
- 輻射感測器
- 其他
- 積體電路
- 模擬
- Micro
- 邏輯
- 記憶
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 土地系統
- 作戰車輛(戰車、步兵戰車、裝甲運兵車)
- 戰術車輛(悍馬、防地雷反伏擊車)
- 火砲和間接火力系統
- 地面防空(GBAD)系統
- 士兵系統和穿戴式電子設備
- 其他
- 海軍系統
- 水面作戰艦艇
- 航空母艦
- 潛水艇
- 兩棲作戰艦艇
- 無人水面/水下航行器(USV/UUV)
- 其他
- 機載系統
- 戰鬥機和攻擊機
- 運輸機及加油機
- 直升機(攻擊和運輸)
- 無人機和無人作戰飛行器
- 其他
- 空間系統
- 軍事通訊衛星
- 偵察/監視衛星
- 導航衛星(GPS/PNT)
- 飛彈預警衛星
- 空間情境察覺
- 其他
- 電子戰(EW)與訊號情報(SIGINT)系統
- 機載電子戰吊艙及干擾系統
- 海軍電子戰系統
- 地面電子戰(EW)與訊號情報(SIGINT)基地台
- 定向能量武器系統
- 飛彈和導引飛彈
- 彈道飛彈和巡航飛彈
- 精確導引炸彈和砲彈
- 反導/攔截系統
- 滯空攻擊彈藥
- C4ISR 和軍事通訊
- 戰術通訊網路和無線電
- 軍用衛星通訊(MILSATCOM)終端
- 指揮與控制(C2)系統
- ISR地面站和處理系統
第7章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第8章:公司簡介
- 全球主要公司
- Analog Devices, Inc.
- Texas Instruments Incorporated
- Microchip Technology Incorporated
- BAE Systems plc
- Qorvo, Inc.
- 該地區的主要公司
- 北美洲
- Northrop Grumman
- Raytheon Technologies
- L3Harris Technologies
- MACOM Technology Solutions
- CAES
- SkyWater Technology
- GlobalFoundries
- Teledyne Technologies
- 歐洲
- Infineon Technologies
- STMicroelectronics
- 北美洲
The Global Military & Defense Semiconductor Market was valued at USD 6.2 billion in 2025 and is estimated to grow at a CAGR of 7.4% to reach USD 12.9 billion by 2035.
The market is expanding as defense organizations increase investments in advanced electronic systems, intelligent computing technologies, and mission-critical semiconductor solutions. Rising defense spending across multiple regions continues to accelerate the procurement of high-performance semiconductor components designed for secure, reliable, and demanding operating environments. Growing emphasis on electronic warfare capabilities, modernization of defense platforms, and deployment of advanced digital technologies is strengthening demand for specialized semiconductor devices with enhanced processing performance and durability. The integration of artificial intelligence and machine learning into modern defense equipment is further increasing the need for powerful processors, advanced memory technologies, and energy-efficient semiconductor architectures capable of supporting real-time decision-making in complex operational conditions. In addition, ongoing upgrades of existing military systems and continued development of next-generation defense technologies are encouraging greater adoption of innovative semiconductor solutions. These factors, combined with increasing focus on secure domestic semiconductor production and resilient supply chains, continue to support long-term growth across the global Military & Defense Semiconductor Market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.2 Billion |
| Forecast Value | $12.9 Billion |
| CAGR | 7.4% |
The continued expansion of national defense budgets remains one of the primary growth drivers for the Military & Defense Semiconductor Market. Increasing adoption of artificial intelligence, machine learning, and autonomous technologies across defense applications is creating sustained demand for advanced processors, high-density memory devices, and specialized semiconductor components that deliver high computing performance while operating within strict size, weight, and power requirements. Growing investments in digital defense capabilities and advanced electronic systems are further strengthening demand for innovative semiconductor technologies that improve operational effectiveness and mission readiness.
The integrated circuits segment accounted for 52.6% share in 2025, making it the largest product category. Integrated circuits continue to play a vital role across a broad range of defense electronic systems because they provide the processing, control, communication, and signal management functions required for advanced military applications. Growing demand for highly reliable, ruggedized, and specialized integrated circuit technologies is supporting continued market expansion, while increasing qualification requirements and specialized manufacturing processes further reinforce the long-term importance of this segment.
The C4ISR & Military Communications segment held 30.4% share in 2025, holding the largest application share. Rising investments in advanced command, communication, intelligence, surveillance, and reconnaissance capabilities continue to drive demand for sophisticated semiconductor technologies that enable secure communications, rapid data processing, and reliable system interoperability. Increasing deployment of digitally connected defense platforms and advanced communication networks is further strengthening the need for high-performance semiconductor solutions that support modern military operations.
North America Military & Defense Semiconductor Market accounted for 39% share in 2025. Strong government investment in defense modernization, continued procurement of advanced electronic systems, and increasing emphasis on strengthening domestic semiconductor manufacturing capabilities continue to support regional market growth. Ongoing investments in semiconductor innovation, advanced packaging technologies, and secure production capabilities are reinforcing North America's leadership while supporting long-term expansion of the regional defense semiconductor industry.
Major companies operating in the global military & defense semiconductor market include Texas Instruments, Analog Devices, Microchip Technology, Infineon Technologies, STMicroelectronics, BAE Systems, Northrop Grumman, Raytheon Technologies, L3Harris Technologies, Qorvo, MACOM Technology Solutions, CAES (Honeywell), SkyWater Technology, GlobalFoundries, and Teledyne Technologies. Companies operating in the military & defense semiconductor market are strengthening their competitive positions by investing in advanced semiconductor technologies, secure manufacturing capabilities, and next-generation electronic solutions. Product innovation remains a key strategy, with manufacturers developing high-performance processors, specialized integrated circuits, advanced memory technologies, and energy-efficient semiconductor architectures designed for demanding defense applications. Strategic collaborations, long-term defense contracts, mergers, acquisitions, and technology partnerships are helping companies expand their capabilities and strengthen market presence. Businesses are also increasing research and development investments to improve semiconductor reliability, processing performance, cybersecurity, and system integration. Expanding domestic manufacturing capacity, strengthening supply chain resilience, and enhancing production capabilities further support long-term competitiveness.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Product type trends
- 2.2.2 Application trends
- 2.2.3 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising defense budgets for advanced electronic warfare and compute-enabled systems
- 3.2.1.2 Growth in demand for radiation-hardened, mission-critical semiconductors
- 3.2.1.3 Accelerated modernization of legacy defense platforms
- 3.2.1.4 Increasing need for high-performance semiconductor architectures in next-gen defense systems
- 3.2.1.5 Integration of AI/ML in defense operations and autonomous systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High R&D intensity and extended product qualification cycles for defense-grade semiconductors
- 3.2.2.2 Export control frameworks and escalating geopolitical fragmentation of semiconductor supply chains
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of space-based defense and satellite communication infrastructure
- 3.2.3.2 Development of next-generation hypersonic and advanced missile defense systems
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Discrete semiconductors
- 5.2.1 Power diodes
- 5.2.2 Rectifiers
- 5.2.3 Transistors
- 5.2.4 Thyristors & SCRs
- 5.2.5 Power modules
- 5.2.6 Others
- 5.3 Optoelectronics
- 5.3.1 LEDs & IR LEDs
- 5.3.2 Laser diodes
- 5.3.3 Photodiodes
- 5.3.4 Optocouplers / optoisolators
- 5.3.5 Infrared detectors
- 5.3.6 Others
- 5.4 Sensors
- 5.4.1 MEMS sensors
- 5.4.2 Pressure sensors
- 5.4.3 Temperature sensors
- 5.4.4 Magnetic sensors
- 5.4.5 Chemical & environmental sensors
- 5.4.6 Image sensors
- 5.4.7 Radiation sensors
- 5.4.8 Others
- 5.5 Integrated circuits
- 5.5.1 Analog
- 5.5.2 Micro
- 5.5.3 Logic
- 5.5.4 Memory
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Land systems
- 6.2.1 Combat vehicles (Tanks, IFVs, APCs)
- 6.2.2 Tactical vehicles (HMMWVs, MRAPs)
- 6.2.3 Artillery & indirect fire systems
- 6.2.4 Ground-based air defense (GBAD) systems
- 6.2.5 Soldier systems & wearable electronics
- 6.2.6 Others
- 6.3 Naval systems
- 6.3.1 Surface combatants
- 6.3.2 Aircraft carriers
- 6.3.3 Submarines
- 6.3.4 Amphibious warfare ships
- 6.3.5 Unmanned surface & underwater vehicles (USV/UUV)
- 6.3.6 Others
- 6.4 Airborne systems
- 6.4.1 Fighter & attack aircraft
- 6.4.2 Transport & tanker aircraft
- 6.4.3 Helicopters (attack & transport)
- 6.4.4 UAVs & UCAVs
- 6.4.5 Others
- 6.5 Space systems
- 6.5.1 Military communications satellites
- 6.5.2 Reconnaissance & surveillance satellites
- 6.5.3 Navigation satellites (GPS/PNT)
- 6.5.4 Missile warning satellites
- 6.5.5 Space situational awareness
- 6.5.6 Others
- 6.6 Electronic warfare (EW) & SIGINT systems
- 6.6.1 Airborne EW pods & jamming systems
- 6.6.2 Naval EW suites
- 6.6.3 Ground-based EW & SIGINT stations
- 6.6.4 Directed energy weapon systems
- 6.7 Missiles & guided munitions
- 6.7.1 Ballistic & cruise missiles
- 6.7.2 Precision-guided bombs & artillery shells
- 6.7.3 Anti-missile / interceptor systems
- 6.7.4 Loitering munitions
- 6.8 C4ISR & military communications
- 6.8.1 Tactical communication networks & radios
- 6.8.2 Military satellite communication (MILSATCOM) terminals
- 6.8.3 Command & control (C2) systems
- 6.8.4 ISR ground stations & processing systems
Chapter 7 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 North America
- 7.2.1 U.S.
- 7.2.2 Canada
- 7.3 Europe
- 7.3.1 Germany
- 7.3.2 UK
- 7.3.3 France
- 7.3.4 Spain
- 7.3.5 Italy
- 7.3.6 Russia
- 7.4 Asia Pacific
- 7.4.1 China
- 7.4.2 India
- 7.4.3 Japan
- 7.4.4 Australia
- 7.4.5 South Korea
- 7.5 Latin America
- 7.5.1 Brazil
- 7.5.2 Mexico
- 7.5.3 Argentina
- 7.6 Middle East and Africa
- 7.6.1 South Africa
- 7.6.2 Saudi Arabia
- 7.6.3 UAE
Chapter 8 Company Profiles
- 8.1 Global Key Players
- 8.1.1 Analog Devices, Inc.
- 8.1.2 Texas Instruments Incorporated
- 8.1.3 Microchip Technology Incorporated
- 8.1.4 BAE Systems plc
- 8.1.5 Qorvo, Inc.
- 8.2 Regional key players
- 8.2.1 North America
- 8.2.1.1 Northrop Grumman
- 8.2.1.2 Raytheon Technologies
- 8.2.1.3 L3Harris Technologies
- 8.2.1.4 MACOM Technology Solutions
- 8.2.1.5 CAES
- 8.2.1.6 SkyWater Technology
- 8.2.1.7 GlobalFoundries
- 8.2.1.8 Teledyne Technologies
- 8.2.2 Europe
- 8.2.2.1 Infineon Technologies
- 8.2.2.2 STMicroelectronics
- 8.2.1 North America


