


 |
市場調查報告書
商品編碼
2121126
從 2026 年到 2035 年,萬壽菊生產和葉黃素供應鏈的市場機會、成長促進因素、產業趨勢和預測。Marigold Flower Production and Lutein Supply Chain Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025 年全球萬壽菊生產和葉黃素供應鏈市場價值為 3.83 億美元,預計到 2035 年將以 7% 的複合年成長率成長至 7.526 億美元。
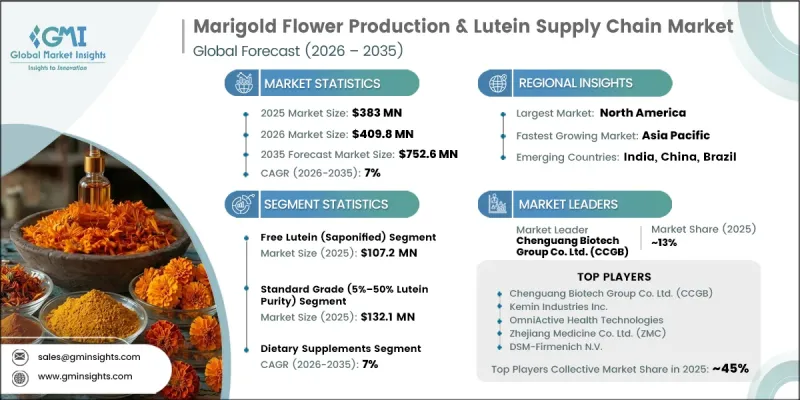
由於多項長期需求促進因素正在改變全球的生產和消費模式,該市場持續擴張。隨著人口老化,人們對支持視力健康的營養素的需求不斷成長,而長時間接觸電子螢幕也推動了各個年齡層對護眼產品的使用。監管方面的進步正在擴大葉黃素在嬰幼兒營養和機能性食品中的核准用途,為生產商創造了更多商機。同時,消費者對天然食品原料的偏好日益成長,加速了從合成色素轉向萬壽菊衍生替代品的轉變。印度和中國合計佔全球新鮮萬壽菊供應量的85%以上,而北美和歐洲則是高價值加工葉黃素原料的關鍵市場,形成了一個全球互聯但又具有區域性的價值鏈。全部區域透過有組織的零售管道銷售營養補充劑的成長進一步促進了該地區的消費。此外,該地區擁有全球最大的葉黃素萃取能力和成長最快的需求,鞏固了其作為未來市場擴張主要驅動力的地位,預計到2035年將持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 3.83億美元 |
| 預測金額 | 7.526億美元 |
| 複合年成長率 | 7% |
預計到2025年,皂化遊離葉黃素的銷售額將達到1.072億美元。這主要歸功於其生物利用度優於酯化葉黃素,使其成為支持成人眼部健康的膳食補充劑(包括軟膠囊和片劑)的首選原料。業界對標準化、高品質遊離葉黃素原料的強勁需求持續推動其在營養補充劑製造領域的廣泛應用,鞏固了該細分市場在整個萬壽菊生產和葉黃素供應鏈市場的主導地位。
預計到2025年,膳食補充劑市場規模將達到1.666億美元,並在2026年至2035年間以7%的複合年成長率成長。這一成長主要得益於廣泛的科學研究增強了消費者對葉黃素類營養產品的信心。消費者對預防性保健的持續關注,以及對眼睛健康的日益重視,推動了已開發市場和新興市場對富含葉黃素的膳食補充劑的穩定需求,從而支撐了整個預測期內的持續成長。
預計2025年,北美萬壽菊生產和葉黃素供應鏈市場規模將達到1.256億美元。該地區的主導地位得益於美國成熟的膳食補充劑行業以及穩定的法規環境,這些因素共同促進了補充劑、食品和嬰幼兒營養品領域原料的創新。豐富的市售營養產品,加上消費者對健康成分的持續需求,不斷為遍佈整個區域供應鏈的原料生產商創造機會。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 按產品形式
- 未來市場趨勢
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 遊離葉黃素(皂化)
- 葉黃素酯
- 萬壽菊油樹脂
- 葉黃素微珠
- 葉黃素粉/晶體
- 葉黃素油懸浮液
第6章 市場估計與預測:依純度分類,2022-2035年
- 標準級(葉黃素純度5%至50%)
- 高純度等級(葉黃素純度80%或更高)
- 食品級(葉黃素純度50%至79%)
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 營養補充品
- 食品/飲料
- 動物飼料
- 製藥
- 化妝品和個人護理
- 其他
第8章 市場估算與預測:供應鏈各階段,2022-2035年
- 中游(提取和加工)
- 下游(配方和分銷)
- 上游(種植和收穫)
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第10章:公司簡介
- Chenguang Biotech Group Co., Ltd.(CCGB)
- Kemin Industries, Inc.
- OmniActive Health Technologies
- DSM-Firmenich NV
- Zhejiang Medicine Co., Ltd.(ZMC)
- Divi's Nutraceuticals(Divi's Laboratories Ltd.)
- Synthite Industries Ltd.
- AVT Natural Products Ltd.
- Plant Lipids Pvt. Ltd.
- Olive Lifesciences Pvt. Ltd.
- Bio-gen Extracts Pvt. Ltd.
- Biomax Life Sciences Ltd.
- Lycored Ltd.
- Hunan Huakang Biotech Inc.
- Aturex Nutritionals
The Global Marigold Flower Production & Lutein Supply Chain Market was valued at USD 383 million in 2025 and is estimated to grow at a CAGR of 7% to reach USD 752.6 million by 2035.
The market continues to advance because of multiple long-term demand drivers that are reshaping both production and consumption patterns worldwide. Growing elderly populations are increasing demand for nutritional ingredients that support vision health, while prolonged exposure to digital screens is encouraging greater use of eye wellness products across different age groups. Regulatory developments are broadening the approved use of lutein in infant nutrition and functional food applications, creating additional commercial opportunities for manufacturers. At the same time, rising preference for naturally derived food ingredients is accelerating the replacement of synthetic color additives with marigold-derived alternatives. India and China collectively contribute more than 85% of the global raw marigold flower supply, whereas North America and Europe represent the primary markets for high-value processed lutein ingredients, creating a globally connected yet regionally specialized supply chain. Expanding dietary supplement distribution through organized retail channels across Asia Pacific is further supporting regional consumption. The region also combines the world's largest extraction capacity with the fastest-growing demand, reinforcing its position as the primary engine of future market expansion through 2035.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $383 Million |
| Forecast Value | $752.6 Million |
| CAGR | 7% |
The free lutein (saponified) segment generated USD 107.2 million in 2025, owing to the preferred choice as it offers improved bioavailability compared with ester-based lutein, making it well suited for adult eye health supplement formulations, including softgels and tablets. Strong industry preference for standardized, high-quality free lutein ingredients continues to support widespread adoption across dietary supplement manufacturing, reinforcing the segment's leading position within the overall marigold flower production & lutein supply chain market.
The dietary supplements segment accounted for USD 166.6 million in 2025 and is projected to grow at a 7% CAGR between 2026 and 2035 owing to the extensive scientific research that has strengthened confidence in lutein-based nutritional products. Continuous consumer interest in preventive health, combined with growing awareness of eye wellness, is encouraging consistent demand for lutein-enriched dietary supplements across developed and emerging markets, supporting sustained growth throughout the forecast period.
North America Marigold Flower Production & Lutein Supply Chain Market captured USD 125.6 million in 2025. Regional leadership is supported by the well-established dietary supplement industry in the United States and a stable regulatory environment that encourages ingredient innovation across supplements, food products, and infant nutrition applications. A broad portfolio of commercially available nutritional products, together with consistent consumer demand for health-focused ingredients, continues to create favorable opportunities for ingredient manufacturers operating throughout the regional supply chain.
Major companies operating in the global marigold flower production & lutein supply chain market include Chenguang Biotech Group Co., Ltd. (CCGB), Kemin Industries, Inc., OmniActive Health Technologies, DSM-Firmenich N.V., Zhejiang Medicine Co., Ltd. (ZMC), Divi's Nutraceuticals (Divi's Laboratories Ltd.), Synthite Industries Ltd., AVT Natural Products Ltd., Plant Lipids Pvt. Ltd., Olive Lifesciences Pvt. Ltd., Bio-gen Extracts Pvt. Ltd., Biomax Life Sciences Ltd., Lycored Ltd., Hunan Huakang Biotech Inc., and Aturex Nutritionals. Companies participating in the marigold flower production & lutein supply chain market are strengthening their competitive position by expanding extraction capacity, improving processing efficiency, and investing in advanced purification technologies to enhance product quality and consistency. Many manufacturers are building long-term sourcing relationships with marigold growers to secure reliable raw material availability while reducing supply chain risks. Businesses are also broadening their product portfolios to address demand from dietary supplements, functional foods, infant nutrition, and natural color applications. Strategic geographic expansion, partnerships with ingredient distributors, and stronger regional manufacturing capabilities are helping companies improve market access.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Product form
- 2.2.2 Purity grade
- 2.2.3 Application
- 2.2.4 Supply Chain Stage
- 2.2.5 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product form
- 3.9 Future market trends
- 3.10 Patent landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product Form, 2022–2035 (USD Million) (Kilo Tons)
- 5.1 Key trends
- 5.2 Free Lutein (Saponified)
- 5.3 Lutein Ester
- 5.4 Marigold Oleoresin
- 5.5 Lutein Beadlets
- 5.6 Lutein Powder/Crystalline
- 5.7 Lutein Oil Suspension
Chapter 6 Market Estimates and Forecast, By Purity Grade, 2022–2035 (USD Million) (Kilo Tons)
- 6.1 Key trends
- 6.2 Standard Grade (5%–50% Lutein Purity)
- 6.3 High Purity Grade (≥80% Lutein Purity)
- 6.4 Food Grade (50%–79% Lutein Purity)
Chapter 7 Market Estimates and Forecast, By Application, 2022–2035 (USD Million) (Kilo Tons)
- 7.1 Key trends
- 7.2 Dietary Supplements
- 7.3 Food & Beverages
- 7.4 Animal Feed
- 7.5 Pharmaceuticals
- 7.6 Cosmetics & Personal Care
- 7.7 Others
Chapter 8 Market Estimates and Forecast, By Supply Chain Stage, 2022–2035 (USD Million) (Kilo Tons)
- 8.1 Key trends
- 8.2 Midstream (Extraction & Processing)
- 8.3 Downstream (Formulation & Distribution)
- 8.4 Upstream (Cultivation & Harvesting)
Chapter 9 Market Estimates and Forecast, By Region, 2022–2035 (USD Million) (Kilo Tons)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 Saudi Arabia
- 9.6.2 South Africa
- 9.6.3 UAE
- 9.6.4 Rest of Middle East and Africa
Chapter 10 Company Profiles
- 10.1 Chenguang Biotech Group Co., Ltd. (CCGB)
- 10.2 Kemin Industries, Inc.
- 10.3 OmniActive Health Technologies
- 10.4 DSM-Firmenich N.V.
- 10.5 Zhejiang Medicine Co., Ltd. (ZMC)
- 10.6 Divi's Nutraceuticals (Divi's Laboratories Ltd.)
- 10.7 Synthite Industries Ltd.
- 10.8 AVT Natural Products Ltd.
- 10.9 Plant Lipids Pvt. Ltd.
- 10.10 Olive Lifesciences Pvt. Ltd.
- 10.11 Bio-gen Extracts Pvt. Ltd.
- 10.12 Biomax Life Sciences Ltd.
- 10.13 Lycored Ltd.
- 10.14 Hunan Huakang Biotech Inc.
- 10.15 Aturex Nutritionals

