


 |
市場調查報告書
商品編碼
2121105
汽車製造設備市場機會、成長促進因素、產業趨勢分析及2026-2035年預測。Auto Manufacturing Equipment Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球汽車製造設備市場預計到 2025 年將達到 336 億美元,年複合成長率為 5.1%,到 2035 年將達到 552 億美元。
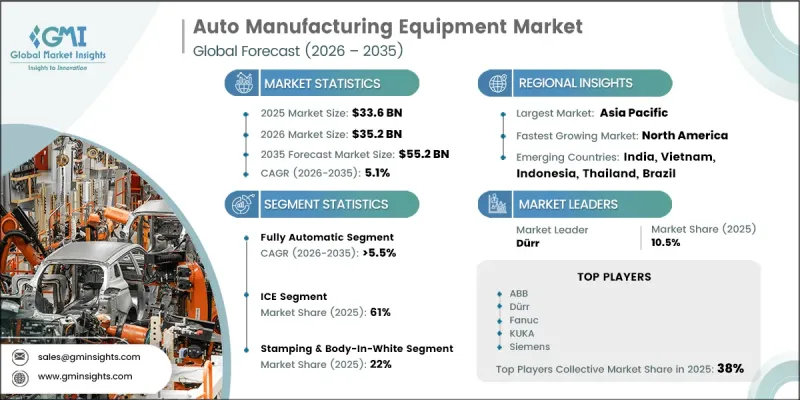
隨著電動車(EV)製造項目的不斷擴展,汽車製造商正在加大對生產設備的投資。向新型汽車平臺的轉型催生了對能夠滿足最新生產要求的專用設備的需求。電池組組裝、電力驅動組件生產、高速焊接、精密加工和自動化測試在汽車製造營運中日益重要。隨著汽車製造商採用新平台並升級生產設備,設備供應商對先進機械和自動化技術的需求也日益成長。製造商也尋求能夠提高效率、一致性和產量,同時又能適應不斷變化的車輛架構的生產系統。因此,對電動車生產投資的增加正在影響整個汽車產業的設備採購決策。同時,傳統汽車計畫的持續生產活動也維持了對現有生產設備的需求。為了因應這些趨勢,設備製造商正在擴展其技術能力,並開發能夠同時滿足不斷變化的汽車生產需求和現有需求的解決方案。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 336億美元 |
| 預測金額 | 552億美元 |
| 複合年成長率 | 5.1% |
預計到2025年,全自動化汽車零件市場佔有率將達到49%,並在2026年至2035年間以5.5%的複合年成長率成長。汽車原始設備製造商(OEM)正擴大採用全自動化生產設備,以提高生產效率並維持穩定的生產週期。自動化系統能夠以最小的人工干預完成機械加工、焊接、組裝、噴漆和檢測等任務。這種自動化程度使製造商能夠在保持產品品質穩定的同時提高產量。因此,不斷提高生產效率和生產一致性的努力正在推動全自動化汽車生產設備的持續普及。
預計到2025年,內燃機(ICE)市佔率將達到61%,並在2026年至2035年間以4%的複合年成長率成長。內燃機汽車的持續生產,尤其是在新興市場和成本敏感型市場,預計將維持對引擎、變速箱、排氣系統和燃油系統生產設備的需求。在整個預測期內,對汽車生產的持續需求將繼續支撐對內燃機相關製造製程設備的投資。
預計到2025年,亞太地區汽車製造設備市場規模將達到142億美元,佔全球市場佔有率的42%。該地區的強勁地位與其龐大的汽車製造基地和完善的供應鏈網路密切相關。中國、日本、印度和韓國聚集了許多汽車整車製造商和零件供應商,對生產機械和工廠自動化解決方案的需求龐大。這些國家持續存在的大規模汽車製造業務鞏固了亞太地區在全球汽車製造設備產業的主導地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 電動車生產計畫的加速推進,正在推動新建專用製造設施的需求。
- 工業4.0和智慧工廠計畫正在加速對自動化領域的投資。
- 全球汽車產量增加及整車廠產能擴張
- 輕質材料(鋁、碳纖維增強複合材料)的廣泛應用需要先進的成型設備。
- 產業潛在風險與挑戰
- 由於需要大量資本投入且投資回收期長,因此中小企業採用此技術受到限制。
- 貿易關稅增加了進口機器人、CNC系統和控制電子設備的成本。
- 互聯與人工智慧賦能的製造系統中的網路安全漏洞
- 市場機遇
- 超級工廠的建設催生了對電池和電動驅動設備製造用待開發區設施的需求。
- 對傳統內燃機(ICE)生產線進行改造和現代化,使其適用於混合動力汽車/電動車平台。
- 新興市場(印度、東南亞、墨西哥)汽車產量成長
- 協作機器人(cobot)為二級和三級供應商實現了自動化。
- 成長促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 人工智慧驅動的工業機器人
- 高速CNC加工系統
- 自動焊接和連接系統
- 伺服驅動壓力沖壓系統
- 自動化噴塗和表面處理系統
- 利用機器視覺進行品質檢測
- 新興技術
- 人工智慧驅動的自主製造系統
- 協作機器人(cobots)
- 自主移動機器人(AMR)
- 人工智慧驅動的機器視覺和缺陷檢測
- 汽車零件和模具的積層製造
- 利用數位孿生進行虛擬試運行
- 最新科技趨勢
- 價格分析,2022-2035年
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國職業安全與健康管理局 (OSHA) 對機器防護的要求
- 美國環保署(EPA)工業設備排放標準
- 美國國家消防協會(NFPA)工業機械安全標準
- 美國國家標準協會 (ANSI) B11 機械安全標準
- 加拿大職業安全與健康中心 (CCOHS) 機械安全需求
- 加拿大標準協會(CSA)機械安全標準
- 歐洲
- 歐盟機械法規
- 符合CE標誌
- REACH(化學品註冊、評估、授權和限制)
- RoHS(有害物質限制)指令
- 歐盟電磁相容性(EMC)指令
- 亞太地區
- 中國強制產品認證(CCC)
- 中國工業機械安全GB標準
- 印度機械和電氣設備安全標準
- 印度標準局 (BIS) 的工業機械標準
- 日本工業機械工業標準(JIS)
- 拉丁美洲
- 巴西國家計量院 (INMETRO) 機器認證要求
- 巴西機械和工作設備安全監管標準(NR)。
- 巴西NR-12機械安全法規
- 墨西哥的NOM機械安全標準
- 中東和非洲
- 海灣合作理事會標準化組織(GSO)機器安全要求
- 沙烏地阿拉伯標準、計量和品質組織(SASO)的工業機械標準
- 沙烏地阿拉伯機械安全技術法規
- 南非國家法規和標準局 (NRCS)
- 北美洲
- 波特的分析
- PESTLE分析
- 2022年成本細分分析
- 專利分析
- 貿易數據分析
- 2022-2025年進出口數量及價值趨勢
- 主要貿易路線及關稅的影響
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例-驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境-宏觀經濟與產業的順風
- 悲觀情景-宏觀經濟放緩或產業逆風
第4章 競爭格局,2025-2026年
- 介紹
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 2022-2035年十大公司生產與銷售分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按收入、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依設備類型分類,2022-2035年
- CNC工具工具機
- 加工中心
- 車床
- 銑床
- 鑽孔和研磨機
- 工業機器人
- 關節機器人
- SCARA機器人
- 協作機器人(cobots)
- 笛卡兒式和Delta式機器人
- 焊接設備
- 電弧焊接系統
- 電阻焊接和點焊系統
- 雷射焊接系統
- 超音波焊接系統
- 沖壓機和壓平機
- 機械壓平機
- 油壓壓平機
- 伺服驅動壓力機
- 射出成型機
- 液壓射出成型機
- 電動射出成型機
- 混合式射出成型機
- 輸送機和物料輸送系統
- 滾筒式輸送機
- 鍊式輸送機和架空輸送機
- 自動導引運輸車(AGV)
- 自主移動機器人(AMR)
- 塗裝和表面處理系統
- 電塗裝塗層(E-coat)系統
- 粉末塗裝系統
- 機器人噴漆房和噴漆生產線
- 密封劑和黏合劑應用系統
- 組裝和品管設備
- 生命週期結束(EOL)測試系統
- 尺寸檢測/三座標測量系統
- 利用機器視覺和人工智慧的檢測系統
- 洩漏檢測和NVH測試設備
第6章 市場估計與預測:依營運模式分類,2022-2035年
- 全自動
- 半自動
- 手動的
第7章 市場估算與預測:依製造階段分類,2022-2035年
- 壓制和白體
- 塗裝和表面處理
- 動力傳動系統和電力驅動組件
- 最終組裝
- 品管和測試
- 物料運輸及廠內物流
第8章 市場估算與預測:依最終用途分類,2022-2035年
- OEM組裝廠
- 一級供應商
- 二級和三級供應商
- 電動車和電池超級工廠
第9章 市場估計與預測:依促進因素分類,2022-2035年
- ICE
- BEV
- PHEV
- HEV
- 其他
第10章 市場估價與預測:依車輛類型分類,2022-2035年
- 搭乘用車
- 掀背車
- 轎車
- SUV
- 商用車輛
- 小型汽車
- 中型車
- 大型汽車
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐的
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 印尼
- 馬來西亞
- 新加坡
- 泰國
- 越南
- ANZ
- 拉丁美洲
- 巴西
- 阿根廷
- 墨西哥
- 中東和非洲
- UAE
- 沙烏地阿拉伯
- 南非
第12章:公司簡介
- 世界公司
- ABB
- ATS
- Bosch Rexroth
- Comau
- DMG Mori
- Durr
- FANUC
- KUKA
- Mitsubishi Electric
- Omron
- Rockwell Automation
- Siemens
- TRUMPF
- Yaskawa Electric
- 當地公司
- EMAG
- FFT Produktionssysteme
- GROB-WERKE
- Komax
- Schuler
- Wuxi Lead Intelligent Equipment
The Global Auto Manufacturing Equipment Market was valued at USD 33.6 billion in 2025 and is estimated to grow at a CAGR of 5.1% to reach USD 55.2 billion by 2035.
Automotive manufacturers are increasing capital spending on production machinery as electric vehicle manufacturing programs continue to expand. The transition toward new vehicle platforms is creating demand for specialized equipment capable of supporting modern production requirements. Battery pack assembly, e-drive component production, high-speed welding, precision machining, and automated testing are becoming increasingly important within automotive manufacturing operations. As automakers introduce new platforms and update production facilities, equipment suppliers are experiencing stronger demand for advanced machinery and automation technologies. Manufacturers are also seeking production systems that can improve efficiency, consistency, and throughput while supporting changing vehicle architectures. Growing investment in electrified vehicle production is therefore influencing equipment purchasing decisions across the automotive industry. At the same time, continued manufacturing activity across conventional vehicle programs is sustaining demand for established production machinery. These developments are encouraging equipment manufacturers to expand their technology capabilities and develop solutions that can address both evolving and established automotive production requirements.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $33.6 Billion |
| Forecast Value | $55.2 Billion |
| CAGR | 5.1% |
The fully automatic segment held a 49% share in 2025 and is forecast to grow at a CAGR of 5.5% from 2026 to 2035. Automotive OEMs are increasingly adopting fully automated production machinery to raise manufacturing throughput while maintaining consistent cycle times. Automated systems can perform machining, welding, assembly, painting, and inspection operations with limited human intervention. This level of automation allows manufacturers to increase production volumes while maintaining consistent output quality. Growing efforts to improve manufacturing efficiency and production consistency are therefore supporting the continued adoption of fully automatic automotive production equipment.
The ICE segment captured 61% share in 2025 and is forecast to grow at a CAGR of 4% share from 2026 to 2035. Continued manufacturing of internal combustion engine vehicles, particularly across emerging and cost-sensitive markets, is expected to sustain demand for equipment used in the production of engines, transmissions, exhaust systems, and fuel systems. Ongoing vehicle production requirements will continue to support investments in machinery designed for ICE-related manufacturing processes throughout the forecast period.
Asia Pacific Auto Manufacturing Equipment Market recorded a 42% share, generating USD 14.2 billion in 2025. The region's strong position is closely linked to its extensive automotive manufacturing base and established supply networks. China, Japan, India, and South Korea have significant concentrations of automotive OEMs and component suppliers, creating substantial demand for production machinery and factory automation solutions. The continued presence of large-scale automotive manufacturing operations across these countries is supporting Asia Pacific's leading position in the global auto manufacturing equipment industry.
Prominent companies operating in the global auto manufacturing equipment market include Siemens, ABB, FANUC, Bosch Rexroth, KUKA, Durr, Yaskawa, ATS, Comau, and Schuler. Companies in the global auto manufacturing equipment market are strengthening their market positions through automation innovation, product development, strategic partnerships, and expansion of manufacturing capabilities. Equipment manufacturers are investing in advanced automation technologies to help automotive producers improve throughput, production consistency, and operational efficiency. Companies are also developing flexible machinery capable of supporting changing vehicle architectures and evolving manufacturing requirements. Strategic collaborations with automotive OEMs and technology providers are helping equipment suppliers improve their solutions and strengthen customer relationships. Manufacturers are expanding their product portfolios across robotics, machining, assembly, welding, inspection, and other production technologies to address a wider range of automotive applications. Regional expansion is another important strategy as companies seek opportunities in high-growth automotive manufacturing markets. Investments in digital manufacturing, intelligent automation, and integrated production systems are also helping suppliers differentiate their offerings. By combining technological innovation with stronger service capabilities and broader geographic reach, market participants are working to secure long-term contracts and strengthen their competitive foothold in the global auto manufacturing equipment industry.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.2 Sources, by region
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Equipment
- 2.2.3 Mode of Operation
- 2.2.4 Manufacturing Stage
- 2.2.5 Propulsion
- 2.2.6 End Use
- 2.2.7 Vehicle
- 2.3 TAM Analysis, 2027-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Accelerating EV production programs driving demand for new & dedicated manufacturing equipment
- 3.2.1.2 Industry 4.0 & smart factory initiatives accelerating automation investment
- 3.2.1.3 Rising global vehicle production volumes & OEM capacity expansion
- 3.2.1.4 Increasing adoption of lightweight materials (aluminum, CFRP) requiring advanced forming equipment
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High capital investment requirements & long payback periods limiting SME adoption
- 3.2.2.2 Trade tariffs inflating cost of imported robots, CNC systems & control electronics
- 3.2.2.3 Cybersecurity vulnerabilities in connected & AI-enabled manufacturing systems
- 3.2.3 Market opportunities
- 3.2.3.1 Gigafactory buildout creating greenfield equipment demand for battery & e-drive manufacturing
- 3.2.3.2 Retrofitting & modernization of legacy ICE production lines for hybrid/EV platforms
- 3.2.3.3 Growth of vehicle production in emerging markets (India, Southeast Asia, Mexico)
- 3.2.3.4 Collaborative robots (cobots) unlocking automation for Tier-2 & Tier-3 suppliers
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.1.1 AI-enabled industrial robotics
- 3.4.1.2 High-speed CNC machining systems
- 3.4.1.3 Automated welding and joining systems
- 3.4.1.4 Servo-driven stamping and press systems
- 3.4.1.5 Automated painting and surface treatment systems
- 3.4.1.6 Machine vision-based quality inspection
- 3.4.2 Emerging technologies
- 3.4.2.1 AI-driven autonomous manufacturing systems
- 3.4.2.2 Collaborative robots (Cobots)
- 3.4.2.3 Autonomous mobile robots (AMRs)
- 3.4.2.4 AI-powered machine vision and defect detection
- 3.4.2.5 Additive manufacturing for automotive components and tooling
- 3.4.2.6 Digital twin-based virtual commissioning
- 3.4.1 Current technological trends
- 3.5 Price analysis, 2022-2035 (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 Occupational Safety and Health Administration (OSHA) Machine Guarding Requirements
- 3.6.1.2 Environmental Protection Agency (EPA) Emission Standards for Industrial Equipment
- 3.6.1.3 National Fire Protection Association (NFPA) Industrial Machinery Safety Standards
- 3.6.1.4 American National Standards Institute (ANSI) B11 Machinery Safety Standards
- 3.6.1.5 Canadian Centre for Occupational Health and Safety (CCOHS) Machinery Safety Requirements
- 3.6.1.6 Canadian Standards Association (CSA) Machinery Safety Standards
- 3.6.2 Europe
- 3.6.2.1 EU Machinery Regulation
- 3.6.2.2 CE Marking Compliance
- 3.6.2.3 REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals)
- 3.6.2.4 RoHS (Restriction of Hazardous Substances) Directive
- 3.6.2.5 EU Electromagnetic Compatibility (EMC) Directive
- 3.6.3 Asia Pacific
- 3.6.3.1 China Compulsory Certification (CCC)
- 3.6.3.2 China GB Standards for Industrial Machinery Safety
- 3.6.3.3 India Machinery and Electrical Equipment Safety Standards
- 3.6.3.4 Bureau of Indian Standards (BIS) Industrial Machinery Standards
- 3.6.3.5 Japanese Industrial Standards (JIS) for Industrial Machinery
- 3.6.4 Latin America
- 3.6.4.1 Brazilian National Institute of Metrology (INMETRO) Machinery Certification Requirements
- 3.6.4.2 Brazilian Regulatory Standards (NR) for Machinery and Work Equipment Safety
- 3.6.4.3 Brazilian NR-12 Machinery Safety Regulation
- 3.6.4.4 Mexican NOM Machinery Safety Standards
- 3.6.5 Middle East & Africa
- 3.6.5.1 GCC Standardization Organization (GSO) Machinery Safety Requirements
- 3.6.5.2 Saudi Standards, Metrology and Quality Organization (SASO) Industrial Machinery Standards
- 3.6.5.3 Saudi Technical Regulations for Machinery Safety
- 3.6.5.4 South African National Regulator for Compulsory Specifications (NRCS)
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Cost breakdown analysis, 2022
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Trade data analysis (Driven by Paid Research)
- 3.11.1 Import/export volume & value trends, 2022-2025
- 3.11.2 Key trade corridors & tariff impact
- 3.12 Capacity & production landscape (Driven by Primary Research)
- 3.12.1 Installed capacity by region & key producer
- 3.12.2 Capacity utilization rates & expansion pipelines
- 3.13 Impact of AI & generative AI on the market
- 3.13.1 AI-driven disruption of existing business models
- 3.13.2 GenAI use cases & adoption roadmap by segment
- 3.13.3 Risks, limitations & regulatory considerations
- 3.14 Sustainability and environmental aspects
- 3.14.1 Sustainable practices
- 3.14.2 Waste reduction strategies
- 3.14.3 Energy efficiency in production
- 3.14.4 Eco-friendly Initiatives
- 3.14.5 Carbon footprint considerations
- 3.15 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.15.1 Base Case — key macro & industry variables driving CAGR
- 3.15.2 Optimistic Scenarios — Favorable macro and industry tailwinds
- 3.15.3 Pessimistic Scenario — Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025-2026
- 4.1 Introduction
- 4.2 Company market share analysis, 2022-2025 (Revenue & Volume)
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Top 10 Company production & sales analysis, 2022-2035
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans and funding
- 4.7 Company tier benchmarking
- 4.7.1 Tier classification criteria & qualifying thresholds
- 4.7.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Equipment, 2022 - 2035 ($Mn, Units)
- 5.1 Key trends
- 5.2 CNC Machines
- 5.2.1 Machining Centers
- 5.2.2 Lathes
- 5.2.3 Milling Machines
- 5.2.4 Drilling & Grinding Machines
- 5.3 Industrial Robots
- 5.3.1 Articulated Robots
- 5.3.2 SCARA Robots
- 5.3.3 Collaborative Robots (Cobots)
- 5.3.4 Cartesian & Delta Robots
- 5.4 Welding Equipment
- 5.4.1 Arc Welding Systems
- 5.4.2 Resistance & Spot Welding Systems
- 5.4.3 Laser Welding Systems
- 5.4.4 Ultrasonic Welding Systems
- 5.5 Stamping & Press Machines
- 5.5.1 Mechanical Stamping Presses
- 5.5.2 Hydraulic Stamping Presses
- 5.5.3 Servo-Driven Presses
- 5.6 Injection Molding Machines
- 5.6.1 Hydraulic Injection Molding Machines
- 5.6.2 Electric Injection Molding Machines
- 5.6.3 Hybrid Injection Molding Machines
- 5.7 Conveyor & Material Handling Systems
- 5.7.1 Roller & Belt Conveyors
- 5.7.2 Chain & Overhead Conveyors
- 5.7.3 Automated Guided Vehicles (AGVs)
- 5.7.4 Autonomous Mobile Robots (AMRs)
- 5.8 Painting & Surface Treatment Systems
- 5.8.1 Electrocoating (E-coat) Systems
- 5.8.2 Powder Coating Systems
- 5.8.3 Robotic Spray Booths & Painting Lines
- 5.8.4 Sealant & Adhesive Application Systems
- 5.9 Assembly & Quality Control Equipment
- 5.9.1 End-of-Line (EOL) Testing Systems
- 5.9.2 Dimensional Inspection & CMM Systems
- 5.9.3 Machine Vision & AI-Powered Inspection Systems
- 5.9.4 Leak Detection & NVH Testing Equipment
Chapter 6 Market Estimates & Forecast, By Mode of Operation, 2022 - 2035 ($Mn, Units)
- 6.1 Key trends
- 6.2 Fully Automatic
- 6.3 Semi-Automatic
- 6.4 Manual
Chapter 7 Market Estimates & Forecast, By Manufacturing Stage, 2022 - 2035 ($Mn, Units)
- 7.1 Key trends
- 7.2 Stamping & Body-in-White
- 7.3 Painting & Surface Treatment
- 7.4 Powertrain & E-Drive Assembly
- 7.5 Final Assembly
- 7.6 Quality Control & Testing
- 7.7 Material Handling & Intra-Plant Logistics
Chapter 8 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 OEM Assembly Plants
- 8.3 Tier-1 Suppliers
- 8.4 Tier-2 & Tier-3 Suppliers
- 8.5 EV & Battery Gigafactories
Chapter 9 Market Estimates & Forecast, By Propulsion, 2022 - 2035 ($Mn)
- 9.1 Key trends
- 9.2 ICE
- 9.3 BEV
- 9.4 PHEV
- 9.5 HEV
- 9.6 Others
Chapter 10 Market Estimates & Forecast, By Vehicle, 2022 - 2035 ($Mn)
- 10.1 Key trends
- 10.2 Passenger Cars
- 10.2.1 Hatchback
- 10.2.2 Sedan
- 10.2.3 SUV
- 10.3 Commercial Vehicle
- 10.3.1 Light duty
- 10.3.2 Medium duty
- 10.3.3 Heavy duty
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 US
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 UK
- 11.3.2 Germany
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.3.6 Russia
- 11.3.7 Nordics
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Southeast Asia
- 11.4.5.1 Indonesia
- 11.4.5.2 Malaysia
- 11.4.5.3 Singapore
- 11.4.5.4 Thailand
- 11.4.5.5 Vietnam
- 11.4.6 ANZ
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Argentina
- 11.5.3 Mexico
- 11.6 MEA
- 11.6.1 UAE
- 11.6.2 Saudi Arabia
- 11.6.3 South Africa
Chapter 12 Company Profiles
- 12.1 Global Players
- 12.1.1 ABB
- 12.1.2 ATS
- 12.1.3 Bosch Rexroth
- 12.1.4 Comau
- 12.1.5 DMG Mori
- 12.1.6 Durr
- 12.1.7 FANUC
- 12.1.8 KUKA
- 12.1.9 Mitsubishi Electric
- 12.1.10 Omron
- 12.1.11 Rockwell Automation
- 12.1.12 Siemens
- 12.1.13 TRUMPF
- 12.1.14 Yaskawa Electric
- 12.2 Regional Players
- 12.2.1 EMAG
- 12.2.2 FFT Produktionssysteme
- 12.2.3 GROB-WERKE
- 12.2.4 Komax
- 12.2.5 Schuler
- 12.2.6 Wuxi Lead Intelligent Equipment

 再製造零件市場:全球產業分析、市場規模、市場佔有率及2026年至2033年預測,依零件類型、應用、車輛類型、銷售管道、再製造流程、國家及地區分類。
 汽車製造市場:按零件、引擎類型、車輛類型、材料類型、自動駕駛等級、銷售管道和最終用戶分類-2026-2032年全球市場預測
 汽車製造設備市場規模、佔有率和成長分析:按設備類型、自動化類型、車輛類型、應用和地區分類-2026-2033年產業預測
 汽車製造設備市場分析及預測(至2035年):類型、產品類型、服務、技術、零件、應用、製程、最終用戶、功能、設備
 汽車再製造市場規模、佔有率、成長及全球產業分析:按類型、應用和地區的洞察,2026-2034年的預測
 2026年全球汽車再製造市場報告汽車發電機市場:2026-2032年全球市場預測(按引擎類型、產品類型、輸出、冷卻方式、最終用戶和銷售管道)汽車契約製造市場:依製造服務類型、車輛類型、合約類型、動力系統、技術水準和最終用戶分類-2026-2032年全球市場預測汽車旋轉分度系統市場:依驅動類型、產品類型、分度角度、工位數量、最終用途分類,全球預測(2026-2032年)2026年全球汽車契約製造市場報告