


 |
市場調查報告書
商品編碼
2109256
地熱有機朗肯迴圈(ORC)市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Geothermal ORC Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球地熱有機朗肯迴圈(ORC)市場預計到 2025 年將達到 150 億美元,年複合成長率為 13.7%,到 2035 年將達到 545 億美元。
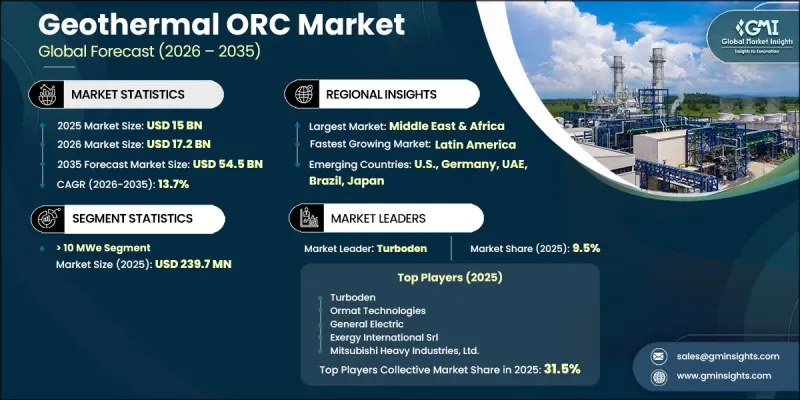
隨著全球能源產業持續向更清潔、更可靠、更永續的發電解決方案轉型,地熱有機朗肯迴圈(ORC)市場正經歷強勁成長。各國政府、電力公司和能源開發商正積極投資地熱發電技術,以加強減少碳排放和建立可靠再生能源來源。 ORC系統的重要性日益活性化,因為它們能夠有效地將低溫和中溫地熱資源轉化為電能,使以往不具商業性吸引力的資源得以利用。能源多元化和朗肯迴圈的不斷成長的需求進一步推動了全球範圍內基於ORC的地熱系統的應用。有利的政府政策、可再生能源獎勵和支持性投資框架為地熱項目開發創造了新的機會。同時,渦輪機性能的提升、工作流體的最佳化以及模組化ORC系統設計等技術進步,正在提高效率、降低營運成本並增強可靠性。分散式地熱發電系統的日益普及、與混合能源項目的整合以及在餘熱回收方面的應用,進一步鞏固了市場前景。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 150億美元 |
| 預計金額 | 545億美元 |
| 複合年成長率 | 13.7% |
根據發電量計算,預計到2025年,10兆瓦以上(MWe)細分市場的規模將達到2.397億美元。有機朗肯循環(ORC)技術相比傳統的熱能轉換方法具有顯著的柔軟性,因為它能夠在較寬的功率範圍內高效運作。此技術不僅適用於大規模熱發電廠,也適用於利用規模較小、輸出功率小規模的熱能資源進行發電。 ORC技術能夠高效、可靠且經濟地將熱能轉化為機械能和電能,這推動了其在高功率裝置中的應用日益廣泛。卓越的運作性能、適應性和更高的效率,也促進了ORC系統在10兆瓦以上(>10 MWe)發電設施中的部署。
預計2035年,美國地熱有機朗肯迴圈(ORC)市場規模將達122億美元。美國地熱資源的持續開發利用正在推動ORC技術的應用,尤其是在處理中低溫熱源方面。電網韌性、清潔能源轉型目標以及對可靠可再生能源發電日益成長的需求,正在加速公用事業公司和開發商採用地熱朗肯迴圈(ORC)解決方案。系統效率的提高以及將先前未開發的地熱資源轉化為生產性能源資產,進一步促進了市場擴張。此外,對現有工業資源地熱利用潛力的深入探索,也推動了ORC型發電系統的更廣泛應用。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 原物料供應及採購分析
- 生產能力評估
- 供應鏈韌性與風險因素
- 配電網路分析
- 監理情勢
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 成長潛力分析
- 波特的分析
- PESTLE分析
- 價格趨勢分析
- 按產能
- 按地區
- 生產能力和生產情況
- 主要生產商的生產能力
- 運轉率和擴張計劃
- 人工智慧和生成式人工智慧對市場(核心解決方案)的影響
- 人工智慧驅動的生產最佳化(核心解決方案)
- 預測性維護和故障檢測(核心解決方案)
- 新機會與趨勢
- 投資分析及未來展望
- 將永續發展措施與工業4.0結合
第4章 競爭情勢
- 介紹
- 企業市佔率分析:按地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 主要進展
- 重要合作夥伴關係和合作
- 主要併購活動
- 產品創新和新產品發布
- 市場擴大策略
- 競爭定位矩陣
第5章 市場規模及預測:依產量分類,2022-2035年
- 1兆瓦或更少
- 1~5 MWe
- 5~10 MWe
- 超過 10 兆瓦
第6章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 義大利
- 法國
- 比利時
- 西班牙
- 俄羅斯
- 亞太地區
- 中國
- 澳洲
- 印度
- 日本
- 韓國
- 菲律賓
- 泰國
- 越南
- 中東和非洲
- UAE
- 沙烏地阿拉伯
- 南非
- 拉丁美洲
- 巴西
- 阿根廷
第7章:公司簡介
- ABB
- ALFA LAVAL
- Atlas Copco AB
- Calnetix Technologies, LLC
- Elvosolar, as
- Enertime
- ENOGIA
- Exergy International Srl
- General Electric
- INTEC GMK
- Kaishan USA
- Mitsubishi Heavy Industries, Ltd.
- ORCAN ENERGY AG
- Ormat Technologies
- Triogen
- Turboden SpA
The Global Geothermal ORC Market was valued at USD 15 billion in 2025 and is estimated to grow at a CAGR of 13.7% to reach USD 54.5 billion by 2035.
The geothermal ORC market is witnessing strong growth as the global energy sector continues to shift toward cleaner, more reliable, and sustainable power generation solutions. Increasing efforts to reduce carbon emissions and establish dependable renewable energy sources are encouraging governments, utilities, and energy developers to invest in geothermal power technologies. Geothermal ORC systems are gaining importance because they can efficiently convert low- and medium-temperature geothermal heat resources into electricity, making previously less attractive resources commercially viable. The growing need for energy diversification and improved grid stability is further supporting the adoption of ORC-based geothermal systems worldwide. Favorable government policies, renewable energy incentives, and supportive investment frameworks are creating new opportunities for geothermal project development. At the same time, technological improvements in turbine performance, working fluid optimization, and modular ORC system designs are enhancing efficiency, lowering operating expenses, and improving reliability. The expanding use of decentralized geothermal power systems, integration with hybrid energy projects, and application in waste heat recovery are further strengthening the market outlook.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $15 Billion |
| Forecast Value | $54.5 Billion |
| CAGR | 13.7% |
Based on power output, the >10 MWe segment was valued at USD 239.7 million in 2025. ORC technology provides significant flexibility compared with conventional thermal energy conversion methods because it can operate efficiently across a wide range of power capacities. The technology supports electricity generation from both large-scale geothermal facilities and smaller thermal resources with lower output levels. Its ability to provide efficient, reliable, and cost-effective conversion of heat energy into mechanical and electrical power has increased its adoption across higher-capacity installations. The combination of strong operational performance, adaptability, and improved efficiency has contributed to the increasing deployment of ORC systems in facilities exceeding 10 megawatts electric (>10 MWe).
The U.S. geothermal ORC market is projected to reach USD 12.2 billion by 2035. The country's growing utilization of geothermal resources is supporting the expansion of ORC technology, especially for applications involving low- and medium-temperature heat sources. Rising attention toward grid resilience, clean energy transition goals, and reliable renewable electricity generation is encouraging utilities and developers to adopt geothermal ORC solutions. Advancements in system efficiency and the conversion of previously unused geothermal heat sources into productive energy assets are further contributing to market expansion. The increasing exploration of geothermal opportunities from existing industrial resources is also supporting the wider deployment of ORC-based power generation systems.
Key players operating in the global geothermal ORC industry include Exergy International Srl, ABB, Turboden S.p.A, General Electric, Ormat Technologies, Mitsubishi Heavy Industries, Ltd., ENOGIA, Atlas Copco AB, ALFA LAVAL, ORCAN ENERGY AG, Calnetix Technologies, LLC, Triogen, Kaishan USA, Enertime, INTEC GMK, and Elvosolar, a.s. Companies operating in the geothermal ORC market are implementing strategies focused on technological innovation, strategic partnerships, and expansion of product capabilities to strengthen their market position. Key participants are investing in research and development activities to improve ORC system efficiency, optimize turbine designs, and enhance operational reliability. Companies are also developing modular and scalable solutions to address the requirements of different geothermal applications and power capacities. Strategic collaborations with energy developers, utilities, and technology providers are helping businesses expand their global presence and accelerate project deployment. Market participants are focusing on cost reduction, advanced working fluid technologies, and integrated energy solutions to improve competitiveness.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Business trends
- 2.1.2 Power output trends
- 2.1.3 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material availability & sourcing analysis
- 3.1.2 Manufacturing capacity assessment
- 3.1.3 Supply chain resilience & risk factors
- 3.1.4 Distribution network analysis
- 3.2 Regulatory landscape
- 3.3 Industry impact forces
- 3.3.1 Growth drivers
- 3.3.2 Industry pitfalls & challenges
- 3.4 Growth potential analysis
- 3.5 Porter's analysis
- 3.5.1 Bargaining power of suppliers
- 3.5.2 Bargaining power of buyers
- 3.5.3 Threat of new entrants
- 3.5.4 Threat of substitutes
- 3.6 PESTEL analysis
- 3.6.1 Political factors
- 3.6.2 Economic factors
- 3.6.3 Social factors
- 3.6.4 Technological factors
- 3.6.5 Legal factors
- 3.6.6 Environmental factors
- 3.7 Price trend analysis (USD/MW)
- 3.7.1 By Capacity
- 3.7.2 By Region
- 3.8 Capacity & production landscape (Driven by Primary Research)
- 3.8.1 Capacity by key producer (Driven by Primary Research)
- 3.8.2 Capacity utilization rates & expansion pipelines (Driven by Primary Research)
- 3.9 Impact of AI & Generative AI on the market (Core Solution)
- 3.9.1 AI-Driven production optimization (Core Solution)
- 3.9.2 Predictive maintenance & fault detection (Core Solution)
- 3.10 Emerging opportunities & trends
- 3.11 Investment analysis & future prospects
- 3.12 Sustainability initiatives & industry 4.0 integration
Chapter 4 Competitive Landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East & Africa
- 4.2.5 Latin America
- 4.3 Key developments
- 4.3.1 Key partnerships & collaborations
- 4.3.2 Major M&A activities
- 4.3.3 Product innovations & launches
- 4.3.4 Market expansion strategies
- 4.4 Competitive positioning matrix
Chapter 5 Market Size and Forecast, By Power Output, 2022 - 2035 (MW & USD Million)
- 5.1 Key trends
- 5.2 <= 1 MWe
- 5.3 > 1 - 5 MWe
- 5.4 > 5 - 10 MWe
- 5.5 > 10 MWe
Chapter 6 Market Size and Forecast, By Region, 2022 - 2035 (MW & USD Million)
- 6.1 Key trends
- 6.2 North America
- 6.2.1 U.S.
- 6.2.2 Canada
- 6.2.3 Mexico
- 6.3 Europe
- 6.3.1 Germany
- 6.3.2 UK
- 6.3.3 Italy
- 6.3.4 France
- 6.3.5 Belgium
- 6.3.6 Spain
- 6.3.7 Russia
- 6.4 Asia Pacific
- 6.4.1 China
- 6.4.2 Australia
- 6.4.3 India
- 6.4.4 Japan
- 6.4.5 South Korea
- 6.4.6 Philippines
- 6.4.7 Thailand
- 6.4.8 Vietnam
- 6.5 Middle East & Africa
- 6.5.1 UAE
- 6.5.2 Saudi Arabia
- 6.5.3 South Africa
- 6.6 Latin America
- 6.6.1 Brazil
- 6.6.2 Argentina
Chapter 7 Company Profiles
- 7.1 ABB
- 7.2 ALFA LAVAL
- 7.3 Atlas Copco AB
- 7.4 Calnetix Technologies, LLC
- 7.5 Elvosolar, a.s.
- 7.6 Enertime
- 7.7 ENOGIA
- 7.8 Exergy International Srl
- 7.9 General Electric
- 7.10 INTEC GMK
- 7.11 Kaishan USA
- 7.12 Mitsubishi Heavy Industries, Ltd.
- 7.13 ORCAN ENERGY AG
- 7.14 Ormat Technologies
- 7.15 Triogen
- 7.16 Turboden S.p.A


