


 |
市場調查報告書
商品編碼
2109228
吸水紙市場機會、成長要素、產業趨勢分析及2026-2035年預測。Absorbent Paper Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球吸水紙市場預計到 2025 年將價值 1,500 億美元,以 4.9% 的複合年成長率成長,到 2035 年達到 2,418 億美元。
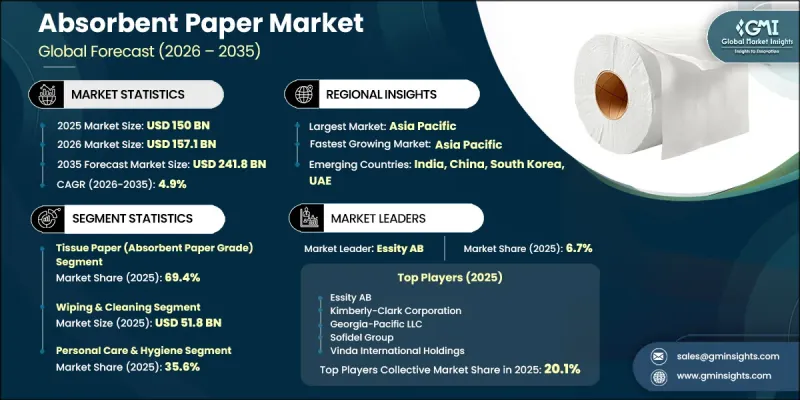
吸收性紙產業的穩定擴張主要得益於人們衛生和公共衛生意識的提高、一次性紙巾和個人用品消費量的增加,以及食品包裝和食品接觸領域對吸收性紙需求的成長。各行業尋求永續的替代一次性塑膠製品,加速向紙基替代品的轉型,也對市場產生了正面影響。對可回收纖維材料和環保生產方式的日益關注,進一步推動了市場成長,這與全球循環經濟計劃和減少廢棄物的目標相符。此外,對永續造紙、改進加工技術和資源高效製造的持續投資,使生產商能夠在滿足不斷變化的環境期望的同時,提供高性能的吸收性紙製品。隨著消費者和企業優先考慮衛生、便利和永續的材料選擇,住宅、商業、醫療保健、飯店和工業領域的需求不斷成長,並持續推動市場擴張。預計這些因素將在整個預測期內為全球吸收性紙市場創造長期成長機會。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 1500億美元 |
| 預測金額 | 2418億美元 |
| 複合年成長率 | 4.9% |
全球吸水紙產業持續維持成長勢頭,這主要得益於各終端用戶領域對一次性吸水紙製品的需求不斷成長,而這又源於人們日益增強的清潔意識和感染預防意識。公共設施、商業機構、醫療機構和住宅的強勁需求持續支撐著市場的穩定成長。同時,旨在推廣永續材料和減少塑膠廢棄物的監管措施也鼓勵製造商和終端用戶採用紙基和纖維基替代品。此外,政府對環保產品的持續政策支持,以及對可回收材料和永續生產方式投資的增加,進一步推動了全球市場對吸水紙解決方案的需求。
預計到2025年,吸水紙巾市佔率將達到69.4%。其主導地位得益於其在住宅、商業、醫療、旅館和公共設施等領域的廣泛應用。消費者衛生意識的提高、可支配收入的增加、對高階紙巾產品的偏好日益成長,以及公共和私人場所衛生措施的不斷加強,都持續推動著吸水紙巾的需求。預計這些因素將使該細分市場在整個預測期內保持主導地位。
預計到2025年,擦拭和清潔用品市場規模將達到518億美元。該行業的成長主要得益於住宅、商業、醫療、食品加工、酒店和工業等環境中吸水紙製品在清潔、維護和衛生管理方面的日益普及。更嚴格的衛生標準、更高的清潔頻率以及對一次性紙質清潔用品日益成長的依賴,持續推動著各終端用戶行業對產品的需求,從而支撐著市場的持續擴張。
到2025年,北美吸水紙市佔率將達到21.4%。該地區的成長主要得益於醫療保健、餐飲服務、飯店和商業領域對衛生和清潔紙製品的需求不斷成長。一次性紙巾產品需求的持續上升,以及食品安全和感染控制法規的日益嚴格,都將繼續推動全部區域市場的擴張。此外,各國政府和產業相關人員對永續造紙、再生纖維開發和資源高效生產技術的持續投資,也正在增強區域市場實力,並支持更廣泛的環境永續性目標。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 衛生意識的提高和對一次性衛生用品需求的成長
- 新興國家紙巾和衛生紙消費量增加
- 用紙製品取代一次性塑膠製品
- 食品包裝與食品接觸應用領域的擴展
- 人們對可回收和永續的紡織材料越來越感興趣。
- 產業潛在風險與挑戰
- 紙漿和原料成本波動
- 吸水紙製品性能與永續性之間的權衡
- 市場機遇
- 開發高性能、永續的吸水紙
- 吸水紙在食品包裝和特殊應用的發展
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 濕縐紙
- 乾皺紋紙
- 衛生紙(吸水紙級)
- 網格加固吸水紙
- 其他
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 擦拭和清洗
- 過濾和分離
- 保護/阻隔塗層
- 食品接觸應用
- 層壓板和複合材料的製造
- 其他
第7章 市場估計與預測:依最終用途產業分類,2022-2035年
- 醫療保健
- 食品/飲料
- 個人護理和衛生用品
- 工業和製造業
- 實驗室/研究
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- 全球主要公司
- Essity AB
- Kimberly-Clark Corporation
- Georgia-Pacific LLC
- Sofidel Group
- Vinda International Holdings
- 該地區的主要公司
- 北美洲
- Kruger Inc.
- Cascades Inc.
- Domtar Corporation
- Mativ Holdings, Inc.
- 亞太地區
- Asia Pulp & Paper(APP)
- Nippon Paper Industries
- Hengan International Group
- Oji Holdings Corporation
- 歐洲
- Metsa Group
- WEPA Group
- Ahlstrom Oyj
- 北美洲
- 小眾玩家/顛覆者
- CMPC(Empresas CMPC SA)
- Lucart SpA
The Global Absorbent Paper Market was valued at USD 150 billion in 2025 and is estimated to grow at a CAGR of 4.9% to reach USD 241.8 billion by 2035.
The steady expansion of the absorbent paper industry is supported by growing awareness of hygiene and sanitation, rising consumption of disposable tissue and personal hygiene products, and increasing demand for absorbent paper across food packaging and food-contact applications. The market is also benefiting from the accelerating transition toward paper-based alternatives as industries seek sustainable replacements for single-use plastics. Rising emphasis on recyclable, fiber-based materials and environmentally responsible manufacturing practices is further encouraging market growth in line with global circular economy initiatives and waste reduction goals. In addition, continuous investments in sustainable paper production, improved processing technologies, and resource-efficient manufacturing are enabling producers to deliver high-performance absorbent paper products while meeting evolving environmental expectations. Increasing demand from residential, commercial, healthcare, hospitality, and industrial sectors continues to reinforce market expansion as consumers and businesses prioritize hygiene, convenience, and sustainable material choices. These factors are expected to create long-term growth opportunities for the global absorbent paper market throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $150 Billion |
| Forecast Value | $241.8 Billion |
| CAGR | 4.9% |
The global absorbent paper industry continues to gain momentum as heightened awareness of cleanliness and infection prevention drives higher consumption of disposable absorbent paper products across multiple end-use sectors. Strong demand from institutional, commercial, healthcare, and residential environments continues to support consistent market growth. At the same time, regulatory measures promoting sustainable materials and reducing plastic waste are encouraging manufacturers and end users to adopt paper- and fiber-based alternatives. Ongoing policy support for environmentally responsible products, combined with increasing investments in recyclable materials and sustainable production practices, is further strengthening demand for absorbent paper solutions across global markets.
The tissue paper (absorbent paper grade) segment held a 69.4% share in 2025. Its leading position is supported by widespread use across residential, commercial, healthcare, hospitality, and institutional applications. Growing consumer focus on hygiene, rising disposable income, increasing preference for premium tissue products, and expanding sanitation initiatives across public and private facilities continue to drive demand for absorbent tissue paper. These factors are expected to sustain the segment's leadership over the forecast period.
The wiping & cleaning segment reached USD 51.8 billion in 2025. Segment growth is being fueled by increasing utilization of absorbent paper products for cleaning, maintenance, and sanitation across residential, commercial, healthcare, food processing, hospitality, and industrial environments. Expanding hygiene standards, rising cleaning frequency, and greater reliance on disposable paper-based cleaning solutions continue to strengthen product demand across a wide range of end-use industries, supporting sustained market expansion.
North America Absorbent Paper Market accounted for 21.4% share in 2025. Regional growth is being driven by rising consumption of hygiene and sanitary paper products across healthcare, food service, hospitality, and commercial sectors. Increasing demand for disposable tissue products, together with stricter food safety and infection control regulations, continues to support market expansion throughout the region. In addition, ongoing investments by governments and industry participants in sustainable paper manufacturing, recycled fiber development, and resource-efficient production technologies are strengthening the regional market while supporting broader environmental sustainability objectives.
Major companies operating in the global absorbent paper market include Ahlstrom Oyj, Asia Pulp & Paper (APP), Cascades Inc., CMPC (Empresas CMPC S.A.), Domtar Corporation, Essity AB, Georgia-Pacific LLC, Hengan International Group, Kimberly-Clark Corporation, Kruger Inc., Lucart S.p.A., Mativ Holdings, Inc., Metsa Group, Nippon Paper Industries, Oji Holdings Corporation, Sofidel Group, Vinda International Holdings, and WEPA Group. Companies operating in the absorbent paper industry are strengthening their market position by investing in sustainable manufacturing technologies, product innovation, and production capacity expansion. Many manufacturers are increasing the use of recycled fiber, improving resource efficiency, and adopting environmentally responsible production processes to align with evolving regulatory requirements and customer preferences. Businesses are also focusing on developing high-quality absorbent paper products with enhanced performance, durability, and softness to differentiate their product portfolios. Strategic partnerships, acquisitions, and distribution network expansion are helping companies improve market reach and secure long-term supply capabilities.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Product type trends
- 2.2.2 Application trends
- 2.2.3 End-use industry trends
- 2.2.4 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising hygiene awareness and demand for single-use sanitary products
- 3.2.1.2 Growing consumption of tissue and hygiene paper in emerging economies
- 3.2.1.3 Shift toward paper-based alternatives to single-use plastics
- 3.2.1.4 Expansion of food packaging and food-contact applications
- 3.2.1.5 Increasing focus on recyclable and sustainable fiber-based materials
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Volatility in pulp and raw material costs
- 3.2.2.2 Performance–sustainability trade-offs in absorbent paper products
- 3.2.3 Market opportunities
- 3.2.3.1 Development of high-performance sustainable absorbent paper
- 3.2.3.2 Expansion of absorbent paper in food packaging and specialty applications
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Wet crepe paper
- 5.3 Dry crepe paper
- 5.4 Tissue paper (absorbent paper grade)
- 5.5 Scrim-reinforced absorbent paper
- 5.6 Others
Chapter 6 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Wiping & cleaning
- 6.3 Filtration & separation
- 6.4 Protection & barrier covering
- 6.5 Food contact
- 6.6 Lamination & composite manufacturing
- 6.7 Others
Chapter 7 Market Estimates and Forecast, By End-Use Industry, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Healthcare & Medical
- 7.3 Food & Beverage
- 7.4 Personal care & hygiene
- 7.5 Industrial & manufacturing
- 7.6 Laboratory & research
- 7.7 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global Key Players
- 9.1.1 Essity AB
- 9.1.2 Kimberly-Clark Corporation
- 9.1.3 Georgia-Pacific LLC
- 9.1.4 Sofidel Group
- 9.1.5 Vinda International Holdings
- 9.2 Regional key players
- 9.2.1 North America
- 9.2.1.1 Kruger Inc.
- 9.2.1.2 Cascades Inc.
- 9.2.1.3 Domtar Corporation
- 9.2.1.4 Mativ Holdings, Inc.
- 9.2.2 Asia Pacific
- 9.2.2.1 Asia Pulp & Paper (APP)
- 9.2.2.2 Nippon Paper Industries
- 9.2.2.3 Hengan International Group
- 9.2.2.4 Oji Holdings Corporation
- 9.2.3 Europe
- 9.2.3.1 Metsa Group
- 9.2.3.2 WEPA Group
- 9.2.3.3 Ahlstrom Oyj
- 9.2.1 North America
- 9.3 Niche Players/Disruptors
- 9.3.1 CMPC (Empresas CMPC S.A.)
- 9.3.2 Lucart S.p.A.


