


 |
市場調查報告書
商品編碼
2109224
預警與控制(AEW&C)系統市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Airborne Early Warning and Control (AEWandC) System Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球預警與控制(AEW&C)系統市場預計到 2025 年將達到 64 億美元,年複合成長率為 5.9%,到 2035 年將達到 115 億美元。
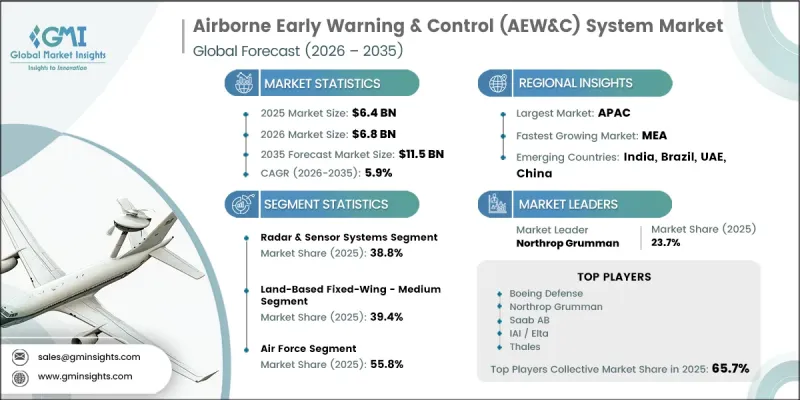
市場成長主要受地緣政治不確定性加劇、全球國防費用增加、各國防機構空中監視能力持續現代化等因素驅動。老舊空中監視機隊的更新換代,以及對增強空域監視和作戰準備能力日益成長的需求,持續推動長期採購活動。不斷擴大的國防現代化舉措和對先進監視技術投入的增加,也創造了有利的成長機會。此外,現代空中威脅日益複雜,以及對一體化、以網路為中心的軍事行動的日益重視,促使各國防機構投資於下一代空中指揮和監視系統。多個地區加強國內國防製造能力的努力也進一步促進了市場擴張。空中預警與控制(AEW&C)系統市場也受惠於航空電子設備、監視技術、任務系統和數位通訊領域的持續進步。這些進步提高了作戰效率,增強了情境察覺能力,並支援在日益複雜的作戰環境中實現更有效的國防協調。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 64億美元 |
| 預計金額 | 1150萬美元 |
| 複合年成長率 | 5.9% |
不斷成長的國防預算持續為空中預警與控制(AEW&C)系統市場提供長期支持,使各國政府能夠投資於先進的空中監視平台和尖端國防能力。老舊飛機的不斷退役以及維持作戰準備的需要,催生了穩定的替換需求,使其受短期預算波動的影響相對較小。同時,空中監視技術的進步和不斷變化的任務需求,推動了更靈活高效的平台配置的開發,從而支持持續創新,並擴大了全球國防市場的採購機會。
到2025年,雷達和感測器系統領域將佔據38.8%的市場。雷達和感測器技術在飛機探測、監視、追蹤和任務效能方面發揮著至關重要的作用,這支撐了其主導地位。由於其技術複雜性和性能要求,這些系統在專案總投資中佔有很大比例。對更強探測能力、更高追蹤精度和更強監視性能的日益成長的需求,持續推動著新飛機和現代化改造項目中對先進雷達和感測器技術的持續投資。
2025年,陸基固定翼(中型)飛機市佔率將達到39.4%。該細分市場憑藉其在作戰航程、監視能力、有效載荷和總運營成本方面的出色平衡,持續引領市場。中型固定翼平台具有部署柔軟性高、維護效率高、任務性能優異等優點,使其成為尋求經濟高效的空中監視能力的國家國防機構的理想選擇。其對各種作戰需求的適應性也持續推動著其在多個地區的擴張。
預計到2025年,北美預警與控制(AEW&C)系統市佔率將達到29.5%。這一區域成長主要得益於國防現代化方面的持續投資、先進機載監視平台的持續採購以及長期軍事能力提升計畫。不斷努力提高作戰準備水準、加強空域監視以及擴展綜合防禦能力,正在推動對先進AEW&C系統的穩定需求。長期國防規劃和對戰略監視技術的持續投資預計將在整個預測期內支撐市場持續成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 全球地緣政治緊張局勢加劇和國防預算不斷增加
- 老舊預警機的現代化改造與更換。
- 無人機、巡航飛彈和低能見度飛機帶來的威脅日益加劇。
- 對以網路為中心、可互通的聯合行動的需求日益成長。
- 亞太地區(印度、中國、韓國、日本)國內國防工業的擴張
- 產業潛在風險與挑戰
- 高昂的採購、開發和維護成本
- 一批老舊飛機,交付週期長,維修成本。
- 市場機遇
- 公務機作為經濟高效的預警機平台,在特殊任務中的崛起。
- 人工智慧與人類和無人協作技術的融合
- 促進因素
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 生產能力和生產情況
- 主要生產商的生產能力
- 運轉率和擴張計劃
第4章 競爭情勢
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 雷達感測器系統
- 任務系統和軟體
- 通訊和數據鏈路系統
- 電子支援措施(ESM)
- 辨識友善/友善反對派(IFF)
第6章 市場估計與預測:依平台類型分類,2022-2035年
- 地面固定翼飛機 - 大型(運輸機等級)
- 地面型固定翼飛機 - 中型
- 地面固定翼飛機 - 輕型
- 艦載固定翼飛機
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 防空與威脅偵測
- 指揮、控制和作戰管理(C2/BM)
- 海上情境察覺
- 邊境/國防安全保障
第8章 市場估算與預測:依最終用戶分類,2022-2035年
- 空軍
- 海軍
- 聯合與聯合防禦司令部
- 國防安全保障和邊境管制機構
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Boeing Defense, Space & Security
- Northrop Grumman Corporation
- Thales Group
- Airbus Defence & Space
- Raytheon Intelligence & Space(RTX)
- Israel Aerospace Industries(IAI)/Elta Systems
- Elbit Systems
- Embraer Defence & Security
- 該地區的主要公司
- 北美洲
- L3Harris Technologies
- 亞太地區
- Hindustan Aeronautics Limited(HAL)
- 歐洲
- Saab AB
- Leonardo SpA
- Indra Sistemas
- Turkish Aerospace Industries(TAI/TUSAS)
- 北美洲
- 小眾玩家/顛覆者
- General Atomics Aeronautical Systems
- Viasat Inc.
The Global Airborne Early Warning & Control (AEW&C) System Market was valued at USD 6.4 billion in 2025 and estimated to grow at a CAGR of 5.9% to reach USD 11.5 billion by 2035.
Market growth is driven by rising geopolitical uncertainties, increasing global defense spending, and continuous modernization of airborne surveillance capabilities across defense organizations. The replacement of aging airborne surveillance fleets, combined with the growing need to strengthen airspace monitoring and operational readiness, continues to support long-term procurement activities. Expanding defense modernization initiatives and increasing investments in advanced surveillance technologies are also creating favorable growth opportunities. In addition, the rising complexity of modern aerial threats and the growing emphasis on integrated, network-centric military operations are encouraging defense agencies to invest in next-generation airborne command and surveillance systems. Increasing efforts to strengthen domestic defense manufacturing capabilities across several regions are further supporting market expansion. The airborne early warning & control (AEW&C) system market is also benefiting from continuous advancements in avionics, surveillance technologies, mission systems, and digital communications that enhance operational efficiency, improve situational awareness, and support more effective defense coordination across increasingly complex operational environments.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.4 Billion |
| Forecast Value | $11.5 Million |
| CAGR | 5.9% |
Growing defense budgets continue to provide long-term support for the airborne early warning & control (AEW&C) system market, enabling governments to invest in advanced airborne surveillance platforms and modern defense capabilities. The ongoing retirement of aging aircraft and the need to maintain operational readiness are creating consistent replacement opportunities that remain relatively unaffected by short-term budget fluctuations. At the same time, advancements in airborne surveillance technologies and evolving mission requirements are encouraging the development of more flexible and efficient platform configurations, supporting continuous innovation and expanding procurement opportunities across global defense markets.
The radar and sensor systems segment accounted for 38.8% share in 2025. This leadership is supported by the essential role of radar and sensor technologies in aircraft detection, surveillance, tracking, and mission effectiveness. These systems represent a significant portion of overall program investment due to their technical complexity and performance requirements. Increasing demand for enhanced detection capabilities, improved tracking accuracy, and stronger surveillance performance continues to support sustained investments in advanced radar and sensor technologies for both new aircraft and modernization programs.
The land-based fixed-wing - medium segment held 39.4% share in 2025. The segment continues to lead the market by offering an effective balance of operational range, surveillance capability, payload capacity, and overall operating costs. Medium-sized fixed-wing platforms provide greater deployment flexibility, improved maintenance efficiency, and strong mission performance, making them an attractive solution for national defense organizations seeking cost-effective airborne surveillance capabilities. Their adaptability to a wide range of operational requirements continues to support growing adoption across multiple regions.
North America Airborne Early Warning & Control (AEW&C) System Market accounted for 29.5% share in 2025. Regional growth is supported by sustained investments in defense modernization, continued procurement of advanced airborne surveillance platforms, and long-term military capability enhancement programs. Ongoing efforts to improve operational readiness, strengthen airspace surveillance, and expand integrated defense capabilities continue to create stable demand for advanced AEW&C systems. Long-term defense planning and consistent investments in strategic surveillance technologies are expected to support continued market growth throughout the forecast period.
Major companies operating in the global airborne early warning & control (AEW&C) system market include Airbus Defence & Space, Boeing Defense, Space & Security, Elbit Systems, Embraer Defence & Security, General Atomics Aeronautical Systems, Hindustan Aeronautics Limited (HAL), Indra Sistemas, Israel Aerospace Industries (IAI) / Elta Systems, L3Harris Technologies, Leonardo S.p.A., Northrop Grumman Corporation, Raytheon Intelligence & Space (RTX), Saab AB, Thales Group, Turkish Aerospace Industries (TAI/TUSAS), and Viasat Inc. Companies operating in the airborne early warning & control (AEW&C) system market are focusing on continuous technology innovation, platform modernization, and strategic partnerships to strengthen their competitive position. Leading manufacturers are investing in research and development to enhance surveillance capabilities, mission systems, digital communications, and operational efficiency while meeting evolving defense requirements. Businesses are expanding collaboration with defense agencies, aircraft manufacturers, and technology providers to accelerate product development and improve program execution. Companies also prioritize long-term maintenance, upgrade, and lifecycle support services to strengthen customer relationships and generate recurring revenue.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Component trends
- 2.2.2 Platform Type trends
- 2.2.3 Application trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Escalating Geopolitical Tensions and Rising Defense Budgets Worldwide
- 3.2.1.2 Modernization and Replacement of Aging AEW&C Fleets
- 3.2.1.3 Increasing Threat from Drones, Cruise Missiles, and Low-Observable Aircraft
- 3.2.1.4 Growing Demand for Network-Centric, Interoperable Coalition Operations
- 3.2.1.5 Expansion of Indigenous Defense Manufacturing in Asia-Pacific (India, China, South Korea, Japan)
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Procurement, Development, and Maintenance Costs
- 3.2.2.2 Aging Fleets with Long Delivery Timelines and Rising Sustainment Costs
- 3.2.3 Market opportunities
- 3.2.3.1 Rise of Missionized Business Jets as Cost-Effective AEW&C Platforms
- 3.2.3.2 Integration of AI and Manned-Unmanned Teaming Technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.2 Europe
- 3.5.3 Asia Pacific
- 3.5.4 Latin America
- 3.5.5 Middle East & Africa
- 3.6 Porter’s analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database)
- 3.8.1 Import/Export Volume & Value Trends
- 3.8.2 Key Trade Corridors & Tariff Impact
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Production Capacity by Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Company market share analysis, 2025
- 4.1.1 By Region
- 4.1.1.1 North America
- 4.1.1.2 Europe
- 4.1.1.3 Asia-Pacific
- 4.1.1.4 Latin America
- 4.1.1.5 Middle East and Africa
- 4.1.2 Market Concentration Analysis
- 4.1.1 By Region
- 4.2 Competitive analysis of major market players
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Component, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Radar & Sensor Systems
- 5.3 Mission Systems & Software
- 5.4 Communication & Data Link Systems
- 5.5 Electronic Support Measures (ESM)
- 5.6 Identification Friend or Foe (IFF)
Chapter 6 Market Estimates and Forecast, By Platform Type, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Land-Based Fixed-Wing - Large (Transport-Class)
- 6.3 Land-Based Fixed-Wing - Medium
- 6.4 Land-Based Fixed-Wing - Light
- 6.5 Carrier-Based Fixed-Wing
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Air Defense & Threat Detection
- 7.3 Command, Control & Battle Management (C2/BM)
- 7.4 Maritime Domain Awareness
- 7.5 Border & Homeland Security
Chapter 8 Market Estimates and Forecast, By End-User, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Air Force
- 8.3 Navy
- 8.4 Joint & Allied Defense Commands
- 8.5 Homeland Security & Border Agencies
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Boeing Defense, Space & Security
- 10.1.2 Northrop Grumman Corporation
- 10.1.3 Thales Group
- 10.1.4 Airbus Defence & Space
- 10.1.5 Raytheon Intelligence & Space (RTX)
- 10.1.6 Israel Aerospace Industries (IAI) / Elta Systems
- 10.1.7 Elbit Systems
- 10.1.8 Embraer Defence & Security
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 L3Harris Technologies
- 10.2.2 Asia Pacific
- 10.2.2.1 Hindustan Aeronautics Limited (HAL)
- 10.2.3 Europe
- 10.2.3.1 Saab AB
- 10.2.3.2 Leonardo S.p.A.
- 10.2.3.3 Indra Sistemas
- 10.2.3.4 Turkish Aerospace Industries (TAI/TUSAS)
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 General Atomics Aeronautical Systems
- 10.3.2 Viasat Inc.


