


 |
市場調查報告書
商品編碼
2109183
聚四氟乙烯膠帶及薄膜市場機會、成長促進因素、產業趨勢分析及2026-2035年預測PTFE Tapes and Films Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球聚四氟乙烯膠帶和薄膜市場預計到 2025 年將達到 9.168 億美元,年複合成長率為 5.4%,到 2035 年將達到 16 億美元。
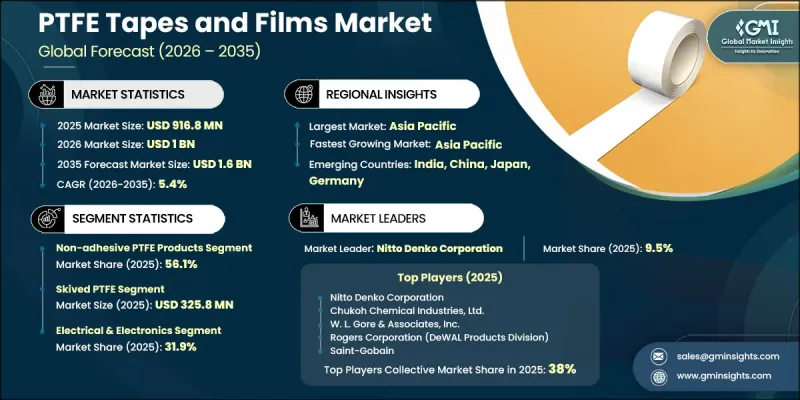
受半導體製造、先進電子產品和高性能工業應用領域需求成長的推動,聚四氟乙烯(PTFE)膠帶和薄膜產業正經歷穩定成長。對可靠的電絕緣材料、耐化學腐蝕解決方案和熱穩定性組件日益成長的需求,正在推動多個行業的市場成長。 PTFE膠帶和薄膜因其在極端溫度下的優異性能、耐化學腐蝕性和低摩擦特性而日益重要。航太、交通運輸和通訊技術領域對輕質耐用材料的日益普及,進一步刺激了市場需求。此外,高頻電子系統對低損耗介電材料的需求不斷成長,也為PTFE產品創造了新的成長機會。半導體技術的持續進步和國內電子製造業的發展,也促進了全球PTFE膠帶和薄膜消費量的成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 9.168億美元 |
| 預測金額 | 16億美元 |
| 複合年成長率 | 5.4% |
半導體生產和先進電子系統的擴張推動了對聚四氟乙烯(PTFE)膠帶和薄膜的強勁需求。這些材料具有優異的絕緣性、耐熱性和耐化學性,使其適用於嚴苛的生產環境。 PTFE產品在半導體和電子設備製造中絕緣、介電保護、掩蔽和表面保護等特殊應用領域的日益普及,也促進了市場的發展。此外,持續加強國內半導體產能建置也推動了高性能材料的應用成長。
預計到2025年,非黏性聚四氟乙烯(PTFE)產品將佔56.1%的市佔率。該細分市場之所以能保持其主導地位,是因為其應用範圍廣泛,包括電氣絕緣、化學加工、脫模、物料輸送、半導體製造以及高溫作業環境等。非黏性PTFE膠帶和薄膜廣泛應用於航太、電子和化學等產業,支撐著市場需求的穩定成長。由於無需黏合劑層,它們性能可靠,因此適用於各種專業工業流程。
預計到2025年,刨削聚四氟乙烯(PTFE)市場的銷售額將達到3.258億美元。該市場地位穩固,得益於刨削聚四氟乙烯材料在電子、電氣絕緣、航太、化學和工業設備等領域的廣泛應用。刨削聚四氟乙烯薄膜和膠帶具有厚度均勻、優異的電氣性能、高耐化學性、低摩擦係數以及在寬溫度範圍內可靠的性能。這些特性使其更適用於需要耐久性、柔軟性和長期運作穩定性的應用。
預計到2025年,北美聚四氟乙烯(PTFE)膠帶和薄膜市佔率將達到29.1%。隨著半導體生產和高科技電子產品製造的持續擴張,該地區的市場預計將繼續成長。對先進電絕緣材料日益成長的需求,以及在航太、國防、汽車、化學和醫療等終端應用產業的強大影響力,都推動了該地區市場的成長。此外,對具有優異介電性能、熱穩定性、耐腐蝕性和低摩擦特性的材料的需求不斷成長,也進一步促進了PTFE膠帶和薄膜在北美特殊應用領域的應用。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 半導體和先進電子製造的擴張
- 對高性能電絕緣材料的需求日益成長
- 化學加工中耐腐蝕材料的應用日益廣泛
- 來自航太和高性能運輸設備行業的需求不斷成長。
- 高頻通訊和先進電子系統的發展
- 產業潛在風險與挑戰
- PFAS基材料面臨的環境和監管壓力
- 高性能聚四氟乙烯材料的先進加工流程複雜且成本高昂
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估算與預測:依產品組成分類,2022-2035年
- 聚四氟乙烯黏合劑產品
- 不黏聚四氟乙烯產品
第6章 市場估價與預測:依製造流程分類,2022-2035年
- Skib 加工的聚四氟乙烯
- 糊狀擠出聚四氟乙烯
- 鑄造聚四氟乙烯
- 膨體聚四氟乙烯(ePTFE)
- 其他
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 天花板
- 電氣絕緣和電纜護套
- 化學防護
- 脫模劑/不沾劑
- 表面保護和減少磨損
- 過濾/通風
- 其他
第8章 市場估算與預測:依最終用途產業分類,2022-2035年
- 電氣和電子設備
- 化學處理
- 航太/國防
- 車
- 醫療和製藥
- 食品/飲料
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Nitto Denko Corporation
- Chukoh Chemical Industries, Ltd.
- WL Gore & Associates, Inc.
- Rogers Corporation(DeWAL Products Division)
- Saint-Gobain
- 該地區的主要公司
- 北美洲
- Taconic
- 歐洲
- AvenEx Coating Technologies(Lenzing Plastics GmbH & Co. KG)
- Guarniflon SpA
- Tesa SE
- 北美洲
- 小眾玩家/顛覆者
- DUNMORE Corporation
- PPI Adhesive Products Ltd.
- 3P Corporate
The Global PTFE Tapes and Films Market was valued at USD 916.8 million in 2025 and is estimated to grow at a CAGR of 5.4% to reach USD 1.6 billion in 2035.
The PTFE tapes and films industry is experiencing steady expansion due to rising demand from semiconductor manufacturing, advanced electronics, and high-performance industrial applications. Increasing requirements for reliable electrical insulation materials, chemically resistant solutions, and thermally stable components are supporting market growth across several industries. PTFE tapes and films are gaining importance due to their ability to perform under extreme temperatures, resist chemical exposure, and provide low-friction properties. The growing adoption of lightweight and durable materials in aerospace, transportation, and communication technologies is further strengthening demand. Additionally, the increasing requirement for low-loss dielectric materials in high-frequency electronic systems is creating new growth opportunities for PTFE-based products. The continuous advancement of semiconductor capabilities and domestic electronics manufacturing initiatives is also contributing to the rising consumption of PTFE tapes and films globally.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $916.8 Million |
| Forecast Value | $1.6 Billion |
| CAGR | 5.4% |
The expansion of semiconductor production and advanced electronic systems is creating strong demand for PTFE tapes and films. These materials provide excellent insulation performance along with thermal and chemical resistance, making them suitable for demanding manufacturing environments. Increasing use of PTFE products for specialized applications such as insulation, dielectric protection, masking, and surface protection within semiconductor and electronics manufacturing is supporting market development. The continued focus on strengthening domestic semiconductor production capabilities is also contributing to increased adoption of high-performance materials.
The non-adhesive PTFE products segment accounted for 56.1% share in 2025. The segment maintains its dominance due to its extensive application across electrical insulation, chemical processing, release applications, material handling, semiconductor manufacturing, and high-temperature operating conditions. The broad usability of non-adhesive PTFE tapes and films across industries such as aerospace, electronics, and chemical manufacturing has supported consistent demand growth. Their ability to deliver dependable performance without adhesive layers makes them suitable for various specialized industrial processes.
The skived PTFE segment generated USD 325.8 million in 2025. The segment's strong market position is supported by the widespread use of skived PTFE materials across electronics, electrical insulation, aerospace, chemical processing, and industrial equipment applications. Skived PTFE films and tapes provide consistent thickness, excellent electrical characteristics, strong chemical resistance, low friction, and reliable performance across a broad temperature range. These properties enhance their suitability for applications requiring durability, flexibility, and long-term operational stability.
North America PTFE Tapes and Films Market accounted for a 29.1% share in 2025. The regional market is expected to grow as semiconductor production and high-tech electronics manufacturing continue to expand. Increasing demand for advanced electrical insulation materials and the strong presence of end-use industries, including aerospace, defense, automotive, chemical processing, and healthcare, are contributing to regional growth. The rising need for materials with superior dielectric performance, thermal stability, corrosion resistance, and low-friction characteristics is further driving the adoption of PTFE tapes and films across specialized applications in North America.
Prominent players operating in the global PTFE tapes and films industry include 3P Corporate, Taconic, Nitto Denko Corporation, Saint-Gobain, Chukoh Chemical Industries, Ltd., Rogers Corporation (DeWAL Products Division), Tesa SE, Guarniflon S.p.A., DUNMORE Corporation, AvenEx Coating Technologies (Lenzing Plastics GmbH & Co. KG), W. L. Gore & Associates, Inc., and PPI Adhesive Products Ltd. Companies operating in the PTFE tapes and films market are focusing on product innovation, capacity expansion, strategic partnerships, and technology development to strengthen their market position. Manufacturers are investing in advanced production processes to improve PTFE product performance, durability, and application flexibility. Companies are also expanding their product portfolios to address growing demand from semiconductor, electronics, aerospace, and industrial sectors. Strengthening distribution networks and improving customer support capabilities are helping companies increase market reach. Several players are emphasizing research and development activities to create customized PTFE solutions with enhanced thermal stability, chemical resistance, and electrical performance.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Product configuration trends
- 2.2.2 Manufacturing process trends
- 2.2.3 Application trends
- 2.2.4 End-user industry trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Expansion of semiconductor and advanced electronics manufacturing
- 3.2.1.2 Growing demand for high-performance electrical insulation
- 3.2.1.3 Rising use of corrosion-resistant materials in chemical processing
- 3.2.1.4 Increasing demand from aerospace and high-performance transportation applications
- 3.2.1.5 Growth of high-frequency communication and advanced electronic systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Environmental and regulatory pressure on PFAS-based materials
- 3.2.2.2 High processing complexity and cost of high-performance PTFE materials
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Product Configuration, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Adhesive PTFE products
- 5.3 Non-adhesive PTFE products
Chapter 6 Market Estimates and Forecast, By Manufacturing Process, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Skived PTFE
- 6.3 Paste extruded PTFE
- 6.4 Cast PTFE
- 6.5 Expanded PTFE (ePTFE)
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Sealing
- 7.3 Electrical insulation & cable wrapping
- 7.4 Chemical protection
- 7.5 Release & non-stick
- 7.6 Surface protection & wear reduction
- 7.7 Filtration & venting
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By End-Use Industry, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Electrical & electronics
- 8.3 Chemical processing
- 8.4 Aerospace & defense
- 8.5 Automotive
- 8.6 Medical & pharmaceutical
- 8.7 Food & beverage
- 8.8 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Nitto Denko Corporation
- 10.1.2 Chukoh Chemical Industries, Ltd.
- 10.1.3 W. L. Gore & Associates, Inc.
- 10.1.4 Rogers Corporation (DeWAL Products Division)
- 10.1.5 Saint-Gobain
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Taconic
- 10.2.2 Europe
- 10.2.2.1 AvenEx Coating Technologies (Lenzing Plastics GmbH & Co. KG)
- 10.2.2.2 Guarniflon S.p.A.
- 10.2.2.3 Tesa SE
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 DUNMORE Corporation
- 10.3.2 PPI Adhesive Products Ltd.
- 10.3.3 3P Corporate

 聚四氟乙烯市場:全球市場預測,2026-2032年聚四氟乙烯(PTFE)薄膜市場:全球市場預測,2026-2032年膨體聚四氟乙烯市場:全球預測,2026-2032年
 全球聚四氟乙烯(PTFE)薄膜市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 發泡聚四氟乙烯市場規模、佔有率和趨勢分析報告:按形態、應用、最終用途、地區和細分市場預測(2026-2033 年)聚四氟乙烯(PTFE)薄膜和膠帶市場規模、佔有率和趨勢分析報告:按類型、應用、地區和細分市場分類(2026-2033 年)
 聚四氟乙烯(PTFE)市場:按應用、形態、終端用戶產業和地區分類
 聚四氟乙烯(PTFE)市場規模、佔有率、趨勢和預測:按形態、類型、應用、最終用途行業和地區分類,2026-2034年聚四氟乙烯顆粒市場:依等級、製程、包裝及應用分類-2026-2032年全球預測聚四氟乙烯內襯水熱合成反應器市場:按加熱方式、壓力類型、應用和最終用戶分類的全球預測,2026-2032年