


 |
市場調查報告書
商品編碼
2101981
匯流排市場機會、成長要素、產業趨勢分析及2026-2035年預測。Busbar Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

預計到 2025 年,全球匯流排市場價值將達到 225 億美元,年複合成長率為 4.7%,到 2035 年將達到 359 億美元。
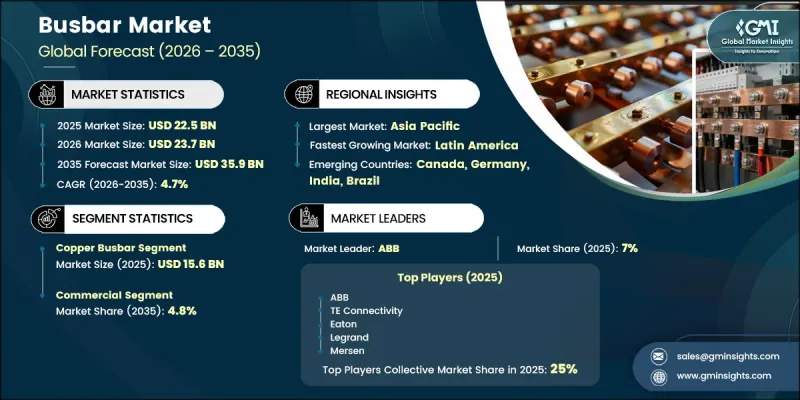
隨著住宅、商業和工業領域對高效可靠配電解決方案的需求不斷成長,匯流排市場持續擴張。電氣化項目投資的增加、電力基礎設施的現代化以及可再生能源系統的擴展,為市場成長創造了有利環境。開發中國家快速的城市化和日益活躍的建設活動,進一步推動了智慧建築和自動化基礎設施中先進匯流排系統的應用。製造商也致力於模組化產品設計和永續製造實踐,將可回收材料融入產品之中。交通運輸系統的電氣化程度不斷提高,以及在電動車、電力電子和可再生能源應用領域的投資不斷成長,進一步加速了產品需求。絕緣疊層匯流排憑藉其卓越的電氣性能、緊湊的設計和更高的運行效率,正被廣泛接受。與傳統佈線系統相比,匯流排具有更高的可靠性、更低的傳輸損耗和更最佳化的空間利用率。工業的持續擴張、人口的成長以及全球電力消耗量的不斷增加,進一步推動了對先進配電技術的需求,預計匯流排市場將實現長期穩定成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 225億美元 |
| 預計金額 | 359億美元 |
| 複合年成長率 | 4.7% |
銅匯流排市場預計到2025年將達到156億美元,主要得益於其卓越的導電性、優異的熱效率和長使用壽命。交通電氣化投資的增加,以及電動車和充電基礎設施的日益普及,正顯著提升對高性能銅匯流排的需求。銅的耐用性和優異的電氣性能使其成為許多工業和商業應用領域的理想選擇,尤其是在高效能電力傳輸至關重要的領域。
預計到2035年,商業應用領域將以4.8%的複合年成長率成長。都市化和商業基礎設施擴張推動電力消耗量增加,持續支撐市場成長。商業設施需要可靠且有效率的配電系統來滿足日益成長的電力負荷,對先進匯流排解決方案的需求仍然強勁。預計在整個預測期內,對現代化商業開發和節能建築基礎設施的投資增加將進一步推動該應用領域的擴張。
受配電基礎設施現代化和整體能源效率提升的持續推動,預計到2035年,美國匯流排市場將以3.5%的複合年成長率成長。為最大限度減少輸電損耗和提高配電效率而增加對先進電力系統的投資,正在加速匯流排技術的應用。持續的基礎設施升級和向更可靠的配電網路的過渡預計將繼續推動美國市場的擴張。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 原物料供應及採購分析
- 供應鏈韌性與風險因素
- 配電網路分析
- 中斷
- 監理情勢
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 成長潛力分析
- 波特的分析
- PESTLE分析
- 新機會和趨勢
- 數位化和物聯網整合
- 投資分析及未來展望
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧最佳化生產
- 預測性維護和故障檢測
- 價格趨勢分析
- 按材料分類(美元/噸)
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場規模及預測:依材料分類,2022-2035年
- 銅
- 電解韌性瀝青(ETP)
- 厭氧(OF)
- 鋁
第6章 市場規模及預測:依設計分類,2022-2035年
- 堅硬的
- 靈活的
- 層壓板
第7章 市場規模及預測:依產量範圍分類,2022-2035年
- 低的
- 中等的
- 高的
第8章 市場規模及預測:依應用領域分類,2022-2035年
- 住宅
- 商業
- 產業
第9章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
- 拉丁美洲
- 巴西
- 阿根廷
- 智利
第10章:公司簡介
- ABB
- Amphenol Corporation
- C&S Electric
- CHINT Group
- EAE Elektrik
- Eaton Corporation
- Furukawa Electric
- Legrand
- Littelfuse
- Megabarre Group
- Mersen
- Methode Power Solutions
- Mitsubishi Electric
- nVent
- Oriental Copper
- Pogliano Busbar
- Rogers Corporation
- Storm Power Components
- TE Connectivity
- Toshiba Corporation
- Wohner GmbH
The Global Busbar Market was valued at USD 22.5 billion in 2025 and is estimated to grow at a CAGR of 4.7% to reach USD 35.9 billion by 2035.
The Busbar Market continues to expand as demand for efficient and dependable power distribution solutions rises across residential, commercial, and industrial sectors. Increasing investments in electrification projects, modernization of power infrastructure, and the growing deployment of renewable energy systems are creating favorable conditions for market growth. Rapid urban development and expanding construction activities in developing economies are further strengthening the adoption of advanced busbar systems in smart buildings and automated infrastructure. Manufacturers are also focusing on modular product designs and sustainable manufacturing practices by incorporating recyclable materials into their offerings. Rising electrification across transportation systems, together with growing investments in electric mobility, power electronics, and renewable energy applications, continues to accelerate product demand. Insulated laminated busbars are gaining wider acceptance because they provide superior electrical performance, compact designs, and improved operational efficiency. Compared with conventional wiring systems, busbars offer enhanced reliability, lower transmission losses, and optimized space utilization. Continuous industrial expansion, population growth, and increasing global electricity consumption are further driving the need for advanced power distribution technologies, positioning the Busbar Market for stable long-term growth.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $22.5 Billion |
| Forecast Value | $35.9 Billion |
| CAGR | 4.7% |
The copper busbar market was valued at USD 15.6 billion in 2025 owing to its excellent electrical conductivity, outstanding thermal efficiency, and extended service life. Growing investments in transportation electrification, along with the expanding adoption of electric vehicles and charging infrastructure, are significantly increasing demand for high-performance copper busbars. The material's durability and superior electrical performance make it the preferred choice across a broad range of industrial and commercial applications where efficient power transmission remains essential.
The commercial application segment is projected to grow at a CAGR of 4.8% through 2035. Rising electricity consumption driven by accelerating urbanization and expanding commercial infrastructure continues to support market growth. As commercial facilities require dependable and efficient electrical distribution systems to support increasing power loads, the demand for advanced busbar solutions continues to strengthen. Growing investments in modern commercial developments and power-efficient building infrastructure are expected to further support the expansion of this application segment throughout the forecast period.
U.S. Busbar Market is anticipated to grow at a CAGR of 3.5% through 2035 supported by ongoing initiatives aimed at modernizing power distribution infrastructure and improving overall energy efficiency. Increasing investments in advanced electrical systems designed to minimize transmission losses and improve distribution efficiency are accelerating the adoption of busbar technologies. Continued infrastructure upgrades and the transition toward more reliable power distribution networks are expected to sustain market expansion across the country.
Key players operating in the Global Busbar Market include ABB, Amphenol Corporation, C&S Electric, CHINT Group, EAE Elektrik, Eaton Corporation, Furukawa Electric, Legrand, Littelfuse, Megabarre Group, Mersen, Methode Power Solutions, Mitsubishi Electric, nVent, Oriental Copper, Pogliano Busbar, Rogers Corporation, Storm Power Components, TE Connectivity, Toshiba Corporation, and Wohner GmbH. Companies operating in the Busbar Market are strengthening their competitive position by investing in product innovation, expanding manufacturing capabilities, and developing advanced power distribution solutions that improve efficiency and reliability. Manufacturers are focusing on lightweight, modular, and insulated busbar designs that support modern electrical infrastructure while reducing installation complexity. Strategic partnerships, capacity expansions, and geographic expansion initiatives are enabling companies to strengthen their global presence and serve a broader customer base. Businesses are also increasing investments in research and development to improve product durability, thermal performance, and electrical conductivity.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Business trends
- 2.1.2 Material trends
- 2.1.3 Design trends
- 2.1.4 Power range trends
- 2.1.5 Application trends
- 2.1.6 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material availability & sourcing analysis
- 3.1.2 Supply chain resilience & risk factors
- 3.1.3 Distribution network analysis
- 3.1.4 Disruptions
- 3.2 Regulatory landscape
- 3.3 Industry impact forces
- 3.3.1 Growth drivers
- 3.3.2 Industry pitfalls & challenges
- 3.4 Growth potential analysis
- 3.5 Porter's Analysis
- 3.5.1 Bargaining power of suppliers
- 3.5.2 Bargaining power of buyers
- 3.5.3 Threat of new entrants
- 3.5.4 Threat of substitutes
- 3.6 PESTEL Analysis
- 3.6.1 Political factors
- 3.6.2 Economic factors
- 3.6.3 Social factors
- 3.6.4 Technological factors
- 3.6.5 Environmental factors
- 3.6.6 Legal factors
- 3.7 Emerging opportunities & trends
- 3.8 Digitalization & IoT integration
- 3.9 Investment analysis & future prospects
- 3.10 Impact of AI & Generative AI on the market (Driven by Primary Research)
- 3.10.1 AI-driven production optimization
- 3.10.2 Predictive maintenance & fault detection
- 3.11 Price trend analysis (Driven by Primary Research)
- 3.11.1 By material, (USD/ton)
Chapter 4 Competitive Landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, 2025
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Middle East & Africa
- 4.2.1.5 Latin America
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Merger & acquisition
- 4.5.2 Partnership & collaboration
- 4.5.3 New product launched
- 4.5.4 Expansion plans & funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Size and Forecast, By Material, 2022 - 2035 (Kilo Ton, USD Million)
- 5.1 Key trends
- 5.2 Copper
- 5.2.1 Electrolytic Tough Pitch (ETP)
- 5.2.2 Oxygen Free (OF)
- 5.3 Aluminum
Chapter 6 Market Size and Forecast, By Design, 2022 - 2035 (Kilo Ton, USD Million)
- 6.1 Key trends
- 6.2 Solid
- 6.3 Flexible
- 6.4 Laminated
Chapter 7 Market Size and Forecast, By Power range, 2022 - 2035 (Kilo Ton, USD Million)
- 7.1 Key trends
- 7.2 Low
- 7.3 Medium
- 7.4 High
Chapter 8 Market Size and Forecast, By Application, 2022 - 2035 (Kilo Ton, USD Million)
- 8.1 Key trends
- 8.2 Residential
- 8.3 Commercial
- 8.4 Industrial
Chapter 9 Market Size and Forecast, By Region, 2022 - 2035 (Kilo Ton, USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.2.3 Mexico
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 France
- 9.3.3 UK
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Middle East & Africa
- 9.5.1 Saudi Arabia
- 9.5.2 UAE
- 9.5.3 South Africa
- 9.6 Latin America
- 9.6.1 Brazil
- 9.6.2 Argentina
- 9.6.3 Chile
Chapter 10 Company Profiles
- 10.1 ABB
- 10.2 Amphenol Corporation
- 10.3 C&S Electric
- 10.4 CHINT Group
- 10.5 EAE Elektrik
- 10.6 Eaton Corporation
- 10.7 Furukawa Electric
- 10.8 Legrand
- 10.9 Littelfuse
- 10.10 Megabarre Group
- 10.11 Mersen
- 10.12 Methode Power Solutions
- 10.13 Mitsubishi Electric
- 10.14 nVent
- 10.15 Oriental Copper
- 10.16 Pogliano Busbar
- 10.17 Rogers Corporation
- 10.18 Storm Power Components
- 10.19 TE Connectivity
- 10.20 Toshiba Corporation
- 10.21 Wohner GmbH

 匯流排市場分析:按額定電流、導體類型、最終用戶、產業和地區分類(2026-2034 年)
 疊層鋁匯流排市場報告:趨勢、預測與競爭分析(至2035年)
 匯流排市場:2026-2032年全球市場預測(依材質、絕緣類型、額定功率、製造流程和應用分類)
 匯流排市場分析及預測(至2035年):類型、產品類型、應用、材質、技術、最終用戶、組件、安裝類型、功能、解決方案
 2026年全球匯流排市場報告
 匯流排市場 - 全球產業規模、佔有率、趨勢、機會、預測:按導體類型、額定功率、最終用戶、地區和競爭格局分類,2021-2031年全球電鍍化學品市場(按技術、化學、應用和最終用途產業分類)預測(2026-2032年)通用箱型匯流排市場(依最終用戶、類型、材質和應用分類)-2026-2032年全球預測
 匯流排市場規模、佔有率和成長分析(按導體類型、額定功率、最終用戶和地區分類)-2026-2033年產業預測
 匯流排鍍層市場規模、佔有率及成長分析(依基材、金屬鍍層、應用及地區分類)-2026-2033年產業預測