


 |
市場調查報告書
商品編碼
2101923
2026 年至 2035 年裝盒機市場機會、成長要素、產業趨勢分析及預測。Cartoning Machinery Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球裝盒機市場預計到 2025 年將達到 53 億美元,年複合成長率為 5.1%,到 2035 年將達到 87 億美元。
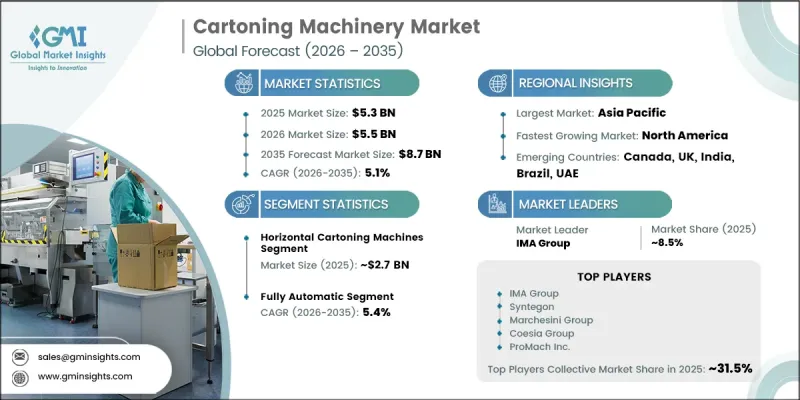
隨著各行各業的製造商不斷增加對包裝自動化的投資,以提高營運效率、產品品質和生產一致性,裝盒機市場持續擴張。減少勞動力依賴、消除包裝錯誤和提高生產效率的壓力日益增大,促使企業採用能夠處理大量生產的先進裝盒設備。自動化裝盒系統能夠完美滿足不斷變化的生產需求,提供更大的生產柔軟性,並可適應各種包裝規格。隨著企業將數位技術、智慧自動化、機器人、人工智慧和即時生產監控等技術融入包裝運營,智慧製造的持續發展進一步加速了市場成長。這些創新提高了設備性能,最佳化了維護計劃,並提升了整體生產效率。此外,日益嚴格的藥品包裝法規(涉及產品可追溯性、序列化和供應鏈透明度)也持續推動對先進裝盒機的需求,這些裝盒機能夠在滿足法規要求的同時,保持全球製造工廠的高速生產和包裝精度。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 53億美元 |
| 預測金額 | 87億美元 |
| 複合年成長率 | 5.1% |
預計到2025年,水平裝盒機市場規模將達27億美元,並在2026年至2035年間以5.1%的複合年成長率成長。水平裝盒機憑藉其高效處理複雜包裝操作並保持高速、高精度和一致性的能力,持續引領市場。它們能夠處理多種包裝配置,實現快速產品切換,即使在高產量生產環境下也能高效運作,因此在包裝要求嚴格的行業中得到廣泛應用。隨著對操作柔軟性和生產效率的日益重視,預計在預測期內,對水平裝盒機的需求將進一步增強。
預計到2025年,全自動裝盒機市佔率將達到59.4%,並在2035年之前以5.4%的複合年成長率成長。人事費用上升和持續的勞動力短缺正促使製造商投資於全自動包裝系統,以最大限度地減少人工操作,同時提高加工能力。對於需要高精度、高速度和符合法規要求的大規模製造業而言,這些機器正成為越來越有吸引力的選擇,能夠確保包裝品質的一致性,提高生產可靠性,並提升營運效率。預計對工廠自動化的持續投資將進一步加速全自動裝盒機的普及。
預計到2025年,美國裝盒機市場規模將達到10.54億美元。這一成長主要得益於對智慧製造技術的投資增加,這些技術透過自動化、連網設備和數位化生產管理來提高包裝效率。隨著各主要產業持續增加對製造自動化的資本投入,企業致力於提高生產力、降低營運成本和實現生產設施現代化,因此對先進裝盒機的需求持續成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 自動化程度的提高是由人事費用上升和技術純熟勞工的。
- 藥品序列化和追蹤溯源的全球合規要求
- 電子商務的擴張正在推動對高速二次包裝的需求。
- 永續發展法規正在加速從塑膠包裝到紙質包裝的轉變。
- 產業潛在風險與挑戰
- 關鍵部件供應鏈中斷
- 缺乏熟練的操作人員來安裝、檢驗和維護最先進的生產線。
- 機會
- 模組化和緊湊型紙盒設計便於中小企業採用。
- 透過 PaaS(打包即服務)和租賃模式降低資本投資門檻。
- 促進因素
- 成長潛力分析
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 監理情勢
- 標準和合規要求
- 區域監理框架
- 認證標準
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 價格分析
- 對過去價格趨勢的分析
- 按業務類型(高階/低階/大眾市場)分類的定價策略
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 波特的分析
- PESTLE分析
- 消費者購買行為分析
- 人口趨勢
- 影響購買決策的因素
- 消費者產品採納
- 首選分銷管道
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依機器類型分類,2022-2035年
- 水平裝盒機
- 立式裝盒機
- 環繞式紙盒
第6章 市場估算與預測:依自動化程度分類,2022-2035年
- 全自動
- 半自動
- 手動的
第7章 市場估計與預測:依產能分類,2022-2035年
- 低速(低於70 CPM)
- 中速(70-150 CPM)
- 高速(超過 150 CPM)
第8章 市場估價與預測:依紙箱/包裝材料分類,2022-2035年
- 紙板
- 紙板
- 其他材料(再生紙板、生物基複合材料)
第9章 市場估計與預測:依最終用途產業分類,2022-2035年
- 食品/飲料
- 藥品和醫療保健
- 個人護理化妝品
- 消費品/家居用品
- 其他(化學產品、農藥)
第10章 市場估價與預測:依通路分類,2022-2035年
- 直銷
- 間接銷售
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
第12章:公司簡介
- 世界公司
- IMA Group
- Syntegon Technology GmbH
- Coesia Group
- Marchesini Group
- Uhlmann Group
- 該地區的領先企業
- Romaco Group
- ProMach Inc.
- ACG Worldwide
- ADCO Manufacturing
- Kama GmbH
- 新興企業
- Pharmaworks
- Jacob White Packaging
- Econocorp Inc.
- Nuspark Inc.
- Cama Group
The Global Cartoning Machinery Market was valued at USD 5.3 billion in 2025 and estimated to grow at a CAGR of 5.1% to reach USD 8.7 billion by 2035.
The cartoning machinery market continues to expand as manufacturers across multiple industries increase investments in packaging automation to improve operational efficiency, product quality, and production consistency. Growing pressure to reduce labor dependency, eliminate packaging errors, and increase manufacturing productivity is encouraging businesses to adopt advanced cartoning equipment capable of supporting high-volume operations. Automated cartoning systems provide greater production flexibility while accommodating a broad range of packaging formats, making them well suited for evolving manufacturing requirements. The ongoing shift toward smart manufacturing is further accelerating market growth as companies integrate digital technologies, intelligent automation, robotics, artificial intelligence, and real-time production monitoring into packaging operations. These innovations improve equipment performance, optimize maintenance schedules, and increase overall production efficiency. In addition, stricter pharmaceutical packaging regulations related to product traceability, serialization, and supply chain transparency continue to strengthen demand for advanced cartoning machinery capable of supporting regulatory compliance while maintaining high-speed production and packaging accuracy across global manufacturing facilities.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.3 Billion |
| Forecast Value | $8.7 Billion |
| CAGR | 5.1% |
The horizontal cartoning machinery market generated USD 2.7 billion in 2025 and is expected to grow at a CAGR of 5.1% from 2026 to 2035. Horizontal cartoning machines continue to lead the market because they efficiently manage complex packaging operations while maintaining high levels of speed, precision, and consistency. Their ability to support multiple package configurations, accommodate rapid product changeovers, and operate efficiently within high-volume manufacturing environments continues to drive adoption across industries with demanding packaging requirements. Increasing emphasis on operational flexibility and production efficiency is expected to further strengthen demand for horizontal cartoning machinery throughout the forecast period.
The fully automatic cartoning machinery market accounted for 59.4% share in 2025 and is anticipated to grow at a CAGR of 5.4% through 2035. Rising labor costs and ongoing workforce shortages are encouraging manufacturers to invest in fully automated packaging systems that improve throughput while minimizing manual intervention. These machines deliver consistent packaging quality, enhanced production reliability, and greater operational efficiency, making them increasingly attractive for large-scale manufacturing operations that require precision, speed, and regulatory compliance. Continued investments in factory automation are expected to further accelerate adoption of fully automatic cartoning machinery.
U.S. Cartoning Machinery Market was valued at USD 1,054 million in 2025. Growth is being supported by increasing investments in smart manufacturing technologies that improve packaging efficiency through automation, connected equipment, and digital production management. Ongoing capital investment in manufacturing automation across major industries continues to strengthen demand for advanced cartoning machinery as companies focus on improving productivity, reducing operating costs, and modernizing production facilities.
Key companies operating in the global cartoning machinery market include IMA Group, Syntegon Technology GmbH, Coesia Group, Marchesini Group, Uhlmann Group, Romaco Group, ProMach Inc., ACG Worldwide, ADCO Manufacturing, Kama GmbH, Pharmaworks, Jacob White Packaging, Econocorp Inc., Nuspark Inc., and Cama Group. Companies operating in the cartoning machinery market are strengthening their market position by expanding automation capabilities, improving machine flexibility, and investing in advanced packaging technologies. Manufacturers continue to develop high-speed systems that support multiple packaging formats while reducing downtime and increasing production efficiency. Businesses are also integrating digital monitoring, intelligent controls, and predictive maintenance features to enhance equipment performance and minimize operational interruptions. Strategic investments in research and development enable companies to introduce innovative solutions that meet evolving industry requirements and regulatory standards.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Machine type
- 2.2.3 Automation level
- 2.2.4 Capacity
- 2.2.5 Carton/packaging material
- 2.2.6 End-use industry
- 2.2.7 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising automation adoption driven by labor cost inflation & skilled labor shortage
- 3.2.1.2 Pharmaceutical serialization & track-and-trace compliance mandates globally
- 3.2.1.3 E-commerce expansion driving demand for high-speed secondary packaging
- 3.2.1.4 Sustainability regulations accelerating shift from plastic to carton-based packaging
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Supply chain disruptions for critical components
- 3.2.2.2 Skilled operator shortage for installation, validation & maintenance of advanced lines
- 3.2.3 Opportunities
- 3.2.3.1 Modular & compact cartoner designs unlocking SME adoption
- 3.2.3.2 Packaging-as-a-service (PaaS) & leasing models reducing capex barriers
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Future market trends
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Regulatory landscape
- 3.6.1 Standards and compliance requirements
- 3.6.2 Regional regulatory frameworks
- 3.6.3 Certification standards
- 3.7 Trade data analysis (HS Code 8422.40)
- 3.7.1 Import/export volume & value trends
- 3.7.2 Key trade corridors & tariff impact
- 3.8 Pricing analysis
- 3.8.1 Historical price trend analysis (driven by primary research)
- 3.8.2 Pricing strategy by player type (premium / value / mass market)
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-driven disruption of existing business models
- 3.9.2 GenAI use cases & adoption roadmap by segment
- 3.9.3 Risks, limitations & regulatory considerations
- 3.10 Porter's analysis
- 3.11 PESTEL analysis
- 3.12 Consumer buying behavior analysis
- 3.12.1 Demographic trends
- 3.12.2 Factors affecting buying decisions
- 3.12.3 Consumer product adoption
- 3.12.4 Preferred distribution channel
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.1 By Region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Machine Type, 2022 - 2035, (USD Billion) (Million Units)
- 5.1 Key trends
- 5.2 Horizontal cartoning machines
- 5.3 Vertical cartoning machines
- 5.4 Wraparound cartoners
Chapter 6 Market Estimates & Forecast, By Automation Level, 2022 - 2035, (USD Billion) (Million Units)
- 6.1 Key trends
- 6.2 Fully automatic
- 6.3 Semi-automatic
- 6.4 Manual
Chapter 7 Market Estimates & Forecast, By Capacity, 2022 - 2035, (USD Billion) (Million Units)
- 7.1 Key trends
- 7.2 Low speed (Below 70 CPM)
- 7.3 Medium speed (70-150 CPM)
- 7.4 High speed (Above 150 CPM)
Chapter 8 Market Estimates & Forecast, By Carton/Packaging Material, 2022 - 2035, (USD Billion) (Million Units)
- 8.1 Key trends
- 8.2 Paperboard
- 8.3 Corrugated fiberboard
- 8.4 Others (recycled board, bio-based composites)
Chapter 9 Market Estimates & Forecast, By End-Use Industry, 2022 - 2035, (USD Billion) (Million Units)
- 9.1 Key trends
- 9.2 Food & beverage
- 9.3 Pharmaceuticals & healthcare
- 9.4 Personal care & cosmetics
- 9.5 Consumer goods & household products
- 9.6 Others (chemicals, agrochemicals)
Chapter 10 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035, (USD Billion) (Million Units)
- 10.1 Key trends
- 10.2 Direct sales
- 10.3 Indirect sales
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035, (USD Billion) (Million Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Australia
- 11.4.6 Indonesia
- 11.4.7 Malaysia
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 MEA
- 11.6.1 Saudi Arabia
- 11.6.2 UAE
- 11.6.3 South Africa
Chapter 12 Company Profiles
- 12.1 Global Players
- 12.1.1 IMA Group
- 12.1.2 Syntegon Technology GmbH
- 12.1.3 Coesia Group
- 12.1.4 Marchesini Group
- 12.1.5 Uhlmann Group
- 12.2 Regional Champions
- 12.2.1 Romaco Group
- 12.2.2 ProMach Inc.
- 12.2.3 ACG Worldwide
- 12.2.4 ADCO Manufacturing
- 12.2.5 Kama GmbH
- 12.3 Emerging Players
- 12.3.1 Pharmaworks
- 12.3.2 Jacob White Packaging
- 12.3.3 Econocorp Inc.
- 12.3.4 Nuspark Inc.
- 12.3.5 Cama Group

 全球立式搬運機市場規模、佔有率、趨勢及成長分析報告(2026-2034)全球臥式搬運機市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 立式裝盒機市場機會、成長促進因素、產業趨勢分析及2026-2035年預測。
 頂裝式墨水匣(TLC)市場規模、佔有率和成長分析:按機器類型、自動化程度、應用、最終用戶和地區分類-2026-2033年產業預測
 封箱機市場:2026-2032年全球市場預測(按自動化程度、材料、加工速度和產能、封箱機構、操作方法、紙箱類型、產業和分銷管道分類)臥式裝盒機市場商機、成長要素、產業趨勢分析及2026-2035年預測。搬運機市場:依型號、材料、自動化程度、操作方式、產業及通路分類-2026-2032年全球市場預測
 裝盒機市場規模、佔有率和成長分析:按機器類型、自動化程度、紙盒類型、產能、最終用途產業和地區分類-2026-2033年產業預測紙箱機械市場:按機器類型、自動化程度、運作模式和最終用途產業分類,全球預測,2026-2032年麵團分割和擀壓機市場:按產品類型、技術、麵團處理能力、終端用戶產業和分銷管道分類,全球預測,2026-2032年