


 |
市場調查報告書
商品編碼
2101884
脈衝電場消融市場機會、成長要素、產業趨勢分析及2026-2035年預測Pulsed Field Ablation Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球脈衝電場消融市場預計到 2025 年將價值 22 億美元,並將以 23.7% 的複合年成長率成長,到 2035 年達到 193 億美元。
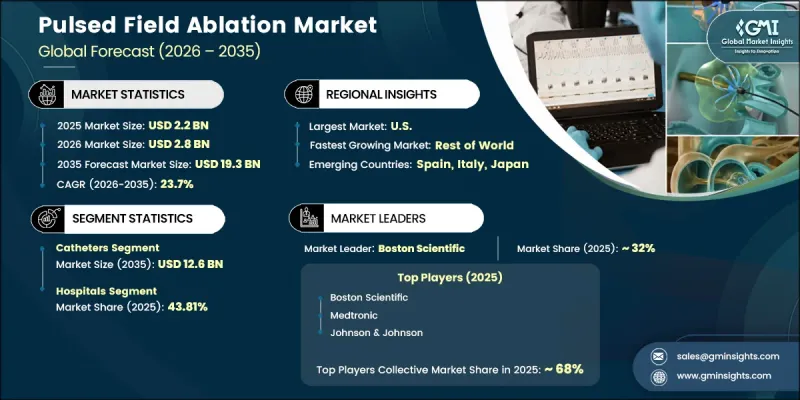
由於心律不整負擔日益加重、對微創治療的需求不斷成長,以及安全性更高、治療效果更佳的先進消融技術日益普及,該市場正經歷快速成長。脈衝電場消融(PFA) 是一種創新的心臟治療技術,它利用高壓電能透過不可逆電穿孔 (IRE) 選擇性地靶向異常心肌組織,無需依賴熱機制即可實現組織修復。這種非熱療法能夠實現精準治療,同時降低損傷周圍敏感解剖結構的風險。導管介入手術的日益普及、電生理學的進步、專業心臟醫療基礎設施的建設以及對更安全治療方法日益成長的需求,都推動了市場成長。心血管疾病(包括心房顫動和其他心律不整)的盛行率上升,進一步推動了先進消融解決方案的需求。隨著醫療專業人員不斷重視有效的心律不整管理策略,預計在預測期內,脈衝電場消融技術的應用將顯著加速。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 22億美元 |
| 預計金額 | 193億美元 |
| 複合年成長率 | 23.7% |
預計到2035年,導管市場規模將達到126億美元。這一強勁成長主要得益於經皮(PFA)手術在治療心律不整(尤其是心房顫動)的日益普及。作為向目標心肌組織輸送電能的主要器械,PFA導管在實現精準高效的消融方面發揮著至關重要的作用,並已成為整個治療系統中不可或缺的組成部分。
截至2025年,醫院將佔據43.81%的市場。醫院仍然是主要的終端用戶,這得益於其先進的電生理設施、專業的醫務人員以及開展複雜導管介入手術所需的完善基礎設施。醫院配備了先進的心臟定位技術、影像系統和經驗豐富的電生理團隊,在心房顫動和其他心律不整的治療中發揮主導作用。
預計到2025年,美國脈衝電場消融市場規模將達12億美元。美國是脈衝電場消融技術的主要市場,這主要歸因於其心臟心律不整(尤其是心房顫動)的高發生率。人口老化和相關健康風險因素的增加,導致這些疾病的發生率不斷上升,持續推動對先進心率管理解決方案的需求。醫療機構正擴大採用創新的消融技術,以應對日益沉重的心血管疾病負擔並改善患者預後。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 促進因素
- 心房顫動和心律不整的盛行率增加
- 對微創手術的需求日益成長
- PFA技術的進步
- 與熱消融相比,手術時間較短,且併發症較低。
- 產業潛在風險與挑戰
- 難以找到技術嫻熟的電生理學家
- PFA系統的高昂資本成本
- 市場機遇
- 拓展應用範圍,超越心房顫動
- 促進因素
- 成長潛力分析
- 監理情勢
- 技術展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 未來市場趨勢
- 波特的分析
- PESTLE分析
- 人工智慧和生成式人工智慧對市場的影響
- 價值鏈分析
- 管道分析
- 贖回方案
- 2024-2026年PFA技術的飛躍:心臟電生理學的新階段
- 安全性比較-脈衝場消融術、射頻消融術和冷凍消融術
第4章 競爭情勢
- 介紹
- 企業矩陣分析
- 企業市佔率分析
- 世界
- 美國
- 西班牙
- 義大利
- 日本
- 世界其他地區
- 競爭定位矩陣
- 主要市場公司的競爭分析
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 發電機
- 導管
- 周邊設備
第6章 市場估計與預測:依最終用途分類,2022-2035年
- 醫院
- 心臟導管檢查室
- 門診手術中心
- 其他最終用戶
第7章 市場估計與預測:依地區分類,2022-2035年
- 美國
- 西班牙
- 義大利
- 日本
- RoW
第8章:公司簡介
- Abbott
- Biotronik
- Boston Scientific
- Johnson & Johnson
- Kardium
- Medtronic
- Pulsecare Medical
- Sichuan Jinjiang Electronics
The Global Pulsed Field Ablation Market was valued at USD 2.2 billion in 2025 and is estimated to grow at a CAGR of 23.7% to reach USD 19.3 billion by 2035.
The market is experiencing rapid growth due to the increasing burden of cardiac arrhythmias, rising demand for minimally invasive treatment approaches, and growing adoption of advanced ablation technologies that offer improved safety and procedural outcomes. Pulsed field ablation (PFA) is an innovative cardiac treatment technology that uses high-voltage electrical energy to selectively target abnormal heart tissue through irreversible electroporation (IRE), allowing tissue modification without relying on heat-based mechanisms. This non-thermal approach supports precise treatment delivery while reducing the likelihood of injury to nearby sensitive anatomical structures. The increasing acceptance of catheter-based procedures, improvements in electrophysiology technologies, expanding availability of specialized cardiac care infrastructure, and rising focus on safer therapeutic options are contributing to market growth. The growing prevalence of cardiovascular conditions, including atrial fibrillation and other rhythm disorders, is further increasing the need for advanced ablation solutions. As healthcare providers continue prioritizing effective rhythm management strategies, the adoption of pulsed field ablation technologies is expected to accelerate significantly during the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.2 Billion |
| Forecast Value | $19.3 Billion |
| CAGR | 23.7% |
The catheter segment is expected to reach USD 12.6 billion by 2035. The segment's strong growth is supported by the increasing use of PFA procedures for managing cardiac arrhythmias, particularly atrial fibrillation. As the primary device responsible for delivering electrical energy to targeted cardiac tissue, PFA catheters play a vital role in achieving accurate and efficient ablation outcomes, making them a critical component of the overall treatment system.
The hospitals segment held 43.81% share in 2025. Hospitals remain the primary end users due to their access to advanced electrophysiology facilities, specialized medical professionals, and comprehensive infrastructure required for complex catheter-based procedures. The availability of advanced cardiac mapping technologies, imaging systems, and experienced electrophysiology teams enables hospitals to serve as major treatment centers for atrial fibrillation and other cardiac rhythm conditions.
U.S. Pulsed Field Ablation Market generated USD 1.2 billion in 2025. The United States represents a major market for pulsed field ablation technologies due to the high prevalence of cardiac arrhythmias, particularly atrial fibrillation. The increasing incidence of these conditions, supported by an aging population and the growing occurrence of related health risk factors, continues to create demand for advanced rhythm management solutions. Healthcare providers are increasingly adopting innovative ablation technologies to address the rising cardiovascular disease burden and improve patient outcomes.
Major companies operating in the global pulsed field ablation market include Medtronic, Abbott, Boston Scientific, Johnson & Johnson, Biotronik, Kardium, Pulsecare Medical, and Sichuan Jinjiang Electronics. Companies operating in the pulsed field ablation market are strengthening their competitive position by investing in advanced technology development, expanding product portfolios, and improving catheter-based ablation solutions. Market participants are focusing on enhancing treatment precision, procedural efficiency, device safety, and clinical performance through continuous research and innovation. Strategic collaborations with healthcare institutions, research organizations, and medical professionals are helping companies accelerate product development and expand clinical adoption. Businesses are also increasing investments in regulatory approvals, manufacturing capabilities, and global distribution networks to improve market accessibility. Companies are prioritizing clinical studies, technology improvements, and physician training programs to support wider acceptance of PFA procedures.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Product type trends
- 2.2.3 End use trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing prevalence of atrial fibrillation and cardiac arrhythmias
- 3.2.1.2 Growing demand for minimally invasive procedures
- 3.2.1.3 Advancements in PFA technology
- 3.2.1.4 Faster procedure times and reduced complications compared to thermal ablation
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Limited availability of skilled electrophysiologists
- 3.2.2.2 High capital cost of PFA systems
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion beyond atrial fibrillation into broader applications
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by primary research)
- 3.5 Technology landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Pricing analysis (Driven by primary research)
- 3.7 Future market trends
- 3.8 Porter's analysis
- 3.9 PESTEL analysis
- 3.10 Impact of AI and Generative AI on the market (Driven by primary research)
- 3.11 Value chain analysis (Driven by primary research)
- 3.12 Pipeline analysis
- 3.13 Reimbursement scenario
- 3.14 The 2024-2026 PFA breakout - reshaped cardiac EP landscape
- 3.15 Safety profile comparison - PFA vs. Radiofrequency Ablation vs. Cryoablation
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company matrix analysis
- 4.3 Company market share analysis (Driven by primary research)
- 4.3.1 Global
- 4.3.2 U.S.
- 4.3.3 Spain
- 4.3.4 Italy
- 4.3.5 Japan
- 4.3.6 Rest of the World
- 4.4 Competitive positioning matrix
- 4.5 Competitive analysis of major market players
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Generators
- 5.3 Catheters
- 5.4 Accessory devices
Chapter 6 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Hospitals
- 6.3 Cardiac catheterization labs
- 6.4 Ambulatory surgical centers
- 6.5 Other end users
Chapter 7 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 U.S.
- 7.3 Spain
- 7.4 Italy
- 7.5 Japan
- 7.6 RoW
Chapter 8 Company Profiles
- 8.1 Abbott
- 8.2 Biotronik
- 8.3 Boston Scientific
- 8.4 Johnson & Johnson
- 8.5 Kardium
- 8.6 Medtronic
- 8.7 Pulsecare Medical
- 8.8 Sichuan Jinjiang Electronics

 脈衝電場消融市場趨勢與預測:依治療領域、產品組件、應用領域、消融源、主要地區及主要公司分類(至2035年)
 脈衝電場消融市場規模、佔有率和成長分析:按產品類型、應用、最終用戶、手術類型、組件、技術和地區分類-2026-2033年產業預測
 2026-2034年全球電生理導管市場規模、佔有率、趨勢和成長分析報告
 電生理導管市場:依產品類型、能源來源、應用、最終用戶和技術分類-2026-2032年全球市場預測
 脈衝電場消融市場:按組件、模式、適應症、最終用戶和地區分類電生理消融導管市場:按技術、手術、產品類型和最終用戶分類 - 2026-2032年全球預測
 2026年全球電生理導管市場報告2026年全球電生理消融導管市場報告2026年脈衝場消融全球市場報告
 脈衝電場消融市場分析及預測(至2035年):依類型、產品類型、技術、應用、最終用戶、設備、製程、部署類型及功能分類