


 |
市場調查報告書
商品編碼
2101670
TAVR市場機會、成長促進因素、產業趨勢分析及2026-2035年預測。TAVR (Transcatheter Aortic Valve Replacement) Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球經導管主動脈瓣置換術術 (TAVR) 市場預計到 2025 年價值 66 億美元,預計到 2035 年將以 9.8% 的複合年成長率成長至 165 億美元。
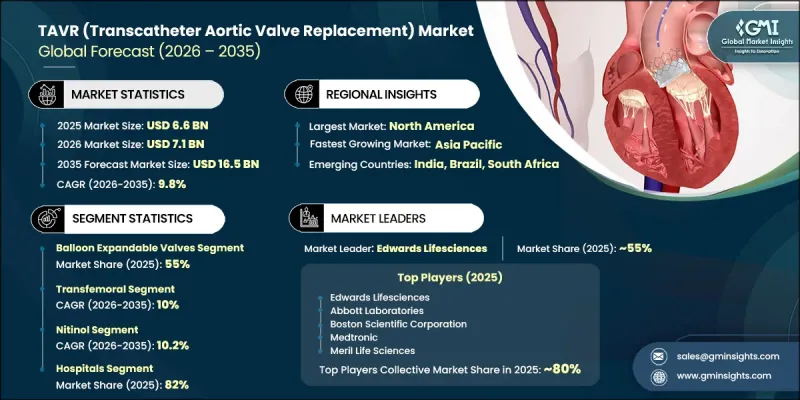
經導管主動脈瓣置換術術 (TAVR) 市場持續強勁成長,因為對於更廣泛的臨床風險類別的主動脈瓣狹窄患者而言,經導管瓣膜置換術已成為越來越受歡迎的治療選擇。越來越多的臨床證據表明,與傳統治療方法相比,TAVR 能帶來更佳的患者預後,這持續推動著醫師對該手術的接受度和廣泛應用。老年人口的快速成長、心血管疾病盛行率的上升以及已開發國家醫療報銷體系的不斷完善,進一步促進了 TAVR 市場的長期擴張。瓣膜技術的進步、精細的手術規劃以及影像技術的持續創新,提高了治療的精確度,並擴大了 TAVR 的臨床應用範圍。隨著全球平均壽命的延長,符合經導管瓣膜置換術的患者數量持續成長,對微創心臟介入治療的需求也日益旺盛。此外,北美、歐洲和亞太地區醫療保健系統對先進心血管護理的普及,推動了手術數量的增加,進一步鞏固了全球經導管主動脈瓣置換術術 (TAVR) 市場的良好長期成長前景。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 66億美元 |
| 預測金額 | 165億美元 |
| 複合年成長率 | 9.8% |
預計到2025年,球囊擴張型瓣膜市佔率將達到55%,並在2035年之前以9.6%的複合年成長率成長,成為領先的瓣膜植入方式。該細分市場之所以能保持其主導地位,是因為球囊擴張型系統能夠實現極其精準的瓣膜定位、可靠的植入性能以及穩定的血流動力學結果。其成熟的臨床表現、長期耐用性和可預測的手術特性持續推動著醫療專業人員的廣泛應用,顯著促進了全球市場手術量的成長。
預計到2025年,醫院將佔據82%的市場佔有率,並在2026年至2035年間以9.6%的複合年成長率成長。醫院仍然是經導管瓣膜置換術的主要終端用戶,因為該手術需要先進的心臟導管介入設備、多學科臨床團隊、專業的病患監測能力以及完善的急救醫療基礎設施。大型心血管治療中心繼續承擔大部分手術,這些中心擁有經驗豐富的臨床團隊和完善的心臟疾病診療體系,確保患者照護。
預計到2025年,北美經導管主動脈瓣置換術術(TAVR)市佔率將達到46%,並在2035年之前以9.6%的複合年成長率成長。美國仍然是該地區需求的最大驅動力,而加拿大也是一個重要的市場,這得益於其完善的醫療保健體系。全部區域持續受益於有利的報銷政策、不斷擴大的患者群體、醫生對該技術的接受度提高以及專業治療中心的建立,所有這些因素都促進了手術數量的增加和市場的持續擴張。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 成長促進因素
- 老年人口增加
- TAVR技術的進步
- 向微創手術過渡
- 改善報銷制度和保險覆蓋範圍。
- 產業潛在風險與挑戰
- TAVR設備高成本
- 併發症風險
- 機會
- 新一代設備現已上市,其耐用性已提升。
- 在亞太地區和其他新興市場擴張
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 2025年價格分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 投資情勢
- 贖回方案
- 未來市場趨勢
- TAVR設備歷代演變
- 人工智慧和生成式人工智慧對市場的影響
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業矩陣分析
- 企業市佔率分析
- 世界
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依部署類型分類,2022-2035年
- 球囊擴張型閥
- 自膨脹閥
- 機械膨脹閥
第6章 市場估計與預測:依移植手術類型分類,2022-2035年
- 經股骨
- 經尖端
- 經主動脈
第7章 市場估計與預測:依材料分類,2022-2035年
- 鎳鈦諾
- 不銹鋼
- 鈷鉻合金
- 其他材料
第8章 市場估算與預測:依最終用途分類,2022-2035年
- 醫院
- 門診手術中心
- 其他最終用戶
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- Abbott Laboratories
- Anteris Technologies
- Boston Scientific Corporation
- Bracco
- Edwards Lifesciences
- Foldax
- JenaValve Technology
- LEPU Medical
- Medtronic
- Meril Life Sciences
- MicroPort
- Peijia Medical
- Venus Medtech
The Global TAVR (Transcatheter Aortic Valve Replacement) Market was valued at USD 6.6 billion in 2025 and is estimated to grow at a CAGR of 9.8% to reach USD 16.5 billion by 2035.
The TAVR (Transcatheter Aortic Valve Replacement) market continues to experience strong growth as transcatheter valve procedures become an increasingly preferred treatment option for patients with aortic stenosis across a broader range of clinical risk categories. Expanding clinical evidence demonstrating favorable patient outcomes compared with conventional treatment approaches continues to support wider physician acceptance and procedural adoption. Long-term market expansion is further driven by the rapid growth of the aging population, increasing prevalence of cardiovascular disorders, and ongoing improvements in healthcare reimbursement across developed economies. Advances in valve technology, enhanced procedural planning, and continuous innovation in imaging capabilities are improving treatment precision while supporting broader clinical application. As life expectancy rises worldwide, the number of patients eligible for transcatheter valve replacement continues to increase, creating sustained demand for minimally invasive cardiac interventions. Healthcare systems across North America, Europe, and Asia Pacific are also expanding access to advanced cardiovascular care, encouraging higher procedural volumes and reinforcing favorable long-term growth prospects for the global TAVR (Transcatheter Aortic Valve Replacement) market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.6 Billion |
| Forecast Value | $16.5 Billion |
| CAGR | 9.8% |
The balloon-expandable valves segment accounted for 55% share in 2025 and is projected to grow at a CAGR of 9.6% through 2035, making them the leading deployment type. The segment maintains its dominant position because balloon-expandable systems provide highly accurate valve placement, reliable deployment performance, and consistent hemodynamic outcomes. Their established clinical performance, long-term durability, and predictable procedural characteristics continue to support widespread adoption among healthcare providers, contributing significantly to procedural growth across the global market.
The hospitals segment held 82% share in 2025 and is expected to grow at a CAGR of 9.6% during 2026-2035. Hospital settings remain the primary end users because transcatheter valve replacement procedures require advanced cardiac catheterization facilities, multidisciplinary clinical teams, specialized patient monitoring capabilities, and comprehensive emergency care infrastructure. High-volume cardiovascular treatment centers continue to perform the majority of procedures, supported by experienced clinical teams and well-established structural heart programs that ensure safe and effective patient care.
North America TAVR (Transcatheter Aortic Valve Replacement) Market accounted for 46% share in 2025 and is projected to grow at a CAGR of 9.6% through 2035. The United States remains the largest contributor to regional demand, while Canada also represents an important market supported by its established healthcare system. Market growth across the region continues to benefit from favorable reimbursement policies, expanding patient eligibility, growing physician adoption, and increasing availability of specialized treatment centers, all of which continue to support higher procedural volumes and sustained market expansion.
Major companies operating in the Global TAVR (Transcatheter Aortic Valve Replacement) market include Medtronic, Edwards Lifesciences, Abbott Laboratories, Boston Scientific Corporation, LEPU Medical, MicroPort, Venus Medtech, Meril Life Sciences, Peijia Medical, JenaValve Technology, Foldax, Bracco, and Anteris Technologies. Companies operating in the TAVR (Transcatheter Aortic Valve Replacement) market are strengthening their competitive position by investing heavily in research and development to improve valve performance, procedural safety, and long-term clinical outcomes. Manufacturers continue to expand product portfolios through technological innovation while focusing on minimally invasive treatment solutions that improve physician confidence and patient recovery. Strategic collaborations with healthcare providers, clinical research organizations, and academic institutions are supporting product development and expanding clinical adoption.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Market definitions
- 1.2 Research approach
- 1.3 Quality commitments
- 1.3.1 GMI AI policy & data integrity commitment
- 1.3.1.1 Source consistency protocol
- 1.3.1 GMI AI policy & data integrity commitment
- 1.4 Research trail & confidence scoring
- 1.4.1 Research trail components
- 1.4.2 Scoring components
- 1.5 Data collection
- 1.5.1 Partial list of primary sources
- 1.6 Data mining sources
- 1.6.1 Paid sources
- 1.6.1.1 Sources, by region
- 1.6.1 Paid sources
- 1.7 Base estimates and calculations
- 1.7.1 Base year calculation
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Deployment type trends
- 2.2.3 Implantation procedures trends
- 2.2.4 Material trends
- 2.2.5 End use trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing Elderly Population
- 3.2.1.2 Advancements in TAVR Technology
- 3.2.1.3 Shift Toward Minimally Invasive Procedures
- 3.2.1.4 Improved Reimbursement and Insurance Coverage
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Cost of TAVR Devices
- 3.2.2.2 Risk of Complications
- 3.2.3 Opportunities
- 3.2.3.1 Next generation device launches with extended durability
- 3.2.3.2 Expansion in Asia Pacific and other emerging markets
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.5 Pricing analysis, 2025
- 3.6 Technology and innovation landscape (Driven by Primary Research)
- 3.6.1 Current technological trends
- 3.6.2 Emerging technologies
- 3.7 Investment landscape
- 3.8 Reimbursement scenario
- 3.9 Future market trends (Driven by Primary Research)
- 3.10 Evolution of TAVR devices by generation
- 3.11 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.12 Porter's analysis
- 3.13 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company matrix analysis
- 4.3 Company market share analysis (Driven by Primary Research)
- 4.3.1 Global
- 4.3.2 North America
- 4.3.3 Europe
- 4.3.4 Asia Pacific
- 4.3.5 LAMEA
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Deployment Type, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Balloon-expandable valves
- 5.3 Self-expanding valves
- 5.4 Mechanically expanded valves
Chapter 6 Market Estimates and Forecast, By Implantation Procedures, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Transfemoral
- 6.3 Transapical
- 6.4 Transaortic
Chapter 7 Market Estimates and Forecast, By Material, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Nitinol
- 7.3 Stainless steel
- 7.4 Cobalt chromium
- 7.5 Other materials
Chapter 8 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 Hospitals
- 8.3 Ambulatory Surgical Centers
- 8.4 Other end users
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Netherlands
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 Japan
- 9.4.3 India
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Abbott Laboratories
- 10.2 Anteris Technologies
- 10.3 Boston Scientific Corporation
- 10.4 Bracco
- 10.5 Edwards Lifesciences
- 10.6 Foldax
- 10.7 JenaValve Technology
- 10.8 LEPU Medical
- 10.9 Medtronic
- 10.10 Meril Life Sciences
- 10.11 MicroPort
- 10.12 Peijia Medical
- 10.13 Venus Medtech

 經導管三尖瓣置換系統市場:全球市場預測,2026-2032年經導管主動脈瓣置換系統市場:全球市場預測,2026-2032年
 經導管心臟瓣膜市場:依產品類型、輸送系統、最終用戶和地區分類
 經導管心臟瓣膜全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 經導管心臟瓣膜置換術市場規模、佔有率和成長分析(按產品、手術方法、最終用途、應用和地區分類)-2026-2033年產業預測
 經導管心臟瓣膜市場規模、佔有率和趨勢分析報告:按應用、技術、地區和細分市場預測(2025-2033 年)
 經導管心臟瓣膜置換術和修復:全球市場佔有率和排名、總收入和需求預測(2025-2031 年)
 經導管心臟瓣膜置換術的全球市場:洞察,競爭情形,市場預測:2030年
 經導管心臟瓣膜的開發平台 - 開發階段,市場區隔,地區和國家,法規途徑,主要企業(2024年版)