


 |
市場調查報告書
商品編碼
2101622
熱電聯產設備市場機會、成長要素、產業趨勢分析及2026-2035年預測CHP Equipment Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球化學液壓包裝 (CHP) 設備市場預計到 2025 年將達到 116 億美元,年複合成長率為 6.5%,到 2035 年將達到 221 億美元。
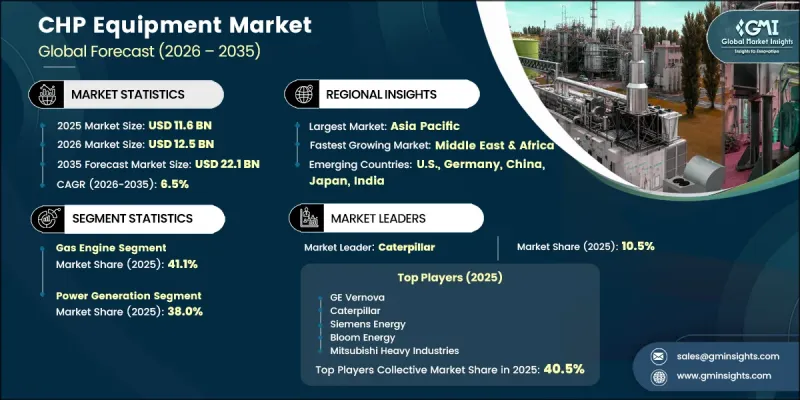
隨著各行業擴大採用能夠利用單一燃料同時生產電力和可用熱能的現場三聯產系統,熱電聯產 (CHP) 安裝市場持續成長。與傳統發電方式相比,這些系統具有更高的燃料利用效率,使其成為尋求降低能源成本和提高營運效率的企業的理想選擇。對能源安全、脫碳努力和彈性電力基礎設施的日益關注,正在推動工業、商業和公共設施對整合能源系統的投資。市場也逐步轉向旨在適應多種燃料選擇、具備數位監控功能和麵向未來的能源解決方案的先進平台。製造商正在投資於能夠提高系統柔軟性、運作可靠性和長期永續性的技術,同時滿足不斷變化的能源需求。對分散式能源的需求不斷成長、能源基礎設施的現代化以及持續的技術創新,為市場擴張創造了有利條件。預計這些因素將在整個預測期內支持技術、容量、應用、燃料類型和安裝類型等各個細分市場的持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 116億美元 |
| 預計金額 | 221億美元 |
| 複合年成長率 | 6.5% |
預計到2025年,燃氣引擎系統將佔據41.1%的市場佔有率,並在2035年之前以6.5%的複合年成長率成長。該細分市場之所以能保持主導地位,是因為燃氣引擎技術在廣泛的功率範圍內具有多功能性和擴充性。這些系統適用於各種商業和工業應用,因為它們不僅運作效率高,還能適應多種燃料來源。持續的技術創新、對靈活能源解決方案日益成長的需求以及對燃料適應性的日益重視,預計將進一步鞏固該細分市場的長期成長。
預計到2025年,發電領域將佔38%的市場佔有率,並在2026年至2035年間以6.6%的複合年成長率成長。需求成長主要由熱電聯產(CHP)系統驅動,該系統使企業能夠同時利用回收的熱能進行發電,從而提高整體能源效率並減少對外部能源的依賴。分散式能源基礎設施投資的增加、對可靠能源供應日益成長的重視以及對最佳化能源消耗的日益關注,都將繼續推動這一應用領域的整體擴張。
預計到2025年,北美熱電聯產(CHP)設備市佔率將達到22.9%,並在2035年之前維持5.9%的複合年成長率。該地區持續受惠於節能基礎設施投資的增加、工業設施的現代化改造以及對容錯型現場發電系統日益成長的需求。分散式能源技術的日益普及、有利於提高能源效率的政策支持以及老舊電力設施的持續更新換代,都推動了市場的持續成長。隨著降低營運成本、提高能源可靠性以及支持長期永續性目標的日益重視,預計該地區的需求將在預測期內進一步增強。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 原物料供應及採購分析
- 生產能力評估
- 供應鏈韌性與風險因素
- 配電網路分析
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 監理情勢
- 成長潛力分析
- 波特的分析
- PESTLE分析
- 成本結構分析:熱電聯產設備
- 熱電聯產技術整體的新商機
- 數位轉型和智慧熱電聯產營運
- 關鍵終端使用者領域尚未開發的成長潛力
- 投資趨勢與長期市場展望
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧最佳化生產
- 預測性維護和故障檢測
第4章 競爭情勢
- 介紹
- 企業市佔率分析:按地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場規模及預測:依技術分類,2022-2035年
- 燃氣引擎
- 燃氣渦輪機
- 蒸氣渦輪
- 微型渦輪機
- 燃料電池
- 其他
第6章 市場規模與預測:依燃料類型分類,2022-2035年
- 天然氣
- 沼氣
- 生質能
- 煤炭
- 氫
- 其他
第7章 市場規模及預測:依產能分類,2022-2035年
- 50 kW
- >50 kW~500 kW
- >500 kW~1 MW
- >1 MW~10 MW
- >10 MW~50 MW
- >50 MW
第8章 市場規模及預測:依應用領域分類,2022-2035年
- 發電
- 製程加熱
- 區域供熱
- 三聯供
第9章 市場規模及預測:依安裝類型分類,2022-2035年
- 新的
- 改裝
第10章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 丹麥
- 瑞典
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 印尼
- 泰國
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
- 埃及
- 土耳其
- 拉丁美洲
- 巴西
- 阿根廷
- 智利
第11章:公司簡介
- AB HOLDING SPA
- Bloom Energy
- Capstone Green Energy Corporation
- Caterpillar
- Clarke Energy
- Cummins
- Doosan Fuel Cell
- EC POWER
- Everllence
- FuelCell Energy
- GE Vernova
- INNIO
- Kawasaki Heavy Industries
- Mitsubishi Heavy Industries
- Rolls-Royce
- Siemens Energy
- Solar Turbines
- TEDOM
- Wartsila
- Yanmar Holdings
The Global CHP Equipment Market was valued at USD 11.6 billion in 2025 and is estimated to grow at a CAGR of 6.5% to reach USD 22.1 billion by 2035.
The CHP equipment market continues to gain momentum as industries increasingly adopt on-site cogeneration systems capable of producing electricity and usable thermal energy from a single fuel source. These systems offer significantly higher fuel utilization efficiency than conventional power generation methods, making them an attractive solution for organizations seeking to lower energy costs and improve operational efficiency. Rising emphasis on energy security, decarbonization initiatives, and resilient power infrastructure is encouraging greater investment in integrated energy systems across industrial, commercial, and institutional facilities. The market is also experiencing a gradual shift toward advanced platforms designed to support multiple fuel options, digital monitoring capabilities, and future-ready energy solutions. Manufacturers are investing in technologies that improve system flexibility, operational reliability, and long-term sustainability while addressing changing energy requirements. Growing demand for distributed energy resources, increasing modernization of energy infrastructure, and continuous technological advancements are creating favorable conditions for market expansion. These factors are expected to support sustained growth across technology, capacity, application, fuel type, and installation segments throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $11.6 Billion |
| Forecast Value | $22.1 Billion |
| CAGR | 6.5% |
The gas engine systems accounted for 41.1% share in 2025 and is anticipated to grow at a CAGR of 6.5% through 2035. The segment maintains its leading position due to the versatility and scalability of gas engine technology across a broad range of power capacities. These systems support a variety of fuel sources while providing high operational efficiency, making them suitable for diverse commercial and industrial applications. Continued technological improvements, increasing demand for flexible energy solutions, and greater focus on fuel adaptability are expected to strengthen the long-term growth of this segment.
The power generation segment held 38% share in 2025 and is projected to grow at a CAGR of 6.6% during 2026-2035. Demand is driven by the ability of combined heat and power systems to generate electricity while simultaneously utilizing recovered thermal energy, enabling organizations to improve overall energy efficiency and reduce dependence on external power supplies. Increasing investments in distributed energy infrastructure, greater emphasis on reliable energy availability, and growing interest in optimizing energy consumption continue to support expansion across this application segment.
North America CHP Equipment Market held 22.9% share in 2025 and is forecast to register a CAGR of 5.9% through 2035. The region continues to benefit from increasing investments in energy-efficient infrastructure, modernization of industrial facilities, and growing demand for resilient on-site power generation systems. Expanding adoption of distributed energy technologies, favorable policy support for energy efficiency, and ongoing replacement of aging power equipment are contributing to sustained market growth. Rising focus on reducing operational costs, improving energy reliability, and supporting long-term sustainability objectives is expected to further strengthen regional demand over the forecast period.
Major companies operating in the global CHP equipment market include AB Holding SPA, Bloom Energy, Capstone Green Energy Corporation, Caterpillar, Clarke Energy, Cummins, Doosan Fuel Cell, EC POWER, Everilience, FuelCell Energy, GE Vernova, INNIO, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Rolls-Royce, Siemens Energy, Solar Turbines, TEDOM, Wartsila, and Yanmar Holdings. Companies operating in the CHP equipment market are strengthening their competitive position through continuous product innovation, technology advancement, and expansion of integrated energy solutions. Manufacturers are investing in research and development to improve fuel flexibility, increase system efficiency, and enhance digital monitoring capabilities. Businesses are also expanding production capacity, strengthening distribution networks, and broadening their service portfolios to support long-term customer requirements. Strategic partnerships, technology collaborations, and geographic expansion remain important approaches for increasing market penetration and addressing growing demand across industrial and commercial sectors.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Business trends
- 2.1.2 Technology trends
- 2.1.3 Fuel trends
- 2.1.4 Capacity trends
- 2.1.5 Application trends
- 2.1.6 Installation trends
- 2.1.7 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material availability & sourcing analysis
- 3.1.2 Manufacturing capacity assessment
- 3.1.3 Supply chain resilience & risk factors
- 3.1.4 Distribution network analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls & challenges
- 3.3 Regulatory landscape
- 3.4 Growth potential analysis
- 3.5 Porter's analysis
- 3.5.1 Bargaining power of suppliers
- 3.5.2 Bargaining power of buyers
- 3.5.3 Threat of new entrants
- 3.5.4 Threat of substitutes
- 3.6 PESTEL analysis
- 3.6.1 Political factors
- 3.6.2 Economic factors
- 3.6.3 Social factors
- 3.6.4 Technological factors
- 3.6.5 Legal factors
- 3.6.6 Environmental factors
- 3.7 Cost structure analysis of CHP equipment
- 3.8 Emerging opportunities across CHP technologies
- 3.9 Digital transformation & intelligent CHP operations
- 3.10 Untapped growth potential across key end use areas
- 3.11 Investment trends & long-term market outlook
- 3.12 Impact of AI & Generative AI on the market (Driven by Primary Research)
- 3.12.1 AI-Driven production optimization (Driven by Primary Research)
- 3.12.2 Predictive maintenance & fault detection (Driven by Primary Research)
Chapter 4 Competitive Landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East & Africa
- 4.2.5 Latin America
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans & funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Size and Forecast, By Technology, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Gas engine
- 5.3 Gas turbine
- 5.4 Steam turbine
- 5.5 Microturbine
- 5.6 Fuel cell
- 5.7 Others
Chapter 6 Market Size and Forecast, By Fuel, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Natural gas
- 6.3 Biogas
- 6.4 Biomass
- 6.5 Coal
- 6.6 Hydrogen
- 6.7 Others
Chapter 7 Market Size and Forecast, By Capacity, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 50 kW
- 7.3 > 50 kW - 500 kW
- 7.4 > 500 kW - 1 MW
- 7.5 > 1 MW - 10 MW
- 7.6 > 10 MW - 50 MW
- 7.7 > 50 MW
Chapter 8 Market Size and Forecast, By Application, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Power generation
- 8.3 Process heating
- 8.4 District heating
- 8.5 Trigeneration
Chapter 9 Market Size and Forecast, By Installation, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 New
- 9.3 Retrofit
Chapter 10 Market Size and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.2.3 Mexico
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Netherlands
- 10.3.7 Denmark
- 10.3.8 Sweden
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 Japan
- 10.4.3 India
- 10.4.4 South Korea
- 10.4.5 Australia
- 10.4.6 Indonesia
- 10.4.7 Thailand
- 10.5 Middle East & Africa
- 10.5.1 Saudi Arabia
- 10.5.2 UAE
- 10.5.3 South Africa
- 10.5.4 Egypt
- 10.5.5 Turkey
- 10.6 Latin America
- 10.6.1 Brazil
- 10.6.2 Argentina
- 10.6.3 Chile
Chapter 11 Company Profiles
- 11.1 AB HOLDING SPA
- 11.2 Bloom Energy
- 11.3 Capstone Green Energy Corporation
- 11.4 Caterpillar
- 11.5 Clarke Energy
- 11.6 Cummins
- 11.7 Doosan Fuel Cell
- 11.8 EC POWER
- 11.9 Everllence
- 11.10 FuelCell Energy
- 11.11 GE Vernova
- 11.12 INNIO
- 11.13 Kawasaki Heavy Industries
- 11.14 Mitsubishi Heavy Industries
- 11.15 Rolls-Royce
- 11.16 Siemens Energy
- 11.17 Solar Turbines
- 11.18 TEDOM
- 11.19 Wartsila
- 11.20 Yanmar Holdings

 全球熱電聯產設備市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 汽電共生設備市場:依技術、燃料類型、容量、安裝類型、所有權類型和最終用途分類-全球預測,2026-2032年
 汽電共生設備市場-全球產業規模、佔有率、趨勢、機會與預測:按技術、燃料類型、應用、地區和競爭格局分類,2021-2031年
 全球汽電共生電廠市場預測至2034年-按燃料類型、組件、容量、技術、應用、最終用戶和地區分類的分析
 汽電共生設備市場規模、佔有率、趨勢和預測:按燃料、容量、技術、應用和地區分類,2026-2034年
 2026年全球汽電共生設備市場報告
 汽電共生設備市場規模、佔有率和成長分析(按類型、燃料類型、自用範圍、終端用戶產業和地區分類)-2026-2033年產業預測
 熱電聯產設備市場:依燃料、技術、容量、應用、國家及地區分類-全球產業分析、市場規模、市場佔有率及2025-2032年預測