


 |
市場調查報告書
商品編碼
2101618
2026 年至 2035 年水雷戰對抗系統市場的商業機會、成長要素、產業趨勢分析與預測。Mine Countermeasure (MCM) Systems Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球水雷戰對抗系統市場預計到 2025 年將達到 24 億美元,年複合成長率為 5.7%,到 2035 年將達到 43 億美元。
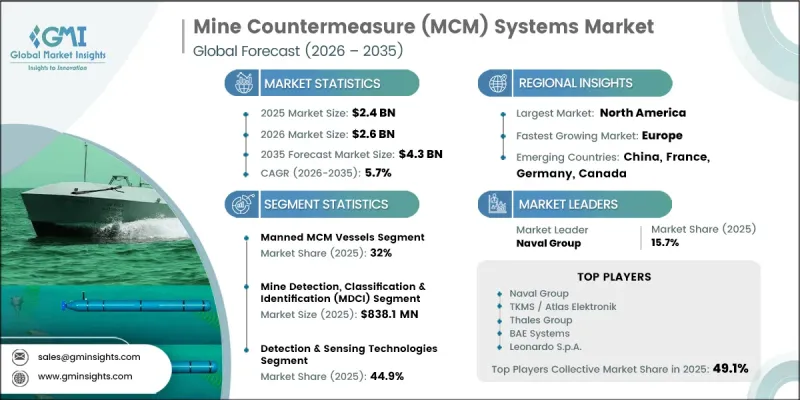
隨著各國海軍日益重視提升應對水下水雷威脅的能力,並應對日益嚴格的海上安全要求,水雷戰對抗系統市場正在不斷擴張。保護戰略水道、海上貿易航線、近海設施和關鍵水下基礎設施的重要性日益凸顯,促使各國政府加大對先進水雷戰解決方案的投資。持續進行的海軍艦隊現代化項目、自主技術的日益普及以及水下探測和響應系統的進步,都為市場發展帶來了積極影響。向無人平台的轉變正在改變傳統的水雷作業方式,提升任務安全性、作戰效率和威脅偵測能力。先進的感測技術、基於人工智慧(AI)的分析以及新一代聲吶系統,能夠更精準地識別和清除水下危險。隨著海上環境日益複雜,國防機構正優先考慮靈活且技術先進的解決方案,以提高作戰準備水準。對可靠的水雷探測、分類和處理能力的持續需求,預計將為市場參與企業創造持續的商機。對自主系統、海軍現代化舉措和海上防禦基礎設施的投資增加,預計將支持全球反水雷措施(MCM)系統市場的持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 24億美元 |
| 預計金額 | 43億美元 |
| 複合年成長率 | 5.7% |
受各國為應對不斷變化的水下安全挑戰而加大海軍現代化力度的推動,水雷戰對抗系統市場正經歷強勁成長。世界各國政府都在投資先進的海上防禦技術,例如自主水面平台、水下航行器和遙控系統,以提高作戰效率,同時減少人員在執行高風險任務時所面臨的危險。對關鍵海上通道、港口、近海資產和水下設施安全保障的日益重視,進一步擴大了對先進水雷戰能力的需求。這些趨勢正促使國防機構加速採用更有效率、技術主導的反水雷措施方案。
預計2025年,載人反水雷措施(MCM)市佔率將達到32%。該細分市場之所以能保持主導地位,是因為它能夠滿足多種任務需求,包括水雷搜索、水雷對抗、指揮控制以及爆炸物處理。載人掃雷艦配備了先進的聲吶系統、水雷處理技術和綜合作戰管理能力,在複雜的水雷戰行動中繼續發揮至關重要的作用。其作戰柔軟性和與其他防禦平台的整合能力,使其成為全球海軍反水雷措施計畫的關鍵組成部分。
預計到2025年,水雷探測、分類和識別(MDCI)市場規模將達到8.381億美元。該領域在水雷清除作業開展前識別水下水雷威脅方面發揮著至關重要的作用。先進的探測技術、不斷提升的聲吶性能、自主水下航行器以及人工智慧(AI)影像處理系統的日益普及,正在推動該領域的成長。隨著這些解決方案不斷提高探測精度、減少誤報並加快威脅評估速度,MDCI能力正成為現代海軍水雷戰戰略的重要組成部分。
北美水雷戰對抗系統市場正經歷顯著成長,這主要得益於海軍現代化投資的增加、自主水雷對抗技術的日益普及以及對關鍵海上資產保護力度的加強。包括美國國防部和美國海軍在內的國防機構不斷增加的支出,正在支持先進水雷對抗解決方案的研發和部署。此外,自主水下航行器、無人水面載具、先進聲吶技術和水雷清除系統的日益融合,也進一步鞏固了該地區市場。預計這些投資將提升海上安全能力,並推動北美市場持續成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 海軍現代化計畫增加,重點發展先進的水雷戰能力。
- 擴大自主式和無人式排雷平台的應用。
- 加強對關鍵海上基礎設施和戰略航道的保護。
- 水下感測、人工智慧目標辨識和聲吶技術的進步
- 多邊海軍演習和海上安全合作增加
- 產業潛在風險與挑戰
- 先進MCM系統的高採購成本與生命週期成本
- 複雜的水下工作環境和不斷演變的地雷威脅。
- 市場機遇
- 人工智慧驅動的自主掃雷與水下機器人技術進步
- 增加對關鍵海上基礎設施和戰略水道保護的投資。
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估計與預測:依平台類型分類,2022-2035年
- 自主水下航行器(AUV)
- 遙控潛水器(ROV)
- 無人水面載具(USV)
- 機載水雷對抗系統
- 載人反水雷艦
第6章 市場估計與預測:依營運類型分類,2022-2035年
- 地雷探測、分類與識別(MDCI)
- 掃雷(衝擊式和機械式)
- 地雷處置和中和
- 航行安全和航線勘測
第7章 市場估計與預測:依技術分類,2022-2035年
- 檢測和感測技術
- 地雷中和與處置系統
- 任務管理、指揮控制與自主系統
第8章 市場估算與預測:依最終用戶分類,2022-2035年
- 海軍(遠洋和近海作戰艦艇)
- 海岸防衛隊和港口安全部隊
- 特種作戰海上部隊
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 法國
- 英國
- 德國
- 挪威
- 義大利
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 智利
- 墨西哥
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Naval Group
- TKMS/Atlas Elektronik
- Thales Group
- BAE Systems
- Leonardo SpA
- 該地區的主要公司
- 北美洲
- Northrop Grumman
- Lockheed Martin
- L3Harris Technologies
- RTX Corporation
- 亞太地區
- ST Engineering
- IAI(Israel Aerospace Industries)
- Elbit Systems
- 歐洲
- Exail Holding
- Kongsberg Defence & Aerospace
- Saab AB
- 北美洲
- 小眾玩家/顛覆者
- Kraken Robotics
- Saab Seaeye
- General Dynamics
- HII(Huntington Ingalls Industries-Mission Technologies)
- Textron Systems
The Global Mine Countermeasure (MCM) Systems Market was valued at USD 2.4 billion in 2025 and is estimated to grow at a CAGR of 5.7% to reach USD 4.3 billion in 2035.
The Mine Countermeasure (MCM) Systems Market is expanding as maritime security requirements continue to rise and naval forces focus on strengthening capabilities against underwater mine threats. Increasing concerns regarding the protection of strategic waterways, maritime trade routes, offshore facilities, and critical underwater infrastructure are encouraging governments to invest in advanced mine warfare solutions. The market is benefiting from ongoing naval fleet modernization programs, rising adoption of autonomous technologies, and advancements in underwater detection and response systems. The transition toward unmanned platforms is reshaping traditional mine countermeasure operations by improving mission safety, operational efficiency, and threat detection capabilities. Advanced sensing technologies, artificial intelligence-based analysis, and next-generation sonar systems are supporting more accurate identification and neutralization of underwater hazards. As maritime environments become increasingly complex, defense organizations are prioritizing flexible and technologically advanced solutions to improve operational readiness. The growing requirement for reliable mine detection, classification, and disposal capabilities is expected to create sustained opportunities for market participants. Increased investments in autonomous systems, naval modernization initiatives, and maritime defense infrastructure are likely to support the continued expansion of the global mine countermeasure (MCM) systems market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.4 Billion |
| Forecast Value | $4.3 Billion |
| CAGR | 5.7% |
The Mine Countermeasure (MCM) Systems Market is witnessing strong growth due to increasing naval modernization efforts aimed at addressing changing underwater security challenges. Governments worldwide are investing in advanced maritime defense technologies, including autonomous surface platforms, underwater vehicles, and remotely controlled systems, to improve operational effectiveness while reducing personnel exposure during high-risk missions. The growing focus on securing important maritime corridors, ports, offshore assets, and underwater facilities is further increasing demand for advanced mine warfare capabilities. These developments are encouraging defense organizations to adopt more efficient and technology-driven mine countermeasure solutions.
The manned MCM vessels segment accounted for 32% share in 2025. The segment maintains a leading position due to its ability to support multiple mission requirements, including mine hunting, mine sweeping, command and control operations, and explosive ordnance disposal activities. Equipped with advanced sonar systems, mine disposal technologies, and integrated combat management capabilities, manned MCM vessels continue to serve as essential assets for complex mine warfare operations. Their operational flexibility and ability to coordinate with other defense platforms make them an important component of naval modernization programs worldwide.
The mine detection, classification & identification (MDCI) segment captured USD 838.1 million in 2025. This segment plays a critical role in identifying underwater mine threats before neutralization activities are conducted. Growing adoption of advanced detection technologies, improved sonar capabilities, autonomous underwater vehicles, and artificial intelligence-supported image processing systems is strengthening segment growth. These solutions enhance detection accuracy, reduce unnecessary alerts, and enable faster threat assessment, making MDCI capabilities a fundamental part of modern naval mine warfare strategies.
North America Mine Countermeasure (MCM) Systems Market is experiencing notable expansion due to rising naval modernization investments, increasing adoption of autonomous mine warfare technologies, and growing efforts to secure important maritime assets. Increased spending by defense organizations, including the U.S. Department of Defense (DoD) and the U.S. Navy, is supporting the development and deployment of advanced mine countermeasure solutions. The regional market is strengthened by greater integration of autonomous underwater vehicles, unmanned surface vehicles, advanced sonar technologies, and mine neutralization systems. These investments are expected to enhance maritime security capabilities and support continued growth across North America.
Prominent companies operating in the Global Mine Countermeasure (MCM) Systems Market include Lockheed Martin, BAE Systems plc, Elbit Systems, Exail Holding, General Dynamics (Bluefin Robotics), HII (Huntington Ingalls Industries - Mission Technologies), Israel Aerospace Industries (IAI), Kongsberg Defence & Aerospace, Kraken Robotics, L3Harris Technologies, Leonardo S.p.A., Naval Group, Northrop Grumman, RTX Corporation, Saab AB (Underwater Systems & Seaeye), Saab Seaeye, ST Engineering, Textron Systems, Thales Group, and TKMS / Atlas Elektronik. Companies operating in the Mine Countermeasure (MCM) Systems Market are strengthening their market position through continuous technology development, strategic collaborations, and expansion of advanced maritime defense solutions. Industry participants are investing in autonomous platforms, enhanced detection technologies, and integrated command systems to address evolving naval requirements. Companies are also focusing on research and development initiatives to improve underwater sensing accuracy, operational efficiency, and mission safety. Partnerships with defense organizations and naval forces are helping manufacturers expand their capabilities and increase global presence. In addition, businesses are enhancing product portfolios, developing customized solutions, and investing in next-generation unmanned technologies to gain a stronger competitive advantage in the evolving mine countermeasure systems market.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Platform type trends
- 2.2.2 Operation type trends
- 2.2.3 Technology trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising naval modernization programs focused on advanced mine warfare capabilities
- 3.2.1.2 Growing adoption of autonomous and unmanned mine countermeasure platforms
- 3.2.1.3 Increasing protection of critical maritime infrastructure and strategic sea lanes
- 3.2.1.4 Advancements in underwater sensing, AI-enabled target recognition, and sonar technologies
- 3.2.1.5 Increasing multinational naval exercises and maritime security cooperation
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High procurement and lifecycle costs of advanced MCM systems
- 3.2.2.2 Complex underwater operating environments and evolving mine threats
- 3.2.3 Market opportunities
- 3.2.3.1 Advancements in AI-enabled autonomous mine hunting and underwater robotics
- 3.2.3.2 Growing investments in protecting critical maritime infrastructure and strategic waterways
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Platform Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Autonomous underwater vehicles (AUVs)
- 5.3 Remotely operated vehicles (ROVs)
- 5.4 Unmanned surface vehicles (USVs)
- 5.5 Airborne MCM systems
- 5.6 Manned MCM vessels
Chapter 6 Market Estimates and Forecast, By Operation Type, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Mine detection, Classification & identification (MDCI)
- 6.3 Mine sweeping (Influence & mechanical)
- 6.4 Mine disposal & neutralization
- 6.5 Navigation safety & route survey
Chapter 7 Market Estimates and Forecast, By Technology, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Detection & Sensing Technologies
- 7.3 Mine Neutralization & Disposal Systems
- 7.4 Mission Management, C2 & Autonomous Systems
Chapter 8 Market Estimates and Forecast, By End-User, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Naval forces (blue-water & littoral Combat)
- 8.3 Coast guard & port/harbor security forces
- 8.4 Special operations maritime forces
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 France
- 9.3.2 United Kingdom
- 9.3.3 Germany
- 9.3.4 Norway
- 9.3.5 Italy
- 9.3.6 Sweden
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Chile
- 9.5.3 Mexico
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Naval Group
- 10.1.2 TKMS / Atlas Elektronik
- 10.1.3 Thales Group
- 10.1.4 BAE Systems
- 10.1.5 Leonardo S.p.A.
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Northrop Grumman
- 10.2.1.2 Lockheed Martin
- 10.2.1.3 L3Harris Technologies
- 10.2.1.4 RTX Corporation
- 10.2.2 Asia Pacific
- 10.2.2.1 ST Engineering
- 10.2.2.2 IAI (Israel Aerospace Industries)
- 10.2.2.3 Elbit Systems
- 10.2.3 Europe
- 10.2.3.1 Exail Holding
- 10.2.3.2 Kongsberg Defence & Aerospace
- 10.2.3.3 Saab AB
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Kraken Robotics
- 10.3.2 Saab Seaeye
- 10.3.3 General Dynamics
- 10.3.4 HII (Huntington Ingalls Industries - Mission Technologies)
- 10.3.5 Textron Systems


