


 |
市場調查報告書
商品編碼
2101597
綜合防空反導市場機會、成長要素、產業趨勢分析及2026-2035年預測Integrated Air and Missile Defense Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球綜合防空和飛彈防禦市場預計到 2025 年將達到 335 億美元,並以 10.8% 的複合年成長率成長,到 2035 年將達到 958 億美元。
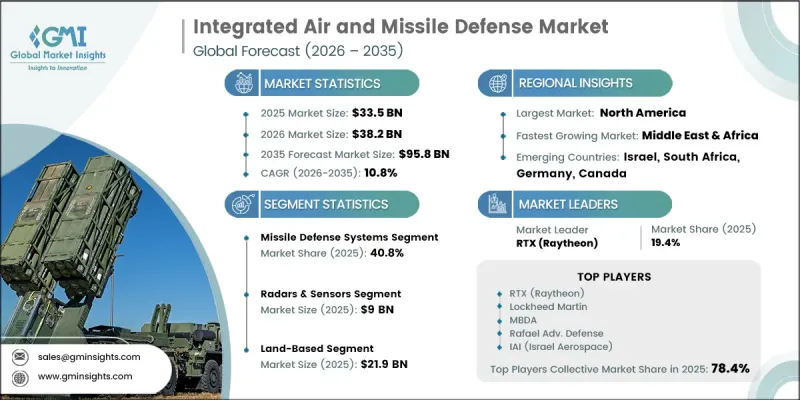
地緣政治不確定性加劇、軍事現代化項目不斷擴大、國防費用持續成長以及對多層防禦能力的投資增加,共同推動了整個一體化防空反導產業的發展。世界各國政府持續優先部署先進的防空反導系統,以增強國家安全並提高應對不斷演變的空中威脅的能力。對下一代攔截器、先進雷達技術、一體化指揮控制平台和網路中心戰解決方案的持續採購,支撐著市場的持續擴張。日益複雜的空中威脅使得對更強的探測、追蹤和攔截能力的需求不斷成長,進一步加速了對一體化防禦系統的需求。持續關注提升作戰準備、增強情境察覺以及擴展多層防禦架構,推動全球國防機構的長期投資。隨著各國軍隊不斷推進關鍵防禦基礎設施的現代化並增強一體化監視能力,預計全球一體化防空反導市場將在預測期內保持強勁成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 335億美元 |
| 預計金額 | 958億美元 |
| 複合年成長率 | 10.8% |
綜合防空反導市場持續受惠於國防現代化投資的增加以及先進多層防禦系統的發展。隨著各國政府不斷提升探測、追蹤和摧毀各類空中威脅的能力,對先進防禦技術的需求日益成長。雷達系統、攔截技術、遠端監視能力以及一體化指揮控制解決方案的持續進步,正在提高作戰效率,並促進現代防禦網路內部更緊密的協調。
到2025年,飛彈防禦系統市佔率將達到40.8%,成為最大的產品類型。該領域之所以能保持主導地位,是因為飛彈防禦系統在保護戰略資產、軍事設施、關鍵基礎設施和人口稠密地區免受各種空中威脅方面發揮著至關重要的作用。對先進監視技術、整合指揮系統和尖端攔截平台的持續投資,有助於確保採購的穩定性,並進一步提升多層次防禦戰略在全球國防專案中的重要性。
預計2025年,地面防空系統市場規模將達219億美元。地面防空系統持續推動市場發展,因為它們能夠為邊境、軍事設施、關鍵基礎設施和其他戰略資產提供全面的保護。對先進防空技術、移動飛彈平台、雷達系統以及指揮控制能力的持續投資將繼續增強這一市場,並支持更廣泛的軍事現代化進程。
2025年,北美綜合防空反導市場將佔據33.1%的市場。這一區域成長持續受到國防預算增加、國家安全持續投入以及先進多層飛彈防禦系統部署不斷擴大的推動。隨著加強國土防禦能力、改善監視基礎設施以及擴展綜合指揮控制網路的重要性日益凸顯,全部區域對先進防空反導技術的強勁需求仍然存在。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 增加國防費用和軍事現代化計劃
- 整合指揮控制(C2)、多域網路和感測器融合架構的採用率不斷提高。
- 北約及其盟國的綜合防空和飛彈防禦(IAMD)舉措,以及多邊互通性計畫的擴展。
- 新一代攔截器、遠端雷達和多層防空系統的採購量正在增加。
- 針對現代衝突中無人機使用日益增多的情況,迅速部署反無人機系統(C-UAS)能力。
- 產業潛在風險與挑戰
- 一體化防空反導系統的部署成本和全壽命週期成本都很高。
- 多域防禦網路中的複雜整合和互通性
- 市場機遇
- 人工智慧驅動的作戰管理和下一代感測器融合技術的發展
- 對防禦超音速武器和無人機(UAS)能力的需求日益成長
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估計與預測:依系統類型分類,2022-2035年
- 飛彈防禦系統
- 防空系統
- 無人機系統(C-UAS)
- 反火箭、反火砲和反迫擊砲(C-RAM)系統
- 高超音速武器對抗系統
第6章 市場估計與預測:依組件分類,2022-2035年
- 雷達和感測器
- 指揮、控制和作戰管理(C2/BMC)
- 攔截者
- 發射系統
- 通訊和網路基礎設施
- 整合和支援服務
第7章 市場估計與預測:依平台分類,2022-2035年
- 陸基
- 海軍
- 機載
第8章 市場估計與預測:依範圍層分類,2022-2035年
- 超短程防空系統(VSHORAD)
- 短程防空系統(SHORAD)
- 中程防空系統(MRAD)
- 遠端防空系統(LRAD)/上層
第9章 市場估價與預測:依最終用戶分類,2022-2035年
- 陸軍/地面部隊
- 海軍/海上力量
- 空軍/航太部隊
- 政府國防和民防機構
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 波蘭
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
- 以色列
第11章:公司簡介
- 全球主要公司
- RTX(Raytheon)
- Lockheed Martin
- MBDA
- Rafael Advanced Defense Systems Ltd.
- IAI(Israel Aerospace)
- 該地區的主要公司
- 北美洲
- Northrop Grumman
- 亞太地區
- Hanwha Aerospace
- LIG Nex1
- Bharat Electronics Limited(BEL)
- Mitsubishi Heavy Industries(MHI)
- 歐洲
- Thales Group
- Leonardo SpA
- BAE Systems
- Saab AB
- Rheinmetall
- HENSOLDT
- Kongsberg Defence & Aerospace
- Diehl Defence
- ASELSAN
- 北美洲
- 小眾玩家/顛覆者
- Almaz-Antey
The Global Integrated Air and Missile Defense Market was valued at USD 33.5 billion in 2025 and is estimated to grow at a CAGR of 10.8% to reach USD 95.8 billion by 2035.
Growth across the integrated air and missile defense industry is being driven by rising geopolitical uncertainty, expanding military modernization programs, increasing defense expenditures, and greater investment in layered defense capabilities. Governments continue to prioritize advanced air and missile defense systems to strengthen national security and improve protection against evolving aerial threats. Ongoing procurement of next-generation interceptors, advanced radar technologies, integrated command and control platforms, and network-centric defense solutions is supporting sustained market expansion. The growing need to enhance detection, tracking, and interception capabilities against increasingly sophisticated airborne threats is further accelerating demand for integrated defense systems. Continued emphasis on strengthening operational readiness, improving situational awareness, and expanding multi-layered defense architectures is encouraging long-term investment across defense organizations worldwide. As military forces continue to modernize critical defense infrastructure and enhance integrated surveillance capabilities, the global integrated air and missile defense market is expected to maintain strong growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $33.5 Billion |
| Forecast Value | $95.8 Billion |
| CAGR | 10.8% |
The integrated air and missile defense market continues to benefit from increasing investments in defense modernization and the development of advanced multi-layered protection systems. Demand for sophisticated defense technologies is rising as governments strengthen their capabilities to detect, track, and neutralize a broad range of airborne threats. Continuous advancements in radar systems, interceptor technologies, long-range surveillance capabilities, and integrated command and control solutions are improving operational effectiveness while supporting greater coordination across modern defense networks.
The missile defense systems segment accounted for 40.8% share in 2025, making it the largest product category. The segment maintains its leading position because missile defense systems play a critical role in protecting strategic assets, military facilities, critical infrastructure, and populated areas from a wide range of aerial threats. Continued investment in advanced surveillance technologies, integrated command systems, and modern interceptor platforms support consistent procurement while reinforcing the importance of multi-layered defense strategies across global defense programs.
The land-based segment generated USD 21.9 billion in 2025. Land-based systems continue to lead the market because they provide comprehensive protection for borders, military installations, critical infrastructure, and other strategic assets. Ongoing investments in advanced air defense technologies, mobile missile platforms, radar systems, and command and control capabilities continue to strengthen this segment while supporting broader military modernization initiatives.
North America Integrated Air and Missile Defense Market accounted for 33.1% share in 2025. Regional growth continues to be supported by increasing defense budgets, sustained investments in national security, and expanding deployment of advanced layered missile defense systems. Rising emphasis on strengthening homeland defense capabilities, improving surveillance infrastructure, and enhancing integrated command and control networks continues to generate strong demand for advanced air and missile defense technologies across the region.
Major companies operating in the global integrated air and missile defense market include Almaz-Antey, ASELSAN, BAE Systems, Bharat Electronics Limited (BEL), Diehl Defence, Hanwha Aerospace, HENSOLDT, Israel Aerospace Industries (IAI), Kongsberg Defence & Aerospace, Leonardo S.p.A., LIG Nex1, Lockheed Martin, MBDA, Mitsubishi Heavy Industries (MHI), Northrop Grumman, Rafael Advanced Defense Systems, Rheinmetall, Saab AB, Thales Group, and RTX (Raytheon). Companies operating in the integrated air and missile defense market are strengthening their competitive position by investing in advanced interceptor technologies, next-generation radar systems, and integrated command and control solutions. Manufacturers continue to focus on research and development to improve detection capabilities, targeting accuracy, system interoperability, and operational performance. Strategic partnerships, defense contracts, and collaboration with government agencies remain essential for expanding market presence and securing long-term procurement opportunities. Companies are also increasing investments in network-centric defense technologies, scalable system architectures, and advanced surveillance capabilities to address evolving security requirements.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 System type trends
- 2.2.2 Component trends
- 2.2.3 Platform trends
- 2.2.4 Range layer trends
- 2.2.5 End-user trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising defense spending and military modernization programs
- 3.2.1.2 Growing adoption of integrated command-and-control (C2), multi-domain networking, and sensor fusion architectures
- 3.2.1.3 Expansion of NATO and allied Integrated Air and Missile Defence (IAMD) initiatives and multinational interoperability programs
- 3.2.1.4 Increasing procurement of next-generation interceptors, long-range radars, and layered air defense systems
- 3.2.1.5 Rapid deployment of counter-UAS (C-UAS) capabilities driven by the increasing use of drones in modern conflicts
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High acquisition and lifecycle costs of integrated air and missile defense systems
- 3.2.2.2 Complex integration and interoperability across multi-domain defense networks
- 3.2.3 Market opportunities
- 3.2.3.1 Development of AI-enabled battle management and next-generation sensor fusion technologies
- 3.2.3.2 Growing demand for counter-hypersonic and counter-UAS defense capabilities
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By System Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Missile Defense Systems
- 5.3 Anti-Aircraft Defense Systems
- 5.4 Counter-UAS (C-UAS) Systems
- 5.5 Counter-Rockets, Artillery & Mortars (C-RAM) Systems
- 5.6 Counter-Hypersonic Systems
Chapter 6 Market Estimates and Forecast, By Component, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Radars & Sensors
- 6.3 Command, Control & Battle Management (C2/BMC)
- 6.4 Interceptors
- 6.5 Launch Systems
- 6.6 Communication & Network Infrastructure
- 6.7 Integration & Support Services
Chapter 7 Market Estimates and Forecast, By Platform, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Land-Based
- 7.3 Naval-Based
- 7.4 Airborne
Chapter 8 Market Estimates and Forecast, By Range Layer, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Very Short-Range Air Defense (VSHORAD)
- 8.3 Short Range Air Defense (SHORAD)
- 8.4 Medium Range Air Defense (MRAD)
- 8.5 Long Range Air Defense (LRAD) / Upper Tier
Chapter 9 Market Estimates and Forecast, By End-user, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Army / Land Forces
- 9.3 Navy / Maritime Forces
- 9.4 Air Force / Aerospace Forces
- 9.5 Government Defense & Civil Security Agencies
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Poland
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
- 10.6.4 Israel
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 RTX (Raytheon)
- 11.1.2 Lockheed Martin
- 11.1.3 MBDA
- 11.1.4 Rafael Advanced Defense Systems Ltd.
- 11.1.5 IAI (Israel Aerospace)
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Northrop Grumman
- 11.2.2 Asia Pacific
- 11.2.2.1 Hanwha Aerospace
- 11.2.2.2 LIG Nex1
- 11.2.2.3 Bharat Electronics Limited (BEL)
- 11.2.2.4 Mitsubishi Heavy Industries (MHI)
- 11.2.3 Europe
- 11.2.3.1 Thales Group
- 11.2.3.2 Leonardo S.p.A.
- 11.2.3.3 BAE Systems
- 11.2.3.4 Saab AB
- 11.2.3.5 Rheinmetall
- 11.2.3.6 HENSOLDT
- 11.2.3.7 Kongsberg Defence & Aerospace
- 11.2.3.8 Diehl Defence
- 11.2.3.9 ASELSAN
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Almaz-Antey

 防空作戰市場分析及預測(至2035年):類型、產品、服務、技術、組件、應用、部署、最終用戶、功能
 整合防空與飛彈防禦市場:規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測
 2026年全球綜合防空反導市場報告2026年全球飛彈及飛彈防禦系統市場報告
 飛彈防禦系統市場-2026-2032年全球市場預測
 2026-2030年全球飛彈及飛彈防禦系統市場
 綜合防空與飛彈防禦市場報告:趨勢、預測及競爭分析(至2035年)防空作戰市場報告:趨勢、預測與競爭分析(至2035年)飛彈及飛彈防禦系統市場報告:趨勢、預測及競爭分析(至2035年)2026年全球防空戰爭市場報告