


 |
市場調查報告書
商品編碼
2101544
高功率微波武器市場機會、成長要素、產業趨勢分析及2026-2035年預測。High Power Microwave Weapons Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球高功率微波武器市場價值為16億美元,預計2035年將以13.3%的複合年成長率成長至55億美元。
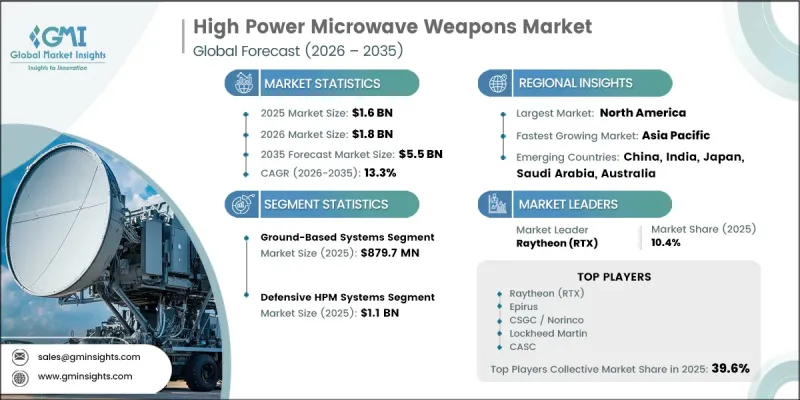
隨著國防機構日益重視先進定向能技術、下一代防禦能力和現代化軍事系統,市場正在不斷成長。對非致命性武器技術的投資增加,推動了旨在應對不斷演變的電子威脅並減少對傳統攔截方法依賴的解決方案的研發。對先進防禦系統日益成長的需求、反無人機技術的廣泛應用以及主要國防經濟體持續推進的軍事現代化,為高功率微波武器製造商創造了巨大的商機。這些系統之所以備受關注,是因為它們具有經濟高效的電子干擾能力,並能支援未來的國防戰略。微波生成技術、系統整合和部署柔軟性的不斷改進也促進了市場擴張。隨著國防機構繼續優先發展先進電子戰能力,高功率微波武器市場預計將在預測期內保持持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 16億美元 |
| 預測金額 | 55億美元 |
| 複合年成長率 | 13.3% |
預計到2025年,地面系統業務的銷售額將達到8.797億美元。該業務板塊的強勁地位得益於國防應用中對可靠電子防護的固定式和移動式地面解決方案的日益普及。高操作柔軟性、強大的功率供給能力以及與現有國防基礎設施的兼容性,持續推動軍事機構對地面高功率微波系統的需求。
預計2026年至2035年間,進攻性高功率微波(HPM)領域將以14.8%的複合年成長率成長。該領域的成長主要得益於對旨在應對電磁戰能力和電子威脅的先進防禦解決方案日益成長的需求。國防領域對先進微波技術的投資增加、脈衝生成能力的提升以及與現代軍事平台整合能力的增強,都為進攻性HPM系統的研發和採購提供了支援。對先進電子戰戰略的日益重視預計將進一步推動國防應用領域整體這些系統的需求。
到2025年,北美高功率微波武器市場佔有率將達到47.1%。這一區域成長主要得益於對先進國防技術的需求不斷成長、軍事能力的現代化以及對定向能量武器研發的持續投入。該地區的國防機構繼續將先進電子戰解決方案列為優先事項,以此作為提升軍事戰備水準和加強應對新興安全挑戰的更廣泛努力的一部分。主要國防機構和產業相關人員正在持續進行研發工作,以推動高功率微波技術從研發專案向作戰部署階段的過渡。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 應對無人機的反制措施及日益嚴重的無人機群威脅
- 政府加大對定向能量武器(DEW)計畫的投入
- 軍事現代化和一體化防空飛彈防禦計劃
- 氮化鎵 (GaN) 和固體微波技術的進展
- 對可重複使用、低成本、高容量的國防解決方案的需求日益成長。
- 產業潛在風險與挑戰
- 高昂的開發成本和系統整合成本
- 發電和溫度控管的限制
- 市場機遇
- 擴大反無人機系統和關鍵基礎設施保護計劃
- 緊湊型固體微波技術和氮化鎵(GaN)技術的進步
- 促進因素
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 生產能力和生產情況
- 主要生產商的生產能力
- 運轉率和擴張計劃
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依波發射模式分類,2022-2035年
- 連續波(CW)HPM系統
- 脈衝波HPM系統
第6章 市場估計與預測:依平台分類,2022-2035年
- 地面系統
- 機載系統
- 海軍和海洋系統
- 天基系統
第7章 市場估價與預測:依業務角色分類,2022-2035年
- 防禦型HPM系統
- 進攻型HPM系統
第8章 市場估算與預測:依最終使用者分類,2022-2035年
- 陸軍/地面部隊
- 海軍/海上力量
- 空軍
- 國防安全保障和執法機關
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 俄羅斯
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Raytheon(RTX)
- Epirus
- CSGC/Norinco
- Lockheed Martin
- CASC
- 該地區的主要公司
- 北美洲
- Boeing Defense, Space & Security
- Leidos
- 亞太地區
- Tonbo Imaging
- 歐洲
- BAE Systems plc
- Diehl Defence GmbH & Co. KG
- Thales Group
- 北美洲
- 小眾玩家/顛覆者
- ThinKom Solutions
- Rafael Advanced Defense Systems
The Global High-Power Microwave Weapons Market was valued at USD 1.6 billion in 2025 and is estimated to grow at a CAGR of 13.3% to reach USD 5.5 billion by 2035.
The market is experiencing growth as defense organizations increasingly focus on advanced directed energy technologies, next-generation defense capabilities, and modern military systems. Rising investments in non-kinetic weapon technologies are supporting the development of solutions designed to counter evolving electronic threats while reducing dependence on conventional interception methods. Growing demand for advanced defense systems, increasing adoption of counter-unmanned technology, and continued military modernization initiatives across major defense economies are creating significant opportunities for high-power microwave weapon manufacturers. These systems are gaining attention due to their ability to provide cost-efficient electronic disruption capabilities and support future defense strategies. Continuous improvements in microwave generation technologies, system integration, and deployment flexibility are further contributing to market expansion. As defense agencies continue prioritizing advanced electronic warfare capabilities, the high-power microwave weapons market is expected to experience sustained growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $1.6 Billion |
| Forecast Value | $5.5 Billion |
| CAGR | 13.3% |
The ground-based systems segment generated USD 879.7 million in 2025. The segment's strong position is supported by increasing adoption of fixed and mobile ground-based solutions for defense applications requiring reliable electronic protection capabilities. High operational flexibility, strong power availability, and compatibility with existing defense infrastructure continue to encourage demand for ground-based high-power microwave systems across military organizations.
The offensive high-power microwave (HPM) segment is projected to grow at a CAGR of 14.8% during 2026-2035. Growth within this segment is being driven by increasing attention toward electromagnetic warfare capabilities and advanced defense solutions designed to address electronic threats. Rising defense investments in advanced microwave technologies, improved pulse generation capabilities, and enhanced integration with modern military platforms are supporting the development and procurement of offensive HPM systems. The growing focus on advanced electronic warfare strategies is expected to strengthen demand for these systems across defense applications.
North America High-Power Microwave Weapons Market accounted for 47.1% share in 2025. Regional growth is supported by increasing demand for advanced defense technologies, modernization of military capabilities, and ongoing investments in directed energy weapon development. Defense organizations across the region continue to prioritize advanced electronic warfare solutions as part of broader efforts to enhance military readiness and strengthen protection against emerging security challenges. Continued research and development initiatives by leading defense agencies and industry participants are supporting the transition of high-power microwave technologies from development programs toward operational deployment.
Major companies operating in the global high-power microwave weapons market include Lockheed Martin Corporation, Epirus Inc., Raytheon Technologies (RTX), BAE Systems plc, Thales Group, Boeing Defense, Space & Security, Rafael Advanced Defense Systems, Leidos, Diehl Defence GmbH & Co. KG, CASIC (China Aerospace Science & Industry Corp.), NORINCO (China North Industries Group Corp.), ThinKom Solutions, and Tonbo Imaging. Companies operating in the high-power microwave weapons market are strengthening their market position by investing in research and development, expanding technology capabilities, and improving system integration expertise. Market participants are focusing on advancing microwave technologies, enhancing product reliability, and developing solutions that address evolving defense requirements. Strategic collaborations with defense organizations and government agencies help companies secure development opportunities and expand their presence in global defense programs. Businesses are also increasing investments in manufacturing capabilities, testing infrastructure, and engineering expertise to accelerate technology advancement and improve operational readiness.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Wave emission mode trends
- 2.2.2 Platform trends
- 2.2.3 Operational role trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising counter-drone and drone swarm threats
- 3.2.1.2 Increasing government investments in directed energy weapon (DEW) programs
- 3.2.1.3 Military modernization and integrated air & missile defense initiatives
- 3.2.1.4 Advancements in Gallium Nitride (GaN) and solid-state microwave technologies
- 3.2.1.5 Growing demand for reusable, low-cost, deep-magazine defense solutions
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High development and system integration costs
- 3.2.2.2 Power generation and thermal management limitations
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of counter-UAS and critical infrastructure protection programs
- 3.2.3.2 Advancements in compact solid-state microwave and Gallium Nitride (GaN) technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.2 Europe
- 3.5.3 Asia Pacific
- 3.5.4 Latin America
- 3.5.5 Middle East & Africa
- 3.6 Porter's analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database)
- 3.8.1 Import/Export Volume & Value Trends
- 3.8.2 Key Trade Corridors & Tariff Impact
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Production Capacity by Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis, 2025
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia-Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.2 Market Concentration Analysis
- 4.2.1 By Region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Wave Emission Mode, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Continuous wave (CW) hpm systems
- 5.3 Pulsed wave hpm systems
Chapter 6 Market Estimates and Forecast, By Platform, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Ground-based systems
- 6.3 Airborne systems
- 6.4 Naval / maritime systems
- 6.5 Space-based systems
Chapter 7 Market Estimates and Forecast, By Operational Role, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Defensive hpm systems
- 7.3 Offensive hpm systems
Chapter 8 Market Estimates and Forecast, By End-User, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Army / ground forces
- 8.3 Navy / maritime forces
- 8.4 Air force
- 8.5 Homeland security & law enforcement
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Russia
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Raytheon (RTX)
- 10.1.2 Epirus
- 10.1.3 CSGC / Norinco
- 10.1.4 Lockheed Martin
- 10.1.5 CASC
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Boeing Defense, Space & Security
- 10.2.1.2 Leidos
- 10.2.2 Asia Pacific
- 10.2.2.1 Tonbo Imaging
- 10.2.3 Europe
- 10.2.3.1 BAE Systems plc
- 10.2.3.2 Diehl Defence GmbH & Co. KG
- 10.2.3.3 Thales Group
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 ThinKom Solutions
- 10.3.2 Rafael Advanced Defense Systems


