


 |
市場調查報告書
商品編碼
2101529
低溫電池回收市場機會、成長要素、產業趨勢分析及2026-2035年預測Cryogenic Battery Recycling Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球低溫電池回收市場預計到 2025 年將達到 4.104 億美元,並以 18.9% 的複合年成長率成長,到 2035 年達到 23 億美元。
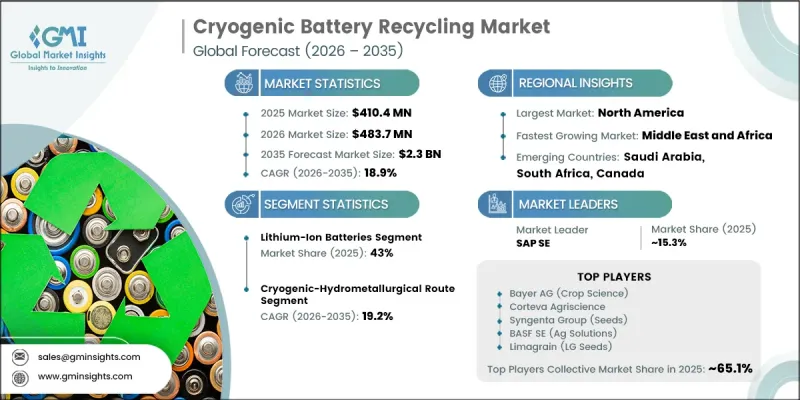
低溫電池回收市場是電池回收行業中一個高度專業化的細分市場,其特點是採用低溫預處理技術,在提高材料回收效率的同時,增強操作安全性並符合監管要求。隨著全球電動車的普及,達到使用壽命終點的電池組數量不斷增加,為回收材料提供了穩定的來源。主要汽車市場電池廢棄物數量的成長,提高了商業規模低溫回收作業的可行性。此工藝的顯著優勢在於,能夠在回收有價值的電池材料的同時,在整個下游回收階段保持材料品質。長期市場成長主要受行業結構性趨勢而非短期經濟波動的支撐,預計在預測期內,低溫電池回收將成為永續電池生命週期管理和資源回收日益重要的解決方案。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 4.104億美元 |
| 預測金額 | 23億美元 |
| 複合年成長率 | 18.9% |
預計到2025年,鋰離子電池市佔率將達到43%。此細分市場佔據主導地位的原因在於:廢棄電動車電池數量不斷增加、可回收材料的經濟價值高,以及鋰離子電池的化學性質與低溫預處理技術高度親和性。與傳統的回收方法相比,低溫製程能夠更有效率地進行下游分離,並回收高純度材料,因為它可以有效中和溫度敏感的電池組分,同時保持電極的完整性。
預計到2025年,低溫濕式冶金製程將佔據41.5%的市場佔有率,並在2035年之前以19.2%的複合年成長率成長。該製程憑藉其在營運擴充性、材料回收率和產品純度方面的有效平衡,持續引領市場。其能夠生產滿足電池製造應用品質要求的再生材料,推動了該工藝的日益普及,使其成為對回收效率和穩定運行性能有較高要求的商業規模回收設施的首選加工方法。
預計到2025年,北美低溫電池回收市場佔有率將達到30.5%,並在2035年之前以17%的複合年成長率成長。該地區保持領先地位的原因在於:持續投資於電池回收網路、擴大回收基礎設施、電動車相關製造業活動活性化以及主導電池處理技術的日益普及。商業規模回收作業中低溫預處理系統的日益普及,有助於提高材料回收能力和營運效率,從而進一步推動該地區市場成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 隨著第一代電動車電池壽命的結束,全球廢棄電池處理量正在激增。
- 歐盟電池法規 2023/1542:規定了回收成分和回收率的最低標準。
- 保障關鍵礦產(鋰、鈷、鎳等被指定為戰略原料)供應面臨挑戰。
- 產業潛在風險與挑戰
- 由於液態氮消耗量大,低溫製程的運作成本比傳統製程更高。
- 監管碎片化以及根據《巴塞爾公約》和聯合國第38.3號公約對電池廢棄物進行跨境分類的障礙
- 市場機遇
- 對永續電動車電池處置和材料回收的需求日益成長。
- 監管機構對循環經濟和危險廢棄物管理的關注度日益提高
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 價格趨勢
- 按地區
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 專利趨勢
- 貿易統計資料(註:貿易統計僅涵蓋主要國家)
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估計與預測:依電池化學成分分類,2022-2035年
- 鋰離子電池(Li-ion)
- NMC(鎳-錳-鈷)-鈷和鎳的回收率高。
- NCA(鎳鈷鋁)-電動車高密度電池組
- 磷酸鋰鐵(LFP) – 成長最快的細分市場,不含鈷。
- LMO(鋰錳氧化物)和其他類型的鋰離子電池
- 鉛酸
- 液態鉛酸電池
- VRLA/AGM(閥控式鉛酸蓄電池及吸附式玻璃纖維隔板蓄電池)
- 鎳基
- 鎳鎘合金(Ni-Cd)
- 鎳氫電池(Ni-MH)
- 全固態電池和新興化學系統
- 全固態電池(硫化物、氧化物、聚合物電解質)
- 鈉離子電池
- 鋰硫(Li-S)及其他新興化學品
第6章 市場估算與預測:依路線分類的回收工藝,2022-2035年
- 低溫和機械途徑
- 低溫濕式冶金路線
- 低溫和高溫冶金路線
- 低溫直接回收路線
第7章 市場估價與預測:依電池類型分類,2022-2035年
- 電動車和電動旅行電池
- 固定式儲能電池
- 工業和商業電池
- 家用電子電器電池
- 用於航太、國防和特殊用途的電池
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第9章:公司簡介
- Retriev Technologies
- Umicore NV
- Redwood Materials
- Fortum Battery Recycling
- Glencore plc
- BRUNP Recycling
- Duesenfeld GmbH
- SungEel HiTech
- Accurec Recycling GmbH
- Cirba Solutions
- Green Li-ion
- cylib GmbH
- American Battery Technology Company(ABTC)
- Ascend Elements
- Nth Cycle
- Primobius
The Global Cryogenic Battery Recycling Market was valued at USD 410.4 million in 2025 and is estimated to grow at a CAGR of 18.9% to reach USD 2.3 billion by 2035.
The cryogenic battery recycling market represents a specialized segment within the broader battery recycling industry, distinguished by its use of cryogenic pretreatment technology that enhances material recovery efficiency while improving operational safety and supporting regulatory compliance. As electric vehicle adoption continues to mature globally, an increasing number of battery packs are approaching the end of their operational lifespan, creating a steady supply of recyclable materials. Growing battery retirement volumes across major automotive markets are making commercial-scale cryogenic recycling operations increasingly viable. The process offers significant advantages for recovering valuable battery materials while preserving material quality throughout downstream recycling stages. Long-term market growth is supported by structural industry trends rather than short-term economic fluctuations, positioning cryogenic battery recycling as an increasingly important solution for sustainable battery lifecycle management and resource recovery over the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $410.4 Million |
| Forecast Value | $2.3 Billion |
| CAGR | 18.9% |
The lithium-ion batteries segment accounted for 43% share in 2025. Its market leadership is supported by the expanding number of retired electric vehicle batteries, the high economic value of recoverable materials, and the strong compatibility between lithium-ion battery chemistry and cryogenic pretreatment technology. The cryogenic process effectively neutralizes temperature-sensitive battery components while preserving electrode integrity, enabling more efficient downstream separation processes and supporting the recovery of high-purity materials compared with conventional recycling approaches.
The cryogenic-hydrometallurgical route represented 41.5% share in 2025 and is anticipated to grow at a CAGR of 19.2% throughout 2035. This processing route continues to lead the market because it delivers an effective balance of operational scalability, material recovery performance, and product purity. Its ability to produce recycled materials that satisfy the quality requirements of battery manufacturing applications has strengthened its adoption, making it one of the preferred processing methods for commercial-scale recycling facilities seeking high recovery efficiency and consistent operational performance.
North America Cryogenic Battery Recycling Market accounted for 30.5% share in 2025 and is expected to grow at a CAGR of 17% through 2035. The region maintains its leading position due to continued investment in battery collection networks, expanding recycling infrastructure, increasing manufacturing activity related to electric mobility, and the growing deployment of advanced battery processing technologies. The rising integration of cryogenic pretreatment systems into commercial recycling operations is further supporting regional market growth while enhancing material recovery capabilities and operational efficiency.
Major companies operating in the global cryogenic battery recycling market include Retriev Technologies, Umicore N.V., Redwood Materials, Fortum Battery Recycling, Glencore plc, BRUNP Recycling, Duesenfeld GmbH, SungEel HiTech, Accurec Recycling GmbH, Cirba Solutions, Green Li-ion, cylib GmbH, American Battery Technology Company (ABTC), Ascend Elements, Nth Cycle, and Primobius. Companies participating in the cryogenic battery recycling market are strengthening their competitive position by expanding processing capacity, investing in advanced recycling technologies, and improving material recovery efficiency. Industry participants continue to prioritize research and development to enhance cryogenic pretreatment processes, increase operational safety, and maximize the recovery of valuable battery materials. Strategic collaborations, technology partnerships, and acquisitions are helping companies broaden their capabilities while expanding their geographic presence. Businesses are also focusing on automation, process optimization, and sustainable recycling practices to improve productivity and reduce operating costs.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Battery Chemistry
- 2.2.3 Recycling process route
- 2.2.4 Battery source
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
- 2.4.2 Critical success factors
- 2.5 Future Outlook and Strategic Recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 First-Generation EV Battery End-of-Life Wave Accelerating Spent Battery Volumes Globally
- 3.2.1.2 EU Battery Regulation 2023/1542 Mandating Minimum Recycled Content & Recovery Rate Thresholds
- 3.2.1.3 Critical Mineral Supply Security Imperatives - Lithium, Cobalt & Nickel Designated as Strategic Raw Materials
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Liquid Nitrogen Consumption Costs Elevating Cryogenic Process OPEX vs. Conventional Alternatives
- 3.2.2.2 Regulatory Fragmentation & Cross-Border Battery Waste Classification Barriers under Basel Convention & UN 38.3
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing Demand for Sustainable EV Battery Disposal & Material Recovery
- 3.2.3.2 Rising Regulatory Focus on Circular Economy & Hazardous Waste Management
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.8 Future market trends
- 3.9 Technology and Innovation Landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code) (Note: the trade statistics will be provided for key countries only)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint considerations
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Battery Chemistry, 2022 - 2035 (USD Million) (Kilo Tons)
- 5.1 Key trends
- 5.2 Lithium-ion (Li-ion)
- 5.2.1 NMC (Nickel Manganese Cobalt) - High Cobalt & Nickel Recovery Value
- 5.2.2 NCA (Nickel Cobalt Aluminum) - EV-Grade High-Density Packs
- 5.2.3 LFP (Lithium Iron Phosphate) - Fastest-Growing Sub-Segment, Cobalt-Free
- 5.2.4 LMO (Lithium Manganese Oxide) & Other Li-ion Variants
- 5.3 Lead-Acid
- 5.3.1 Flooded Lead-Acid
- 5.3.2 VRLA/AGM (Valve-Regulated Lead-Acid & Absorbent Glass Mat)
- 5.4 Nickel-Based
- 5.4.1 Nickel-Cadmium (Ni-Cd)
- 5.4.2 Nickel-Metal Hydride (Ni-MH)
- 5.5 Solid-State & Emerging Chemistries
- 5.5.1 Solid-State Batteries (Sulfide, Oxide & Polymer Electrolyte)
- 5.5.2 Sodium-Ion (Na-ion) Batteries
- 5.5.3 Lithium-Sulfur (Li-S) & Other Emerging Chemistries
Chapter 6 Market Estimates and Forecast, By Recycling Process Route, 2022 - 2035 (USD million) (Kilo Tons)
- 6.1 Key trends
- 6.2 Cryogenic-Mechanical Route
- 6.3 Cryogenic-Hydrometallurgical Route
- 6.4 Cryogenic-Pyrometallurgical Route
- 6.5 Cryogenic-Direct Recycling Route
Chapter 7 Market Estimates and Forecast, By Battery Source, 2022 - 2035 (USD million) (Kilo Tons)
- 7.1 Key trends
- 7.2 EV & e-Mobility Batteries
- 7.3 Stationary Energy Storage Batteries
- 7.4 Industrial & Commercial Batteries
- 7.5 Consumer Electronics Batteries
- 7.6 Aerospace, Defense & Specialty Batteries
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 (USD million) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Retriev Technologies
- 9.2 Umicore N.V.
- 9.3 Redwood Materials
- 9.4 Fortum Battery Recycling
- 9.5 Glencore plc
- 9.6 BRUNP Recycling
- 9.7 Duesenfeld GmbH
- 9.8 SungEel HiTech
- 9.9 Accurec Recycling GmbH
- 9.10 Cirba Solutions
- 9.11 Green Li-ion
- 9.12 cylib GmbH
- 9.13 American Battery Technology Company (ABTC)
- 9.14 Ascend Elements
- 9.15 Nth Cycle
- 9.16 Primobius

