


 |
市場調查報告書
商品編碼
2083371
鉀礦開採及貿易市場機會、成長促進因素、產業趨勢分析及2026-2035年預測。Potash Mining and Trade Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

據估計,2025 年全球鉀肥開採和貿易市場價值為 460 億美元,預計到 2035 年將以 5% 的複合年成長率成長至 753 億美元。
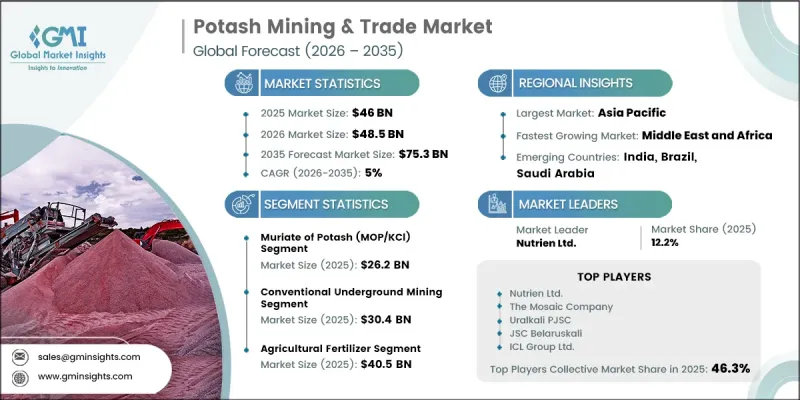
鉀肥產業涵蓋多種礦產資源,包括鉀元素,這些資源從天然礦床中開採出來,並加工成用於農業和工業的商業產品。該行業包含多個產品類型,這些類別的鉀含量、性能特徵和最終用途要求各不相同。鉀是植物生長和生產力所必需的最重要營養素之一,它支持著直接影響農業生產的關鍵生物過程。由於其農業化學功能尚無實際替代品,因此在各種市場狀況和農業週期中,鉀的需求都保持強勁。鉀肥開採和貿易市場受益於這種根本性的依賴性,形成了穩定的長期需求前景。市場動態也受到生產區域集中度的影響;少數生產區域佔據了全球大部分產量,而消費則廣泛分佈於各大農業經濟體。這種供應集中和需求地域分散的結合,持續影響全球鉀肥產業的貿易流動、定價結構和投資活動。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 460億美元 |
| 預測金額 | 753億美元 |
| 複合年成長率 | 5% |
預計到2025年,氯化鉀(MOP/KCl)市場規模將達262億美元。其市場主導地位得益於其相對於鉀含量而言極高的經濟效益,使其成為大規模施肥項目和各種農業應用的首選。該產品能夠為作物生產提供經濟高效的營養支持,因此持續保持較高的市場滲透率。
到2025年,農業肥料市場規模將達到405億美元。鉀在提高作物產量、維持土壤養分平衡以及改善植物在各種生長條件下的整體生長能力方面發揮著至關重要的作用。除了農業應用外,工業和化學領域的需求也進一步支撐了市場。在這些領域,鉀肥是多種生產過程的重要原料,從而保證了其在眾多終端用戶產業的穩定消耗。
預計到2025年,北美鉀肥開採和貿易市場規模將達101億美元。主要農業全部區域廣泛的商業農業活動和既定的化肥消費模式持續支撐著區域需求。供應鏈效率的提高、分銷基礎設施的完善以及農業領域的持續技術進步,預計將進一步加速北美鉀肥市場的擴張,並支撐長期消費趨勢。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 全球農業部門對化肥的需求不斷成長
- 人口成長導致對農作物產量的需求不斷增加。
- 耕地面積擴大
- 產業潛在風險與挑戰
- 引入永續和高效的採礦方法
- 新興市場化肥消費量增加
- 市場機遇
- 與採礦活動相關的環境問題
- 全球鉀價波動趨勢
- 該項目需要大量資金投入。
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 未來市場趨勢
- 專利趨勢
- 交易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依產品分類,2022-2035年
- 氯化鉀(MOP/KCl)
- 硫酸鉀(SOP)
- 硫酸鉀鎂(SOPM/蘭格賓石)
- 硝酸鉀( KNO₃ )
- 多鹵石及其他
第6章 市場估算與預測:依採礦與開採方法分類,2022-2035年
- 傳統地下採礦
- 解決方案挖掘
- 鹽水/蒸發採礦
- 其他
第7章 市場估計與預測:依最終用途分類,2022-2035年
- 農業肥料
- 工業和化學加工
- 動物飼料添加劑
- 醫藥級及食品級
- 除冰及其他服務
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第9章:公司簡介
- Nutrien Ltd.
- The Mosaic Company
- Uralkali PJSC
- JSC Belaruskali
- K+S Aktiengesellschaft
- ICL Group Ltd.
- EuroChem Group AG
- Arab Potash Company
- SQM SA
- Qinghai Salt Lake Industry
The Global Potash Mining & Trade Market was valued at USD 46 billion in 2025 and is estimated to grow at a CAGR of 5% to reach USD 75.3 billion by 2035.
Potash consists of potassium-containing mineral resources that are extracted from natural deposits and processed into commercial products for agricultural and industrial applications. The industry encompasses several product categories that differ in potassium concentration, performance characteristics, and end-use requirements. Potassium remains one of the most critical nutrients required for plant development and productivity, supporting essential biological processes that directly influence agricultural output. Since no practical alternative exists for its agronomic function, demand remains resilient across varying market conditions and agricultural cycles. The Potash Mining & Trade Market benefits from this fundamental dependence, creating a stable long-term demand outlook. Market dynamics are also influenced by a concentrated production landscape, where a limited number of producing regions account for a substantial share of global output, while consumption remains widely distributed across major agricultural economies. This combination of concentrated supply and geographically diversified demand continues to shape trade flows, pricing structures, and investment activity throughout the global potash industry.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $46 Billion |
| Forecast Value | $75.3 Billion |
| CAGR | 5% |
The muriate of Potash (MOP/KCl) segment generated USD 26.2 billion in 2025. Its leading position is supported by favorable economic efficiency relative to potassium content, making it the preferred choice across large-scale fertilizer programs and broad agricultural applications. The product continues to maintain strong market penetration due to its ability to deliver cost-effective nutrient supplementation for crop production.
The agricultural fertilizer applications segment accounted for USD 40.5 billion in 2025. Potash plays a vital role in supporting crop productivity, maintaining nutrient balance within agricultural soils, and enhancing overall plant performance under varying growing conditions. Beyond agricultural use, demand is further supported by industrial and chemical sectors where potash-based materials serve as important inputs in multiple manufacturing processes, helping sustain consistent consumption across a broad range of end-use industries.
North America Potash Mining & Trade Market reached USD 10.1 billion in 2025. Regional demand remains supported by extensive commercial farming activities and well-established fertilizer consumption patterns throughout major agricultural regions. Continued improvements in supply chain efficiency, distribution infrastructure, and technological advancements across the agricultural sector are expected to reinforce market expansion and support long-term consumption trends throughout North America.
Key participants operating in the Global Potash Mining & Trade Market include The Mosaic Company, Nutrien Ltd., JSC Belaruskali, Uralkali PJSC, ICL Group Ltd., K+S Aktiengesellschaft, EuroChem Group AG, Arab Potash Company, Qinghai Salt Lake Industry, and SQM S.A. Companies operating in the Potash Mining & Trade Market are focusing on several strategic initiatives to strengthen their market position and expand their global footprint. Capacity expansion projects remain a key priority as producers seek to improve output capabilities and meet rising long-term demand. Businesses are also investing in operational efficiency programs, advanced mining technologies, and supply chain optimization to reduce production costs and enhance competitiveness. Strategic partnerships, long-term supply agreements, and distribution network expansion are commonly used to secure customer relationships and improve market access. In addition, many industry participants are increasing investments in logistics infrastructure and export capabilities to strengthen international trade operations.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Product
- 2.2.2 Mining & Extraction Method
- 2.2.3 End Use
- 2.2.4 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising global fertilizer demand from agriculture
- 3.2.1.2 Population growth increasing crop yield requirements
- 3.2.1.3 Expansion of arable land regions
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Sustainable and efficient mining practices adoption
- 3.2.2.2 Emerging markets increasing fertilizer consumption levels
- 3.2.3 Market opportunities
- 3.2.3.1 Environmental concerns related to mining operations
- 3.2.3.2 Volatility in global potash pricing trends
- 3.2.3.3 High capital investment requirements for projects
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Future market trends
- 3.10 Patent landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product, 2022-2035 (USD Million) (Kilo Tons)
- 5.1 Key trends
- 5.2 Muriate of potash (MOP/KCl)
- 5.3 Sulfate of potash (SOP)
- 5.4 Sulfate of Potash Magnesia (SOPM/Langbeinite)
- 5.5 Potassium Nitrate (KNO3)
- 5.6 Polyhalite & Others
Chapter 6 Market Estimates and Forecast, By Mining & Extraction Method, 2022-2035 (USD Million) (Kilo Tons)
- 6.1 Key trends
- 6.2 Conventional underground mining
- 6.3 Solution mining
- 6.4 Brine/evaporation mining
- 6.5 Others
Chapter 7 Market Estimates and Forecast, By End use, 2022-2035 (USD Million) (Kilo Tons)
- 7.1 Key trends
- 7.2 Agricultural fertilizers
- 7.3 Industrial & chemical processing
- 7.4 Animal feed supplements
- 7.5 Pharmaceutical & food grade
- 7.6 De-icing & others
Chapter 8 Market Estimates and Forecast, By Region, 2022-2035 (USD Million) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Nutrien Ltd.
- 9.2 The Mosaic Company
- 9.3 Uralkali PJSC
- 9.4 JSC Belaruskali
- 9.5 K+S Aktiengesellschaft
- 9.6 ICL Group Ltd.
- 9.7 EuroChem Group AG
- 9.8 Arab Potash Company
- 9.9 SQM S.A.
- 9.10 Qinghai Salt Lake Industry

 全球鉀礦開採和貿易市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 鉀鹼市場報告:按形態、等級、最終用途和地區分類(2026-2034 年)
 2026年全球鉀肥市場報告
 2026-2030年全球亞硫酸氫鉀市場
 高純度碳酸鉀市場依形態、純度等級、生產製程、包裝、通路及應用分類-2026-2032年全球預測
 按形態、等級、應用、最終用途產業、純度、銷售管道和地區分類的苛性鉀市場規模、佔有率和成長分析 - 2026-2033 年產業預測
 鉀肥市場規模、佔有率及成長分析(按產品、應用類型、最終用途及地區分類)-2026-2033年產業預測
 鉀肥市場-全球產業規模、佔有率、趨勢、機會和預測,按產品(氯化鉀、硫酸鉀、硝酸鉀、其他)、最終用途(農業、非農業)、地區和競爭情況分類,2020-2030 年預測
 全球亞硫酸氫鉀市場
 鉀肥市場規模、佔有率、趨勢分析報告:依產品、最終用途、地區、細分市場預測,2025-2032